
 Indoor Leafy Green Precision Nutrition Program Market | 2026-2036
Indoor Leafy Green Precision Nutrition Program Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Leafy Green Precision Nutrition Program Market Insights
Pharmaceutical-grade nutrient specification tiers is rotating demand toward higher-margin contracts in the Indoor Leafy Green Precision Nutrition Program Market. AeroFarms leverages proprietary aeroponic stacks to sustain year-round output consistency for retail chains. Bowery Farming anchors its position through in-house AI-driven nutrient calibration systems that reduce input waste. Plenty Unlimited differentiates via large-scale vertical farms positioned near major US metropolitan distribution hubs.
Indoor leafy green precision nutrition programs deploy sensor-integrated fertigation systems that adjust macronutrient and micronutrient delivery in real time based on plant growth stage and environmental conditions, with dissolved oxygen levels and electrical conductivity serving as primary control parameters. These programs aim to maximize biomass accumulation and phytochemical density while minimizing water and fertilizer inputs in controlled environment agriculture. IoT Sensors and AI Analytics together capture the dominant value share, as hardware-generated data streams require algorithmic interpretation to trigger automated nutrient adjustments. Vertical Farming applications attract disproportionate capital allocation relative to farmer cooperatives, given the operational scale and repeatability of indoor tower and rack configurations.
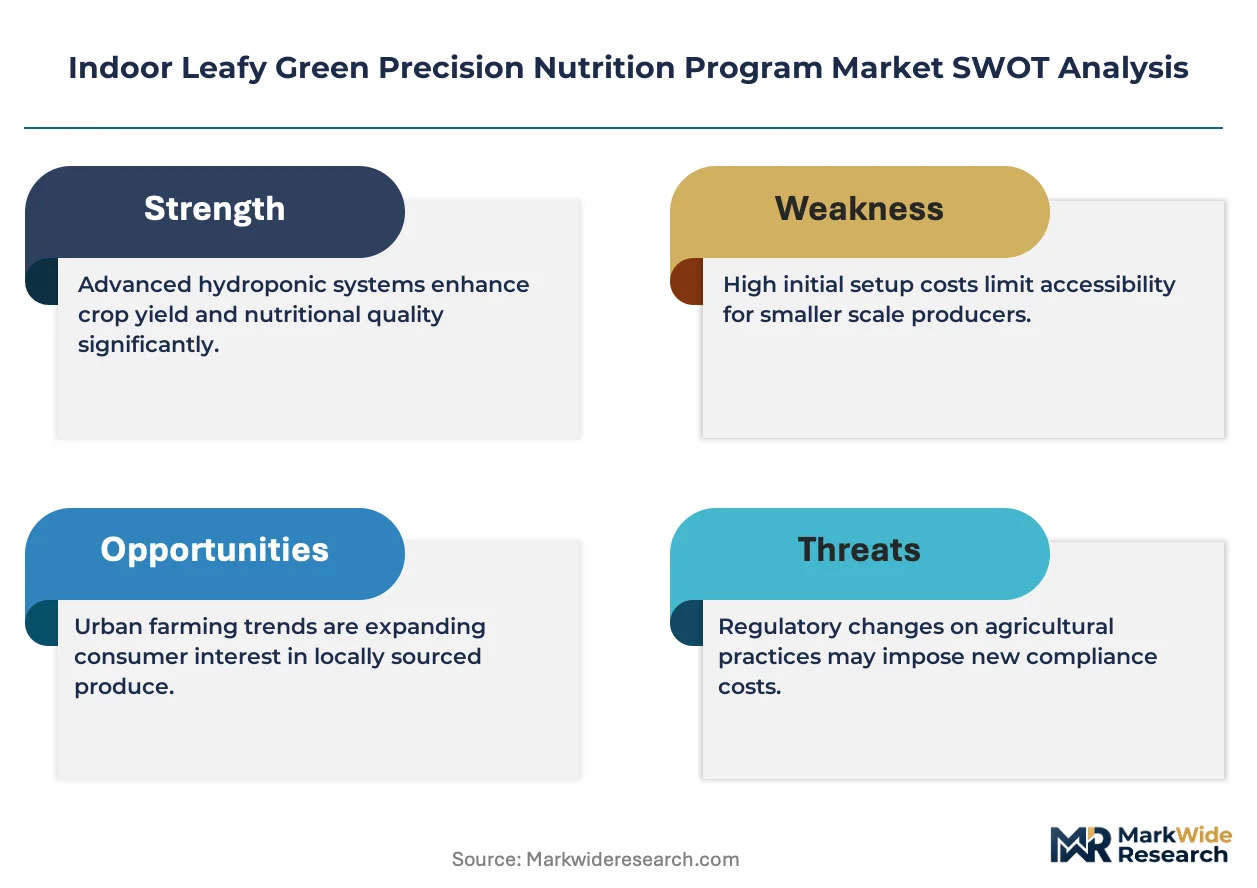
EPA water discharge standards and OSHA agricultural chemical handling requirements shape system design and compliance costs for US-based operators, while the EU Green Deal farm-to-fork targets accelerate nutrient-use-efficiency mandates across member state controlled-environment facilities. The USDA organic certification framework creates a parallel compliance track for growers marketing soilless produce under organic labels. Stakeholders must monitor how evolving definitions of organic hydroponic production alter input sourcing rules and premium market access.
Market Dynamics
Closed-loop nutrient recovery systems are compressing operational expenditure structures for commercial vertical farming operators, as EU F-Gas Regulation compliance costs and carbon accounting mandates force capital reallocation toward recirculating infrastructure.
Growth Catalysts
- EU Green Deal farm-to-fork nutrient-use-efficiency targets:Member state controlled-environment facilities face binding reduction mandates for synthetic fertilizer discharge, accelerating retrofit demand for sensor-integrated fertigation systems.
- Wageningen-cluster research partnerships:Direct technology transfer agreements between Dutch agritech deployers and plant science institutions compress commercialization timelines for precision dosing algorithms.
- Pharmaceutical-grade specification tiers:Biomass purchasers in functional food and nutraceutical supply chains now contract for phytochemical density guarantees, creating premium contract structures beyond commodity leafy green pricing.
Market Restraints
- Input cost volatility in potassium and nitrogen compounds:Fertilizer supply concentration in Belarus and Russia exposes European and North American operators to price spikes and import disruption risk.
- Technical limitation in dissolved oxygen sensor calibration:Drift errors in low-conductivity hydroponic solutions require frequent manual recalibration, degrading automated system reliability.
- Regulatory friction from USDA organic hydroponic definitional disputes:Pending rulemaking on soilless production eligibility threatens premium market access for certified operators.
Strategic Opportunities
- Underpenetrated Japan metropolitan corridor deployment:METI urban agriculture subsidies and PMDA novel food consultation pathways create favorable entry conditions for precision nutrition system exporters.
- Technology convergence between computer vision and electrochemical sensing:Multi-modal plant stress detection enables predictive nutrient adjustment before visible symptom expression.
- Distribution innovation through retail chain captive sourcing agreements:Direct-to-produce-department contracts eliminate wholesale intermediary margins and secure volume commitments.
Industry Challenges
- Specialized skill scarcity in plant physiology-electrical engineering hybrid roles:System optimization requires staff capable of interpreting both spectral reflectance data and pump curve specifications.
- Capex intensity of redundant nutrient mixing infrastructure:Pharmaceutical-grade production requires parallel batching systems to prevent cross-contamination, doubling initial equipment outlay.
- Certification timeline compression for ISO 22000 food safety management:Accelerated audit schedules strain documentation capabilities of scaling operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Leafy Green Precision Nutrition Program Market |
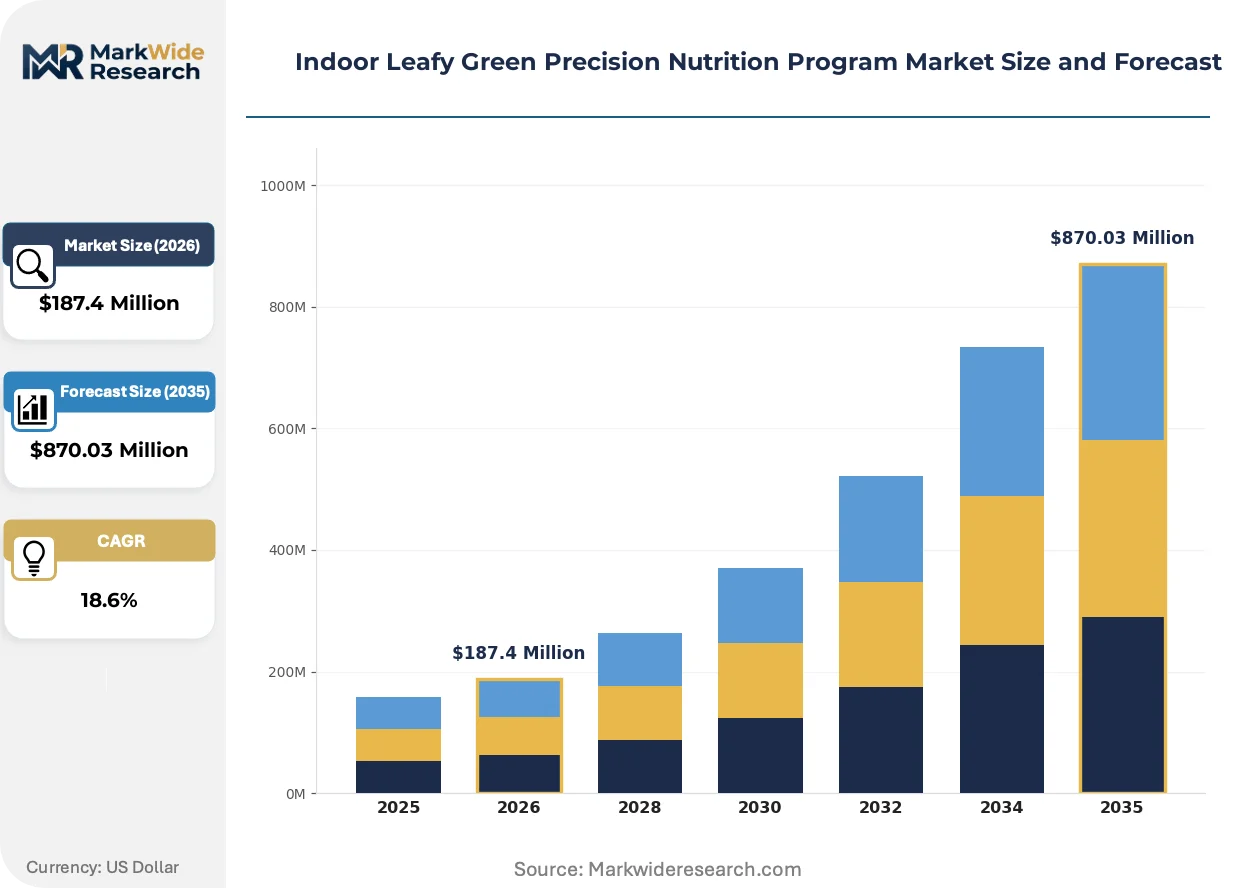
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
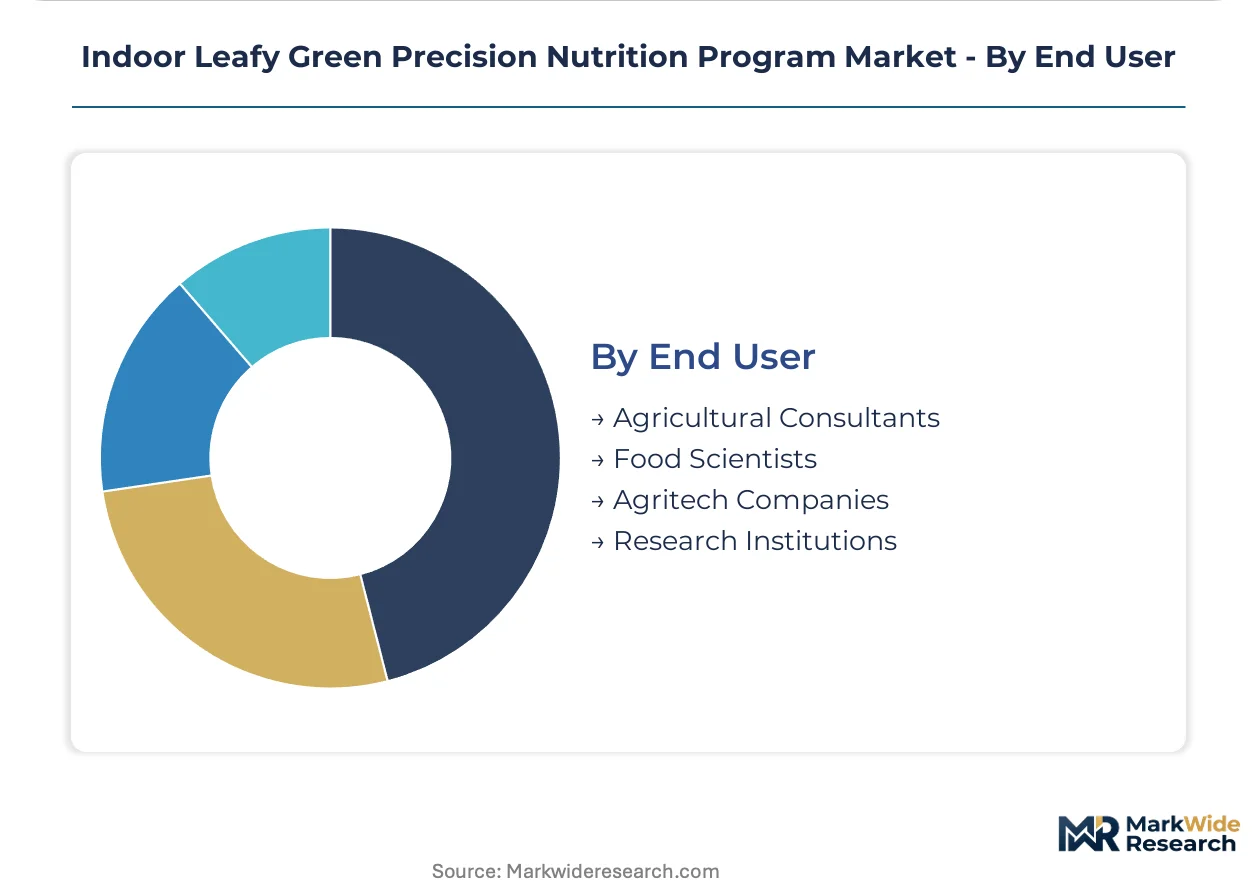
| Segmentation | Program Type: Personalized Meal Plans, Nutrient Optimization, Growth Monitoring, Yield Enhancement Technology: IoT Sensors, AI Analytics, Machine Learning Algorithms, Data Integration Platforms Application: Farmer Cooperatives, Urban Hydroponics, Controlled Environment Agriculture, Vertical Farming End User: Agricultural Consultants, Food Scientists, Agritech Companies, Research Institutions |
| Companies Covered | Dole plc, Taylor Farms, Bonduelle, Fresh Del Monte Produce, Chiquita Brands International, AeroFarms, Plenty Unlimited, Bowery Farming, BrightFarms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Leafy Green Precision Nutrition Program Market Trends and Innovations
Algorithmic nutrient dosing is displacing scheduled replacement protocols across commercial controlled-environment agriculture, with real-time electrical conductivity feedback loops now standard in premium system configurations.
Hyperspectral imaging combined with machine learning classifiers is decomposing traditional growth-stage-based feeding schedules into continuous, plant-specific macronutrient adjustments. Large-scale vertical farming operators in the Netherlands and United States deploy these systems to sustain phytochemical consistency across harvest cycles. The technology is compressing the competitive advantage window for operators relying on manual scouting and fixed recipe programs.
REACH chemical registration requirements and EU F-Gas Regulation phase-down schedules are forcing reformulation of conventional nutrient additives and HVAC-dependent climate systems. Industrial consequence includes accelerated R&D expenditure on bio-based chelating agents and closed-loop refrigeration. Controlled-environment facilities in Germany and Belgium face the steepest compliance cost curves, with several operators relocating expansion capacity to jurisdictions with transitional grace periods.
Retail chain procurement teams now mandate sensor data transparency as a contract precondition, displacing traditional quality assurance through spot testing. This behavioral shift concentrates buying power with vertically integrated producers capable of API-accessible growth environment logs. The pattern is most visible in North American metropolitan distribution corridors, where grocers compete on provenance verification claims.
Indoor Leafy Green Precision Nutrition Program Market Segmentation
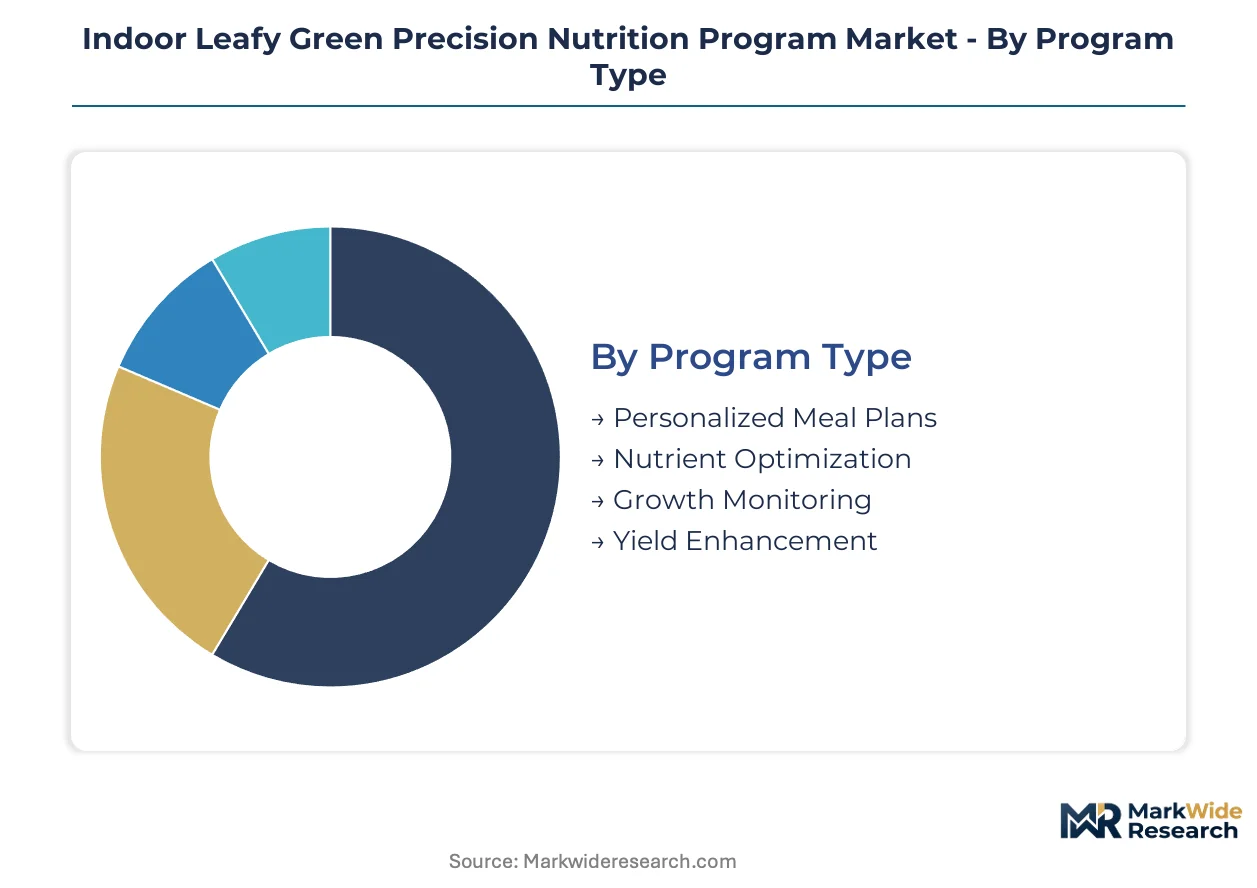
Precision nutrition programs for indoor leafy greens fragment across four operational dimensions, each governing distinct procurement channels and deployment economics. Channel alignment determines margin capture, with technology-integrated segments flowing through direct vendor relationships while advisory services route through institutional intermediaries.
Program Type:
Program categories channel through divergent sales architectures, with hardware-coupled offerings favoring long-term service contracts and software-native products penetrating via SaaS licensing.
- Yield Enhancement:Combines spectral imaging protocols with macronutrient calibration to maximize harvest weight per square meter. Commercial vertical farms in the Netherlands and United States concentrate procurement here, driven by retail chain volume commitments that penalize shortfall. By volume, Yield Enhancement leads. By growth pace, Nutrient Optimization is ahead.
- Nutrient Optimization:Deploys real-time electrical conductivity feedback to adjust N-P-K ratios across growth stages. Demand clusters among German and Belgian controlled-environment operators facing EU F-Gas Regulation compliance cost pressure and binding nutrient-use-efficiency mandates under the EU Green Deal farm-to-fork framework.
- Personalized Meal Plans:Configures crop nutritional profiles for functional food and nutraceutical buyers specifying phytochemical density guarantees.
- Growth Monitoring:Tracks biomass accumulation through computer vision and electrochemical sensing for early stress detection.
Advisory-heavy segments route through agricultural consultants; automation-heavy variants deploy direct-to-grower.
Technology:
Technology stack choices stratify by capital intensity threshold, with sensor-hardware combinations demanding higher upfront outlay but securing recurring data-service revenue streams.
- IoT Sensors:Capture dissolved oxygen, pH, and electrical conductivity at fertigation loop junctions. Dutch Wageningen-cluster deployers anchor demand, leveraging direct research institution partnerships to compress algorithm commercialization timelines. By volume, IoT Sensors leads. By margin expansion trajectory, AI Analytics is climbing the fastest.
- AI Analytics:Interprets multi-parameter data streams to trigger automated nutrient adjustments without human intervention. North American metropolitan corridor operators prioritize this layer to satisfy retail chain procurement mandates for sensor data transparency and API-accessible growth environment logs.
- Machine Learning Algorithms:Refine predictive models for plant stress expression using hyperspectral imaging training datasets.
- Data Integration Platforms:Aggregate disparate hardware inputs into unified control interfaces for multi-site operations.
Hardware-software bundled sales dominate in Europe; modular unbundling prevails in North America.
Application:
Application segments diverge by operational scale, with enterprise-grade configurations attracting disproportionate capital allocation relative to cooperative structures.
- Vertical Farming:Deploys precision nutrition across tower and rack configurations with repeatability sufficient for retail chain captive sourcing agreements. Japanese metropolitan corridor expansion under METI urban agriculture subsidies is accelerating system exports to this segment. By volume, Vertical Farming leads. By policy tailwinds, Controlled Environment Agriculture is gaining share fastest.
- Controlled Environment Agriculture:Encompasses greenhouse and warehouse retrofit installations subject to EPA water discharge standards in the United States and EU Green Deal nutrient-use-efficiency targets. Compliance cost pressure is forcing capital reallocation toward recirculating infrastructure with closed-loop nutrient recovery.
- Urban Hydroponics:Serves small-scale metropolitan operators with modular system footprints.
- Farmer Cooperatives:Pools procurement for shared nutrient calibration services across member holdings.
Enterprise direct sales dominate vertical farming; cooperative segments route through agricultural consultant intermediaries.
End User:
End user categories separate by technical capability depth, with hybrid plant physiology-electrical engineering skill scarcity concentrating value capture among full-stack deployers.
- Agritech Companies:Build proprietary nutrient calibration systems for captive deployment or licensing. These firms absorb the steepest ISO 22000 food safety management certification timeline compression as they scale. By volume, Agritech Companies lead. By contract premium capture, Research Institutions are expanding most quickly.
- Research Institutions:Partner directly with commercial deployers for technology transfer, compressing commercialization timelines for precision dosing algorithms. Wageningen University and Research anchors European demand, with output flowing to Dutch vertical farming operators.
- Agricultural Consultants:Advise grower clients on program selection and system optimization.
- Food Scientists:Specify phytochemical density targets for functional food and nutraceutical supply chain contracts.
Full-stack deployers retain margin through in-house production of nutrient calibration systems; advisory roles capture fees without hardware exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch precision nutrition system exports flow primarily to German and Belgian controlled-environment operators facing EU F-Gas Regulation compliance deadlines. North American metropolitan corridor demand concentrates in US vertical farming hubs seeking retail chain captive sourcing agreements.
United States
Commercial vertical farming operators in New York and New Jersey metropolitan corridors drive demand for sensor-integrated fertigation systems. EPA water discharge standards and OSHA agricultural chemical handling requirements shape system design compliance costs. Chicago and Detroit distribution hubs host operators pursuing retail chain procurement mandates for API-accessible growth environment logs.
Netherlands
Wageningen-cluster research institutions partner directly with agritech deployers to compress commercialization timelines for precision dosing algorithms. EU F-Gas Regulation and national carbon accounting rules push growers toward closed-loop nutrient systems. Eindhoven and Rotterdam vertical farming corridors concentrate pharmaceutical-grade specification tier contracts.
Germany
Controlled-environment facilities in Bavaria and North Rhine-Westphalia face binding nutrient-use-efficiency mandates under EU Green Deal farm-to-fork targets. REACH chemical registration requirements force reformulation of conventional nutrient additives. Berlin-Brandenburg operators absorb steepest compliance cost curves for bio-based chelating agent R&D.
Belgium
Greenhouse retrofit installations in Flanders deploy real-time electrical conductivity feedback systems to adjust N-P-K ratios across growth stages. EU Green Deal nutrient-use-efficiency targets accelerate capital reallocation toward recirculating infrastructure. Several operators relocate expansion capacity to jurisdictions with transitional grace periods.
Japan
Metropolitan corridor deployment in Tokyo and Osaka accelerates under METI urban agriculture subsidies. PMDA novel food consultation pathways create favorable entry conditions for precision nutrition system exporters. Kanto region operators pursue pharmaceutical-grade specification tiers for functional food supply chain contracts.
Indoor Leafy Green Precision Nutrition Program Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and captive production dimensions. The vendor base stratifies into three tiers: full-stack deployers with in-house AI-driven nutrient calibration, hardware-agnostic software licensors, and advisory-heavy agricultural consultants. Strategic moves concentrate on technology convergence partnerships and backward integration into sensor manufacturing to secure supply chain control.
Within the full-stack deployer tier, AeroFarms and Bowery Farming exemplify the vertically integrated model with proprietary aeroponic and AI-driven systems respectively. Plenty Unlimited occupies a position at the scale-driven end of the spectrum, anchoring large-scale vertical farm deployment near major US metropolitan distribution hubs. These three entities represent the dominant competitive archetypes: technology licensors, captive producers, and scale-focused operators.
| Leading Market Players |
|---|
| Dole plc |
| Taylor Farms |
| Bonduelle |
| Fresh Del Monte Produce |
| Chiquita Brands International |
| AeroFarms |
| Plenty Unlimited |
| Bowery Farming |
| BrightFarms |
| Others |
Pricing and Supply Chain Analysis
Bio-based chelating agent substitution for synthetic EDTA variants is redrawing supplier geography toward Nordic biotech clusters while compressing margin structures for legacy compound manufacturers. This input transition simultaneously elevates R&D amortization costs and fragments volume pricing power across tiered certification grades.
Pricing Analysis
The technology-generation pricing gap separating first-generation scheduled fertigation systems from second-generation sensor-integrated platforms and emerging third-generation predictive AI stacks defines current contract structures. Three-tier pricing structure across pharmaceutical-grade, commercial-grade, and basic compliance levels anchors the market, with ISO 22000 certification and API-accessible data logs as primary price differentiation drivers. Pricing pressure stems from potassium and nitrogen compound import volatility, squeezing mid-tier operators most acutely. Retail chain procurement teams exhibit lowest price sensitivity due to captive sourcing premiums, while farmer cooperatives face acute margin compression.
Supply Chain Analysis
Inventory lead times for dissolved oxygen sensors and electrochemical probes have extended due to semiconductor component shortages, forcing Dutch and German operators to hold larger safety stocks. Supply concentrates in the Netherlands for precision dosing hardware, China for IoT sensor assemblies, and Belgium for greenhouse retrofit integration kits. The chain draws from potassium derivatives, nitrogen compounds, and rare-earth sensor elements as core inputs. Single-source vulnerability in Belarus-Russia fertilizer supply corridors poses structural risk. Distribution runs through direct vendor relationships for vertical farming enterprises and agricultural consultant intermediaries for cooperative segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a cyclical recovery phase driven by EU Green Deal farm-to-fork compliance deadlines forcing capital reallocation toward recirculating infrastructure.
For Market Incumbents: Compound defensive moats through backward integration into sensor manufacturing and captive nutrient formulation capacity. Lock in retail chain API-accessible data mandates before emerging AI-native challengers erode contract renewals. Prioritize ISO 22000 certification acceleration to outpace audit timeline compression. For New Entrants and Emerging Players: Post-harvest phytochemical verification services represent a service-layer gap where incumbents under-serve functional food buyers seeking density guarantees. Target Japanese metropolitan corridor expansion under METI subsidies as the most penetrable geography. Pursue technology convergence partnerships combining computer vision with electrochemical sensing as the go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors full-stack deployers with proprietary AI-driven calibration systems. Over the medium-term window, vertically integrated operators with in-house nutrient formulation and sensor hardware production offer strongest viability. Watch EU F-Gas Regulation phase-down enforcement intensity as the inflection signal for capital reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Secures supply chain control for Dutch vertical farming operators facing semiconductor lead time volatility. |
| Technology Convergence Partnership | Combines Wageningen-cluster research with commercial deployers to compress algorithm commercialization timelines. |
| Pharmaceutical-Grade Certification Investment | Unlocks premium contract structures for functional food buyers specifying phytochemical density guarantees. |
| Captive Retail Chain Sourcing Agreement | Eliminates wholesale intermediary margins for North American metropolitan corridor operators. |
| Closed-Loop Nutrient Recovery Infrastructure | Addresses EU Green Deal farm-to-fork mandates for German and Belgian controlled-environment facilities. |
Research Methodology
Initial hypotheses were tested against primary input from vertical farm operations directors, agritech procurement leads, greenhouse facility managers, and food scientist formulators, then refined through secondary validation against EU F-Gas Regulation filings, EPA water discharge compliance records, METI subsidy disbursement data, and Wageningen University technology transfer agreements. Bottom-up installation forecasts triangulated against top-down nutrient input demand models.
Variance decomposition across program type, technology stack, application scale, and end-user technical capability depth structured the analytical framework. CAGRs derived from segment-level growth rate reconciliation. Industry-specific inputs included retail chain procurement mandate adoption curves and EU Green Deal implementation timeline assumptions across member states.
Forecasts assume regulatory continuity in EU F-Gas Regulation phase-down schedules and USDA organic hydroponic definitional frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Australia Plant Protein Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Fractionated Pulses Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Global Organic Soy Protein Market
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Yucca Extract Market
Plant Based Food
Soy- Based Food Market