
 Vegan Protein Concentrate Market | 2026-2036
Vegan Protein Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Protein Concentrate Market Analytics
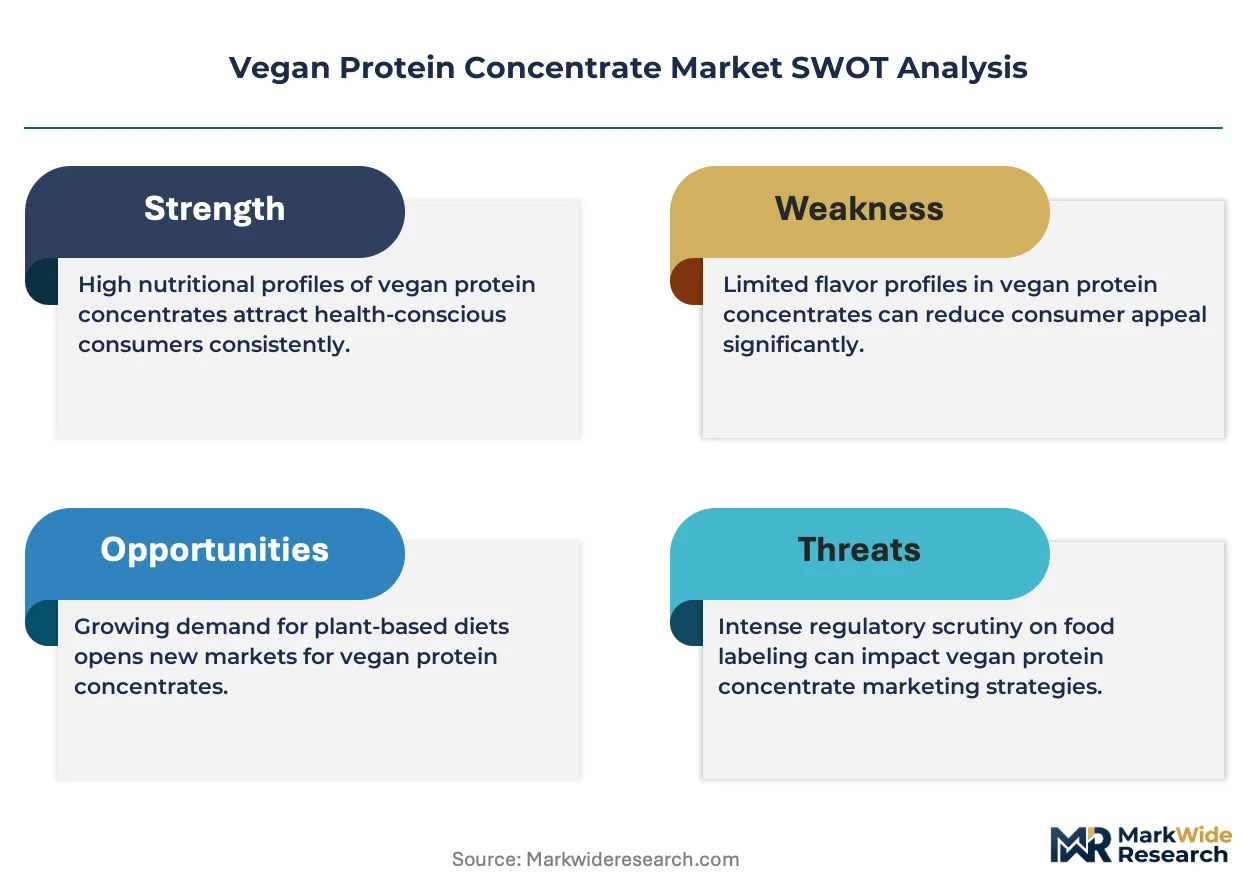
Multi-source procurement from pea and rice protein suppliers is hardening as food manufacturers diversify away from soy dependence. Cargill Incorporated leverages its global oilseed processing footprint to secure non-GMO pea protein streams across North American and European facilities. Glanbia Nutritionals anchors its position through specialized nutrition applications, sustaining R&D intensity in sports and clinical nutrition formulations. Kerry Group competes on taste-masked protein systems, occupying a differentiated niche where flavor functionality determines contract renewals.
Vegan protein concentrate denotes a minimally processed plant-derived protein fraction, typically retaining 50-80% protein content on a dry-weight basis alongside residual fiber, fat, and ash, produced through dry or wet milling followed by aqueous extraction and isoelectric precipitation. Its primary commercial purpose centers on delivering functional nutrition and textural properties to formulated foods, beverages, and dietary supplements without animal-derived inputs. Pea protein commands the largest volume position due to its neutral flavor profile and emulsification capacity in meat analogues, while rice protein represents the fastest-growing category as allergen-free positioning attracts pediatric and clean-label formulations. Powder form dominates manufacturing economics, though ready-to-drink applications are capturing margin pools where convenience premiums offset higher processing costs.
The FDA maintains GRAS notification requirements for novel plant protein isolates, while the USDA oversees organic certification pathways that command price premiums in North American retail channels. EFSA protein quality scoring under the EU Nutrition and Health Claims Regulation shapes permissible marketing language, directly influencing how BENEO and Emsland Group position their concentrate portfolios for European food manufacturers. Stakeholders must monitor evolving amino acid fortification standards and carbon footprint labeling mandates, as these will determine which protein sources and processing geographies retain formulation access.
Market Dynamics
EU Green Deal carbon accounting mandates and F-Gas Regulation phase-down schedules are forcing protein processors to relocate wet-milling capacity toward renewable energy clusters and retrofit extraction lines with low-GWP refrigerants.
Growth Catalysts
- Clean-label meat analogue demand:Food manufacturers in Germany are reformulating burger patties and sausage applications with pea protein concentrates to meet retailer clean-label specifications.
- EFSA protein quality scoring:The EU Nutrition and Health Claims Regulation permits specific amino acid ratio marketing for concentrates scoring above defined thresholds, accelerating pediatric nutrition adoption.
- Pediatric allergen-free positioning:Rice protein isolates are capturing formulation share in hypoallergenic infant formulas as parents reject soy and dairy derivatives.
Market Restraints
- Yellow pea supply concentration:North American prairie drought cycles create 18-24 month price volatility windows that destabilize contract pricing for wet-milled concentrates.
- Isoelectric precipitation yield ceilings:Aqueous extraction methods retain 15-25% residual starch and fiber, limiting protein content to 80% maximum without secondary ultrafiltration.
- F-Gas refrigeration retrofit costs:EU processing facilities face six-figure capital outlays to replace R-404A systems with CO2 or ammonia alternatives before 2030 phase-out deadlines.
Strategic Opportunities
- Carbon-negative protein branding:Dutch and Danish biorefineries are piloting fermentative upcycling of brewer's spent grain into fungal protein concentrates with verified negative emissions credentials.
- Ready-to-drink convenience channel:Sports nutrition brands are launching ambient-stable protein waters using microencapsulated rice isolates that bypass refrigerated supply chains.
- USDA organic certification arbitrage:North American contract manufacturers with dual organic-conventional lines can capture 35-50% price premiums in natural retail channels.
Industry Challenges
- Food technologist scarcity:Formulation chemistry expertise spanning protein denaturation kinetics and flavor masking is concentrated among retiring cohorts at legacy ingredient houses.
- GRAS notification timelines:FDA novel protein consultations for emerging sources such as fava bean or chickpea concentrates extend 18-36 months, freezing pipeline investment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Protein Concentrate Market |
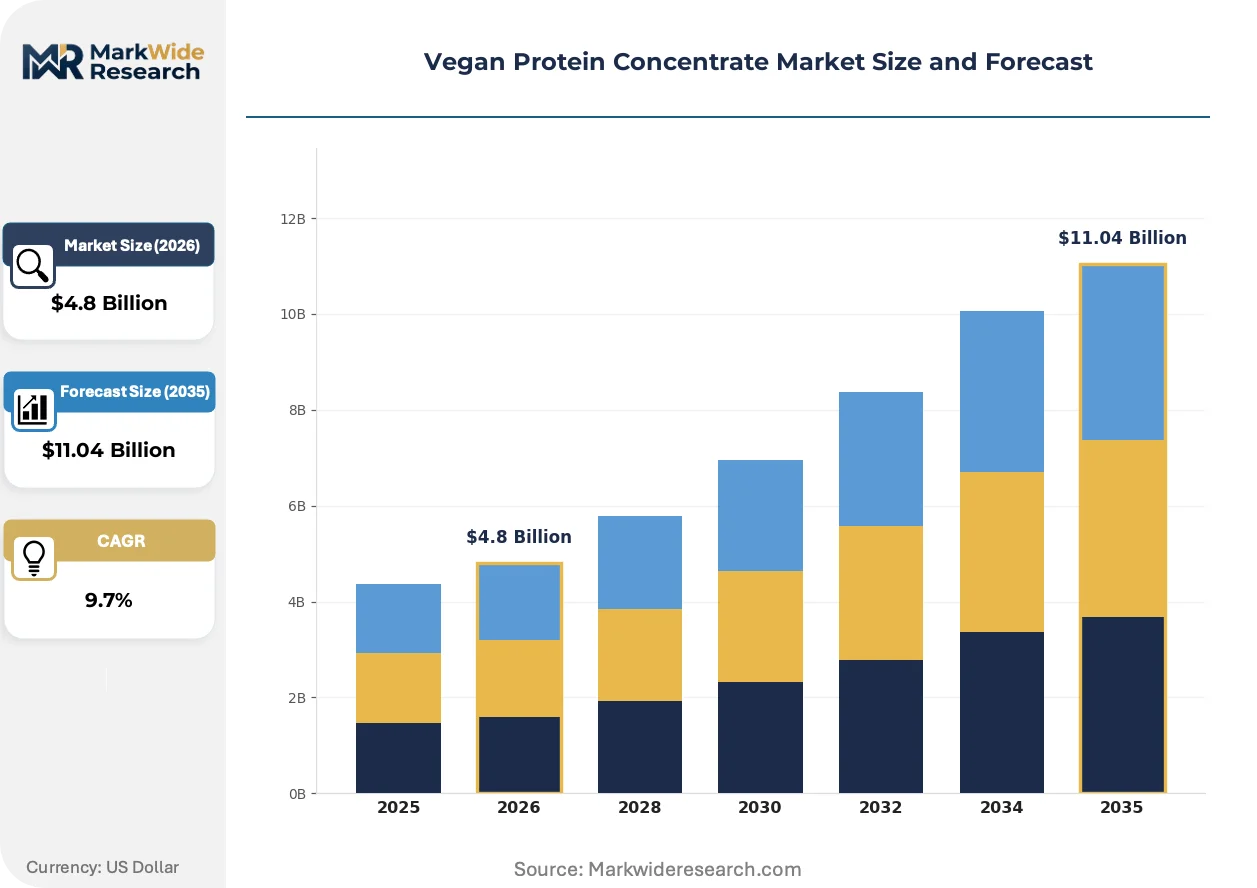
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Hemp Protein End User: Fitness Enthusiasts, Health-conscious Consumers, Food Manufacturers, Nutraceutical Companies Form: Powder, Bar, Ready-to-Drink, Supplement Sachets Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Ingredion Incorporated, Kerry Group, Glanbia Nutritionals, Axiom Foods, Emsland Group, Wilmar International Ltd, BENEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Protein Concentrate Market Evolving Landscape
Processing technology convergence and regulatory disclosure mandates are redrawing competitive boundaries between commodity ingredient suppliers and specialized nutrition houses.
Membrane filtration cascades are decentralizing protein recovery economics. Mid-scale wet-mills in the Netherlands and Denmark are deploying ceramic microfiltration followed by ultrafiltration to produce 85% protein isolates without isoelectric precipitation. Regional dairy cooperatives are retrofitting idle whey processing lines for pea and fava protein, compressing capital barriers for 5,000-10,000 tonne annual outputs. This distributed processing model is decentralizing volume concentration away from North American prairie crushing hubs.
EFSA's updated protein quality methodology under the EU Nutrition and Health Claims Regulation is recalibrating formulation specifications. The DIAAS scoring system now governs permissible "high protein" label claims, compelling concentrate suppliers to validate amino acid digestibility through human clinical trials. Pediatric and clinical nutrition segments are most affected, with German and Dutch manufacturers reformulating toward potato and corn protein blends that score above the 75% DIAAS threshold.
Direct procurement from origin processors is consolidating buyer power. Large European food manufacturers are bypassing traditional ingredient distributors to contract directly with French and Belgian pea protein wet-mills, compressing margin pools for trading houses. This disintermediation is most visible in Germany, where meat analogue producers negotiate 12-24 month offtake agreements with named extraction facilities to secure supply continuity amid volatile raw material flows.
Vegan Protein Concentrate Market Segmentation
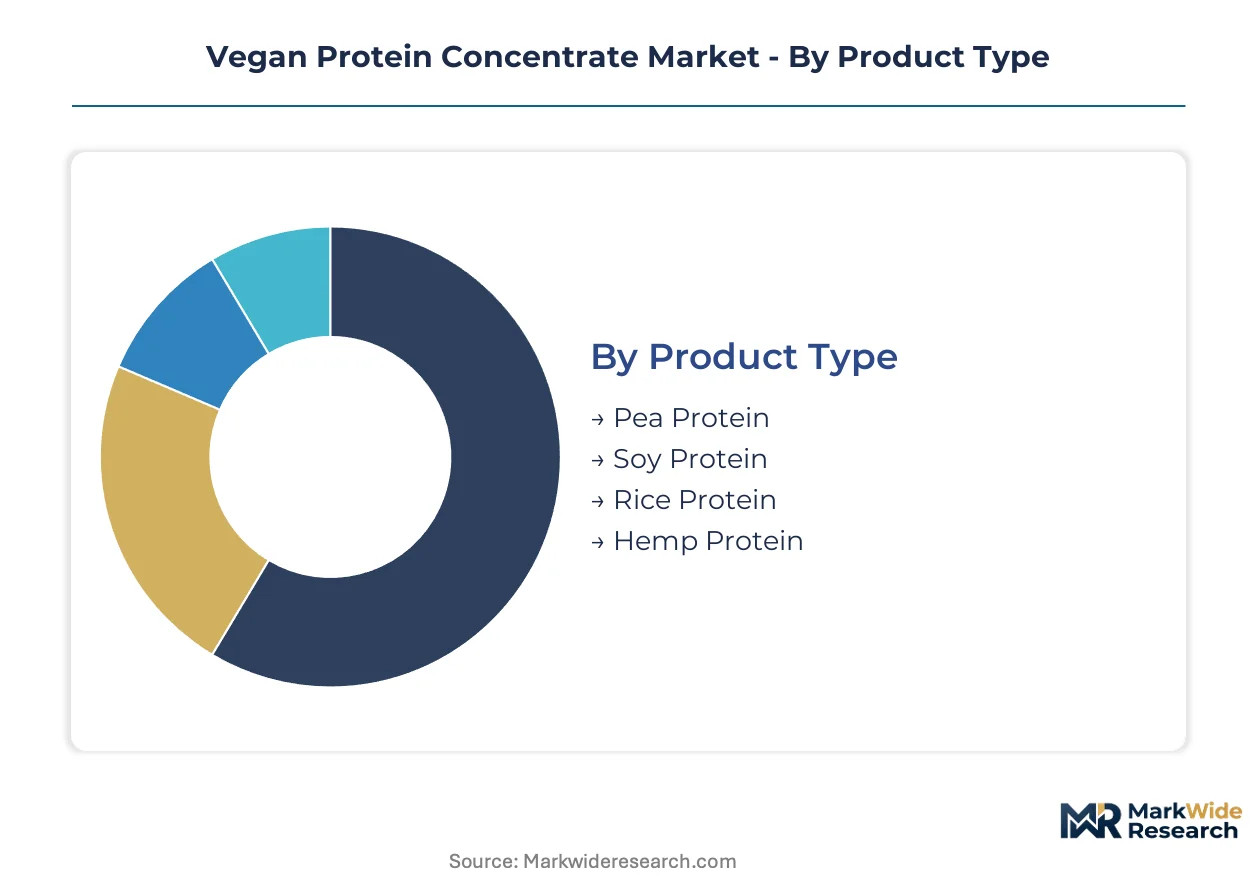
Segmentation in the vegan protein concentrate market reveals how supply-side capabilities and demand-side specifications intersect. Protein source selection, formulation formats, and channel access determine which suppliers capture formulation contracts and retail shelf space.
Product Type:
Supply concentration around yellow pea crushing infrastructure in North America and Europe shapes competitive dynamics across protein categories.
- Pea Protein:Neutral flavor profile and superior emulsification capacity make this the default choice for meat analogue formulations. German and Dutch food manufacturers specify pea concentrates for clean-label burger patties and sausage applications where protein content targets 60-70%.
- Rice Protein:Hypoallergenic positioning drives pediatric nutrition adoption. French and Belgian wet-mills are expanding dedicated rice protein lines to serve infant formula manufacturers rejecting soy and dairy derivatives under EFSA allergen guidance.
- Soy Protein:Mature supply base with established organic certification pathways. USDA organic soy concentrates command 35-50% price premiums in North American natural retail channels.
- Hemp Protein:Residual fiber content limits application to bakery and granola segments. Canadian prairie processors dominate supply with small-batch cold-press extraction.
Pea protein absorbs the bulk of installed capacity; rice protein is expanding most quickly.
End User:
Customer sophistication tiers separate commodity volume buyers from specialized nutrition houses requiring clinical-grade documentation.
- Food Manufacturers:Drive bulk concentrate procurement through 12-24 month offtake agreements. Meat analogue producers in Germany negotiate directly with named extraction facilities to secure supply continuity.
- Nutraceutical Companies:Require DIAAS scoring validation and amino acid fortification documentation. EFSA protein quality thresholds govern permissible marketing claims for pediatric and sports nutrition applications.
- Fitness Enthusiasts:Convenience-oriented demand favors ready-to-mix powders and ambient-stable protein waters. Sports nutrition brands microencapsulate rice isolates to bypass refrigerated supply chains.
- Health-conscious Consumers:Clean-label scrutiny extends to carbon footprint and organic certification. Dutch biorefineries pilot fermentative upcycling with verified negative emissions credentials to capture this segment.
Food manufacturers lock in the majority of long-term contracts; nutraceutical companies are climbing the fastest as clinical validation requirements deepen.
Form:
Processing intensity and packaging economics determine margin capture across delivery formats.
- Powder:Dominates manufacturing economics with minimal moisture content and extended shelf stability. Dry-blending facilities in Germany and the Netherlands compress working capital requirements for mid-scale food manufacturers.
- Ready-to-Drink:Captures convenience premiums where ambient-stable formulations justify higher processing costs. Microencapsulation technology from specialized ingredient houses enables protein waters without refrigerated distribution.
- Bar:Extrusion and binding requirements favor concentrates with specific water-holding capacity. Pea protein isolates with 80%+ content perform best in high-protein snack applications.
- Supplement Sachets:Single-serve packaging adds 40-60% cost premium over bulk powder. Direct-to-consumer brands in Germany and France target travel and workplace consumption occasions.
Powder commands the greatest production volume; ready-to-drink formats are gaining share fastest through convenience channel expansion.
Distribution Channel:
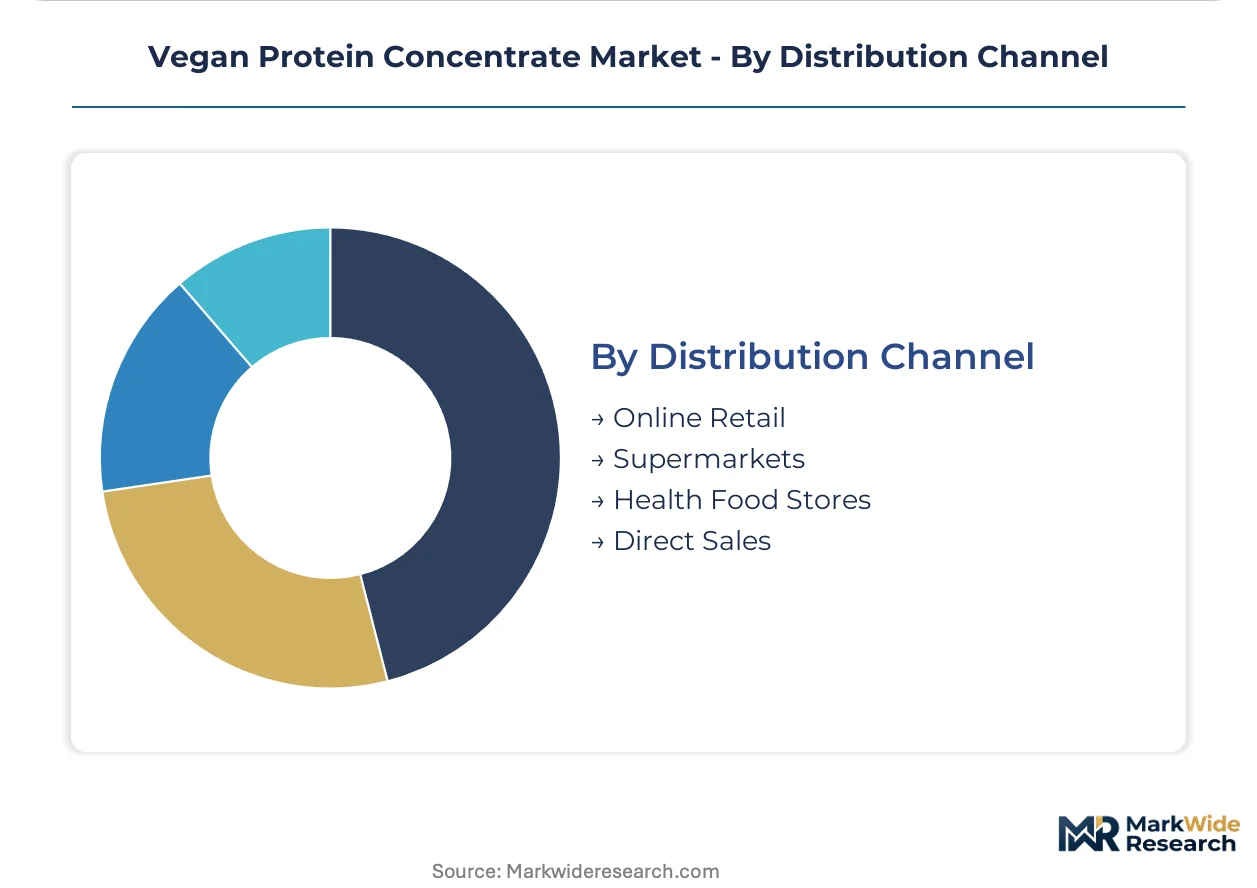
Channel selection determines margin retention and brand control for concentrate suppliers and finished product manufacturers.
- Direct Sales:Large European meat analogue producers bypass distributors to contract directly with French and Belgian wet-mills. This disintermediation compresses margin pools for trading houses.
- Online Retail:Subscription models and direct-to-consumer brands build loyalty through personalized nutrition recommendations. German sports nutrition startups leverage Amazon and specialized fitness platforms for rapid scale.
- Supermarkets:Clean-label specifications from German and Dutch retailers drive reformulation requirements. Pea protein concentrates must meet non-GMO and allergen-free standards to secure shelf placement.
- Health Food Stores:Organic certification and local sourcing narratives command price premiums. North American natural channel buyers prioritize USDA organic concentrates with transparent supply chain documentation.
Direct sales capture the largest contract volumes; online retail is expanding most quickly as digital-native brands disintermediate traditional distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yellow pea cultivation across the Canadian prairies and northern US plains anchors raw material flows for wet-milled concentrates. Processing capacity clusters near these feedstock zones and in European biorefinery corridors where renewable energy integration satisfies EU Green Deal mandates.
United States
Meat analogue startups in Chicago and Minneapolis drive pea protein procurement through direct processor contracts. FDA GRAS notifications for novel isolates create 18-36 month approval windows that freeze pipeline investments. North Dakota and Montana crushing hubs expand aqueous extraction lines to serve domestic food manufacturers.
Germany
Clean-label retailer specifications from Berlin and Hamburg headquarters force reformulation toward non-GMO concentrates. EFSA DIAAS scoring under the EU Nutrition and Health Claims Regulation governs permissible "high protein" marketing language. Ingredient technology clusters in Lower Saxony attract formulation partnerships from Dutch and French wet-mills.
Netherlands
Dairy cooperatives in Friesland and Groningen retrofit idle whey processing lines for pea and fava protein recovery. F-Gas Regulation phase-down deadlines compel six-figure refrigeration retrofits before 2030. Ceramic microfiltration cascades at mid-scale biorefineries produce 85% isolates without isoelectric precipitation.
France
Pediatric nutrition manufacturers in Paris and Lyon specify rice protein for hypoallergenic infant formulas under EFSA allergen guidance. Organic certification pathways command 35-50% price premiums in natural retail channels. Brittany and Normandy wet-mills expand dedicated rice protein lines to serve German contract customers.
Canada
Prairie drought cycles in Saskatchewan and Manitoba create 18-24 month price volatility for yellow pea feedstock. Health Canada and PMRA oversee novel protein safety assessments alongside USDA organic equivalency agreements. Manitoba processors pilot cold-press hemp protein for bakery and granola segments.
Vegan Protein Concentrate Market Competitive Landscape
Capacity expansion dominates the current landscape as wet-mill operators retrofit dairy and oilseed infrastructure for protein extraction. The vendor base separates into three tiers: multinational agribusiness conglomerates with integrated crushing networks, specialized nutrition houses with clinical validation capabilities, and regional biorefineries with flexible batch processing. Strategic archetypes include scale-driven commodity suppliers, taste-functionality specialists, and carbon-negative positioning innovators. M&A activity and direct procurement partnerships represent the primary competitive moves as large food manufacturers bypass distributors to secure offtake agreements.
Within the multinational agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning through global oilseed processing footprints. Kerry Group and Glanbia Nutritionals occupy differentiated niches where flavor functionality and clinical nutrition applications determine contract renewals. Among European ingredient specialists, Emsland Group and BENEO anchor regional supply relationships with German and Dutch food manufacturers seeking EFSA-compliant protein quality documentation.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Ingredion Incorporated |
| Kerry Group |
| Glanbia Nutritionals |
| Axiom Foods |
| Emsland Group |
| Wilmar International Ltd |
| BENEO |
| Others |
Value Network & Pricing Analysis
Large European meat analogue producers negotiate 12-24 month offtake agreements directly with named extraction facilities, compressing margin pools for trading houses and shifting pricing power toward volume-committed buyers with supply continuity requirements.
Pricing Analysis
Service unbundling separates technical formulation support from base concentrate supply, with German and Dutch food manufacturers paying premiums for taste-masked protein systems and DIAAS scoring documentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein content grade and organic certification status. Price erosion runs through commodity pea concentrates as North American prairie crushing hubs expand aqueous extraction capacity. Nutraceutical companies show least price sensitivity due to clinical validation requirements, while mid-scale food manufacturers in competitive retail channels drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-manufacturer channels handle hyperscale demand from German meat analogue producers bypassing traditional ingredient distributors. Raw material flows center on yellow pea cultivation across the Canadian prairies and northern US plains, with wet-milling capacity clustering near these feedstock zones. Processing draws from renewable energy corridors in the Netherlands and Denmark where EU Green Deal mandates drive facility relocation. Single-source vulnerability concentrates in North American prairie drought cycles that destabilize yellow pea feedstock pricing across 18-24 month volatility windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EU F-Gas Regulation phase-down deadlines force capital-intensive refrigeration retrofits that weaker players cannot fund.
For Market Incumbents: Deploy membrane filtration technology upgrades to produce 85% protein isolates without isoelectric precipitation, defending against regional biorefineries with flexible batch processing. Deepen backward integration into named North American pea crushing hubs to secure non-GMO feedstock streams against prairie drought volatility. Anchor position through EFSA DIAAS scoring validation investments that pediatric nutrition manufacturers require for permissible marketing claims. For New Entrants and Emerging Players: Launch via carbon-negative protein branding targeting health-conscious consumers in Dutch and Danish markets where verified negative emissions credentials command shelf space premiums. Target ready-to-drink convenience channels with microencapsulated rice isolates that bypass refrigerated supply chains and capture margin pools from sports nutrition brands. Prioritize hypoallergenic infant formula applications where rice protein is displacing soy and dairy derivatives under EFSA allergen guidance. For Investors and Strategic Acquirers: The window for entry favors specialized nutrition houses with clinical validation capabilities and existing DIAAS scoring documentation. Long-term viability hinges on formulation chemistry expertise spanning protein denaturation kinetics as retiring cohorts at legacy ingredient houses create capability scarcity. Monitor FDA GRAS notification timelines for novel protein sources as the signal indicating when pipeline investment decisions unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Crushing | Cargill leverages North American oilseed infrastructure to secure non-GMO feedstock streams. |
| Membrane Filtration Technology Deployment | Dutch biorefineries deploy ceramic microfiltration to produce 85% isolates without isoelectric precipitation. |
| EFSA DIAAS Scoring Validation | German manufacturers reformulate toward potato and corn protein blends exceeding 75% threshold. |
| Direct Processor Contracting | French wet-mills bypass distributors to negotiate 12-24 month offtake with meat analogue producers. |
| F-Gas Refrigeration Retrofit | EU processing facilities face six-figure capital outlays to replace R-404A systems before 2030 deadlines. |
Research Methodology
Independent corroboration across extraction facility operators, food manufacturer procurement leads, and regulatory affairs specialists at EFSA-notified bodies underwrites the qualitative findings. Primary interviews with plant managers at North American crushing hubs, Dutch dairy cooperative retrofitting teams, and German meat analogue formulation chemists combined with secondary validation from FDA GRAS notification databases, EU F-Gas Regulation implementation schedules, and customs trade data for yellow pea feedstock flows. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Comparable historical periods anchored the forecast window to pre-drought prairie cultivation cycles and prior EU regulatory phase-down implementations. The analytical framework models protein source, formulation format, end-user sophistication tier, and distribution channel access across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs include wet-mill capacity utilization rates and EFSA protein quality scoring adoption curves.
Prairie drought recurrence, F-Gas retrofit compliance delays, and FDA GRAS timeline extensions are the dominant revision risks. Forecasts reflect documented assumptions regarding renewable energy cluster migration and membrane filtration cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Fermented Plant-Based Ingredient Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
Soy- Based Food Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
United States Pea Protein Market
Plant Based Food
USA Plant-Based Creamers Market