
 Textured Pea Protein Market | 2026-2036
Textured Pea Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Textured Pea Protein Market Outlook
Subscription-based formulation support is shifting how textured pea protein suppliers monetize customer relationships beyond commodity tonnage. Roquette Frères leverages its European extraction network to sustain supply security for alt-meat formulators. COSUCRA anchors specialty grade output through backward integration into Belgian yellow pea cultivation. Puris dominates North American organic textured pea protein with in-house production of both protein and starch fractions.
Textured pea protein denotes a thermoplastic extrusion product derived from yellow field peas, typically containing 50-80% protein on a dry weight basis with a fibrous, layered structure that mimics cooked muscle tissue. The extrusion process applies shear, heat, and moisture to denature and align globulin proteins into anisotropic matrices suitable for meat analog rehydration. Powder and textured variants command the largest volume positions, though isolates capture disproportionate margin pools in premium nutritional applications. Meat alternatives represent the fastest-growing application channel, while bakery products remain a mature, price-sensitive outlet where suppliers compete on functional hydration and emulsification performance.
FDA GRAS self-affirmation and EFSA novel food status govern market access for textured pea protein in the United States and European Union respectively, with the EU AI Act beginning to shape digital traceability requirements across ingredient supply chains. China's SAMR and NMPA enforce stricter import registration for novel plant proteins entering foodservice manufacturing. Stakeholders must monitor how evolving protein content labeling standards across multiple jurisdictions reshape product specification requirements and customer procurement criteria.
Market Dynamics
Thermoplastic extrusion capacity concentration among Belgian and French ingredient houses is reshaping supply security for North American plant-based meat formulators. EFSA's accelerated novel food clearance timelines are compressing ingredient authorization cycles across European alt-protein supply chains.
Growth Catalysts
- EFSA Novel Food Streamlining:The European Food Safety Authority's consolidated evaluation pathways for yellow pea protein isolates are shortening time-to-market for textured ingredient variants entering EU27 food manufacturing.
- Alt-Meat Formulation Pull:Plant-based meat manufacturers in Germany's Ruhr food processing corridor are expanding textured pea protein offtake to reduce soy allergen exposure in retail-ready analog products.
- High-Moisture Extrusion Maturation:Twin-screw extrusion technology with precise shear-heat-moisture control is enabling fibrous protein matrix structures that withstand industrial-scale rehydration without texture breakdown.
Market Restraints
- Yellow Pea Protein Concentration Risk:Raw material sourcing clusters in Canada's Prairie Provinces and France's Hauts-de-France region expose processors to climate-driven yield volatility and rail logistics bottlenecks.
- EFSA Novel Food Authorization Costs:The European Union's toxicological dossier requirements and 18-month minimum evaluation timelines impose capital barriers for mid-scale textured protein entrants lacking dedicated regulatory affairs infrastructure.
- Soy Protein Isolate Substitution:Mature soy processing infrastructure and established GRAS status in the United States enable incumbent protein suppliers to undercut pea-based alternatives on formulated cost-per-kilogram.
Strategic Opportunities
- Chinese Foodservice Manufacturing:SAMR and NMPA import registration pathways for novel plant proteins remain underpenetrated by Western textured pea protein suppliers despite accelerating domestic alt-meat R&D investment.
- Precision Fermentation Convergence:Hybrid formulations combining textured pea protein scaffolding with fermentation-derived heme and fat precursors are opening premium positioning in whole-muscle analog categories.
- Subscription Formulation Services:Technical support contracts bundling extrusion parameter optimization with ingredient supply are capturing recurring revenue streams beyond commodity tonnage transactions.
Industry Challenges
- Extrusion Engineering Talent Scarcity:Food science programs produce insufficient specialists in high-moisture extrusion die design and shear-rate optimization for fibrous protein matrix development.
- Dual Certification Timeline Compression:Simultaneous pursuit of USDA Organic and Non-GMO Project Verified status for textured pea protein lines extends quality assurance cycles by 8-14 months.
- Legacy Starch Separation Integration:Retrofitting conventional pea fractionation facilities to capture both protein isolate and native starch co-products demands significant capital reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textured Pea Protein Market |
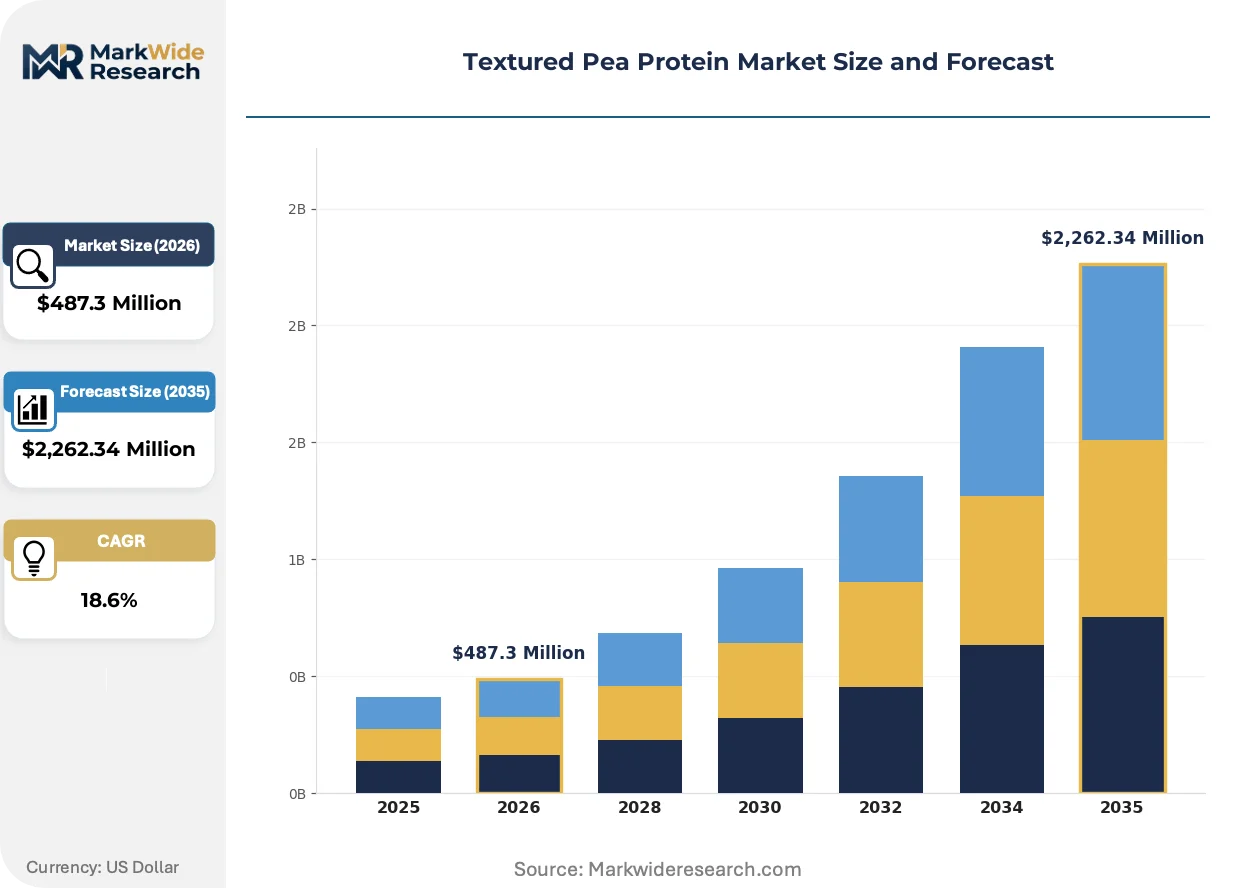
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured, Granules, Isolates, Powder Application: Meat Alternatives, Snacks, Dairy Alternatives, Bakery Products End User: Food Industry, Nutraceuticals, Beverage Industry, Animal Feed Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale |
| Companies Covered | Emsland Group, COSUCRA, Roquette Frères, Burcon NutraScience Corporation, Sotexpro, Ingredion Incorporated, The Scoular Company, Shandong Jianyuan Group, Puris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textured Pea Protein Market Strategic Shifts
Digital traceability infrastructure and AI-enabled extrusion control systems are converging to compress quality variance in textured protein manufacturing. These shifts are redrawing capability requirements for supplier-customer relationships.
High-moisture extrusion with real-time rheological feedback is automating fiber alignment consistency in textured pea protein output. Alt-meat formulators in the Netherlands and Denmark are adopting these systems at pilot scale before full production deployment. This automation is compressing batch-to-batch texture variance that previously required manual operator intervention.
EFSA's implementation of the EU AI Act is mandating algorithmic audit trails for digital traceability systems deployed across ingredient supply chains. Textured pea protein processors selling into EU27 markets must now document machine-learning-driven quality control decisions. Premium organic lines face the steepest compliance documentation requirements.
Buyer consolidation among multinational plant-based meat brands is consolidating formulation partnerships around fewer, deeper supplier relationships. Technical service contracts with guaranteed extrusion parameter support are displacing spot-market ingredient purchasing. Germany and the United Kingdom exhibit the most pronounced procurement model evolution toward integrated supply agreements.
Textured Pea Protein Market Segmentation
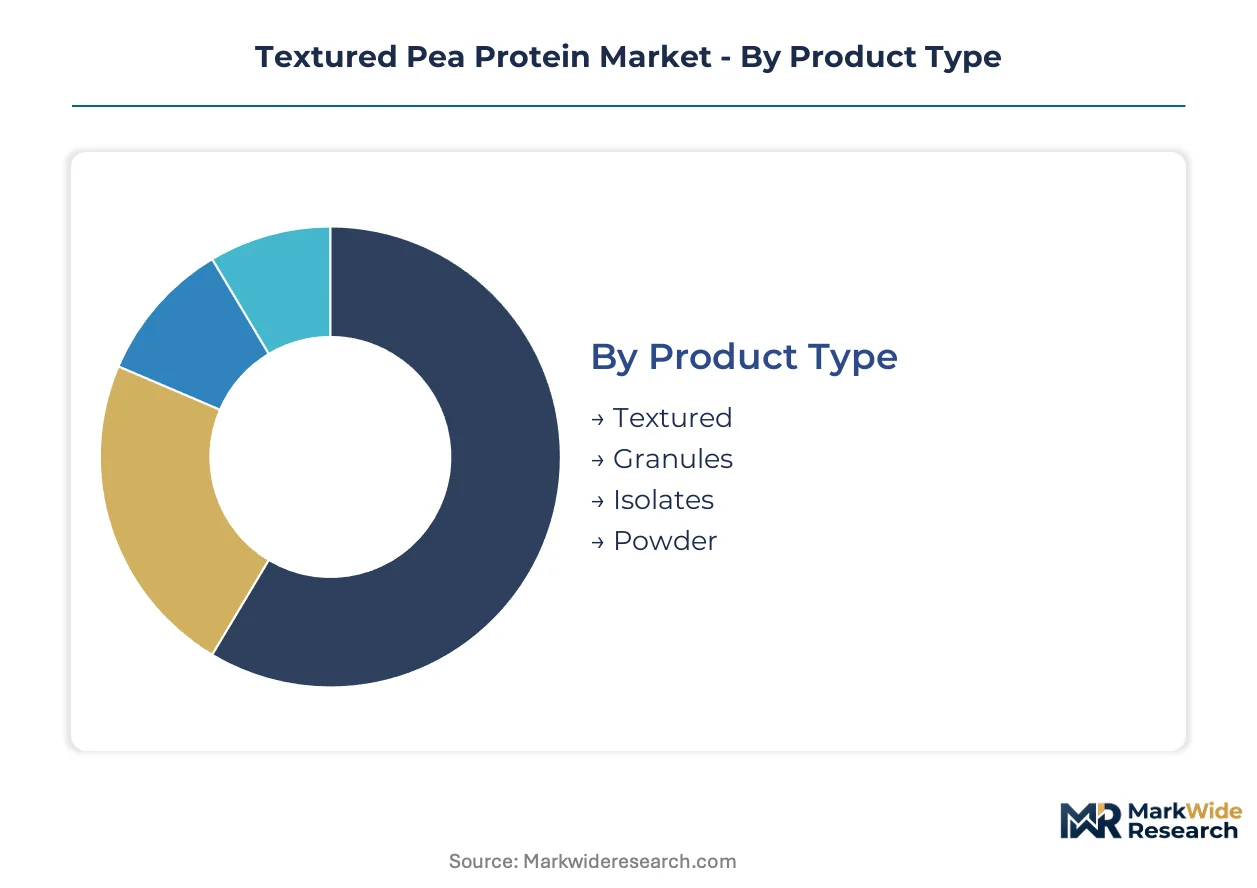
Segmentation in textured pea protein separates commodity-grade volume plays from premium functional grades that command formulation partnerships. Suppliers must align extrusion capability and regulatory dossier depth with the margin structure of each tier.
Product Type:
Volume-driven powder and textured variants dominate tonnage shipments, while isolates capture disproportionate margin pools through higher protein concentration and cleaner label positioning.
- Textured:Thermoplastic extrusion products containing 50-80% protein with fibrous, layered structures mimicking cooked muscle tissue. Germany's Ruhr food processing corridor drives offtake as plant-based meat manufacturers seek soy allergen reduction in retail-ready analogs.
- Isolates:Refined protein fractions exceeding 85% concentration with minimal carbohydrate and fiber content. Premium nutritional applications in sports nutrition and clinical formulations concentrate demand in the Netherlands and Denmark, where EFSA novel food authorizations accelerate ingredient clearance.
- Powder:Intermediate protein concentrates serving cost-sensitive bakery and snack applications. Functional hydration and emulsification performance determine supplier selection in mature European markets.
- Granules:Coarse-textured extrudates optimized for rehydration in foodservice manufacturing. Chinese SAMR import registration pathways remain underpenetrated despite accelerating domestic alt-meat R&D investment.
Today's leader: Textured. Tomorrow's challenger: Isolates.
Application:
Meat alternatives pull the steepest expansion trajectory through high-moisture extrusion maturation, while bakery products remain a mature, price-sensitive outlet where competition centers on functional performance.
- Meat Alternatives:Fastest-expanding channel driven by twin-screw extrusion technology enabling fibrous protein matrices that withstand industrial-scale rehydration. Twin-screw systems with real-time rheological feedback automate fiber alignment consistency in Netherlands and Denmark pilot deployments.
- Bakery Products:Mature outlet where textured pea protein competes on hydration capacity and crumb structure enhancement. Price sensitivity limits premium positioning despite clean-label trends.
- Snacks:Extruded puffed and sheeted applications leveraging pea protein's neutral flavor profile. Health Food Stores channel concentration in Germany and the United Kingdom shapes procurement specifications.
- Dairy Alternatives:Emerging use in fermented and frozen dessert applications requiring emulsion stability. EFSA's EU AI Act implementation is mandating algorithmic audit trails for digital traceability systems in these supply chains.
Meat alternatives claim the steepest expansion trajectory. Dairy alternatives present the longest development runway.
End User:
Food industry procurement is consolidating around integrated supply agreements with guaranteed extrusion parameter support, displacing spot-market purchasing.
- Food Industry:Dominant demand channel spanning plant-based meat, bakery, and snack manufacturing. Buyer consolidation among multinational brands is deepening supplier relationships around technical service contracts.
- Nutraceuticals:Premium-grade isolates for sports nutrition and clinical applications. Dual certification timelines for USDA Organic and Non-GMO Project Verified status extend quality assurance cycles.
- Beverage Industry:Soluble protein fractions for ready-to-drink formulations. Clarity and suspension stability drive specification requirements.
- Animal Feed:Lower-grade protein concentrates for pet food and livestock applications. Price competition with soy and other oilseed meals constrains margin.
Food industry integration is deepening fastest. Nutraceuticals offer the most defensible margin structure.
Distribution Channel:
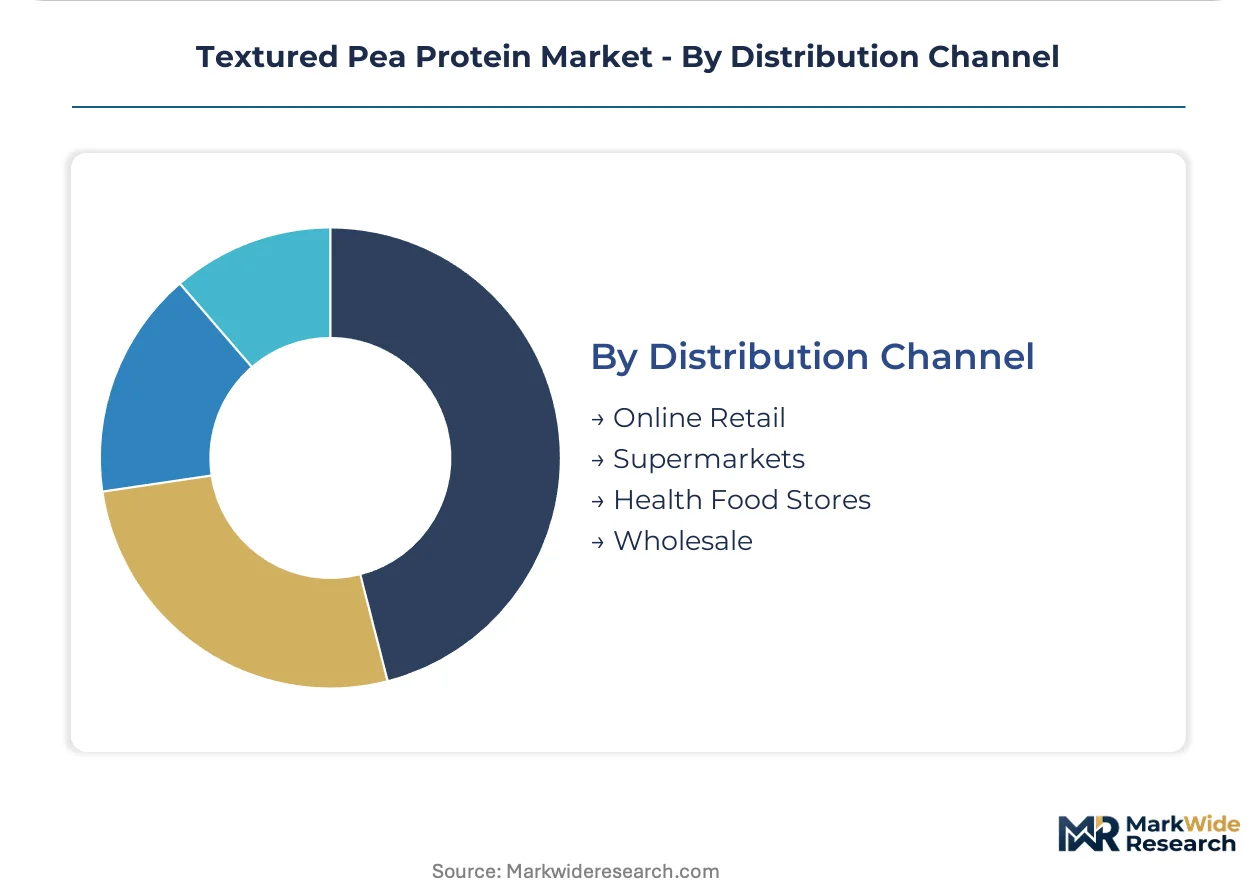
Procurement model evolution toward subscription-based formulation support is reshaping how suppliers monetize customer relationships beyond commodity tonnage.
- Wholesale:Bulk ingredient supply to food manufacturers and co-packers. Technical support contracts bundling extrusion parameter optimization capture recurring revenue streams.
- Online Retail:Direct-to-manufacturer platforms for specialty and organic grades. EFSA's EU AI Act documentation requirements steepen compliance burdens for premium organic lines.
- Supermarkets:Private-label and branded ingredient retail for small-scale foodservice. Limited penetration relative to other plant proteins.
- Health Food Stores:Specialty channel for organic and clean-label certified products. Germany and the United Kingdom exhibit the most pronounced procurement model evolution.
Wholesale technical integration leads current value capture. Online retail compliance costs are rising fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr food processing corridor pulls textured pea protein offtake at scale unmatched elsewhere, while Canada's Prairie Provinces anchor raw material supply security for North American extrusion capacity.
United States
Plant-based meat manufacturers in California and the Pacific Northwest drive demand for high-moisture extruded grades. FDA GRAS self-affirmation pathways enable faster ingredient clearance than EFSA timelines. Roquette Frères maintains supply security for alt-meat formulators through its European extraction network serving US customers.
Germany
EFSA novel food authorizations accelerate textured ingredient clearance across EU27 food manufacturing. The country's national food safety regulator enforces strict toxicological dossier requirements for pea protein isolates. Germany's Ruhr food processing corridor concentrates plant-based meat R&D investment from multinational brands.
China
Domestic alt-meat R&D investment accelerates despite SAMR and NMPA import registration barriers for Western suppliers. The country's national food and drug administration enforces stricter novel plant protein controls than US or EU equivalents. Yangtze River Delta foodservice manufacturers pilot hybrid formulations combining textured pea protein with fermentation-derived precursors.
Belgium
COSUCRA anchors specialty grade output through backward integration into Belgian yellow pea cultivation. EFSA's EU AI Act implementation mandates algorithmic audit trails for digital traceability systems in premium organic lines. Flanders-based extrusion facilities supply fibrous protein matrices to Netherlands and Denmark alt-meat pilots.
Canada
Yellow pea protein concentration risk exposes processors to climate-driven yield volatility in Prairie Provinces. Health Canada maintains novel food notification requirements less burdensome than EFSA's 18-month minimum evaluations. Saskatchewan and Manitoba rail logistics bottlenecks periodically disrupt raw material flows to North American fractionation plants.
Textured Pea Protein Market Competitive Environment
Top-tier vendors anchor integrated supply agreements with guaranteed extrusion parameter support, while mid-scale entrants struggle with EFSA authorization capital barriers. The vendor base clusters around three strategic archetypes: European extraction network operators, North American organic specialists, and Asian-scale commodity processors. Dominant competitive moves include backward integration into yellow pea cultivation and subscription-based formulation service bundling.
Within the European extraction tier, Roquette Frères and COSUCRA exemplify network-operating archetypes with continental supply security positioning. Puris occupies a distinct position among North American organic specialists through in-house production of both protein and starch fractions. Shandong Jianyuan Group represents the Asian-scale commodity processing archetype. Burcon NutraScience Corporation and Ingredion Incorporated sit within the ingredient technology licensing and distribution tier respectively.
| Leading Market Players |
|---|
| Emsland Group |
| COSUCRA |
| Roquette Frères |
| Burcon NutraScience Corporation |
| Sotexpro |
| Ingredion Incorporated |
| The Scoular Company |
| Shandong Jianyuan Group |
| Puris |
| Others |
Value Chain & Pricing Dynamics
High-moisture extrusion automation is compressing unit processing costs while concentrating production capability among Belgian and French ingredient houses with advanced twin-screw infrastructure. This technology transition simultaneously reduces per-kilogram conversion expenses and reinforces supply-side pricing power for processors with capital-intensive extrusion assets.
Pricing Analysis
Capacity additions in Belgium and France are reshaping price floors for textured grades across European alt-meat supply chains. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified isolates from commodity concentrates and feed-grade fractions. Cost compression in standard-tier powder variants is intensifying because soy protein isolate suppliers leverage mature GRAS infrastructure to undercut pea-based alternatives. Foodservice manufacturing channels exhibit the sharpest price sensitivity, while sports nutrition and clinical formulations accept premium positioning for isolate purity.
Supply Chain Analysis
Dual-sourcing requirements from multinational plant-based meat brands mandate multi-supplier qualification across Canadian, French, and Belgian raw material pipelines. Yellow pea protein concentrate draws from Canada's Prairie Provinces and France's Hauts-de-France region, with rail logistics from Saskatchewan and Manitoba feeding North American fractionation plants. Single-source vulnerability concentrates in European extrusion capacity clusters serving Germany's Ruhr corridor. Distribution runs through integrated supply agreements bundling technical service contracts with guaranteed extrusion parameter support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The textured pea protein market functions as a stable compounder anchored by irreversible formulation shifts in plant-based meat manufacturing. EFSA novel food streamlining and high-moisture extrusion maturation provide durable growth mechanics resistant to cyclical demand shocks.
For Market Incumbents: Acquire extrusion engineering talent pools to defend against capability scarcity threatening batch-to-batch quality consistency. Secure backward integration into Belgian and Canadian yellow pea cultivation to mitigate climate-driven yield volatility in Prairie Provinces. Deepen technical service contract penetration among Germany's Ruhr corridor formulators to displace spot-market purchasing.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in organic textured isolates offers white-space entry below Puris's North American positioning. Target Chinese foodservice manufacturing channels where SAMR import registration barriers have kept Western suppliers underpenetrated despite accelerating domestic alt-meat R&D. Lead with hybrid formulation partnerships combining textured pea protein scaffolding with fermentation-derived precursors.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European processors lacking dedicated EFSA regulatory affairs infrastructure. The five-to-ten-year viability window favors acquisition targets with captive extrusion capacity and established novel food dossiers. Watch EFSA clearance timeline compression as the inflection signal accelerating ingredient authorization cycles across EU27 supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yellow Pea Cultivation | COSUCRA's Belgian farming control secures specialty grade output against Prairie Province climate volatility. |
| High-Moisture Extrusion Capacity Expansion | Netherlands and Denmark pilot deployments automate fiber alignment consistency for industrial-scale rehydration. |
| EFSA Novel Food Dossier Investment | Accelerated evaluation pathways compress time-to-market for textured ingredient variants entering EU27 manufacturing. |
| Subscription Formulation Services Launch | Technical support contracts capture recurring revenue streams beyond commodity tonnage transactions. |
| Chinese SAMR Import Registration Pursuit | Yangtze River Delta foodservice penetration opens hybrid formulation opportunities with fermentation-derived precursors. |
Study Parameters
Direct dialogue with extrusion engineering directors, plant-based meat formulation leads, EFSA regulatory affairs specialists, and yellow pea procurement managers grounded qualitative findings in operational reality. Secondary validation drew from EFSA novel food opinions, FDA GRAS notifications, EU AI Act implementation guidance, customs trade data for pea protein concentrates, and SEC filings from publicly traded ingredient processors. Bottom-up capacity assessments across Belgian, French, and North American extrusion facilities were triangulated against top-down demand modeling from alt-meat brand procurement disclosures.
Bottom-up analysis segmented volume and value across the projection horizon by product type, application channel, end-user category, and distribution model. The analytical framework incorporated protein concentration tiers, certification status, and geographic production hub as cross-cutting dimensions. CAGRs were derived from weighted capacity expansion schedules and formulation adoption curves in meat alternative manufacturing. Industry-specific inputs included EFSA authorization timeline distributions, high-moisture extrusion yield coefficients, and organic certification lag periods.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation hybrid formulations would alter the outlook for textured pea protein demand concentration. Forecasts reflect assumptions about EFSA streamlining continuity, extrusion automation diffusion rates, and soy protein substitution elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Canada Plant-Based Food and Beverages Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Middle East and Africa Plant-Based Meat and Dairy Products Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
India Plant Protein Market
Plant Based Food
North America Tofu Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Vegan Meals Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Chicory Roots Market