
 Rice Milk Market | 2026-2036
Rice Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Milk Market Outlook
Single-source reliance on Asian rice protein suppliers is decoupling as North American brands diversify procurement. SunOpta leverages its integrated organic ingredient sourcing to secure supply chain resilience against commodity volatility. Vitasoy International Holdings anchors its position through decades of soy and rice beverage expertise across Asia-Pacific retail channels. WhiteWave Foods competes via established refrigerated distribution networks that dominate conventional grocery placement.
Rice milk is an aqueous emulsion produced by enzymatically treating milled rice with alpha-amylase to hydrolyze starches into fermentable sugars, then filtering and homogenizing to achieve suspension stability between 2-4% fat content, primarily serving as a hypoallergenic dairy alternative for consumers with soy, nut, or lactose intolerances. Organic rice milk occupies the premium tier where certification costs and smaller batch sizes sustain higher per-unit margins despite slower velocity. Barista blend rice milk leads formulation growth as higher protein and fat modifications enable microfoam stability that standard varieties cannot achieve, while ready-to-drink formats remain the volume workhorse in convenience channels.
FDA allergen labeling rules and EFSA novel food consultations shape formulation transparency requirements on both sides of the Atlantic, with organic certification under USDA National Organic Program and EU Regulation 2018/848 adding compliance layers that filter smaller producers from premium shelf placements. China's SAMR dairy-alternative standards and Japan's Food Labeling Act further fragment the regulatory map for exporters. Stakeholders must monitor how pending protein content thresholds in draft EU plant-based milk nomenclature rules reshape competitive positioning between fortified and standard formulations.
Market Dynamics
Formulation differentiation is fragmenting the rice milk category as barista-grade emulsions command premium placement against commodity shelf-stable variants, with enzymatic hydrolysis protocols becoming the decisive technical barrier separating functional tiers.
Growth Catalysts
- Allergen-free positioning:FDA updated labeling guidelines clarify how manufacturers structure hypoallergenic claims, reducing litigation exposure for brands targeting soy and nut-intolerant consumers.
- Specialty coffee channel expansion:Independent cafes across Germany, the United States, and Japan are adopting rice milk for latte art applications where microfoam stability determines menu placement.
- Enzymatic processing advances:Alpha-amylase hydrolysis protocols are improving starch-to-sugar conversion efficiency, enabling cleaner flavor profiles that reduce masking additive loads.
Market Restraints
- Input cost volatility:Organic rice premiums fluctuate with climate-induced harvest variability across Thai and Vietnamese growing regions, compressing margin predictability for certified product lines.
- Protein fortification limitations:Rice protein's incomplete amino acid profile requires blending with pea or soy isolates to achieve nutritional parity, complicating clean-label positioning.
- Refrigerated distribution concentration:Cold-chain infrastructure gaps in secondary markets restrict barista blend penetration beyond major metropolitan clusters.
Strategic Opportunities
- Ready-to-drink convenience channel:Single-serve formats remain underdeveloped in vending and grab-and-go retail across France, Italy, and Spain relative to soy and oat alternatives.
- EU organic certification harmonization:Regulation 2018/848 implementation is streamlining cross-border organic recognition, reducing duplicate audit burdens for multi-market suppliers.
- Pediatric and senior nutrition:Hypoallergenic positioning aligns with institutional feeding programs seeking reduced-allergen meal solutions for sensitive populations.
Industry Challenges
- Formulation talent scarcity:Food scientists with simultaneous expertise in enzymatic hydrolysis and emulsion stability command premium compensation, constraining mid-tier brand R&D expansion.
- Dual certification timelines:USDA National Organic Program and EU organic parallel approvals extend product launch cycles by eight to fourteen months for premium tier entries.
- Homogenization equipment backlogs:High-pressure processing unit lead times from specialized manufacturers are delaying capacity expansion for barista blend production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Milk Market |
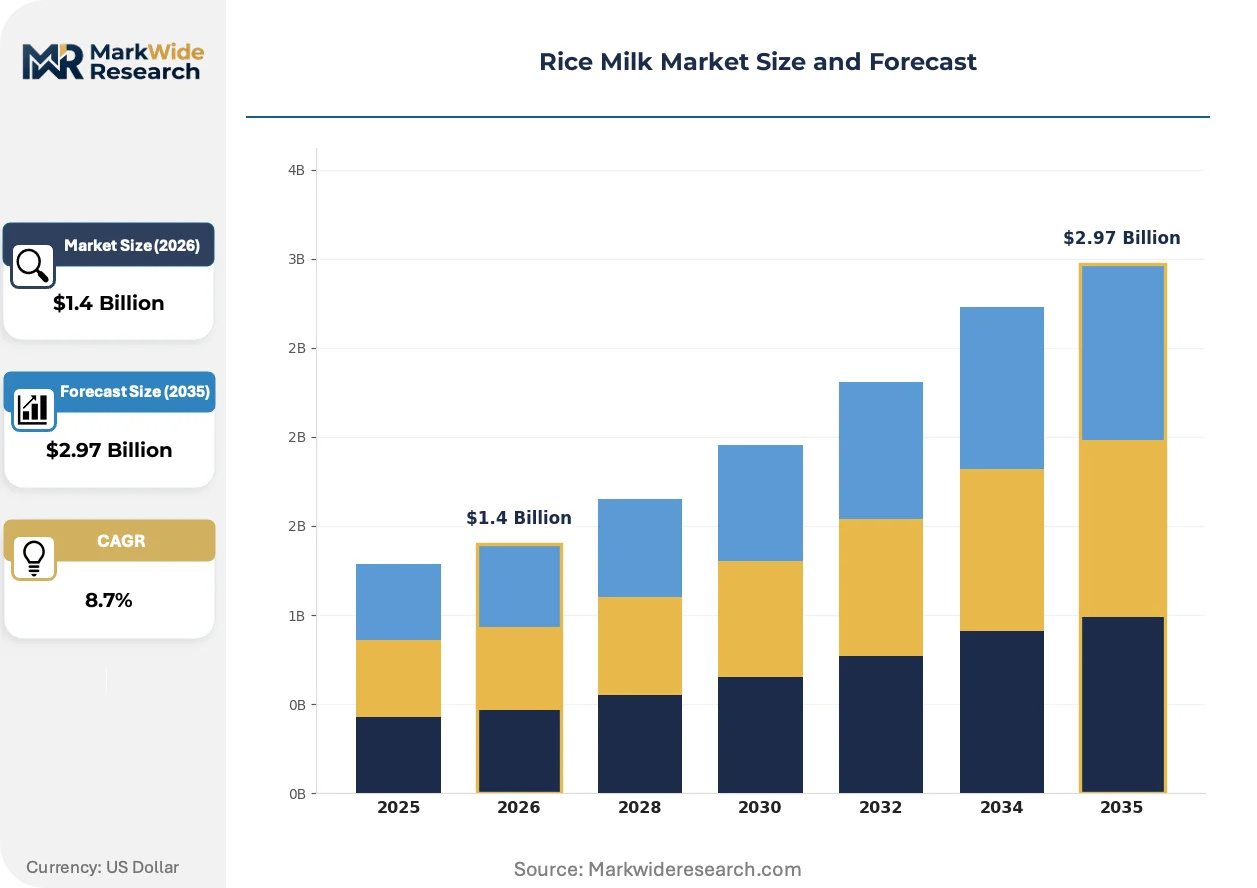
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Rice Milk, Traditional Rice Milk, Flavored Rice Milk, Unsweetened Rice Milk Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Stores Formulation: Fortified Rice Milk, Enriched Rice Milk, Barista Blend Rice Milk, Ready-to-Drink Rice Milk End User: Households, Restaurants, Cafes, Bakeries |
| Companies Covered | SunOpta, Pureharvest, Vitasoy International Holdings, Dream, Gan Teck Kar Foods, The Hain Celestial Group, WhiteWave Foods, Stremicks Heritage Foods, Pacific Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Milk Market Strategic Shifts
Processing technology convergence and regulatory clarity are compressing the gap between artisanal formulation claims and industrial-scale production, reshaping how brands architect their technical narratives.
High-pressure homogenization systems are modularizing production architecture for barista-grade rice milk, allowing mid-scale facilities to replicate microfoam performance previously requiring capital-intensive continuous processing infrastructure. Specialty coffee roasters in Melbourne, Portland, and Copenhagen are adopting these systems for in-house private-label development. The technology is modularizing capital deployment patterns, enabling smaller entrants to contest refrigerated case placement without full-scale plant investment.
EFSA novel food consultations are tightening protein content disclosure thresholds for plant-based milk analogues, forcing reformulation transparency that exposes fortification gaps between premium and standard tiers. The industrial consequence is accelerated R&D spending on complete protein blending systems to preempt competitive disadvantage. German and Dutch brands are responding fastest, leveraging existing organic supply chain relationships to source complementary protein inputs ahead of formal rule adoption.
Cafe procurement patterns are rotating toward direct supplier relationships that bypass traditional beverage distribution intermediaries, with volume commitments tied to exclusive formulation development. This channel disintermediation is most visible in Tokyo's specialty coffee district and Brooklyn's independent cafe cluster, where buyers negotiate custom fat and protein specifications. The shift compresses switching costs and rewards technical responsiveness over brand heritage, favoring agile regional processors against multinational portfolio players.
Rice Milk Market Segmentation
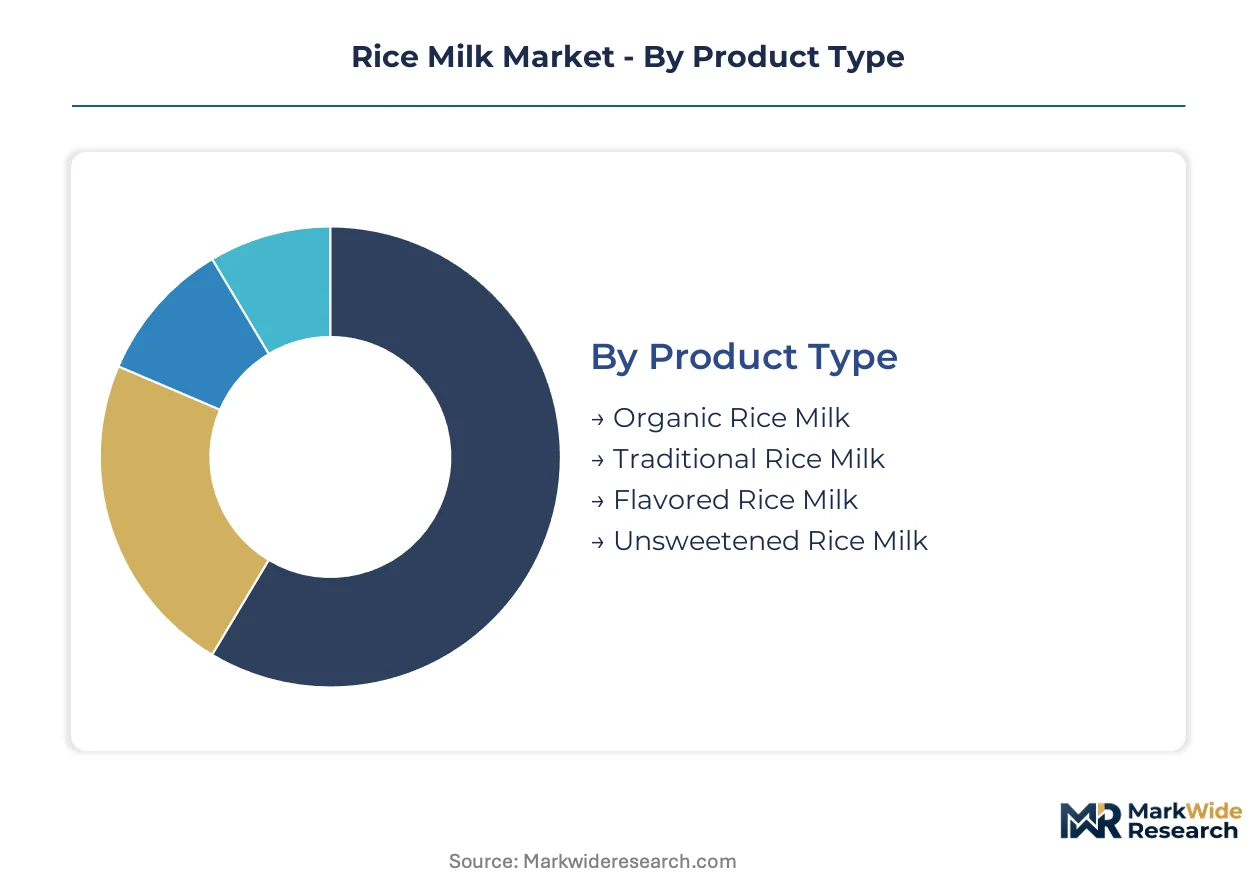
Rice milk segmentation reflects divergent supply chain configurations across certification tiers, formulation technologies, and channel economics. Understanding these partitions reveals where margin compression concentrates and where technical differentiation commands pricing power.
Product Type:
Organic rice milk production concentrates in certified milling facilities across Thai and Vietnamese growing regions where climate volatility shapes input cost structures.
- Organic Rice Milk:USDA National Organic Program and EU Regulation 2018/848 certification requirements sustain premium positioning through controlled supply chains. German retailers REWE and Edeka have expanded private-label shelf space for certified variants as allergen-free positioning hardens into purchase criteria.
- Traditional Rice Milk:Standard milling protocols without enzymatic enhancement dominate volume production. Conventional grocery placement in the United States relies on established refrigerated distribution networks where velocity metrics determine slotting fees.
- Flavored Rice Milk:Vanilla and chocolate variants target pediatric nutrition segments through masking additive loads that complicate clean-label positioning.
- Unsweetened Rice Milk:Zero-sugar formulations serve diabetic and ketogenic diet adherents via health food store channels with higher margin structures than mass retail.
Traditional rice milk absorbs the bulk of installed capacity; organic rice milk is expanding most quickly.
Distribution Channel:
Channel economics fragment rice milk profitability through divergent cold-chain requirements and slotting fee structures.
- Supermarkets:Conventional grocery placement demands refrigerated case infrastructure that bars smaller producers from national distribution. WhiteWave Foods leverages established networks to dominate conventional retail positioning.
- Health Food Stores:Independent natural retailers in Portland and Brooklyn prioritize barista-grade formulations with higher protein and fat modifications for specialty coffee applications.
- Online Retailers:Direct-to-consumer subscription models bypass slotting fee structures but absorb shipping costs that compress margins on shelf-stable formats.
- Specialty Stores:Asian grocery channels in Tokyo and Melbourne stock imported variants targeting diaspora consumers with taste profiles calibrated to regional preferences.
Supermarkets absorb the bulk of installed capacity; online retailers are climbing the fastest.
Formulation:
Enzymatic processing capabilities separate functional tiers through alpha-amylase hydrolysis efficiency and emulsion stability performance.
- Barista Blend Rice Milk:Higher protein and fat modifications achieve microfoam stability that standard varieties cannot replicate. Specialty coffee shops in Copenhagen and Melbourne specify custom fat content for latte art applications.
- Ready-to-Drink Rice Milk:Single-serve formats dominate convenience channel velocity in Japan's vending infrastructure and North American grab-and-go retail. UHT processing enables ambient distribution that bypasses cold-chain constraints.
- Fortified Rice Milk:Vitamin and mineral additions target nutritional parity with dairy, requiring disclosure protocols under FDA allergen labeling rules.
- Enriched Rice Milk:Protein isolates from pea or soy address amino acid profile incompleteness, complicating hypoallergenic claims for sensitive consumers.
Ready-to-drink rice milk absorbs the bulk of installed capacity; barista blend rice milk is gaining share fastest.
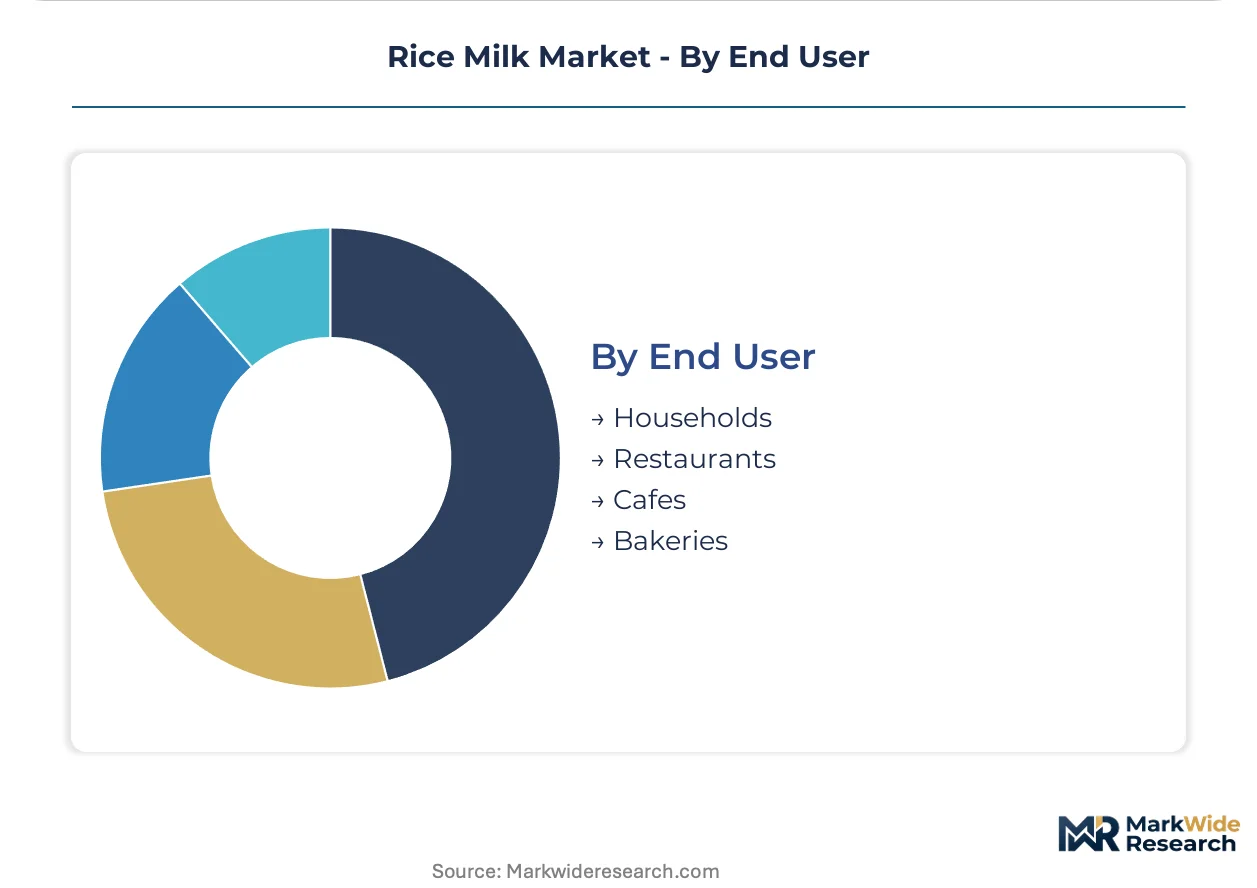
End User:
Demand concentration patterns diverge between institutional procurement with volume commitments and household purchase with brand loyalty fragmentation.
- Cafes:Independent coffee shops in Tokyo's specialty district and Brooklyn negotiate direct supplier relationships with custom formulation specifications. Procurement bypasses traditional beverage distribution intermediaries.
- Households:Retail purchase patterns concentrate in allergen-free households with soy and nut intolerances, where hypoallergenic positioning drives substitution behavior.
- Restaurants:Foodservice procurement prioritizes cost efficiency over technical performance, favoring shelf-stable formats with extended ambient storage.
- Bakeries:Ingredient applications in gluten-free baking formulations leverage rice milk's neutral flavor profile and moisture retention properties.
Households absorb the bulk of installed capacity; cafes are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai and Vietnamese organic rice growing regions anchor supply-side geography, while German retail networks and Japanese vending infrastructure concentrate demand-side pull across divergent channel economics.
United States
FDA updated allergen labeling guidelines clarify hypoallergenic claim structures for soy and nut-intolerant consumers. Independent cafes in Brooklyn and Portland negotiate direct supplier relationships with custom fat specifications for latte art applications. Cold-chain infrastructure gaps in secondary markets restrict barista blend penetration beyond major metropolitan clusters.
Germany
REWE and Edeka store networks have expanded private-label shelf space for certified organic variants as allergen-free positioning hardens into purchase criteria. EU Regulation 2018/848 streamlines cross-border organic recognition, reducing duplicate audit burdens for multi-market suppliers. Specialty coffee roasters in Berlin and Hamburg adopt high-pressure homogenization systems for in-house private-label development.
Japan
The Food Labeling Act shapes formulation transparency requirements for plant-based milk analogues entering retail channels. Tokyo's specialty coffee district procurement patterns rotate toward direct supplier relationships that bypass traditional beverage distribution intermediaries. Vending infrastructure dominates ready-to-drink format velocity through UHT-processed ambient distribution.
China
SAMR dairy-alternative standards fragment the regulatory map for exporters seeking market access. SunOpta leverages integrated organic ingredient sourcing to secure supply chain resilience against commodity volatility. Shanghai and Beijing retail channels concentrate volume for imported variants targeting diaspora consumers with regionally calibrated taste profiles.
Australia
Specialty coffee roasters in Melbourne adopt modular high-pressure homogenization systems to replicate microfoam performance previously requiring capital-intensive continuous processing infrastructure. Asian grocery channels stock imported variants targeting diaspora consumers. Direct-to-consumer subscription models bypass slotting fee structures but absorb shipping costs that compress margins.
Rice Milk Market Competitive Environment
Global majors compete with regional champions across enzymatic processing capabilities and refrigerated distribution reach. The vendor base separates into three functional tiers: integrated organic ingredient specialists, established refrigerated network operators, and agile regional processors with barista-grade technical responsiveness. Strategic moves concentrate on backward integration into Thai and Vietnamese certified milling facilities and portfolio diversification into barista blend formulations.
Among Asia-Pacific anchored beverage conglomerates, Vitasoy International Holdings occupies a position representing decades of soy and rice beverage expertise across retail channels. SunOpta exemplifies the integrated organic ingredient sourcing archetype, securing captive supply chain resilience. WhiteWave Foods sits within the established refrigerated distribution tier, dominating conventional grocery placement through velocity-based slotting fee structures.
| Leading Market Players |
|---|
| SunOpta |
| Pureharvest |
| Vitasoy International Holdings |
| Dream |
| Gan Teck Kar Foods |
| The Hain Celestial Group |
| WhiteWave Foods |
| Stremicks Heritage Foods |
| Pacific Foods |
| Others |
Value Chain & Pricing Dynamics
Family-owned milling cooperatives across Thai and Vietnamese organic growing regions anchor upstream supply, translating harvest volatility into asymmetric pricing power that favors integrated processors with captive certification relationships over spot-market dependent brands.
Pricing Analysis
Extended shelf-life guarantees and cold-chain integrity warranties separate premium barista blends from unbundled commodity shelf-stable variants. Three-tier pricing structure across premium, standard, and economy levels stratifies by USDA National Organic Program certification status and enzymatic processing sophistication. Cost compression in standard-tier conventional milling is intensifying because Thai harvest variability feeds input price swings. Foodservice procurement teams exhibit highest price sensitivity, while specialty coffee roasters in Copenhagen and Melbourne absorb premiums for custom fat specification performance.
Supply Chain Analysis
USDA National Organic Program and EU Regulation 2018/848 certification gating filters supplier pools to certified milling facilities across Thailand, Vietnam, and select North American organic acreage. Alpha-amylase enzyme inputs and high-pressure homogenization equipment draw from specialized chemical and industrial machinery suppliers concentrated in Germany and Japan. Single-source vulnerability concentrates in Thai organic rice premiums where climate-induced harvest variability disrupts contracted offtake. Distribution runs through refrigerated networks for barista blends and ambient UHT channels for ready-to-drink formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rice milk competitive dynamics favor consolidation plays as formulation talent scarcity and dual certification timelines force sub-scale brands toward exit or acquisition.
For Market Incumbents: Lock in backward integration into Thai and Vietnamese certified milling facilities to secure supply chain resilience against commodity volatility. Expand barista blend production capacity through modular high-pressure homogenization systems that replicate microfoam performance without capital-intensive continuous processing infrastructure. Emerging regional processors with technical responsiveness threaten refrigerated case placement dominance. For New Entrants and Emerging Players: Independent cafes in Tokyo's specialty district and Brooklyn represent an underserved buyer archetype seeking direct supplier relationships with custom formulation specifications. Vending and grab-and-go retail across France, Italy, and Spain offers underdeveloped white-space for single-serve ready-to-drink formats. Pursue technical partnership positioning with specialty coffee roasters rather than brand heritage competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier organic-certified brands with established EU Regulation 2018/848 approvals but constrained R&D expansion in Germany and Australia. Long-term viability across the analysis window hinges on enzymatic processing capabilities and refrigerated distribution reach. Monitor EFSA novel food consultation outcomes on protein content disclosure thresholds as inflection indicator for fortification-driven competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Milling | Captive supply from Thai and Vietnamese organic acreage secures margin predictability against harvest volatility. |
| Barista Blend Formulation Development | Higher protein and fat modifications enable microfoam stability that commands premium placement in Copenhagen specialty coffee channels. |
| Dual Certification Investment | Parallel USDA National Organic Program and EU Regulation 2018/848 approvals unlock premium shelf space in REWE and Edeka networks. |
| Direct Cafe Procurement Relationships | Bypassing traditional beverage distribution intermediaries compresses switching costs and rewards technical responsiveness in Brooklyn. |
| Modular High-Pressure Homogenization Deployment | Smaller facilities replicate barista-grade performance without capital-intensive continuous processing infrastructure in Melbourne. |
Study Parameters
Trade databases, organic certification registries, and foodservice procurement records formed the secondary backbone, cross-referenced with primary interviews involving enzymatic processing specialists, specialty coffee roasters, refrigerated distribution operators, and retail category buyers. Bottom-up volume modeling triangulated against top-down value assessments across certification tiers and formulation technologies.
Historical trendline analysis of organic rice input costs and barista blend adoption patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product certification status, enzymatic processing capability, distribution channel cold-chain requirements, and end-use concentration between household and cafe procurement. CAGRs derived from weighted average growth trajectories incorporating FDA allergen labeling compliance costs and EFSA novel food consultation timelines as industry-specific forecast inputs.
Revisions become necessary when EFSA protein content disclosure thresholds materialize in final rule form or when Thai harvest variability disrupts organic rice supply contracts. Forecasts reflect documented assumptions on certification timeline standardization and specialty coffee channel expansion velocity. A model refresh is warranted upon material change in FDA plant-based labeling guideline enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Coconut Milk Derivatives Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Flax Milk Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
South Korea Dairy Alternatives Market
Dairy Alternatives
North America Non-Dairy Cheese Market