
 Low-Calorie Coconut Milk Market | 2026-2036
Low-Calorie Coconut Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Coconut Milk Market Analytics
The low-calorie coconut milk category is pivoting as premium cold-pressed variants separate from commodity heat-processed lines on both price and ingredient transparency. Thai Coconut Public Company Limited leverages integrated plantation-to-package operations across Thailand's central plains. Silk anchors its position through refrigerated distribution dominance in North American retail channels. Vita Coco differentiates via single-origin sourcing claims and sports-focused marketing partnerships.
Low-calorie coconut milk denotes coconut extract diluted to reduced fat content, typically below 3 grams per 100 milliliters, achieved through controlled pressing and centrifugal separation rather than full-fat emulsion. The product serves as a dairy alternative in beverages, curries, and baked formulations where caloric reduction matters. Unsweetened variants lead volume as ketogenic and sugar-conscious consumers reject added sweeteners, while tetra pack formats capture the fastest growth due to ambient shelf stability and e-commerce shipping efficiency. Food manufacturers represent a concentrated margin pool as bulk procurement contracts lock in multi-year supply relationships.
FDA nutrition labeling rules and EFSA health claim assessments shape permissible fat-content descriptors and "low-calorie" qualification thresholds across export markets. Thailand's Ministry of Agriculture enforces Good Agricultural Practice standards for coconut farming that constrain raw material scalability. Stakeholders must monitor evolving plant-based dairy alternative classification battles in the EU and US, as these determine whether coconut milk faces dairy-style nutritional fortification mandates or remains exempt.
Market Dynamics
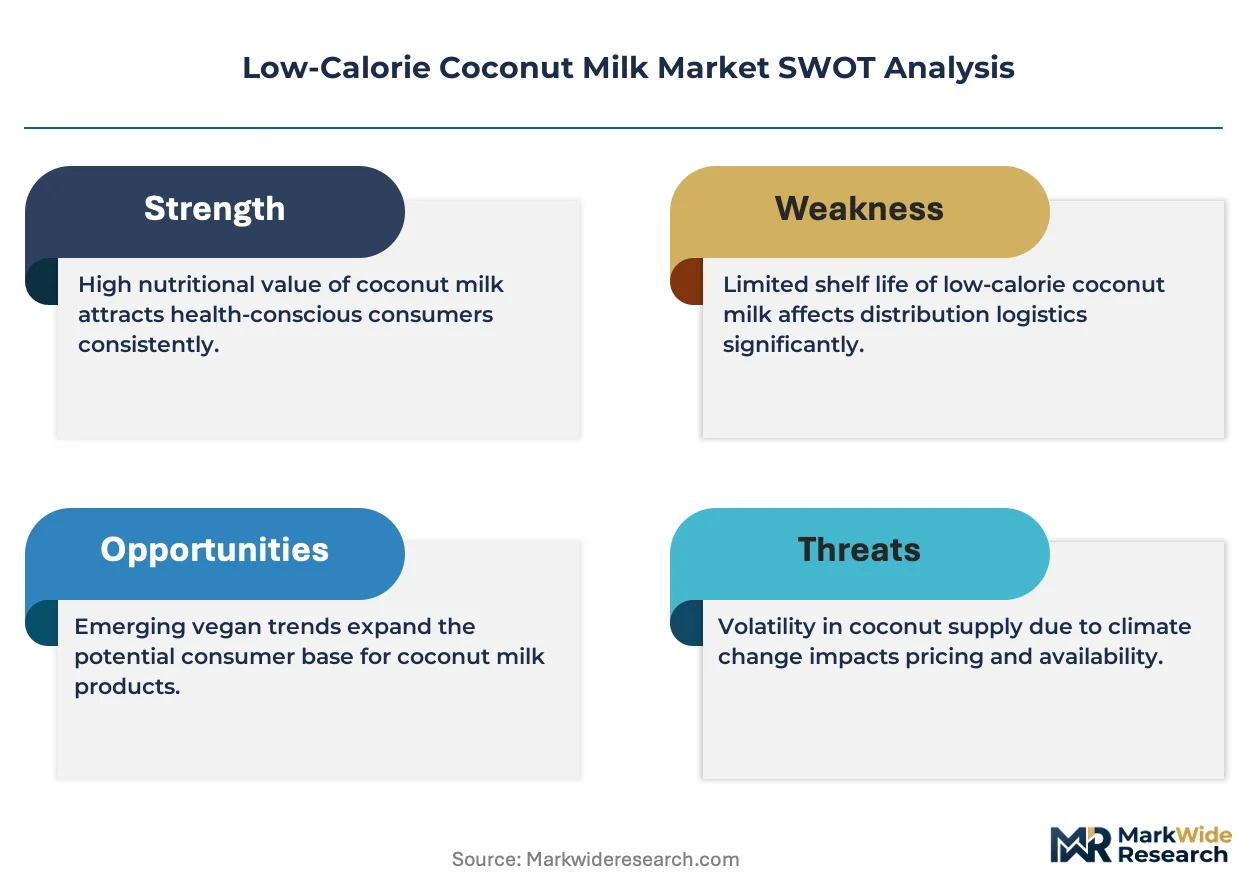
Clean-label mandates from FDA and EFSA are compressing additive tolerances and forcing reformulation investments across the low-calorie coconut milk supply base. This regulatory tightening intersects with raw material concentration in Southeast Asian plantation belts to create margin pressure on mid-tier processors lacking captive sourcing.
Growth Catalysts
- Specialty coffee chain adoption:North American and European café networks now specify low-calorie coconut milk as a standard dairy alternative, creating institutional volume commitments that stabilize procurement planning for processors.
- REACH-compliant clean-label formulations:European manufacturers reformulating under EFSA additive restrictions are capturing shelf space from legacy brands with longer ingredient decks.
- Cold-pressing technology diffusion:Centrifugal separation systems enabling sub-3% fat content without thermal degradation are expanding production capacity in Thailand's central plains processing clusters.
Market Restraints
- Raw material geographic concentration:Over 70% of global coconut supply originates from Indonesian, Philippine, and Thai smallholder plantations, exposing processors to climate volatility and logistics bottlenecks in the Strait of Malacca corridor.
- FDA nutrition labeling compliance costs:Recalibrating fat-content descriptors and "low-calorie" qualification thresholds for US export batches imposes recurring analytical and documentation burdens on mid-cap producers.
- Oat milk substitution threat:Nordic and German food manufacturers are pivoting formulation trials toward domestically sourced oat bases to reduce tropical commodity exposure and simplify supply chains.
Strategic Opportunities
- Tetra pack ambient distribution:Shelf-stable packaging formats are unlocking e-commerce direct-to-consumer channels previously inaccessible to refrigerated coconut milk variants.
- Indian ketogenic diet expansion:Unsweetened low-calorie variants align with FSSAI-compliant sugar reduction campaigns targeting urban metabolic health segments in Mumbai and Bangalore.
- EU Green Deal agricultural incentives:Carbon footprint certification protocols for Southeast Asian exporters are creating premium positioning for plantation-to-package operations with verified deforestation-free sourcing.
Industry Challenges
- Centrifugal separation technician scarcity:Cold-pressing facilities in emerging processing hubs face recruitment gaps for operators capable of maintaining fat-content precision below 3% thresholds.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and BIS compliance pathways for unified product specifications extend time-to-market by 8-14 months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Coconut Milk Market |
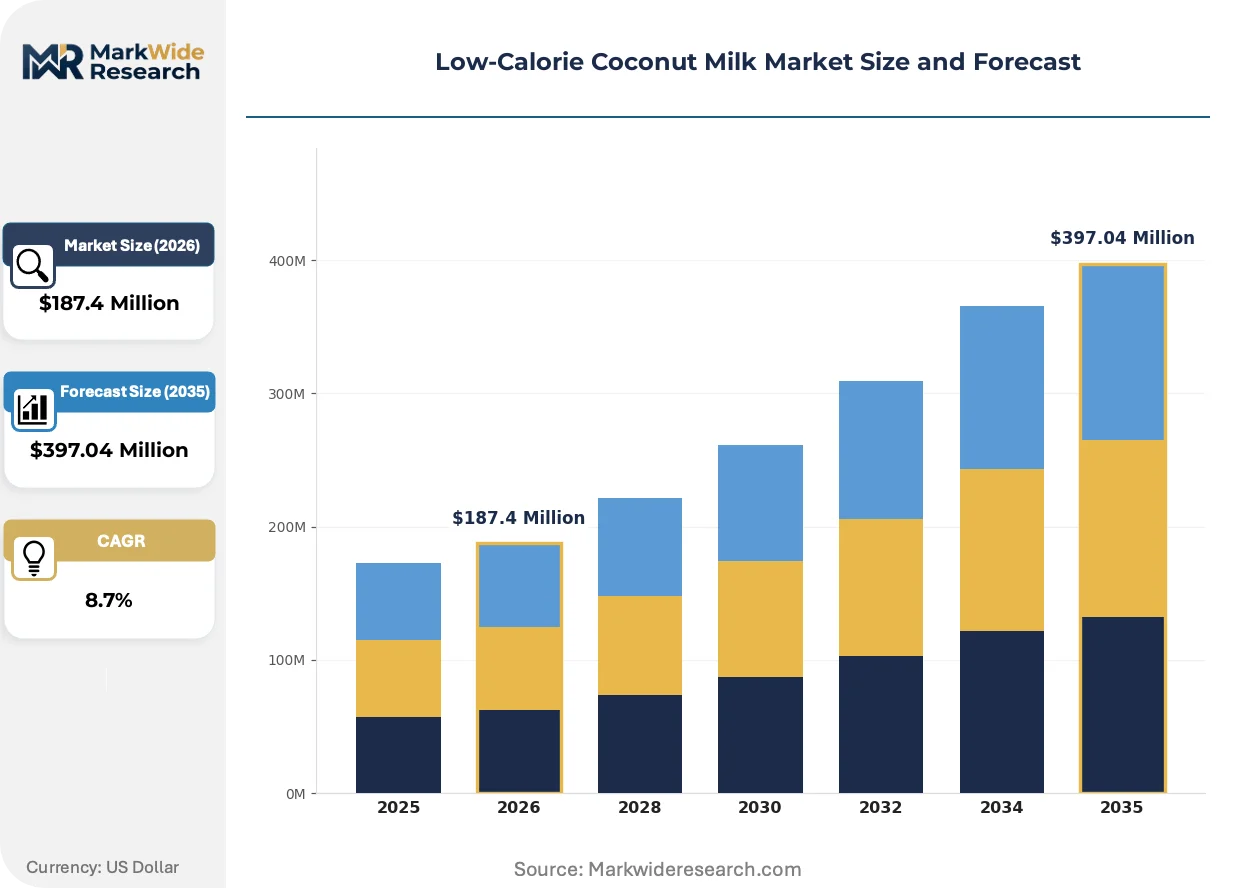
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Sweetened, Flavored, Cream Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores End User: Individuals, Restaurants, Cafés, Food Manufacturers Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | Thai Coconut Public Company Limited, Silk (Whitewave), GraceKennedy Limited, AroyD, Thai Agri Foods Public Company Limited, So Delicious Dairy Free, Pacific Foods, Goya Foods, Vita Coco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Coconut Milk Market Evolving Landscape
Processing technology and packaging format evolution are fragmenting the low-calorie coconut milk category into distinct quality tiers with divergent margin structures. Regulatory alignment pressures and channel-specific consumption patterns are simultaneously reshaping competitive positioning.
Microfiltration systems employing ceramic membrane arrays are decentralizing quality control from centralized laboratories to production-line environments. Thai and Indonesian processors are adopting these systems to enable real-time fat-content adjustment without batch hold times. This capability compression is allowing smaller facilities to achieve specification consistency previously requiring capital-intensive centrifuge infrastructure.
EFSA health claim assessments under the EU Nutrition and Health Claims Regulation are constraining permissible fat-content marketing language for coconut milk exports into European retail channels. Manufacturers must now substantiate "low-calorie" descriptors with validated analytical methodologies rather than formulation proxies. Ambient tetra pack variants with extended shelf-life documentation are capturing disproportionate shelf space as retailers prioritize reduced spoilage risk.
Ketogenic and sugar-conscious consumers are rejecting sweetened coconut milk variants in favor of unsweetened SKUs with zero added carbohydrates. This preference shift is compressing the traditional premium attached to flavored or sweetened product lines. North American specialty grocery channels and direct-to-subscription platforms are the primary beneficiaries of this rotation, with conventional supermarkets slower to rebalance their assortment mix.
Low-Calorie Coconut Milk Market Segmentation
Low-calorie coconut milk procurement patterns diverge sharply across buyer types, with institutional contracts locking in multi-year supply while direct-to-consumer channels reward format innovation. Understanding segment-level decision drivers reveals where margin pools concentrate versus where volume scales.
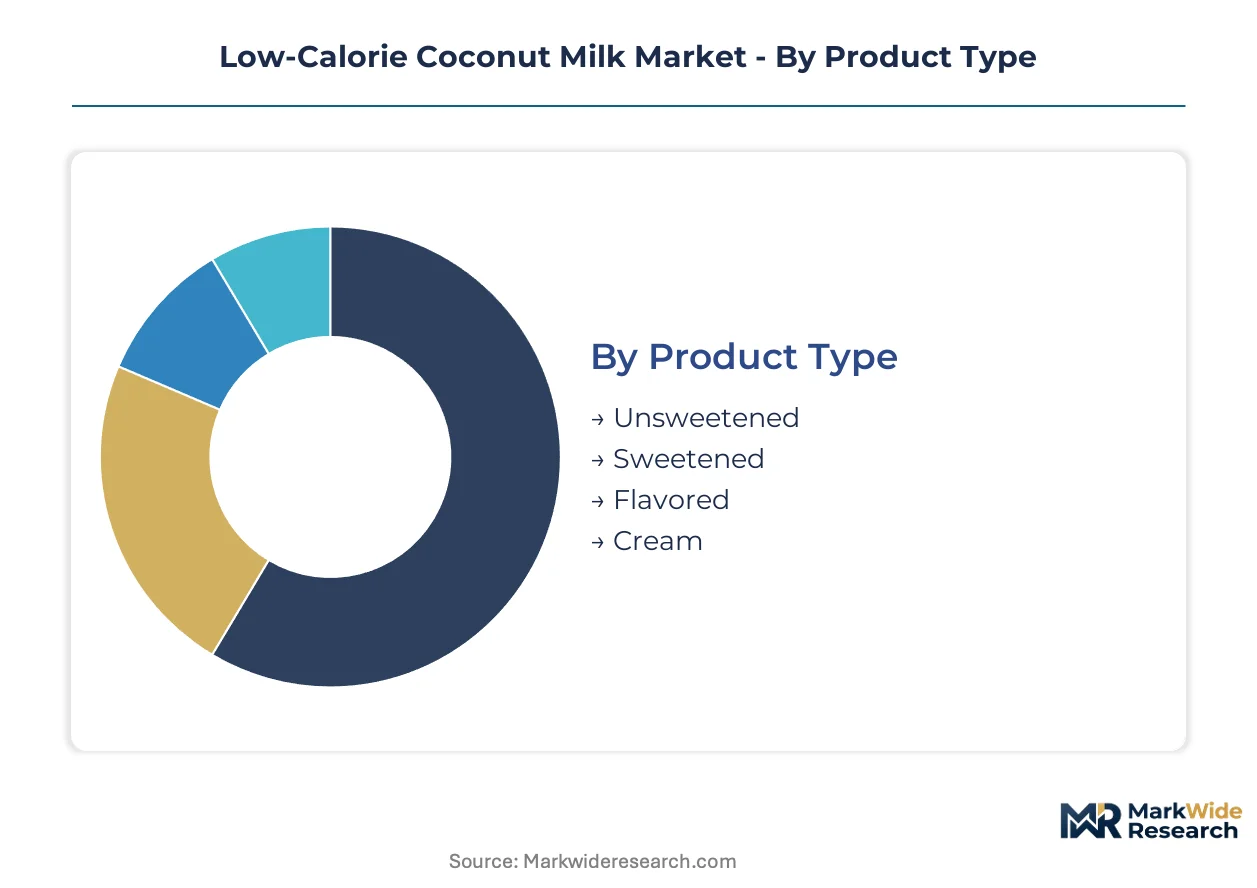
Product Type:
Caloric control and dietary compliance drive purchase selection, with sugar content thresholds separating premium positioning from commodity competition.
- Unsweetened:Zero-added-sugar formulation achieves sub-3% fat content through centrifugal separation alone. Demand concentrates in North American ketogenic and diabetic consumer segments where carbohydrate labeling scrutiny is highest.
- Sweetened:Added cane or coconut sugar increases caloric density above low-calorie thresholds, pushing this segment toward dessert applications and Southeast Asian traditional beverage markets where taste preference overrides nutritional claims.
- Flavored:Vanilla and chocolate variants target café beverage formulation with ingredient transparency requirements under FDA and EFSA additive guidelines.
- Cream:Higher fat concentration suits curry base and sauce applications in Thai and Indonesian food manufacturing.
Volume sits with Unsweetened; growth tilts toward Flavored as specialty coffee chains expand formulation partnerships.
Distribution Channel:
Channel selection determines shelf-life requirements, packaging format compatibility, and margin capture potential for processors.
- Supermarkets:Ambient tetra pack formats dominate refrigerated dairy alternative aisles, with Thai and Indonesian exporters prioritizing FDA-compliant labeling for US retail placement.
- Health Food Stores:Cold-pressed variants in glass bottles command premium positioning through organic certification and single-origin sourcing claims.
- Online Retail:Direct-to-consumer subscription models favor shelf-stable pouches and tetra packs with extended durability for cross-border shipping through the Strait of Malacca logistics corridor.
- Convenience Stores:Single-serve cans and small-format bottles address immediate-consumption demand in Philippine and Indonesian urban centers.
Procurement scale favors Supermarkets; margin expansion concentrates in Health Food Stores.
End User:
Application specificity determines fat-content precision requirements and contract structure complexity.
- Individuals:Home consumers prioritize unsweetened tetra packs for beverage and cooking versatility, with purchasing concentrated in North American and European urban markets.
- Restaurants:Bulk bag-in-box formats serve Southeast Asian and South Asian cuisine establishments requiring consistent curry base performance.
- Cafés:Barista-specific formulations with foaming stability specifications anchor supply relationships with specialty coffee chains in Germany, the United Kingdom, and the United States.
- Food Manufacturers:Ingredient-grade contracts lock in multi-year procurement with Thai and Indonesian processors for bakery and confectionery applications.
Contract value peaks with Food Manufacturers; volume acceleration tracks Cafés.
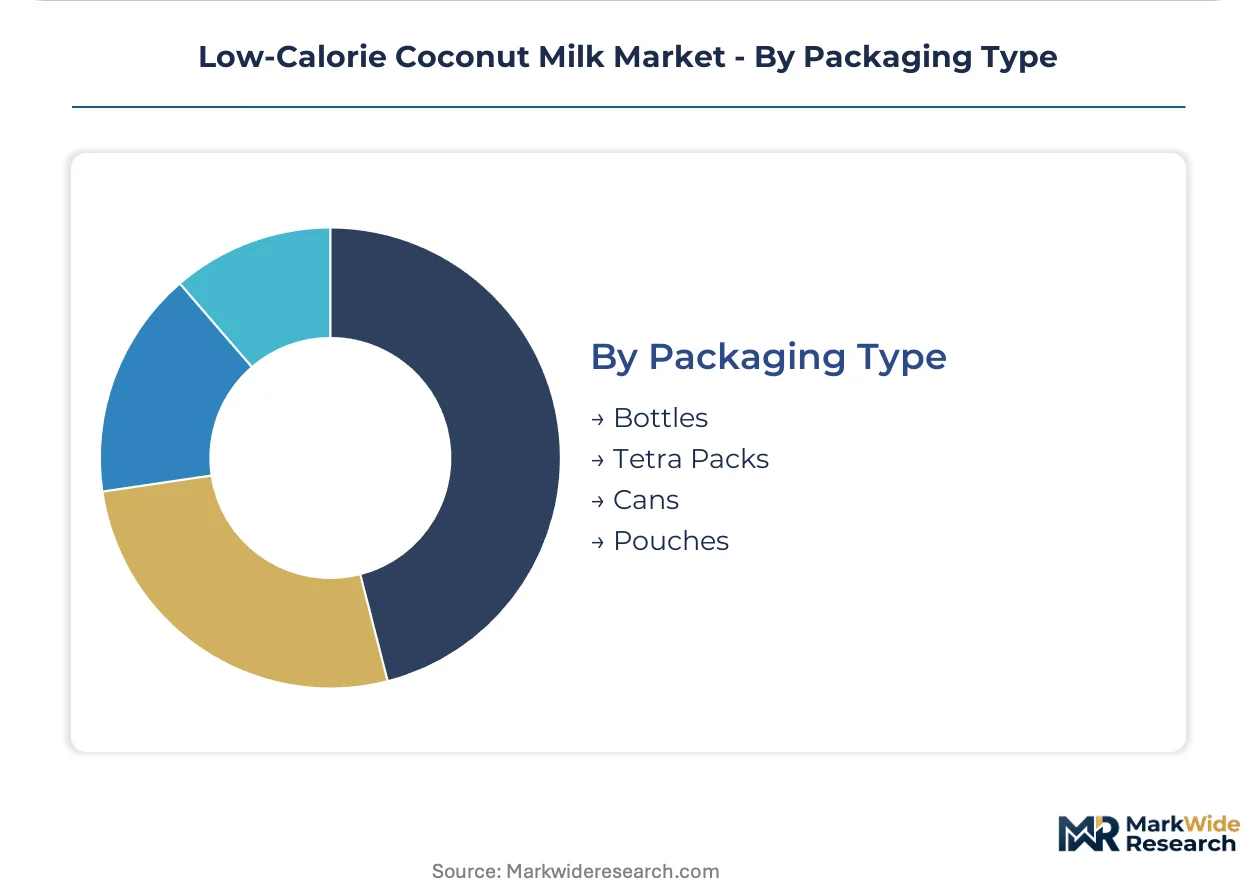
Packaging Type:
Format choice shapes logistics economics, shelf-life extension, and channel accessibility.
- Tetra Packs:Aseptic carton technology enables 12-month ambient stability, unlocking e-commerce distribution and reducing cold-chain dependency for Southeast Asian exporters.
- Bottles:Refrigerated PET and glass containers dominate North American retail dairy alternative aisles with shorter shelf-life requirements.
- Cans:Metal packaging suits food service bulk procurement and traditional markets in the Philippines and Indonesia with established recycling infrastructure.
- Pouches:Flexible format reduces shipping weight for direct-to-consumer channels, gaining traction in Indian and Australian online retail.
Installed base favors Bottles; expansion velocity belongs to Tetra Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangkok anchors the global low-calorie coconut milk trade through its concentration of integrated plantation-to-package operations and cold-pressing facilities in Thailand's central plains processing corridor.
United States
Specialty coffee chains in Seattle, Portland, and San Francisco now specify low-calorie coconut milk as standard dairy alternatives, creating institutional procurement volumes. FDA nutrition labeling rules recalibrate fat-content descriptors for import batches. California's refrigerated distribution networks dominate North American retail channel placement for barista-specific formulations.
Germany
EFSA additive restrictions under REACH compliance protocols drive reformulation investments for European market entry. Berlin and Hamburg-based food manufacturers pivot toward clean-label coconut milk for bakery and confectionery applications. The country's central European logistics position enables redistribution into Nordic markets seeking reduced tropical commodity exposure.
Thailand
Integrated processors in the central plains leverage captive plantation supply to achieve cost advantages in cold-pressed sub-3% fat production. The Ministry of Agriculture enforces Good Agricultural Practice standards constraining raw material scalability. Samut Sakhon and Nakhon Pathom industrial clusters concentrate centrifugal separation capacity expansion.
Indonesia
Smallholder plantations in Sulawesi and Sumatra supply over 35% of global coconut raw material, exposing processors to climate volatility. The Strait of Malacca corridor logistics bottleneck affects export timing to European and North American destinations. Surabaya processing hubs adopt microfiltration ceramic membrane arrays for real-time quality control.
India
Unsweetened low-calorie variants align with FSSAI-compliant sugar reduction campaigns targeting urban metabolic health segments in Mumbai and Bangalore. Tetra pack formats gain traction through direct-to-consumer e-commerce channels. Kerala and Tamil Nadu coastal belts maintain traditional extraction methods alongside modern centrifugal adoption.
Low-Calorie Coconut Milk Market Competitive Landscape
Premium-margin players sit above commodity-margin players across cold-pressing technology adoption and single-origin sourcing certification. The vendor base stratifies into three tiers: integrated plantation operators with captive supply, refrigerated distribution specialists with North American retail dominance, and ingredient-grade contract manufacturers serving food processors. Two dominant competitive moves define current positioning: backward integration into plantation assets to secure raw material certainty, and geographic expansion through ambient tetra pack formats to unlock e-commerce channels.
Within the integrated plantation tier, Thai Coconut Public Company Limited and Thai Agri Foods Public Company Limited represent the archetype of captive sourcing across Thailand's central plains. Among North American refrigerated distribution specialists, Silk occupies a position exemplifying channel dominance through retail dairy alternative aisle placement. At the single-origin sourcing and sports marketing vector, Vita Coco anchors premium positioning through verified deforestation-free supply claims. These three company structures illustrate how geographic origin, distribution control, and certification investment separate margin tiers.
| Leading Market Players |
|---|
| Thai Coconut Public Company Limited |
| Silk (Whitewave) |
| GraceKennedy Limited |
| AroyD |
| Thai Agri Foods Public Company Limited |
| So Delicious Dairy Free |
| Pacific Foods |
| Goya Foods |
| Vita Coco |
| Others |
Value Network & Pricing Analysis
Specialty coffee chain procurement concentration anchors value-based pricing tiers, with institutional buyers extracting volume discounts that compress margins for mid-tier processors lacking captive coconut supply.
Pricing Analysis
Yield-per-hectare outcomes at plantation level anchor value-based pricing for cold-pressed sub-3% fat variants. Premium-mid-economy pricing differentiation separates single-origin certified SKUs from commodity heat-processed lines based on fat-content precision and deforestation-free verification. Cost compression in standard-grade tetra packs is intensifying because Indonesian and Thai processors compete for identical export contracts. Food manufacturers represent the least price-sensitive segment due to multi-year procurement lock-ins, while convenience store distributors exhibit highest sensitivity to per-unit fluctuations.
Supply Chain Analysis
Skilled centrifugal separation technicians remain scarce across Samut Sakhon and Surabaya processing clusters, constraining capacity expansion for precision fat-content production. Raw material supply concentrates in Indonesia, Thailand, and the Philippines, with Sulawesi and Sumatra smallholders feeding over one-third of global coconut extract volume. Downstream distribution runs through refrigerated North American retail networks for barista-grade formulations, while ambient tetra pack channels bypass cold-chain dependency for Southeast Asian exporters. Strait of Malacca logistics chokepoints expose shipment timing to port congestion volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into plantation assets has become the defining competitive race, with processors securing upstream control to insulate margin structures from raw material price swings.
For Market Incumbents: Lock in multi-year supply contracts with Indonesian and Thai smallholder cooperatives before EFSA clean-label mandates accelerate processor consolidation. Expand centrifugal separation capacity in Thailand's central plains to capture specialty coffee chain specification shifts. Defensive patent filings around microfiltration ceramic membrane arrays will raise rival capital requirements. For New Entrants and Emerging Players: FSSAI sugar reduction guidelines in India open a window for unsweetened tetra pack distribution through Mumbai and Bangalore direct-to-consumer channels. Target white-space in Australian and Middle Eastern e-commerce subscription models where ambient packaging logistics remain underdeveloped. Pursue carbon footprint certification under EU Green Deal protocols to command premium positioning in German redistribution markets. For Investors and Strategic Acquirers: The window for entry favors integrated plantation-to-package operators with verified deforestation-free sourcing and existing FDA compliance documentation. Acquisition targets should demonstrate captive raw material access exceeding fifty percent of processing capacity. Watch for inflection where REACH-compliant reformulation costs trigger mid-tier processor distress sales.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive coconut supply from Thai central plains processors eliminates Strait of Malacca exposure. |
| Cold-Pressing Capacity Expansion | Centrifugal separation facilities in Samut Sakhon achieve sub-3% fat precision for coffee chain specifications. |
| Carbon Footprint Certification | EU Green Deal verification unlocks premium shelf placement in Berlin and Hamburg retail channels. |
| Tetra Pack Format Transition | Ambient stability enables e-commerce distribution bypassing refrigerated North American logistics. |
| Barista-Specific Formulation Development | Foaming stability specifications anchor supply relationships with Seattle and Portland specialty coffee networks. |
Research Methodology
Multi-period observation of coconut plantation yield cycles, EFSA additive restriction timelines, and specialty coffee chain procurement patterns anchored the trend analysis, supplemented by interviews with Thai and Indonesian processing facility managers, North American retail category buyers, German food manufacturer procurement leads, and FDA regulatory affairs specialists. Secondary validation drew from customs export records, FDA nutrition labeling guidance documents, EU Nutrition and Health Claims Regulation assessments, and Thai Ministry of Agriculture Good Agricultural Practice standards. Bottom-up processor capacity estimates triangulated against top-down channel shipment volumes.
Segment-weighting across product type, distribution channel, end user, and packaging format dimensions shaped the analytical framework throughout the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating ketogenic diet penetration rates, coffee chain outlet expansion, and tetra pack adoption velocity. Industry-specific inputs included centrifugal separation technology diffusion curves and FSSAI sugar reduction campaign implementation timelines.
Caveats apply where climate volatility in Indonesian smallholder regions, FDA fat-content descriptor recalibrations, or oat milk substitution acceleration in Nordic markets could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Milk Alternatives Market
Dairy Alternatives
Walnut Milk Market
Dairy Alternatives
South Korea Dairy Alternatives Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
Dairy-Free Evaporated Milk Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Australia Dairy Alternatives Market
Dairy Alternatives
Lactose-Free Milk Market
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
North America Non-Dairy Yogurt Market