
 US Ambulatory Cardiac Monitoring Devices Market | 2026-2036
US Ambulatory Cardiac Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Ambulatory Cardiac Monitoring Devices Market Analytics
The US ambulatory cardiac monitoring devices market is repositioning around a sharp split between premium implantable loop recorders and commodity Holter monitors. Abbott leverages its vertical integration across cardiac rhythm management to sustain leadership in implantable diagnostics. iRhythm Technologies specializes in cloud-based algorithm interpretation, while Medtronic anchors hospital channel dominance through its established cardiac device sales infrastructure.
US ambulatory cardiac monitoring devices are portable or implantable electrophysiological recording systems that capture cardiac electrical activity over extended durations—typically 24 hours to several years—using electrodes, wireless transmitters, and cloud-connected analytics platforms to detect arrhythmias outside clinical settings. Mobile cardiac telemetry and implantable loop recorders command the strongest margin pools due to their real-time transmission capabilities and long-term surveillance value. Bluetooth-enabled monitors and wearable patch technologies are expanding fastest among device type and technology segments, driven by patient preference for unobtrusive form factors and seamless smartphone integration.
FDA 510(k) clearance requirements and HIPAA data security standards shape product development timelines and channel economics for manufacturers seeking US market access. The Centers for Medicare & Medicaid Services reimbursement policies for remote cardiac monitoring directly determine adoption velocity across cardiology clinics and home care settings. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled arrhythmia detection algorithms and CMS decisions on expanded remote physiologic monitoring billing codes.
Market Dynamics
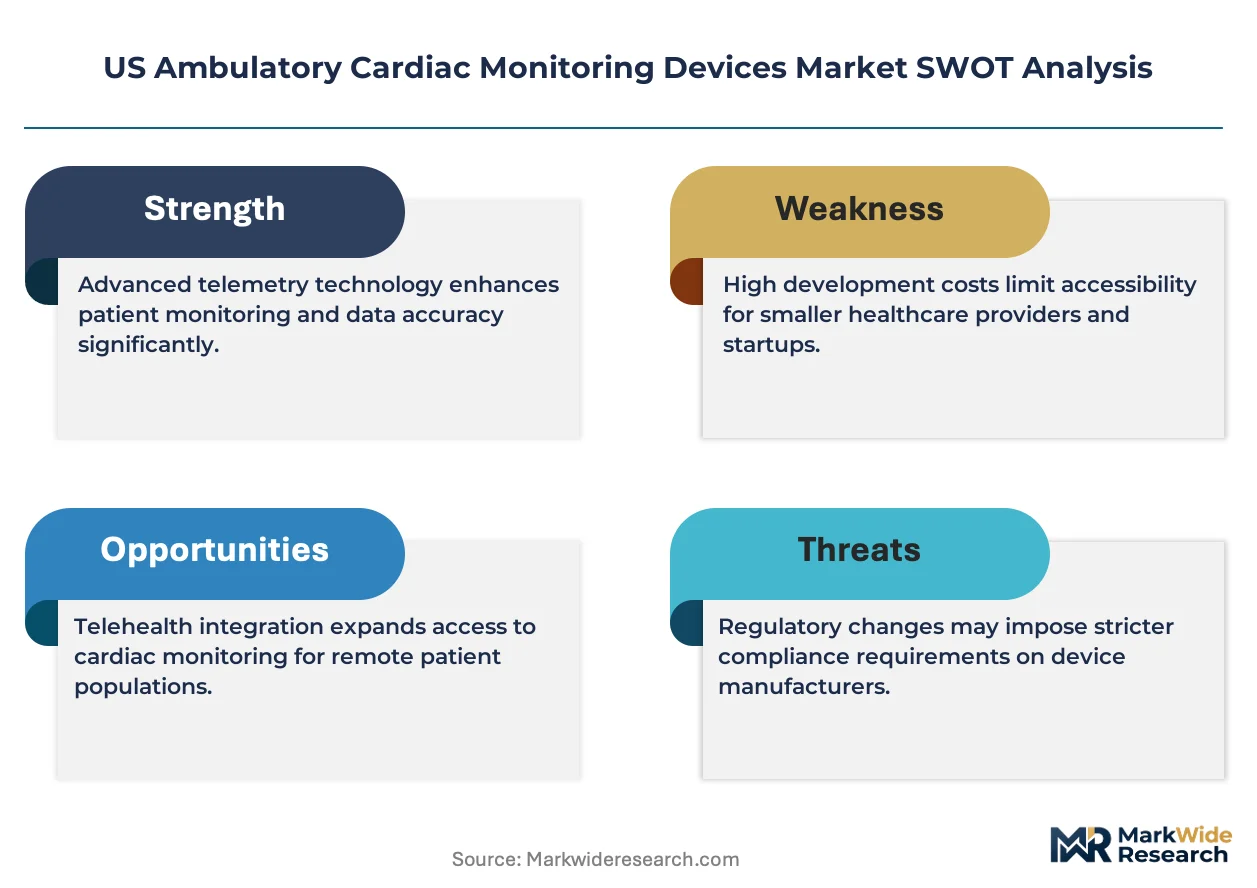
Reimbursement policy divergence between CMS coverage decisions and private payer prior authorization requirements is fragmenting channel economics for ambulatory cardiac monitoring manufacturers. This structural tension compresses margins for mid-tier patch-based monitors while expanding margin pools for real-time telemetry systems that satisfy both billing code requirements.
Growth Catalysts
- CMS Remote Physiologic Monitoring (RPM) Billing Codes:Expanded reimbursement for CPT codes 99453-99458 accelerates adoption of Bluetooth-enabled monitors in cardiology clinic networks across Texas and Florida.
- Hospital Outpatient Department Expansion:Post-operative cardiac surveillance programs are scaling mobile cardiac telemetry deployment to reduce 30-day readmission penalties.
- AI-Enabled Arrhythmia Detection:Cloud-based algorithm interpretation platforms receive favorable FDA 510(k) pathway treatment, shortening time-to-market for algorithm-integrated patch devices.
Market Restraints
- HIPAA Data Security Compliance Costs:Encryption infrastructure and audit requirements impose fixed cost burdens that disproportionately constrain smaller patch-monitor entrants.
- Implantable Loop Recorder Supply Concentration:Three manufacturers control cardiac rhythm management device supply, creating procurement bottlenecks for hospital systems seeking dual-source strategies.
- Holter Monitor Commoditization:24-48 hour ambulatory ECG recording faces displacement pressure from extended-wear patch technologies with superior patient compliance profiles.
Strategic Opportunities
- Rural Health Clinic Penetration:Federally Qualified Health Centers in Mississippi, Alabama, and Arkansas remain underserved for diagnostic cardiology services, creating whitespace for mobile telemetry service models.
- Artificial Intelligence-Enabled Detection Algorithms:FDA guidance on Software as a Medical Device creates regulatory tailwind for cloud-native arrhythmia classification platforms that reduce cardiologist interpretation burden.
- Smartphone Integration Convergence:Bluetooth Low Energy pairing with iOS and Android native health applications is compressing patient onboarding friction and expanding direct-to-consumer channel viability.
Industry Challenges
- Electrophysiologist Interpretation Bottleneck:Cloud algorithm outputs still require physician over-read for billing compliance, constraining scalable service model economics.
- Legacy EHR Integration Complexity:Patchwork HL7 FHIR connectivity standards force custom API development for each health system deployment, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Ambulatory Cardiac Monitoring Devices Market |
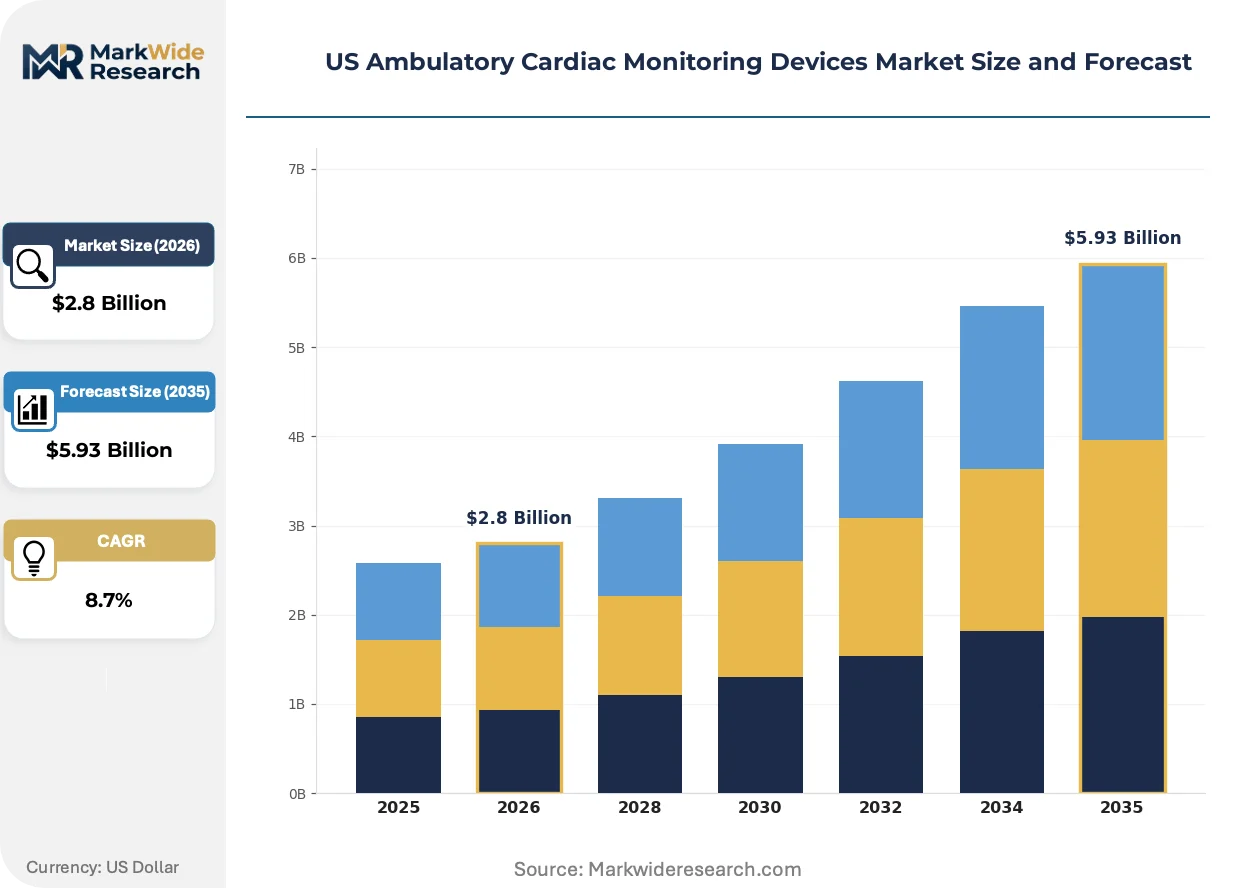
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Holter Monitors, Event Monitors, Mobile Cardiac Telemetry, Implantable Loop Recorders Technology: Wireless, Bluetooth, Cloud-Based, Wearable End User: Cardiology Clinics, Hospitals, Home Care, Remote Patient Monitoring Application: Arrhythmia Detection, Atrial Fibrillation Monitoring, Post-Operative Monitoring, Long-Term Surveillance |
| Companies Covered | Abbott, Medtronic, Boston Scientific Corporation, GE HealthCare, Koninklijke Philips N.V., iRhythm Technologies, BioTelemetry, Schiller AG, ZOLL Medical Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Ambulatory Cardiac Monitoring Devices Market Evolving Landscape
Device architecture is fragmenting into disposable sensor layers, reusable transmitter cores, and cloud analytics subscriptions. This decomposition is reshaping competitive boundaries between hardware manufacturers, software platforms, and cardiac service providers.
Wearable ECG patch technology is modularizing into standardized electrode-agnostic platforms that accommodate multiple sensor configurations. Cardiology clinic networks in California and Texas are adopting these flexible form factors to serve diverse patient anatomies and monitoring durations. The technology is modularizing procurement decisions, allowing buyers to separate sensor subscription costs from analytics platform licensing.
FDA 510(k) premarket notification pathways for wearable ECG devices are streamlining through the De Novo classification route for novel algorithm-enabled products. This regulatory evolution compresses time-to-market for artificial intelligence-integrated monitors while raising evidentiary requirements for training dataset diversity. Patch-based monitor manufacturers with established quality management systems are capturing first-mover advantage in this pathway.
Cardiology procurement committees are unbundling device acquisition from interpretation service contracts, forcing manufacturers to compete on hardware margins alone. Hospital outpatient departments in Florida are leading this disintermediation, sourcing monitors through group purchasing organizations while contracting interpretation services to independent diagnostic testing facilities. The shift is most visible in Medicare Advantage plan networks where capitated payment structures reward cost separation.
US Ambulatory Cardiac Monitoring Devices Market Segmentation
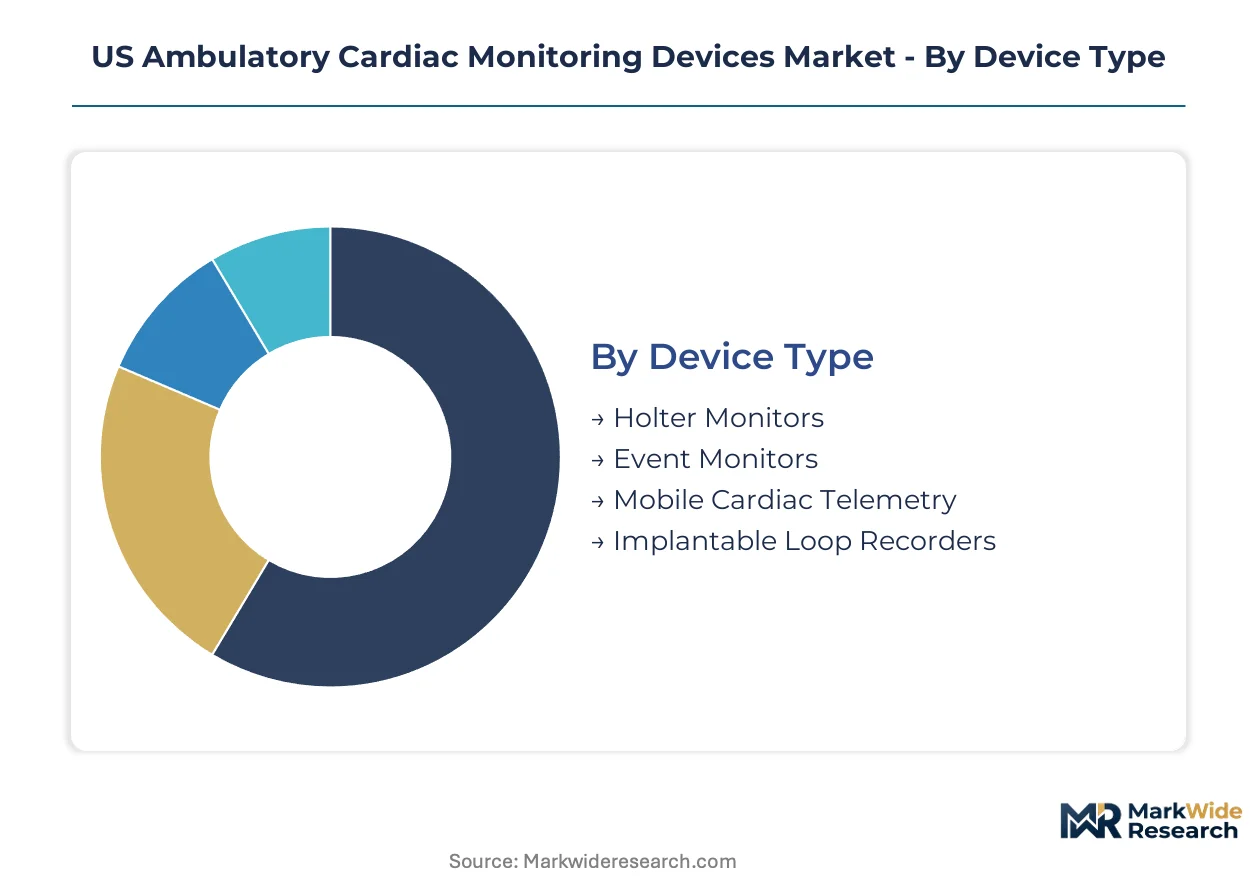
US ambulatory cardiac monitoring devices fragment across four intersecting dimensions that reshape procurement economics. Device type and technology choices determine reimbursement eligibility, while end-user channel and application use-case dictate service model viability for manufacturers.
Device Type:
Hospital procurement committees weigh upfront capital against per-procedure reimbursement when selecting device categories.
- Mobile Cardiac Telemetry:Real-time transmission systems pair cellular modems with cloud analytics platforms for continuous arrhythmia surveillance. Texas and Florida cardiology clinic networks deploy these systems to capture extended monitoring revenue under expanded CMS billing codes.
- Implantable Loop Recorders:Subcutaneous devices with multi-year battery life provide diagnostic value for cryptogenic stroke and infrequent symptom correlation. Three manufacturers dominate hospital system procurement, creating supply concentration risk for dual-source strategies.
- Holter Monitors:24-48 hour tape-based or digital recorders face displacement pressure from patch alternatives with superior patient compliance profiles.
- Event Monitors:Patient-activated or auto-triggered devices capture symptomatic episodes without continuous transmission infrastructure.
Volume sits with Holter Monitors; growth tilts toward Mobile Cardiac Telemetry.
Technology:
Connectivity architecture determines integration complexity with existing health system infrastructure.
- Bluetooth:Low-energy pairing with iOS and Android native health applications compresses patient onboarding friction and expands direct-to-consumer channel viability in California cardiology markets.
- Cloud-Based:Algorithm interpretation platforms receive favorable FDA 510(k) pathway treatment, shortening time-to-market for integrated diagnostic services.
- Wireless:Cellular or Wi-Fi transmission enables real-time alert generation for critical arrhythmia detection without patient smartphone dependency.
- Wearable:Skin-adhesive patch form factors with standardized electrode-agnostic platforms accommodate diverse patient anatomies and monitoring durations.
Wireless dominates current installed base; Bluetooth-enabled configurations are expanding most quickly.
End User:
Channel selection shapes margin structure through reimbursement pathway and service bundling economics.
- Cardiology Clinics:Independent and hospital-affiliated practices in Texas, Florida, and California drive patch-based monitor adoption through group purchasing organization contracts.
- Hospitals:Outpatient departments scale post-operative cardiac surveillance programs to reduce CMS 30-day readmission penalties.
- Home Care:Medicare Advantage capitated payment structures reward cost separation between device acquisition and interpretation services.
- Remote Patient Monitoring:Federally Qualified Health Centers in Mississippi, Alabama, and Arkansas remain underserved for diagnostic cardiology services.
Cardiology Clinics generate highest procedure volume; Remote Patient Monitoring offers steepest expansion trajectory.
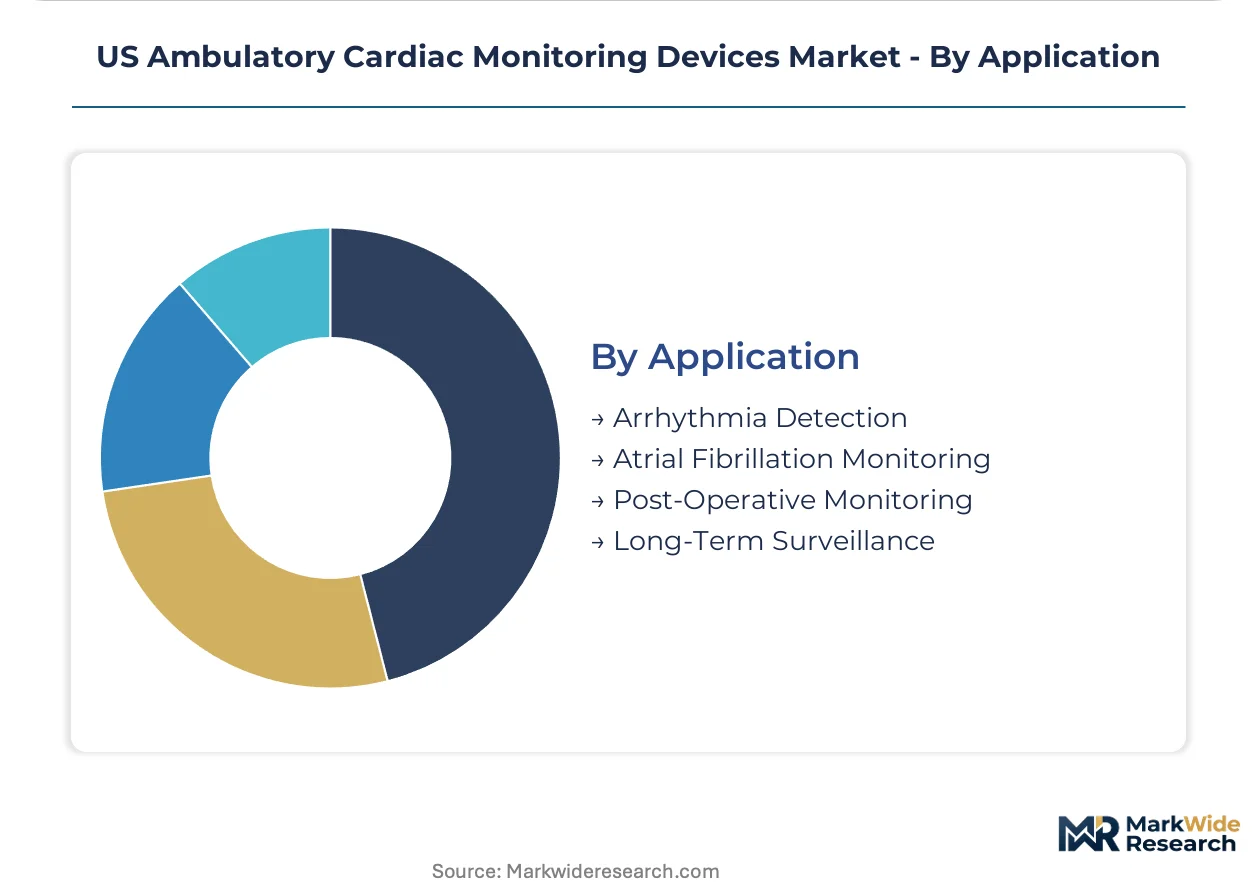
Application:
Clinical indication determines monitoring duration requirements and algorithm sensitivity specifications.
- Atrial Fibrillation Monitoring:Extended surveillance with high-burden detection algorithms supports stroke risk stratification and anticoagulation therapy decisions.
- Arrhythmia Detection:Broad symptom-to-rhythm correlation drives demand across all device categories with variable specificity requirements.
- Post-Operative Monitoring:Hospital outpatient departments deploy mobile telemetry for cardiac surgery and structural intervention surveillance.
- Long-Term Surveillance:Cryptogenic stroke and infrequent palpitation evaluation favor implantable solutions with multi-year monitoring horizons.
Arrhythmia Detection anchors procedure volume; Atrial Fibrillation Monitoring commands premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors cardiac device distribution networks serving Texas cardiology clinic networks deploying mobile cardiac telemetry systems under expanded CMS reimbursement codes.
Texas
Houston Methodist and Baylor Scott & White health systems drive implantable loop recorder procurement for post-operative cardiac surveillance programs. FDA 510(k) clearance pathways for wearable ECG devices accelerate market entry for Bluetooth-enabled monitors through Austin's medical device corridor. San Antonio's military health networks are piloting remote patient monitoring for veteran cardiac rehabilitation services.
Florida
Medicare Advantage penetration in Miami-Dade and Broward counties creates capitated payment structures that reward cost separation between device acquisition and interpretation services. CMS Remote Physiologic Monitoring billing codes 99453-99458 accelerate adoption of patch-based monitors through Tampa Bay cardiology networks. Jacksonville hospital outpatient departments are scaling mobile cardiac telemetry to reduce 30-day readmission penalties.
California
Stanford Health Care and Cedars-Sinai anchor demand for AI-enabled arrhythmia detection platforms with cloud-based algorithm interpretation. HIPAA data security compliance costs for encryption infrastructure shape procurement decisions among Los Angeles cardiology clinic networks. San Francisco Bay Area digital health startups are converging smartphone integration with Bluetooth Low Energy pairing for direct-to-consumer channel development.
New York Metro
Mount Sinai and NYU Langone health systems concentrate procurement of premium implantable diagnostics for cryptogenic stroke evaluation. New York State's telehealth parity laws support reimbursement for remote cardiac monitoring services across Hudson Valley cardiology practices. Buffalo and Rochester Federally Qualified Health Centers remain underserved for diagnostic cardiology, creating whitespace for mobile telemetry service models.
Illinois/Michigan/Ohio
Chicago's Northwestern Medicine and Cleveland Clinic anchor Midwest demand for hospital outpatient department cardiac surveillance programs. Michigan's Blue Cross Blue Shield prior authorization requirements fragment channel economics for mid-tier patch-based monitors. Ohio's rural health clinics in Appalachian counties are deploying event monitors for infrequent palpitation evaluation with limited electrophysiologist access.
US Ambulatory Cardiac Monitoring Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology-integration spectrum, with real-time telemetry systems commanding superior economics against 24-48 hour Holter alternatives. Three manufacturers control cardiac rhythm management device supply for implantable loop recorders, creating procurement concentration risk for hospital systems seeking dual-source strategies. Strategic archetypes include vertically integrated cardiac rhythm management specialists, cloud-native algorithm interpretation platforms, and hardware-agnostic service providers. Competitive moves center on unbundling device acquisition from interpretation service contracts and FDA De Novo pathway navigation for AI-enabled products.
Among US-based cardiac device manufacturers, Abbott and Medtronic occupy positions anchoring hospital channel dominance through established cardiac device sales infrastructure. iRhythm Technologies exemplifies the cloud-native archetype, specializing in algorithm interpretation platforms that reduce cardiologist interpretation burden. These three companies represent the dominant competitive anchors across premium-margin implantable diagnostics and service-based patch monitoring segments.
| Leading Market Players |
|---|
| Abbott |
| Medtronic |
| Boston Scientific Corporation |
| GE HealthCare |
| Koninklijke Philips N.V. |
| iRhythm Technologies |
| BioTelemetry |
| Schiller AG |
| ZOLL Medical Corporation |
| Others |
Value Network & Pricing Analysis
Backward integration into cardiac rhythm management device manufacturing anchors Abbott and Medtronic's supply position while reinforcing premium pricing power for implantable loop recorders. This captive production model insulates these manufacturers from component volatility and supports value-based contracting with hospital systems.
Pricing Analysis
Reimbursement-linked pricing anchors the US ambulatory cardiac monitoring market, with CMS Remote Physiologic Monitoring billing codes determining commercial viability across device tiers. Pricing stratifies across premium implantable diagnostics, standard mobile cardiac telemetry systems, and economy Holter monitor alternatives, with FDA 510(k) clearance tier and real-time transmission capability as primary differentiation drivers. Cost compression in patch-based monitoring intensifies as cardiology clinic networks unbundle hardware from interpretation services. Medicare Advantage plans exhibit highest price sensitivity due to capitated payment structures, while hospital outpatient departments prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for implantable loop recorders face structural constraints as three manufacturers control cardiac rhythm management device supply, creating procurement bottlenecks for hospital systems seeking supply redundancy. Component sourcing draws from Taiwan for semiconductor substrates, Mexico for final device assembly, and domestic US facilities for sterile packaging. Single-source vulnerability concentrates in lithium-ion battery cells and specialized biocompatible polymers. Distribution runs through group purchasing organizations for cardiology clinic networks and direct hospital system contracts for implantable diagnostics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US ambulatory cardiac monitoring devices are consolidating around manufacturers with integrated algorithm platforms and established FDA quality management systems, forcing capital-constrained patch-monitor entrants toward acquisition or exit.
For Market Incumbents: Deploy cloud-native algorithm interpretation capabilities to defend service revenue as cardiology clinic networks unbundle hardware procurement from interpretation contracts. Acquire FDA-cleared patch-monitor platforms to fill portfolio gaps in Bluetooth-enabled extended-wear segments. Reinforce hospital channel dominance through integrated cardiac rhythm management device sales infrastructure before emerging AI-native entrants secure De Novo pathway clearances. For New Entrants and Emerging Players: Enter via Federally Qualified Health Center partnerships in Mississippi, Alabama, and Arkansas where diagnostic cardiology service gaps persist and electrophysiologist access constraints create whitespace for mobile telemetry service models. Target rural health clinic penetration with algorithm-integrated patch devices that reduce specialist interpretation burden. Pursue direct-to-consumer channel development through smartphone-native health application integration in California's digital health corridor. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by vertically integrated cardiac rhythm management specialists seeking algorithm platform capabilities. Long-term viability favors manufacturers with established FDA quality management systems and CMS reimbursement code alignment over hardware-only entrants. Watch FDA De Novo classification decisions for AI-enabled arrhythmia detection as inflection indicator for algorithm-native platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Pathway Navigation | Accelerates market entry for AI-integrated patch monitors through novel algorithm classification. |
| Hospital System Partnership | Secures preferred vendor status for post-operative cardiac surveillance program expansion. |
| Software Companion Development | Enables seamless HL7 FHIR connectivity with Epic and Cerner EHR deployments. |
| Reimbursement Strategy | Aligns CPT code 99453-99458 billing requirements with device transmission capabilities. |
| Geographic Expansion | Captures Medicare Advantage penetration in Florida's capitated payment markets. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, CMS Medicare reimbursement coding decisions, and hospital procurement contract filings, complemented by interviews with cardiology practice administrators, biomedical engineering directors, group purchasing organization contract managers, and electrophysiologists. Secondary validation drew from CMS Medicare claims data, hospital outpatient department quality metrics, and GPO contract disclosure databases. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Segmented projections for device type, technology architecture, end-user channel, and clinical application produced volume and value trajectories calibrated to CMS reimbursement policy evolution and FDA regulatory pathway timing. CAGRs derived from fitted growth curves incorporating historical procedure volume elasticities to reimbursement expansion events. Forecast inputs included cardiology clinic network expansion rates, AI-enabled algorithm 510(k) clearance velocity, and Medicare Advantage plan penetration by metropolitan statistical area.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CMS billing code restriction or FDA algorithm training dataset diversity requirements. Model assumptions reflect documented reimbursement policies, regulatory guidance, and hospital procurement patterns. A model refresh is warranted upon material change in CMS Remote Physiologic Monitoring coding decisions or FDA Software as a Medical Device guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Hypertension Management Devices Market
Cardiovascular Devices
Hemodynamic Monitoring Devices Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Arterial Cannula Market
Cardiovascular Devices
Neuroendovascular Coil Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Surgical Heart Valves Market
Cardiovascular Devices
Global Vascular Embolization Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market