
 India Coronary Stent Market | 2026-2036
India Coronary Stent Market Size, Share, and Industry Trends Forecast 2026-2036
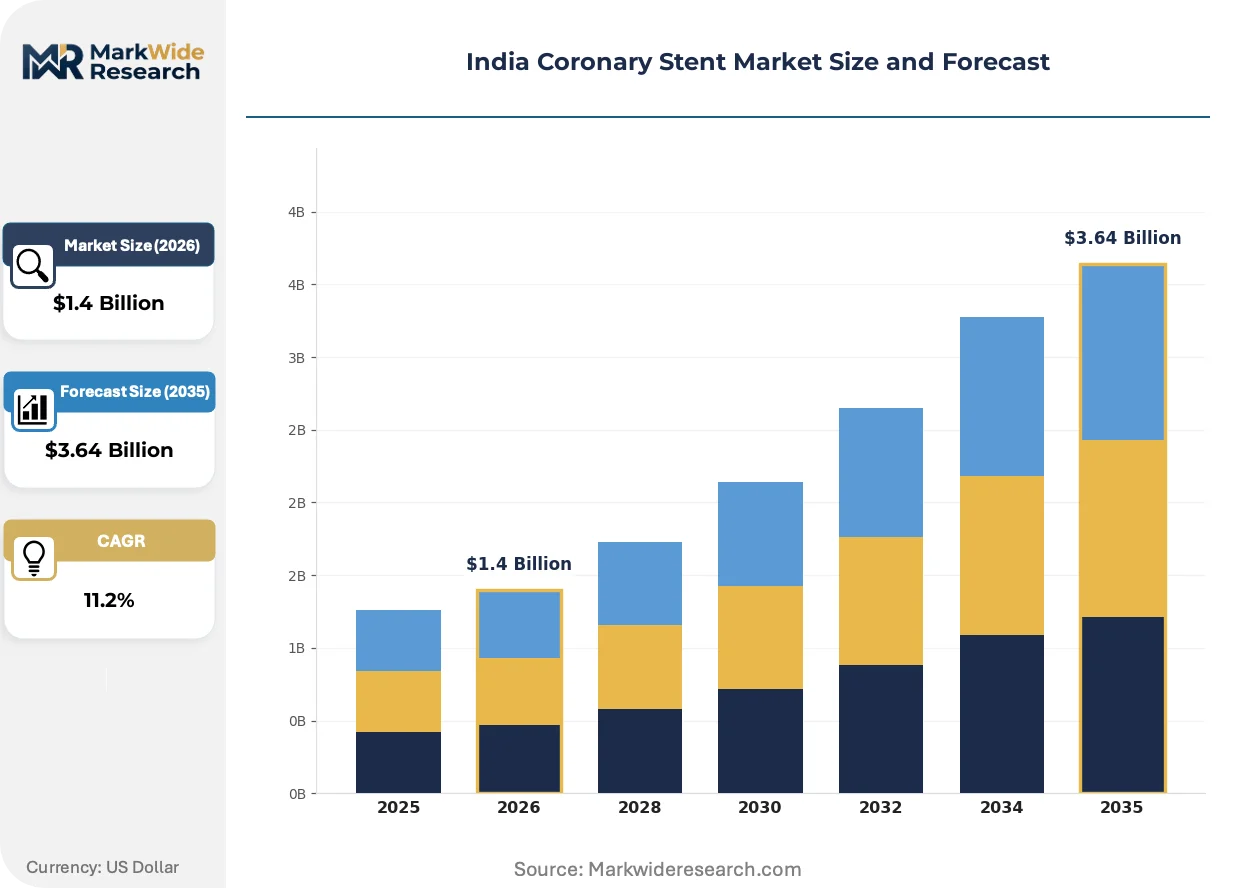
India Coronary Stent Market Outlook
Stent servicing and post-implant monitoring is restructuring how manufacturers capture lifetime value in India. Meril Life Sciences leverages domestic manufacturing scale to anchor pricing power across state-level tenders. Abbott Laboratories sustains technology leadership through polymer coating innovations. Sahajanand Medical Technologies competes on nitinol alloy specialization for complex lesions.
A coronary stent is a tubular mesh device, typically laser-cut from cobalt-chromium or platinum-chromium alloys and often coated with sirolimus or everolimus-eluting polymers, designed to scaffold narrowed coronary arteries and restore myocardial perfusion after percutaneous coronary intervention. Drug-eluting stents command the dominant revenue share due to superior restenosis outcomes, while bio-absorbable stents represent the fastest-growing niche despite manufacturing complexity. Deployment through percutaneous coronary intervention generates the highest procedural volume, whereas metallic stents remain the mature baseline technology with thinning margins.
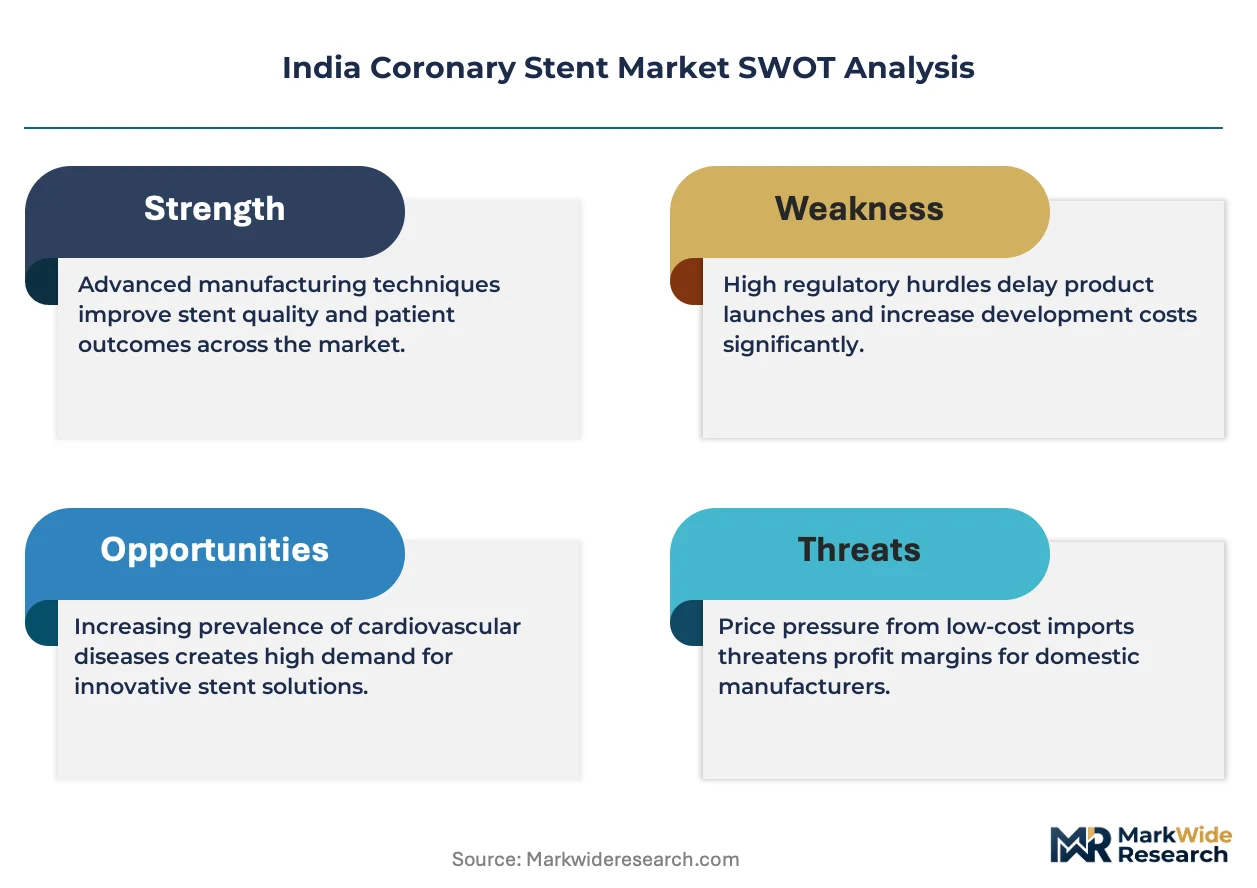
CDSCO regulates stent quality benchmarks under the Medical Device Rules, while BIS certification governs metallic alloy specifications, and the PLI scheme incentivizes domestic production capacity. These frameworks elevate compliance costs for importers while creating procurement preference for locally certified manufacturers. Stakeholders must monitor how CDSCO's evolving risk-based classification affects registration timelines and working capital cycles.
Market Dynamics
CDSCO's tightened quality benchmarks for drug-eluting stents are forcing manufacturers to restructure domestic production footprints and accelerate BIS certification timelines. Tier-2 cardiac centers under India's PLI scheme for medical devices now drive procedural volume expansion.
Growth Catalysts
- Production-Linked Incentive scheme:The PLI scheme for medical devices subsidizes capital expenditure for domestic stent manufacturing, lowering unit economics for local producers.
- Tier-2 city hospital clusters:Cardiac centers in cities like Indore, Lucknow, and Coimbatore are expanding catheterization lab capacity, creating new demand nodes beyond Mumbai and Delhi.
- Drug-eluting polymer advances:Everolimus-eluting stent coatings demonstrate superior restenosis outcomes, accelerating replacement of bare-metal stents in complex lesion cases.
Market Restraints
- CDSCO registration timelines:Risk-based classification under Medical Device Rules extends working capital cycles for importers awaiting stent approval.
- Cobalt-chromium alloy concentration:Domestic supply of laser-grade alloys depends on limited specialty metal processors, creating input cost volatility.
- Bio-absorbable scaffold manufacturing complexity:Polymer degradation control and strut thickness precision limit scalable production of absorbable stents.
Strategic Opportunities
- Kerala cardiac care networks:High per-capita cardiovascular disease prevalence and established tertiary infrastructure create concentrated demand for complex lesion stents.
- Post-implant monitoring services:Stent manufacturers can capture lifetime value through remote patient monitoring partnerships with hospital chains.
- Nitinol alloy specialization:Self-expanding stent platforms for tortuous anatomy represent underdeveloped white space in domestic portfolios.
Industry Challenges
- Interventional cardiologist training pipelines:Shortage of PCI-certified specialists in tier-2 cities constrains procedural throughput expansion.
- CDSCO-BIS dual compliance:Simultaneous medical device registration and metallic alloy certification creates documentation burden and timeline misalignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Coronary Stent Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drug-Eluting Stents, Bare-Metal Stents, Bio-Absorbable Stents, Covered Stents End User: Hospitals, Cardiac Centers, Specialty Clinics, Outpatient Surgical Centers Deployment Method: Percutaneous Coronary Intervention, Balloon Angioplasty, Surgical Procedures, Hybrid Approaches Material: Metallic Stents, Polymer Coated Stents, Biodegradable Materials, Nitinol Alloys |
| Companies Covered | Meril Life Sciences, Biotronik, Boston Scientific, Translumina Therapeutics, B. Braun Melsungen, Abbott Laboratories, Sahajanand Medical Technologies, Lepu Medical Technology, Medtronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Coronary Stent Market Strategic Shifts
Polymer coating chemistry and post-market surveillance integration are restructuring how stent manufacturers differentiate and retain pricing power. Technology convergence between device engineering and digital health monitoring is creating new value capture mechanisms.
Bioresorbable polymer coatings are unifying acute scaffolding performance with long-term vessel restoration in next-generation drug-eluting platforms. Leading cardiac centers in Maharashtra's hospital clusters are piloting these scaffolds for younger patient cohorts requiring future revascularization options. This technology is unifying structural intervention with biological healing timelines, compressing the addressable market for permanent metallic implants.
CDSCO's risk-based classification under Medical Device Rules is elevating documentation requirements for imported stents while accelerating review pathways for domestically manufactured devices. The regulatory friction is redirecting procurement preferences toward BIS-certified local producers in state-level hospital tenders. Maharashtra and Kerala's government hospital networks are now mandating domestic certification for stent suppliers.
State-level tender consolidation is compressing vendor lists and unbundling after-sales service from device pricing. Hospital purchasing committees in tier-2 cities are aggregating volume commitments to extract steeper discounts from manufacturers. This pattern is most visible in Tamil Nadu's centralized medical procurement system, where multi-hospital contracts now dominate stent acquisition decisions.
India Coronary Stent Market Segmentation
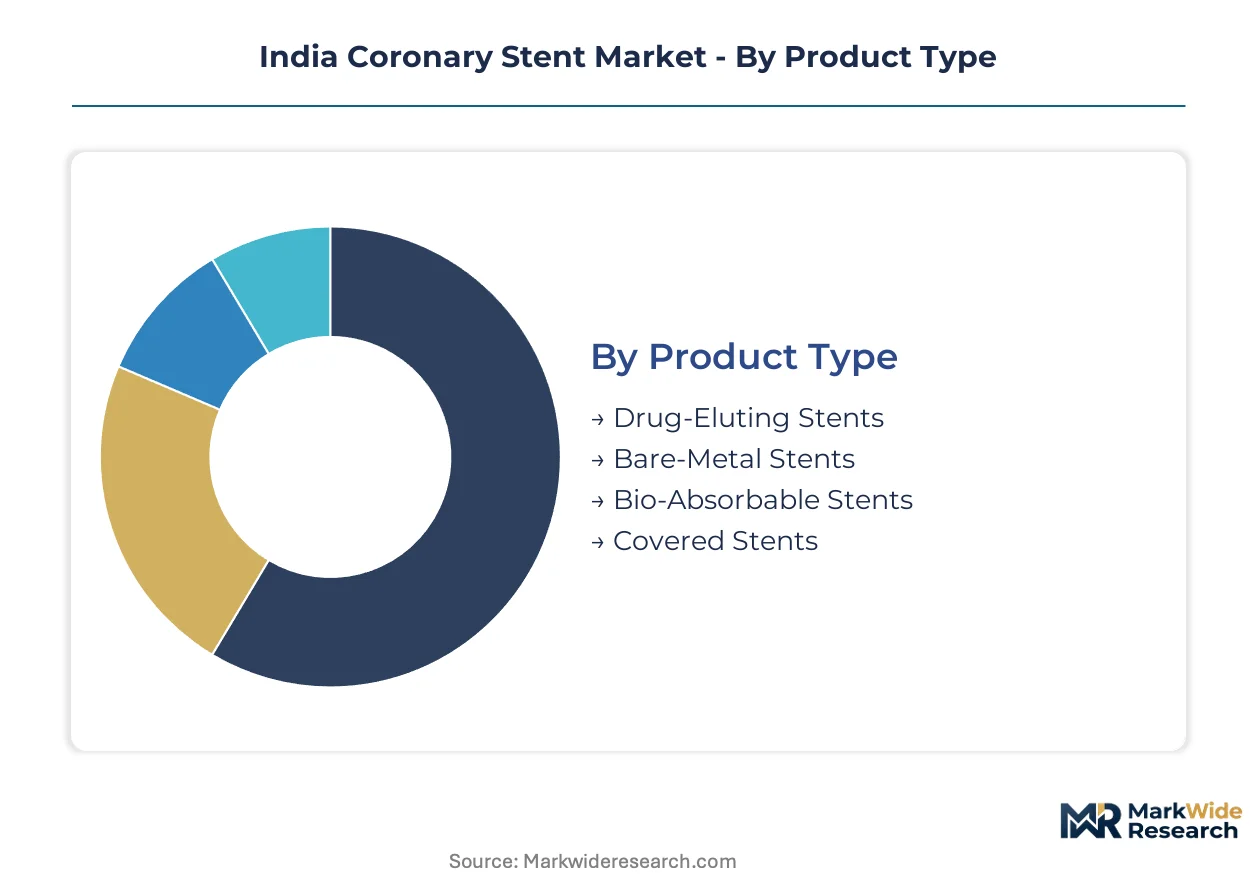
Stent manufacturers in India structure portfolios across four intersecting dimensions: polymer chemistry, deployment setting, procedural technique, and alloy composition. Each axis carries distinct margin profiles and regulatory pathways under CDSCO's risk-based classification.
Product Type:
Polymer coating technology and drug-elution kinetics define clinical outcomes and procurement premiums across Indian hospital networks.
- Drug-Eluting Stents:Laser-cut cobalt-chromium platforms carry sirolimus or everolimus coatings that suppress neointimal hyperplasia. Maharashtra's tertiary cardiac centers and Kerala's government hospital clusters concentrate demand for these devices, driven by CDSCO's tightened quality benchmarks that favor proven restenosis outcomes.
- Bare-Metal Stents:Uncoated stainless steel or cobalt-chromium scaffolds serve cost-constrained procurement in tier-2 city hospitals under Tamil Nadu's centralized tender system. These devices retain relevance where dual antiplatelet therapy compliance is unreliable.
- Bio-Absorbable Stents:Poly-L-lactic acid scaffolds degrade over 24-36 months, eliminating permanent metal burden. Polymer degradation control and strut thickness precision limit scalable domestic production.
- Covered Stents:Expanded polytetrafluoroethylene membranes seal coronary perforations and aneurysms. Niche application concentrates in high-volume intervention centers with emergency complication protocols.
Mature deployment sits with drug-eluting platforms. Newer deployment is concentrated in bio-absorbable scaffolds for younger patient cohorts requiring future revascularization flexibility.
End User:
Facility infrastructure and reimbursement economics determine stent selection protocols across India's fragmented care delivery system.
- Hospitals:Multi-specialty institutions with catheterization lab capacity perform the majority of complex multi-vessel interventions. State-level tender consolidation in Maharashtra and Kerala compresses vendor lists and unbundles after-sales service from device pricing.
- Cardiac Centers:Dedicated intervention facilities under India's PLI scheme for medical devices drive procedural volume expansion in Indore, Lucknow, and Coimbatore.
- Specialty Clinics:Limited diagnostic infrastructure restricts these settings to stable patient referrals rather than acute intervention.
- Outpatient Surgical Centers:Ambulatory capacity for same-day discharge procedures remains underdeveloped in tier-2 cities due to PCI-certified specialist shortages.
High-acuity deployment concentrates in hospital networks. Volume expansion is accelerating fastest in tier-2 cardiac centers.
Deployment Method:
Procedural technique selection hinges on lesion complexity, calcification burden, and operator training pipelines.
- Percutaneous Coronary Intervention:Transradial or transfemoral catheter-based deployment generates the highest procedural volume across Indian cardiac care networks. CDSCO registration timelines for balloon-expandable platforms extend working capital cycles for importers.
- Balloon Angioplasty:Standalone dilation without stent placement retains role in small vessel disease and bifurcation lesions where stent thrombosis risk exceeds restenosis benefit.
- Surgical Procedures:Coronary artery bypass grafting competes for multi-vessel disease with complex PCI, particularly where diabetes and diffuse atherosclerosis complicate stent outcomes.
- Hybrid Approaches:Combined surgical and interventional strategies for left main or multi-vessel disease require coordination between cardiac surgery and intervention teams.
Standard deployment runs through PCI. Hybrid deployment is gaining traction in high-volume tertiary centers with integrated heart teams.
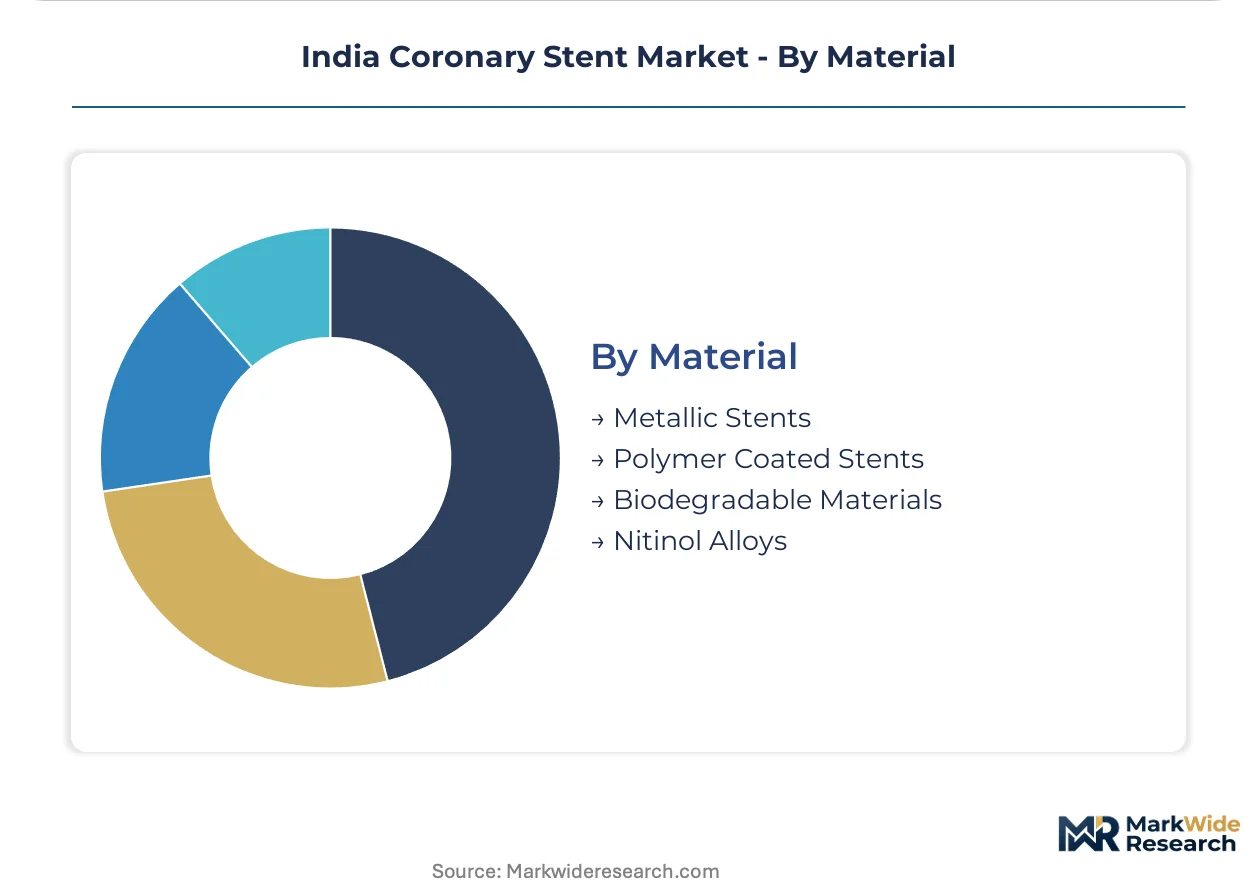
Material:
Alloy specification and surface engineering determine radial strength, deliverability, and long-term biocompatibility profiles.
- Metallic Stents:Cobalt-chromium and platinum-chromium alloys dominate laser-cut manufacturing. Domestic supply of laser-grade alloys depends on limited specialty metal processors, creating input cost volatility for BIS certification pathways.
- Polymer Coated Stents:Bioresorbable polymer coatings unify acute scaffolding with long-term vessel restoration, compressing the addressable market for permanent metallic implants in younger demographics.
- Biodegradable Materials:Polymeric scaffolds eliminate metal retention but require precise degradation control to prevent late scaffold thrombosis.
- Nitinol Alloys:Self-expanding platforms with shape-memory properties serve tortuous anatomy and calcified lesions where balloon-expandable devices fracture.
Permanent metal deployment dominates current volume. Biodegradable material deployment represents the steepest expansion trajectory as manufacturing scales domestically.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing capacity in Maharashtra and Gujarat supplies stents to consumption clusters concentrated in Kerala and Tamil Nadu. State-level procurement policies and CDSCO registration pathways determine regional competitive access.
Maharashtra
Mumbai and Pune host catheterization lab networks performing complex multi-vessel interventions. CDSCO's risk-based classification accelerates review timelines for domestically manufactured devices from local producers. State-level hospital tenders in Maharashtra's government networks now mandate BIS certification for stent suppliers.
Kerala
High per-capita cardiovascular disease prevalence drives concentrated demand for drug-eluting and bio-absorbable platforms. The state's established tertiary cardiac infrastructure attracts specialized intervention procedures from neighboring regions. Kochi and Thiruvananthapuram anchor procurement networks that aggregate volume across government and private hospital chains.
Tamil Nadu
Chennai's medical device manufacturing corridor supports laser-grade alloy processing for cobalt-chromium stent production. The state's centralized medical procurement system compresses vendor lists through multi-hospital contract aggregation. Tier-2 cities including Coimbatore expand catheterization lab capacity under India's PLI scheme for medical devices.
Karnataka
Bengaluru's hospital clusters balance domestic and imported stent sourcing based on CDSCO registration status and polymer coating specifications. The state's cardiac care networks pilot bioresorbable scaffold deployment for younger patient cohorts requiring future revascularization flexibility. Tier-2 expansion in Mysuru and Mangaluru remains constrained by PCI-certified specialist shortages.
Gujarat
Specialty metal processors in Ahmedabad and Vadodara supply laser-grade cobalt-chromium alloys for domestic stent manufacturing. BIS certification pathways for metallic alloy specifications create documentation alignment with CDSCO medical device registration. The state's production-linked incentive beneficiaries anchor pricing power across western Indian state tenders.
India Coronary Stent Market Competitive Environment
Capital-heavy domestic manufacturers compete with asset-light technology licensors and import-dependent distributors. The vendor base clusters around three archetypes: integrated alloy-to-device producers leveraging PLI subsidies, multinational technology leaders with polymer coating IP, and regional specialists in nitinol self-expanding platforms. Dominant competitive moves include backward integration into specialty alloy supply and strategic partnerships with tier-2 cardiac center expansion.
Among domestic integrated manufacturers, Meril Life Sciences and Sahajanand Medical Technologies occupy positions anchored by BIS-certified production scale and state tender participation. Abbott Laboratories exemplifies the technology-licensing archetype through polymer coating innovation portfolios. Biotronik and Boston Scientific represent import-dependent competitors navigating extended CDSCO registration timelines and risk-based classification documentation burdens.
| Leading Market Players |
|---|
| Meril Life Sciences |
| Biotronik |
| Boston Scientific |
| Translumina Therapeutics |
| B. Braun Melsungen |
| Abbott Laboratories |
| Sahajanand Medical Technologies |
| Lepu Medical Technology |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
Backward integration into laser-grade cobalt-chromium alloy supply anchors both production scale and pricing power for domestic manufacturers under India's PLI scheme. Captive control over specialty metal inputs buffers BIS-certified producers from import cost volatility while enabling aggressive tender participation across Maharashtra and Kerala government hospital networks.
Pricing Analysis
Margin tightening in government tenders reflects Tamil Nadu's centralized procurement aggregation, which extracts volume discounts through multi-hospital contracts. Three-tier pricing structure across premium drug-eluting, standard bare-metal, and economy uncoated platforms separates CDSCO-registered imports from BIS-certified domestic devices. Cost-down pressure on premium tiers accelerates because polymer coating innovations face reimbursement compression. Tier-2 cardiac centers exhibit highest price sensitivity, while Kerala's tertiary networks prioritize restenosis outcomes over unit cost.
Supply Chain Analysis
Freight costs for laser-grade cobalt-chromium alloys from Germany and Japan elevate working capital cycles for non-integrated manufacturers awaiting BIS certification. Domestic supply draws from Gujarat's specialty metal processors and Tamil Nadu's medical device corridor, with polymer coating chemicals sourced from US and European specialty chemical producers. Single-source vulnerability concentrates in everolimus-eluting polymer supply, where two global licensors dominate formulation IP. Distribution runs through state-level tender aggregators and hospital GPOs rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited domestic capacity for bio-absorbable scaffold manufacturing props pricing for metallic drug-eluting platforms, constraining volume expansion until polymer degradation control scales.
For Market Incumbents: Extend polymer coating innovation pipelines to differentiate beyond bare-metal alternatives facing tender-driven margin erosion. Anchor backward integration into nitinol alloy supply to defend against Sahajanand Medical Technologies' specialization in self-expanding platforms. Prioritize CDSCO fast-track registration for domestically manufactured devices to compress approval timelines versus import-dependent competitors.
For New Entrants and Emerging Players: Begin with Kerala's cardiac care networks, where per-capita cardiovascular disease prevalence and established tertiary infrastructure create concentrated demand for complex lesion stents. Target tier-2 city cardiac centers in Indore and Lucknow under PLI scheme expansion, where PCI-certified specialist shortages constrain incumbent throughput. Pursue remote patient monitoring partnerships as a go-to-market angle to capture lifetime value beyond device pricing.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated domestic manufacturers seeking BIS-certified production scale and state tender relationships. Long-term viability hinges on CDSCO registration asset value and PLI scheme subsidy capture duration. Watch for bio-absorbable scaffold manufacturing yield improvements as the inflection signal for metallic stent displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Investment | Accelerates CDSCO registration timelines and unlocks Maharashtra government tender participation. |
| Polymer Coating Partnership | Secures everolimus-eluting technology access from global licensors for differentiated restenosis outcomes. |
| Tier-2 Cardiac Center Alliance | Captures PLI scheme-driven procedural volume expansion in Indore, Lucknow, and Coimbatore clusters. |
| Specialty Alloy Backward Integration | Reduces cobalt-chromium input cost volatility and aligns documentation with CDSCO metallic specifications. |
| Post-Implant Monitoring Service Launch | Creates recurring revenue streams through hospital chain partnerships for stent surveillance. |
Study Parameters
Document review covered CDSCO Medical Device Rules filings, BIS certification records, and state-level tender documents from Maharashtra and Kerala, complemented by interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from PLI scheme beneficiary disclosures, hospital procurement databases, and specialty alloy trade data. Bottom-up procedure volume estimates triangulated against top-down manufacturer capacity assessments.
Segmentation outputs across polymer chemistry, deployment setting, procedural technique, and alloy composition dimensions were modeled over the projection horizon. CAGRs derived from procedure volume growth trajectories, reimbursement rate assumptions, and technology substitution curves for bio-absorbable platforms. Forecast inputs incorporated CDSCO registration pipeline timelines, PLI scheme subsidy phase-out schedules, and tier-2 catheterization lab capacity expansion plans.
Underlying measurement precision varies by segment; drug-eluting stent volume carries tighter precision than bio-absorbable scaffold projections given manufacturing yield uncertainties. Forecasts reflect assumptions on regulatory pathway efficiency and specialist training pipeline expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Mitral Valve Disease Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Transcatheter Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Cardiovascular OCT Imaging Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
Atrial Fibrillation (AF) Ablation Market
Cardiovascular Devices
Intravascular Ultrasound (IVUS) System Market
Cardiovascular Devices
Drug-Coated Balloon Catheter Market
Cardiovascular Devices
Global Intravascular Catheters Market