
 Dialysis Catheters Market | 2026-2036
Dialysis Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Dialysis Catheters Market Analysis
China is rewriting competitive dynamics in dialysis catheter manufacturing through expanded cleanroom capacity and polymer compounding investments. Medtronic leverages its integrated vascular access portfolio to sustain hospital channel dominance across North America and Western Europe. B. Braun Melsungen AG anchors European supply security through captive silicone extrusion and sterilization infrastructure in Germany.
Dialysis catheters are sterile, flexible tubes engineered from silicone, polyurethane, or biocompatible polymers with luminal diameters typically ranging from 11.5 to 14.5 French, designed to establish temporary or permanent vascular access for extracorporeal blood purification. Their primary commercial purpose centers on enabling hemodialysis, apheresis, and acute renal replacement therapy in patients with insufficient native fistula maturation or failed permanent access. Tunneled catheters command durable revenue streams due to superior infection resistance and extended dwell times in dialysis centers, while non-tunneled variants dominate emergency acute admissions where rapid cannulation takes priority over longevity. Silicone formulations lead material selection for long-term peritoneal dialysis applications given tissue compatibility, though polyurethane competes aggressively in high-flow hemodialysis segments requiring kink resistance and tensile strength.
The FDA enforces biocompatibility and sterility standards under ISO 10993 and QSR guidelines that govern material validation and manufacturing quality for chronic vascular access devices. EMA's Medical Device Regulation extends equivalent conformity requirements across Europe, while China's NMPA implements GB standards for imported catheter registration that local manufacturers must mirror for domestic market access. Stakeholders should monitor evolving reimbursement pathways for home dialysis catheters as payers recalibrate cost structures between facility-based and remote care delivery models.
Market Dynamics
FDA's strengthened biocompatibility requirements for long-term vascular access devices are compressing manufacturer margins while accelerating material transitions toward silicone and advanced polymer formulations across the dialysis catheter supply base.
Growth Catalysts
- Medicare home dialysis reimbursement:CMS payment policies for remote renal replacement therapy are expanding catheter utilization beyond traditional facility settings into patient residences.
- ISO 10993 material validation:Standardized biocompatibility testing protocols are reducing regulatory friction for silicone-based chronic access devices entering multiple jurisdictions simultaneously.
- Outpatient dialysis center expansion:Freestanding renal care facilities in the United States are scaling catheter procurement volumes as patient volumes shift from hospital-based treatment.
Market Restraints
- Medical-grade silicone supply concentration:Specialty polymer feedstock production clusters in Germany and China, creating geographic vulnerability for catheter manufacturers dependent on consistent material flows.
- EMA MDR conformity assessment timelines:Extended certification periods for Class III vascular access devices are delaying product launches across European markets by 12-18 months.
- Native arteriovenous fistula preference:Clinical guidelines prioritizing permanent surgical access over catheter-based solutions limit addressable volume for long-term tunneled devices.
Strategic Opportunities
- Peritoneal dialysis catheter underpenetration:Home-based renal replacement modalities in India and Brazil remain catheter-underserved relative to hemodialysis prevalence.
- Antimicrobial coating convergence:Integration of silver-ion and chlorhexidine technologies with silicone substrates is opening premium positioning for infection-resistant chronic access devices.
- Direct-to-dialysis-center distribution:Bypassing traditional hospital procurement hierarchies allows manufacturers to capture margin from high-volume outpatient renal networks.
Industry Challenges
- Cleanroom technician scarcity:Sterile catheter manufacturing requires specialized aseptic processing skills that outpace vocational training pipeline output in established production regions.
- Dual ISO-FDA validation complexity:Harmonizing international biocompatibility standards with QSR manufacturing requirements demands redundant testing expenditure for multi-regional product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dialysis Catheters Market |
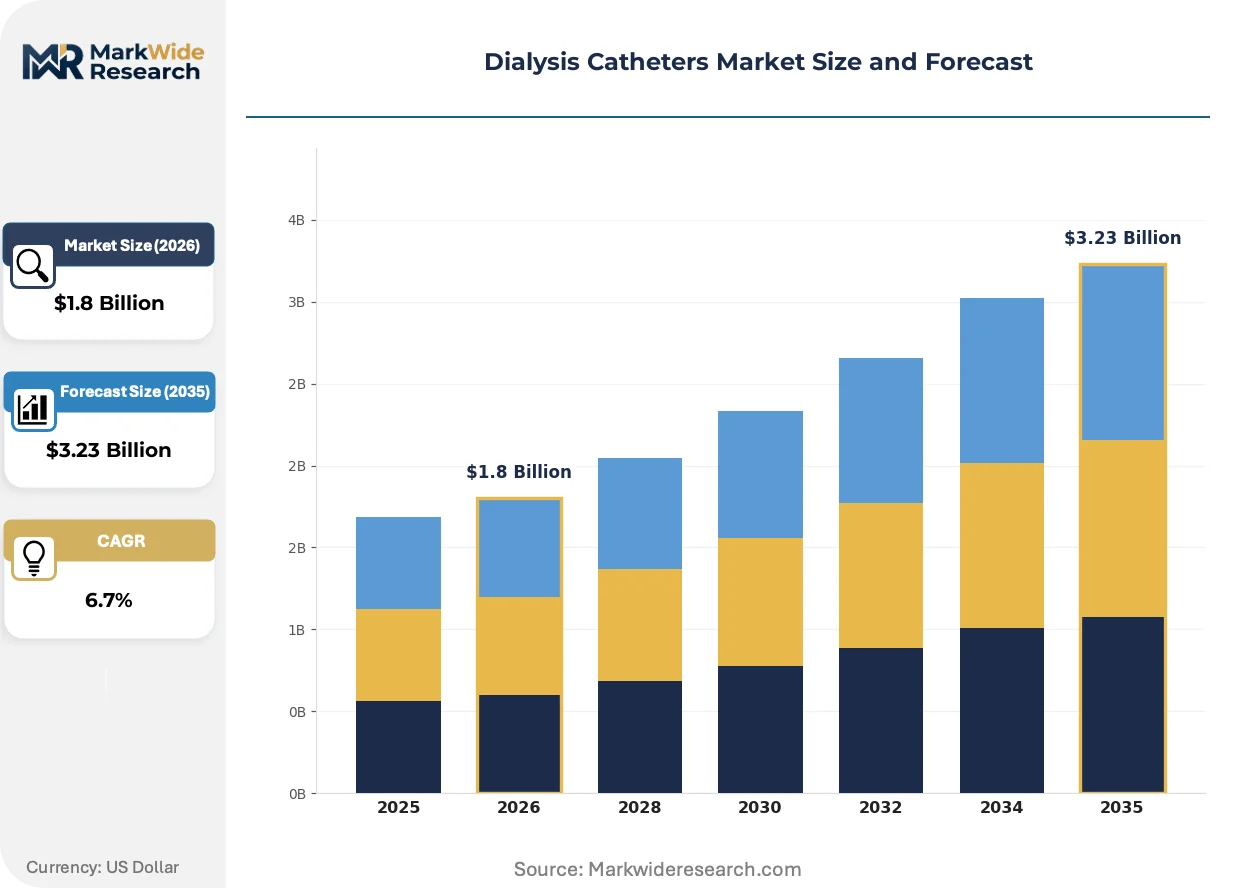
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temporary Catheters, Permanent Catheters, Tunneled Catheters, Non-tunneled Catheters Material: Silicone, Polyurethane, PVC, Biocompatible Polymers End User: Hospitals, Dialysis Centers, Home Care, Specialty Clinics Application: Hemodialysis, Peritoneal Dialysis, Apheresis, Vascular Access |
| Companies Covered | Medtronic, BD, AngioDynamics, Teleflex Incorporated, Merit Medical Systems, B. Braun Melsungen AG, Baxter International, Fresenius Medical Care, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dialysis Catheters Market Emerging Trajectories
Digital manufacturing controls and real-time quality monitoring are compressing defect rates in silicone extrusion processes while enabling lot-level traceability that satisfies tightening vascular access device regulations.
Computational fluid dynamics software is virtualizing catheter lumen design optimization before physical prototyping, allowing Medtronic and B. Braun engineers to simulate blood flow patterns and thrombosis risk across hundreds of geometric permutations. Dialysis centers purchasing high-flow hemodialysis catheters are receiving devices with 15-20% fewer design iterations than legacy development cycles required. This virtualization is compressing R&D timelines from 24 months to 14 months for next-generation tunneled catheter platforms.
EMA's Medical Device Regulation extended equivalent conformity requirements to all chronic vascular access devices, forcing manufacturers to rebuild technical documentation files for products previously certified under the Active Implantable Medical Devices Directive. European notified bodies have consolidated from over 80 to under 25, concentrating assessment capacity and extending review queues. Tunneled dialysis catheters with dwell times exceeding 30 days face the most stringent clinical evidence requirements, pushing manufacturers toward predicate device strategies rather than novel material submissions.
Home dialysis patient training protocols are displacing facility-based catheter insertion as the standard care pathway for peritoneal dialysis initiation in Medicare-covered populations. Renal care networks are unbundling insertion services from device procurement, creating direct purchasing relationships between patients and catheter suppliers. This channel reconfiguration is most visible in United States markets where CMS reimbursement separates device payment from procedural fees, accelerating direct-to-patient delivery models for Tenckhoff and swan-neck peritoneal catheter configurations.
Dialysis Catheters Market Segmentation
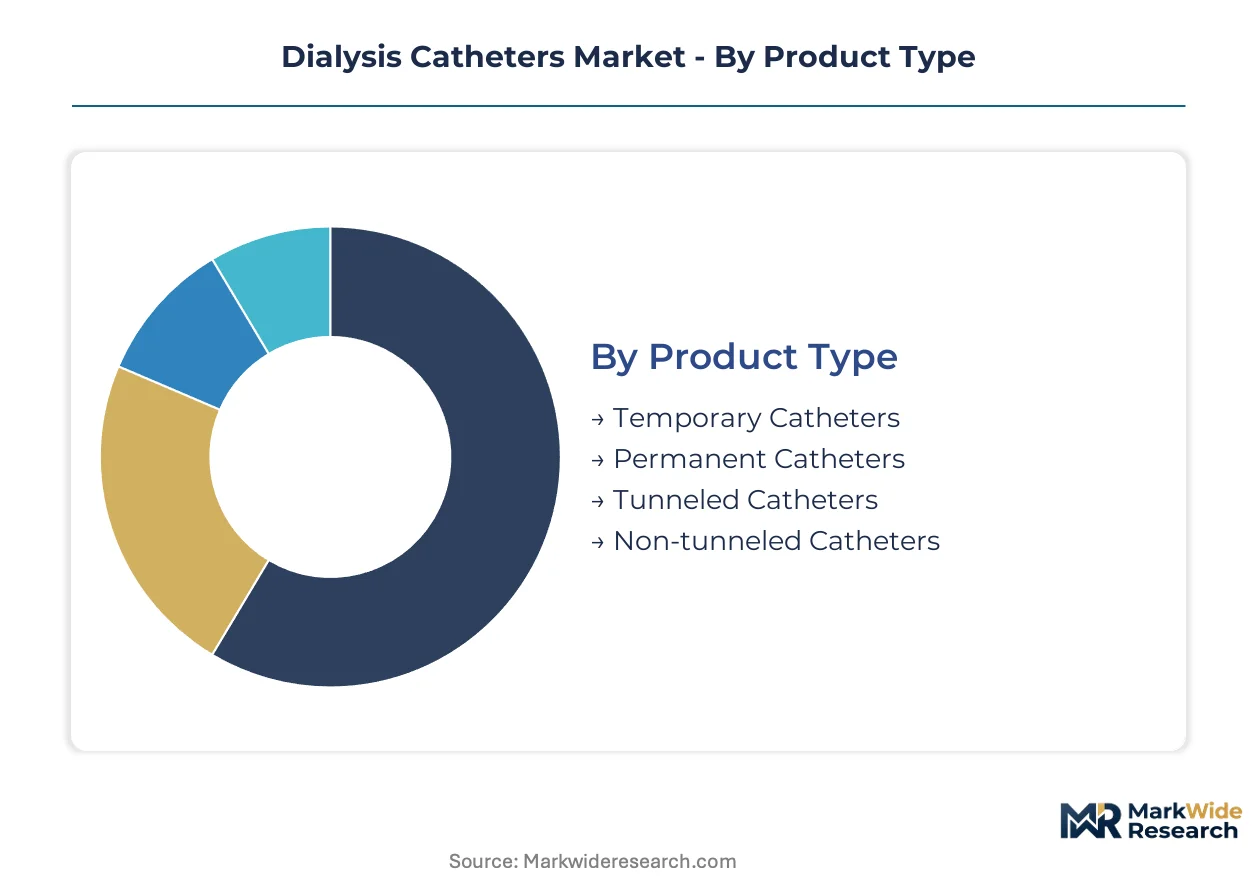
Catheter segmentation in dialysis markets tracks directly to reimbursement cycles and clinical decision hierarchies. Product longevity, material biocompatibility, and care setting economics create distinct commercial compartments that manufacturers must navigate simultaneously.
Product Type:
Cycle times vary dramatically: emergency non-tunneled devices turn over in hours to days, while tunneled platforms sustain revenue over months of dwell time.
- Tunneled Catheters:Silicone-based chronic access devices with subcutaneous cuff fixation engineered for 30-90 day indwelling periods. Demand concentrates in United States dialysis centers where Medicare reimbursement separates device procurement from insertion procedures, creating direct purchasing relationships with manufacturers.
- Non-tunneled Catheters:Acute vascular access for emergency renal replacement with immediate cannulation capability. ICU admissions and emergency departments in Germany and France drive procurement volumes where rapid initiation outweighs infection risk tolerance.
- Temporary Catheters:Short-term bridging devices for fistula maturation periods or failed permanent access.
- Permanent Catheters:Long-term implantable solutions for patients contraindicated for surgical fistula creation.
Tunneled catheters anchor the volume base while non-tunneled variants gain share at the steepest rate through emergency department expansion.
Material:
Cost tiers stratify sharply: medical-grade silicone commands 40-60% premiums over polyurethane in procurement contracts, with biocompatible polymer formulations occupying emerging premium positioning.
- Silicone:Platinum-cured elastomer with superior tissue compatibility and thromboresistance for chronic peritoneal and hemodialysis applications. United States home dialysis programs under CMS reimbursement increasingly specify silicone for patient self-care scenarios where device longevity reduces replacement frequency.
- Polyurethane:High-tensile aromatic or aliphatic formulations delivering kink resistance and high-flow rates in acute hemodialysis. German hospital procurement specifications favor polyurethane for ICU-based acute renal replacement where mechanical durability under stress matters.
- Biocompatible Polymers:Advanced copolymer formulations with integrated antimicrobial surface modifications.
- PVC:Cost-positioned standard material for short-duration acute access in price-sensitive markets.
Silicone dominates revenue contribution while biocompatible polymers climb the fastest as FDA biocompatibility requirements harden.
End User:
Customer concentration has inverted: outpatient dialysis centers now match hospital purchasing volumes as care migration accelerates.
- Dialysis Centers:Freestanding renal care facilities with high-volume catheter consumption and standardized procurement protocols. United States-based chains negotiate direct manufacturer contracts bypassing hospital group purchasing organizations.
- Hospitals:Integrated health systems with diverse vascular access needs spanning emergency, inpatient, and surgical services. German university hospitals maintain captive sterilization capacity influencing catheter sourcing decisions.
- Home Care:Patient-directed purchasing for peritoneal dialysis with unbundled device reimbursement.
- Specialty Clinics:Nephrology-focused ambulatory practices with selective catheter placement capabilities.
Dialysis centers anchor the volume base while home care gains share at the steepest rate through Medicare reimbursement restructuring.
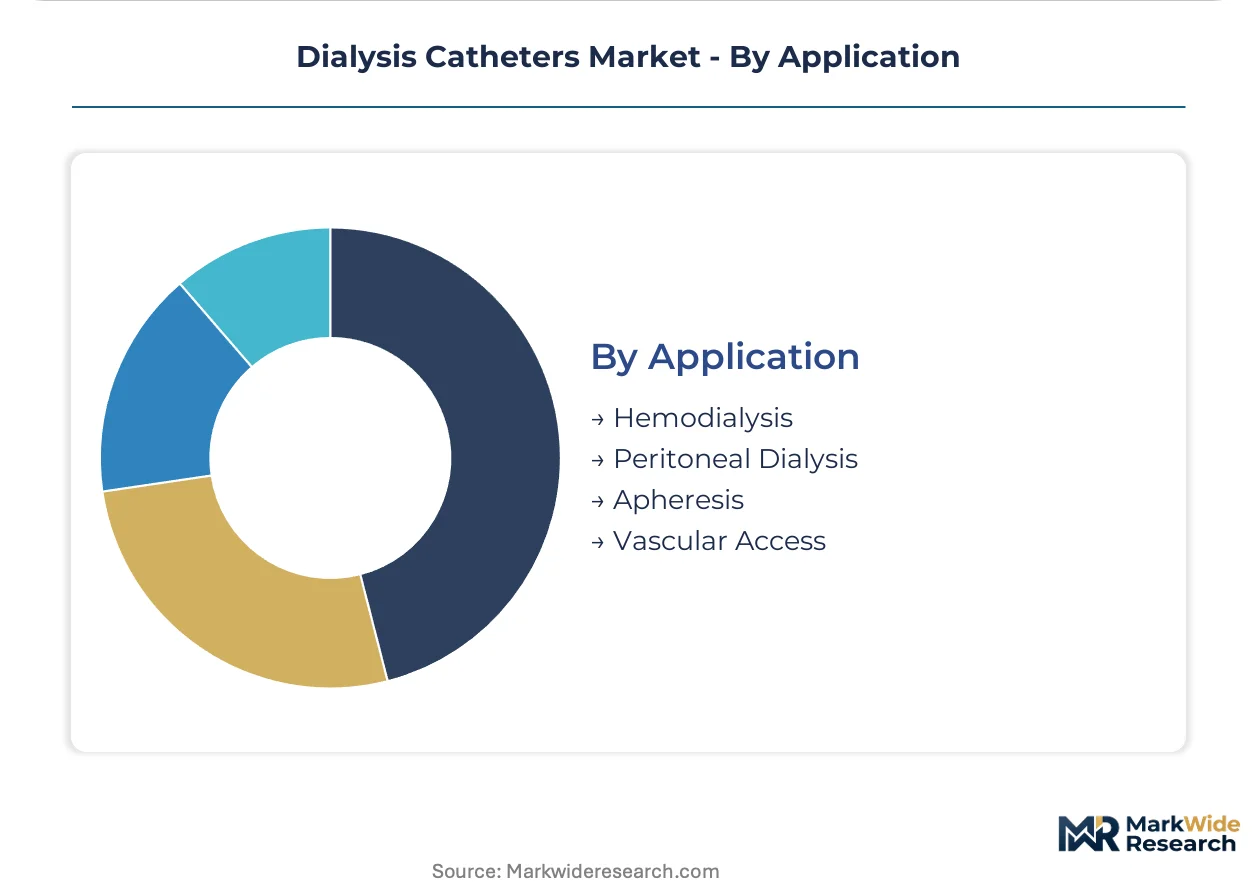
Application:
Clinical utility determines margin structure: hemodialysis catheter procurement absorbs volume discounts while apheresis maintains premium pricing through specialized lumen configurations.
- Hemodialysis:Extracorporeal blood purification via dual-lumen or split-tip catheter designs. United States outpatient facilities under CMS ESRD payment systems drive bulk procurement with quality metrics tied to infection rates.
- Peritoneal Dialysis:Intraperitoneal catheter placement for home-based renal replacement. Brazil and India present catheter-underserved populations relative to hemodialysis prevalence, creating expansion corridors for Tenckhoff and swan-neck configurations.
- Apheresis:Therapeutic plasma exchange and cellular collection procedures.
- Vascular Access:General central venous catheterization for multiple infusion therapies.
Hemodialysis anchors the volume base while peritoneal dialysis gains share at the steepest rate through home care channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty polymer feedstock production clusters in Germany and China, creating geographic vulnerability for catheter manufacturers dependent on consistent material flows. Dialysis catheter demand concentrates in the United States, Germany, China, Japan, and Brazil, each driven by distinct reimbursement structures and regulatory pathways.
United States
Medicare reimbursement for home dialysis under CMS ESRD payment systems accelerates catheter procurement beyond traditional facility settings. The FDA enforces ISO 10993 biocompatibility standards alongside QSR manufacturing guidelines for chronic vascular access devices. Dialysis center chains in Texas and Florida negotiate direct manufacturer contracts, bypassing hospital group purchasing organizations entirely.
Germany
University hospitals in Bavaria and North Rhine-Westphalia maintain captive sterilization capacity that influences catheter sourcing decisions for acute renal replacement. The EMA Medical Device Regulation extends stringent conformity requirements for Class III vascular access devices with dwell times exceeding 30 days. B. Braun Melsungen AG anchors European supply security through captive silicone extrusion infrastructure in Melsungen.
China
Expanded cleanroom capacity and polymer compounding investments in Jiangsu and Zhejiang provinces rewrite competitive dynamics in catheter manufacturing. The NMPA implements GB standards for imported catheter registration that domestic manufacturers must mirror for market access. Local producers in the Yangtze River Delta region scale output to capture share in catheter-underserved peritoneal dialysis segments.
Japan
PMDA oversight of chronic vascular access devices maintains rigorous clinical evidence requirements for tunneled catheter approvals. METI industrial policy supports domestic polymer formulation capabilities for medical-grade silicone production. Osaka-based renal care networks drive procurement of high-flow hemodialysis catheters with infection-resistant surface modifications.
Brazil
Home-based renal replacement modalities remain catheter-underserved relative to hemodialysis prevalence, creating expansion corridors for peritoneal dialysis configurations. ANVISA registration pathways for imported dialysis devices require local clinical validation studies that extend market entry timelines. São Paulo state dialysis center chains absorb growing volumes of acute non-tunneled devices for emergency department admissions.
Dialysis Catheters Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the catheter supply base. The market structure consolidates around diversified medical device conglomerates with vascular access portfolios, while mid-scale manufacturers compete on material specialization and regional channel depth. Two strategic archetypes dominate: integrated hospital suppliers with direct dialysis center relationships, and polymer-focused fabricators with captive extrusion capabilities. Competitive moves concentrate on backward integration into silicone feedstock and direct-to-dialysis-center distribution bypassing traditional procurement hierarchies.
Among diversified platform operators, Medtronic and Baxter International exemplify the integrated vascular access portfolio archetype, leveraging hospital channel dominance across North America and Western Europe. B. Braun Melsungen AG occupies a position as a European-anchored specialist with captive manufacturing infrastructure. These three entities represent distinct competitive postures: Medtronic and Baxter sit within the scale-driven, multi-therapy platform tier, while B. Braun exemplifies regional supply security through in-house polymer processing capabilities.
| Leading Market Players |
|---|
| Medtronic |
| BD |
| AngioDynamics |
| Teleflex Incorporated |
| Merit Medical Systems |
| B. Braun Melsungen AG |
| Baxter International |
| Fresenius Medical Care |
| Cook Medical |
| Others |
Supply Flow & Price Mechanics
Jiangsu province's cleanroom capacity expansion in the Yangtze River Delta directly compresses procurement costs for silicone-based chronic access devices, transferring pricing power toward manufacturers with captive polymer compounding infrastructure. This geographic supply shift forces traditional hospital procurement hierarchies to renegotiate contract terms as direct-to-dialysis-center distribution channels proliferate.
Pricing Analysis
FDA's ISO 10993 biocompatibility requirements dictate the pricing tier structure for chronic vascular access devices, separating platinum-cured silicone formulations from standard polyurethane alternatives. Three-tier pricing structure across premium antimicrobial-coated, standard silicone, and economy polyurethane levels reflects certification grade and dwell time performance. Cost compression in the standard tier is intensifying because German and Chinese polymer feedstock producers are consolidating supply positions. Dialysis center chains exhibit the highest price sensitivity due to volume procurement protocols, while emergency departments prioritize immediate availability over unit cost.
Supply Chain Analysis
Contract manufacturing capacity for medical-grade silicone extrusion concentrates among B. Braun's captive Melsungen facilities and select Jiangsu-based producers serving domestic NMPA registration pathways. Raw material flows draw from specialty polymer clusters in Germany, China, and Japan, with platinum catalyst supply resting on South African and Russian mining outputs. Single-source vulnerability permeates the platinum-cured silicone segment where alternative validation timelines extend 18-24 months. Distribution runs through hospital group purchasing organizations for acute devices, while chronic access platforms increasingly bypass traditional procurement hierarchies through direct manufacturer-dialysis center relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dialysis catheter markets sit in early-cycle expansion as Medicare home dialysis reimbursement policies unbundle device procurement from facility-based care delivery. Peritoneal dialysis penetration in catheter-underserved markets creates foundational growth corridors for manufacturers with polymer formulation capabilities.
For Market Incumbents: Insulate margin positions by deepening backward integration into medical-grade silicone feedstock and securing direct purchasing relationships with high-volume dialysis center chains. The threat of Chinese manufacturers with NMPA-validated cleanroom capacity requires preemptive certification investment in antimicrobial coating technologies. Capacity addition in Texas and Florida outpatient markets anchors channel control against emerging regional competitors. For New Entrants and Emerging Players: Establish a beachhead in Brazil's peritoneal dialysis segment where ANVISA registration barriers filter established competitors and home-based renal replacement remains catheter-underserved relative to hemodialysis prevalence. India's expanding dialysis center network presents secondary white-space opportunity for Tenckhoff catheter configurations. A direct-to-patient delivery model leveraging unbundled CMS reimbursement separates new entrants from hospital GPO dependency. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underutilized vascular access portfolios and stranded silicone extrusion assets. Long-term viability hinges on exposure to home dialysis reimbursement tailwinds and antimicrobial coating convergence. The signal to watch is CMS policy recalibration between facility-based and remote care payment parity, which would accelerate catheter utilization across patient residences.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Integration | Silver-ion and chlorhexidine convergence with silicone substrates opens premium positioning for infection-resistant chronic access devices. |
| Direct-to-Dialysis-Center Distribution | Bypassing hospital GPO hierarchies captures margin from high-volume outpatient renal networks in Texas and Florida. |
| Captive Silicone Extrusion Investment | In-house polymer processing secures supply continuity against German and Chinese feedstock concentration risks. |
| Peritoneal Dialysis Market Development | Brazil and India expansion corridors address catheter-underserved populations relative to hemodialysis prevalence. |
| Dual ISO-FDA Validation Harmonization | Streamlined biocompatibility testing reduces redundant expenditure for multi-regional chronic access device launches. |
Methodological Framework
Desk research of FDA 510(k) filings, EMA MDR technical documentation, and CMS Medicare reimbursement databases preceded structured interviews with dialysis center procurement directors, biomedical engineers, and GPO contracts managers. Primary fieldwork across North American and European renal care networks combined with secondary validation from hospital purchasing databases and polymer trade flow records. Bottom-up catheter volume estimates by material type and dwell time category were triangulated against top-down market sizing from manufacturer revenue disclosures.
Fixed assumptions held regulatory pathway timelines and reimbursement policy structures constant across the analysis window, while silicone feedstock pricing and cleanroom capacity utilization were modeled as variable inputs. Segmentation dimensions included catheter type, material formulation, end-user setting, and geographic regulatory cluster. CAGRs were derived from patient population growth, care setting migration rates, and replacement cycle frequencies for tunneled versus non-tunneled platforms. Infection rate metrics and antimicrobial coating adoption curves informed premium segment expansion assumptions.
Stress conditions across platinum catalyst supply disruption, EMA notified body consolidation delays, and CMS home dialysis reimbursement recalibration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor sensitivities specific to chronic vascular access device markets. Quarterly review of FDA biocompatibility guidance updates and dialysis center chain merger activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
Implant Handpiece Market
Medical Devices
Embolization Plugs Market
Medical Devices
Biodegradable Stents Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Microdebrider Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
Organoids Kits Market
Medical Devices
High Viscosity Bone Cement Market
Medical Devices
Electric Breast Pumps Market
Medical Devices
Global Cryotherapy Market
Medical Devices
Airway Management Market
Medical Devices
Ventilation Devices Market
Medical Devices
Electronic Pill Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Compression Therapy Devices Market