
 Valley Fever Market | 2026-2036
Valley Fever Market Size, Share, and Industry Trends Forecast 2026-2036
Valley Fever Market Outlook
The capital-intensity divergence between large pharmaceutical manufacturers and emerging biotech developers is rotating competitive dynamics across the Valley Fever landscape. Pfizer Inc. leverages its established antifungal manufacturing infrastructure to sustain supply continuity for amphotericin B formulations. Anivive Lifesciences Inc. competes through specialized vaccine development programs targeting Coccidioides immunity. Bristol Myers Squibb anchors its position via broad-spectrum antifungal portfolios that extend into endemic disease markets.
Valley Fever denotes coccidioidomycosis, a fungal infection caused by Coccidioides immitis and C. posadasii species endemic to arid soils of the southwestern United States, Mexico, and parts of Central and South America. Diagnostic Tests are gaining structural priority as PCR-based detection and antigen assays replace slower culture methods in hospital laboratories. Antifungal Medications retain the dominant value share, though Vaccines represent the fastest-expanding segment as developers advance candidates through preclinical and early clinical stages.
FDA oversight governs antifungal drug approval pathways and diagnostic test validation standards, while CDC epidemiological surveillance frameworks dictate reporting protocols for endemic fungal infections. The National Institutes of Health funds translational research that shapes product development priorities for Coccidioides-specific therapeutics. Stakeholders must monitor clinical trial readouts from vaccine developers and diagnostic platform innovators to anticipate shifts in treatment paradigms and procurement standards.
Market Dynamics
Diagnostic platform procurement by hospital-based antifungal therapy programs is compressing detection timelines and redirecting capital toward PCR-based detection systems. This shift is restructuring competitive positioning between established pharmaceutical manufacturers and emerging biotech developers.
Growth Catalysts
- CDC Surveillance Mandates:Tightened reporting requirements for endemic fungal disease in high-burden zones are standardizing diagnostic protocols and expanding testing volumes in Arizona, California, and Texas clinical networks.
- NIH Translational Funding:Federal research priorities for Coccidioides-specific therapeutics are accelerating vaccine candidate advancement through preclinical stages.
- Hospital Laboratory Modernization:Antigen assay adoption is displacing slower culture methods and creating procurement urgency for automated diagnostic platforms.
Market Restraints
- Amphotericin B Supply Concentration:Manufacturing infrastructure for this critical antifungal remains concentrated among limited large-scale producers, exposing procurement continuity risks.
- FDA Validation Burden:Diagnostic test approval pathways for novel detection platforms impose extended timelines and capital requirements on platform innovators.
- Endemic Geography Limitation:Coccidioides habitat confinement to arid southwestern soils restricts addressable patient populations and commercial scale for prophylactic interventions.
Strategic Opportunities
- Mexico Market Expansion:Underpenetrated diagnostic infrastructure in northern Mexican states with Coccidioides endemicity offers volume expansion potential for PCR platform distributors.
- At-Risk Occupational Screening:Agricultural and construction workforce testing programs represent an emerging application segment with concentrated employer procurement authority.
- Vaccine Development Incentives:Priority review vouchers and orphan disease designations for Coccidioides immunity candidates create regulatory tailwinds for biotech developers.
Industry Challenges
- Specialized Mycology Expertise Gap:Clinical microbiology training programs produce insufficient Coccidioides identification specialists, constraining laboratory throughput expansion.
- Cold-Chain Antifungal Distribution:Amphotericin B formulations require temperature-controlled logistics that strain rural healthcare supply networks in endemic counties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valley Fever Market |
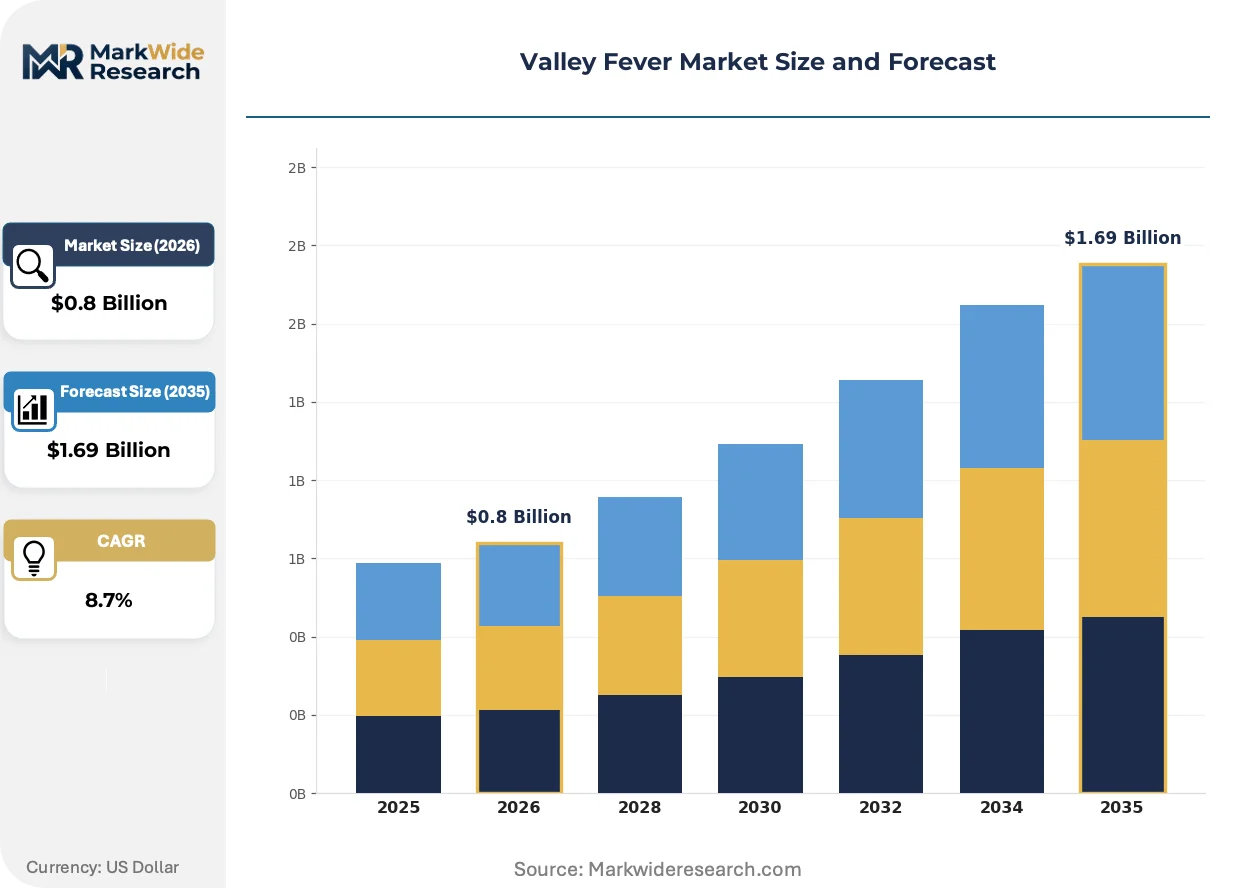
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifungal Medications, Diagnostic Tests, Vaccines, Supportive Care Delivery Mode: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Clinics, Home Care, Research Laboratories Application: Therapeutic, Diagnostic, Prophylactic, Research |
| Companies Covered | Pfizer Inc., Johnson and Johnson, Merck & Co. Inc., GlaxoSmithKline Pharmaceuticals Limited, Bristol Myers Squibb, Fresenius Kabi, Novartis, Anivive Lifesciences Inc., Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valley Fever Market Strategic Shifts
Detection technology advancement and surveillance policy tightening are bifurcating the Valley Fever landscape into rapid-diagnostic and prophylactic-prevention investment tracks. These parallel developments are reshaping capital allocation across the therapeutic continuum.
PCR-based detection is bifurcating hospital laboratory procurement strategies between high-throughput automated platforms and point-of-care antigen systems. Academic medical centers in Phoenix and Tucson are adopting multiplex molecular panels that compress identification timelines from days to hours. This technology compression is enabling same-day treatment initiation while marginalizing culture-dependent workflows.
CDC's endemic fungal disease surveillance frameworks are mandating standardized case definitions and electronic laboratory reporting across Arizona, California, and Texas. These protocols are industrializing epidemiological data collection and creating procurement specifications for interoperable health information systems. Hospital systems in Maricopa County are responding by integrating diagnostic platforms with state health department reporting infrastructure.
Hospital pharmacy committees are consolidating antifungal procurement authority and unbundling diagnostic testing from therapeutic dispensing. This concentration is displacing decentralized physician office purchasing and redirecting volume toward integrated delivery networks with captive laboratory capabilities. The shift is most visible in California's Central Valley, where Kaiser Permanente and Sutter Health systems have centralized Valley Fever management protocols.
Valley Fever Market Segmentation
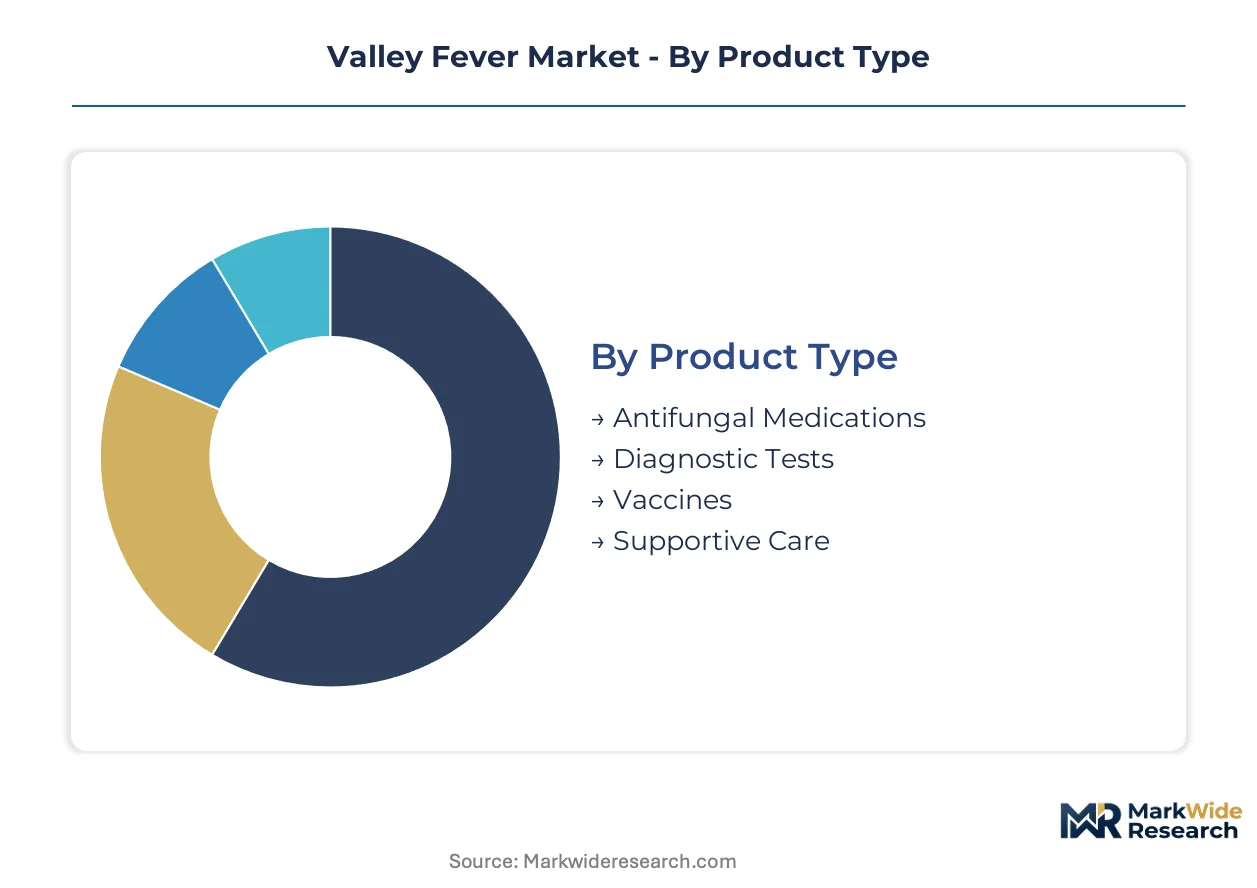
Valley Fever market segmentation reveals distinct procurement patterns across hospital systems, diagnostic laboratories, and emerging prophylactic channels. Each segment category channels capital toward different technology platforms and regulatory pathways.
Product Type:
Hospital pharmacy committees route antifungal procurement through centralized therapeutic protocols, while diagnostic platforms flow through laboratory capital budgets and vaccine candidates attract biotech venture funding.
- Antifungal Medications:Amphotericin B formulations and azole-class drugs dominate therapeutic protocols in Arizona and California hospital networks. Procurement concentrates within integrated delivery networks that manage severe coccidioidomycosis cases requiring inpatient administration.
- Diagnostic Tests:PCR-based detection systems and antigen assays displace culture-dependent workflows in Maricopa County and Central Valley laboratories. These platforms compress identification timelines from days to hours, enabling same-day treatment initiation.
- Vaccines:Preclinical and early-stage Coccidioides immunity candidates attract NIH translational funding and priority review voucher designations.
- Supportive Care:Adjunctive therapies manage inflammatory complications in disseminated disease presentations.
By volume, Antifungal Medications leads. By growth pace, Vaccines is climbing the fastest.
Delivery Mode:
Route selection follows disease severity gradients and care setting economics, with inpatient parenteral administration commanding premium reimbursement versus outpatient oral maintenance.
- Intravenous:Amphotericin B liposomal formulations require temperature-controlled infusion infrastructure available in tertiary medical centers. Cold-chain logistics strain rural healthcare supply networks across endemic counties.
- Oral:Fluconazole and itraconazole tablets enable step-down therapy and outpatient maintenance regimens. Demand concentrates in Kaiser Permanente and Sutter Health systems that have centralized Valley Fever management protocols.
- Subcutaneous:Emerging delivery formats for experimental prophylactic candidates.
- Topical:Limited application for cutaneous manifestations in ambulatory settings.
Oral administration generates the highest prescription volumes. Intravenous retains the steepest revenue per course.
End User:
Procurement authority is migrating toward integrated delivery networks with captive laboratory capabilities, displacing decentralized physician office purchasing.
- Hospitals:Academic medical centers in Phoenix and Tucson anchor antifungal consumption and advanced diagnostic platform adoption. These institutions manage severe disseminated cases and participate in CDC-mandated surveillance reporting.
- Clinics:Community health centers in California's Central Valley handle initial screening and oral therapy initiation. Staffing constraints limit specialized mycology expertise at these sites.
- Home Care:Outpatient infusion services for stable patients requiring prolonged amphotericin B courses.
- Research Laboratories:NIH-funded translational programs and vaccine developer facilities drive preclinical reagent demand.
Hospitals capture the dominant spend share. Research Laboratories are gaining share fastest as vaccine candidates advance.
Application:
Functional segmentation separates revenue-generating therapeutic activity from surveillance-mandated diagnostic testing and forward-looking prophylactic development.
- Therapeutic:Antifungal drug administration for confirmed coccidioidomycosis cases follows standardized protocols in CDC high-burden zones. Arizona, California, and Texas clinical networks drive procedure volumes.
- Diagnostic:PCR and antigen testing volumes expand under tightened CDC reporting requirements for endemic fungal disease. Electronic laboratory reporting integration creates procurement specifications for interoperable health information systems.
- Prophylactic:Occupational screening programs for agricultural and construction workforces represent an emerging application with concentrated employer procurement authority.
- Research:Coccidioides-specific translational studies funded through National Institutes of Health priorities.
Therapeutic application leads by patient volume. Prophylactic is expanding most quickly as at-risk workforce screening programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for Valley Fever diagnostics and therapeutics varies sharply across geographies. Arizona and California hospital systems absorb premium pricing for rapid PCR platforms, while Mexican border clinics remain highly price-sensitive to testing costs.
United States
FDA-regulated diagnostic platforms dominate procurement in Maricopa County and California's Central Valley, where CDC surveillance mandates drive testing volume. Phoenix-based academic medical centers anchor adoption of multiplex molecular panels that compress identification timelines. Kaiser Permanente and Sutter Health systems have centralized Valley Fever management protocols across their networks.
Mexico
Northern Mexican states with Coccidioides endemicity present underpenetrated diagnostic infrastructure and volume expansion potential for PCR distributors. The country's national pharmaceutical regulator governs antifungal importation and clinical trial authorization for vaccine candidates. Sonora and Baja California laboratories are adopting antigen assays to replace slower culture methods.
Canada
Health Canada oversight governs diagnostic test licensing and antifungal drug approval pathways for limited endemic cases in southern prairie provinces. Travel-related coccidioidomycosis screening drives sporadic demand in Toronto and Vancouver reference laboratories. Provincial health authorities coordinate with CDC surveillance frameworks for cross-border case reporting.
Brazil
ANVISA regulates antifungal formulations and diagnostic platform registration for emerging coccidioidomycosis recognition in northeastern arid zones. São Paulo research hospitals participate in NIH-funded translational studies for Coccidioides-specific therapeutics. The country's agricultural workforce screening programs represent nascent prophylactic demand.
Argentina
The national pharmaceutical regulator oversees endemic fungal disease reporting in Córdoba and San Luis provinces where Coccidioides habitat overlaps agricultural regions. Buenos Aires reference laboratories import PCR-based detection systems for disseminated case confirmation. University hospital networks in Rosario are developing regional mycology expertise capacity.
Valley Fever Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Valley Fever landscape. Large pharmaceutical manufacturers leverage established antifungal manufacturing infrastructure to sustain supply continuity, while emerging biotech developers concentrate on specialized vaccine candidates and diagnostic innovations. Three archetypes define competitive positioning: legacy antifungal producers with broad infectious disease portfolios, dedicated endemic fungal disease specialists, and platform-agnostic diagnostic instrument manufacturers. Consolidation pressure and strategic partnerships represent the dominant competitive moves as procurement authority migrates toward integrated hospital networks.
Within the legacy pharmaceutical tier, Pfizer Inc. and Bristol Myers Squibb occupy positions anchored by broad-spectrum antifungal portfolios that extend into endemic disease markets. Anivive Lifesciences Inc. exemplifies the specialist archetype, representing dedicated Coccidioides immunity development programs. These three companies collectively illustrate the capital-intensity divergence reshaping competitive dynamics across detection, therapeutic, and prophylactic investment tracks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson and Johnson |
| Merck & Co. Inc. |
| GlaxoSmithKline Pharmaceuticals Limited |
| Bristol Myers Squibb |
| Fresenius Kabi |
| Novartis |
| Anivive Lifesciences Inc. |
| Dr. Reddy's Laboratories |
| Others |
Value Chain & Pricing Dynamics
PCR platform substitution for culture-dependent workflows is compressing hospital laboratory capital cycles while redistributing procurement authority toward integrated delivery networks with captive diagnostic capabilities. This input transition simultaneously concentrates supplier pricing power among automated platform manufacturers and fragments margin capture for reagent producers.
Pricing Analysis
After-sales service contracts for automated PCR systems drive lifetime value capture for diagnostic platform manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers from community hospital networks and rural reference laboratories. Price differentiation rests on throughput capacity, FDA validation tier, and integrated reporting compliance with CDC surveillance mandates. Pricing pressure stems from Kaiser Permanente and Sutter Health procurement consolidation in California's Central Valley. Community health centers exhibit highest price sensitivity due to constrained capital budgets and staffing limitations.
Supply Chain Analysis
Inventory lead times for amphotericin B liposomal formulations extend through temperature-controlled logistics networks across Arizona, California, and Texas endemic counties. Manufacturing infrastructure draws from Pfizer's established antifungal production facilities and Fresenius Kabi's parenteral drug supply base. Raw material dependencies include phospholipid excipients, sterile water for injection, and specialized vial packaging. Single-source vulnerability concentrates in liposomal formulation technology. Distribution runs through integrated delivery network pharmacy committees that have displaced decentralized physician office purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as PCR-based detection displaces culture-dependent workflows and vaccine candidates threaten prophylactic antifungal demand.
For Market Incumbents: Shield azole-class market position through backward integration into active pharmaceutical ingredient supply and captive diagnostic platform partnerships with Maricopa County hospital systems. FDA validation investment for multiplex molecular panels creates channel control against emerging antigen assay competitors. Cold-chain logistics capability in rural Texas counties provides defensive moat against generic liposomal formulation entrants. For New Entrants and Emerging Players: Occupational screening service gaps in California agricultural corridors and Sonora construction zones offer white-space penetration paths. Employer-sponsored testing programs for at-risk workforces represent the most penetrable segment with concentrated procurement authority. Go-to-market execution should anchor on bundled PCR platform deployment with state health department reporting integration. For Investors and Strategic Acquirers: Capital is best deployed toward preclinical vaccine developers with NIH translational funding and priority review voucher designations. Long-term viability hinges on Coccidioides immunity candidate advancement through Phase I trials. The signal to watch is CDC surveillance mandate expansion into electronic laboratory reporting specifications that favor interoperable diagnostic platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase I progression for Anivive Lifesciences' Coccidioides vaccine candidate validates immunogenicity platform. |
| Regulatory Approval Pathway | FDA 510(k) clearance for multiplex PCR panels accelerates hospital laboratory procurement decisions in Phoenix. |
| Manufacturing Scale-Up | Liposomal amphotericin B capacity expansion addresses cold-chain distribution strain across rural endemic counties. |
| Hospital System Partnership | Kaiser Permanente centralized protocols create template for integrated Valley Fever management adoption. |
| Pipeline Diversification | Antigen assay development complements PCR platforms against culture-dependent workflow displacement. |
Study Parameters
Operator-level perspectives from hospital pharmacy directors, clinical microbiology laboratory managers, CDC surveillance officers, and NIH program officers anchored the qualitative base. Primary fieldwork combined structured interviews with hospital procurement committees and diagnostic platform manufacturers. Secondary validation drew from FDA 510(k) filings, ClinicalTrials.gov registry entries, CDC endemic fungal disease surveillance reports, and hospital GPO contract databases. Bottom-up testing volume estimates and top-down therapeutic expenditure aggregates underwent cross-triangulation.
Sensitivity analysis around CDC mandate timing and vaccine candidate progression probability shaped scenario boundaries. Segmentation modeling covered product type, delivery mode, end user, and application across the projection horizon. CAGRs derived from epidemiological incidence projections, diagnostic platform replacement cycles, and therapeutic protocol standardization curves. Forecast inputs included Coccidioides habitat expansion modeling and hospital laboratory capital budget elasticity.
Underlying assumptions cover sustained endemic disease burden in southwestern states, stable FDA diagnostic validation timelines, and continued NIH translational funding priority, with deviation risk concentrated in vaccine candidate clinical readouts and Mexican regulatory harmonization pace. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Brucellosis Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Virology Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Efavirenz Market
Infectious Disease
IVD Infectious Disease Market
Infectious Disease
Norovirus Infection Treatment Market
Infectious Disease
Infectious Enteritis Treatment Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Infectious Disease Treatments Market
Infectious Disease
Chlamydia Infection Treatment Market
Infectious Disease
Global Infectious Disease Drugs Market
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market