
 Global Infectious Disease Drugs Market | 2026-2036
Global Infectious Disease Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Infectious Disease Drugs Market Foresight
Aftermarket service revenue from companion diagnostics and patient monitoring is fragmenting across therapy settings, forcing drug developers to rebuild margin architecture. Pfizer Inc. leverages its hospital distribution infrastructure to capture pull-through from inpatient antibiotic protocols. Gilead Sciences, Inc. anchors its position in antiviral outpatient regimens through direct-to-specialist channel control. Merck & Co., Inc. competes on manufacturing scale for broad-spectrum agents stocked by national health systems.
Infectious disease drugs comprise chemically synthesized or biologically derived therapeutic agents formulated to inhibit, eradicate, or modulate pathogenic microorganisms within host systems, typically administered via oral, intravenous, or intramuscular routes with defined pharmacokinetic profiles targeting minimum inhibitory concentrations. Their primary purpose is to reduce morbidity and mortality from bacterial, viral, fungal, and parasitic infections across acute and chronic treatment paradigms. Antibiotics still occupy the largest revenue pool within drug type segmentation, though antivirals are capturing accelerated investment following persistent RNA virus outbreaks. Hospital care dominates therapy setting volumes, yet home healthcare is expanding fastest as oral bioavailability improves and reimbursement shifts toward site-neutral payment models.
The FDA's QIDP pathway and EMA's PRIME designation reshape clinical trial incentives, compressing development timelines for novel antibacterial and antifungal candidates. WHO prequalification standards govern access to low-income country procurement through multilateral purchasing agreements, creating tiered market access tiers. China's NMPA accelerated review tracks for anti-infectives address domestic resistance priorities. Stakeholders must monitor how AMR surveillance data from national health agencies redirect formulary placement and pricing negotiations.
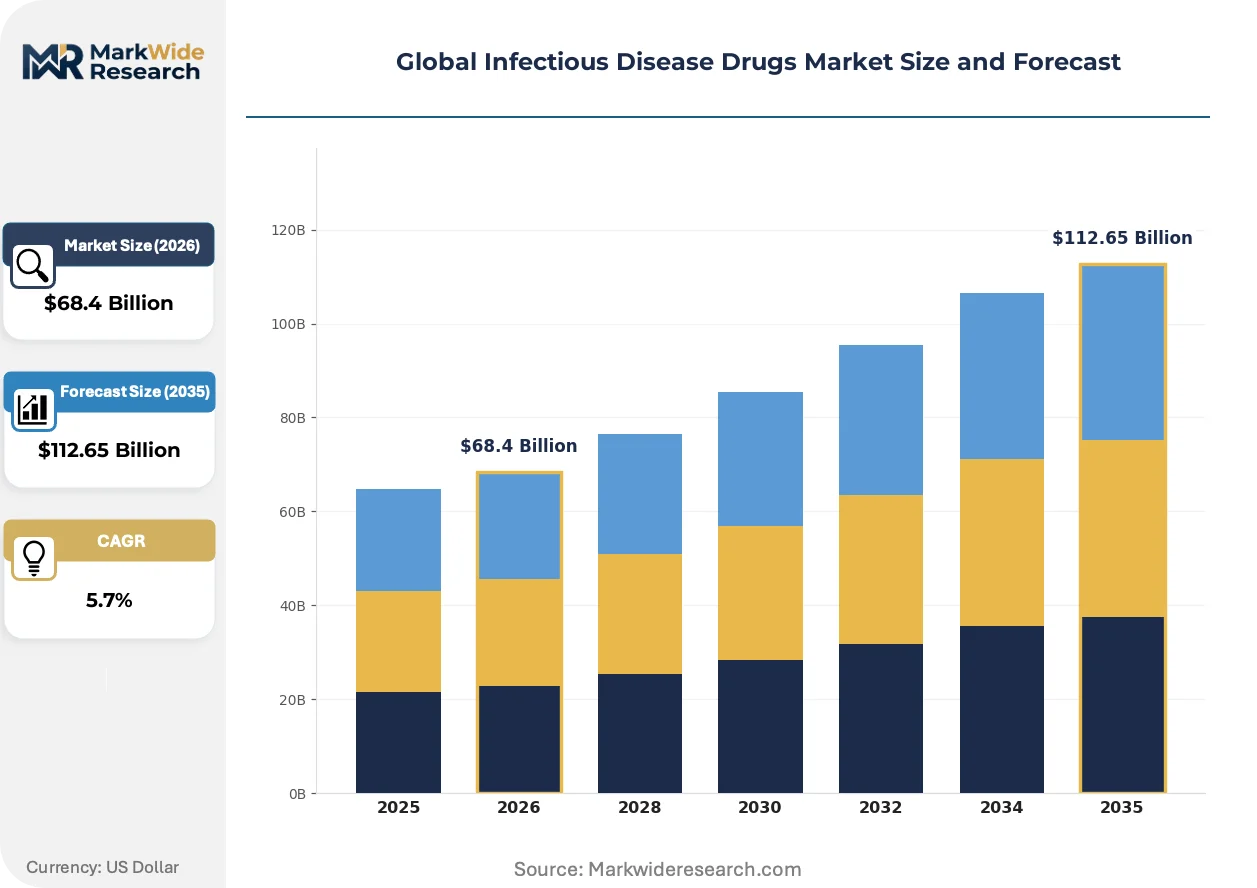
Market Dynamics
Antimicrobial resistance surveillance is compressing development timelines and forcing formularies to rotate faster than patent expirations, restructuring how manufacturers amortize R&D across shorter commercial windows.
Growth Catalysts
- FDA QIDP Pathway:The Qualified Infectious Disease Product designation grants priority review and extended exclusivity, accelerating antibacterial candidates through clinical phases. Hospital systems in India stockpile broad-spectrum agents under national AMR protocols.
- RNA Virus Preparedness:Persistent viral outbreaks drive capital allocation toward nucleoside analog and polymerase inhibitor platforms. Governments in Southeast Asia pre-position antiviral reserves through centralized procurement.
- Companion Diagnostic Integration:Pharmacogenomic testing at point-of-care enables precision dosing for hepatitis C and HIV regimens. Outpatient clinics in Brazil adopt rapid resistance profiling to guide therapy selection.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing clusters in Zhejiang and Shandong provinces create single-source vulnerability for beta-lactam and macrolide precursors.
- Reimbursement Compression:Site-neutral payment models in US Medicare collapse inpatient-outpatient margin spreads, disincentivizing hospital-based antibiotic administration.
- Generic Substitution:Off-patent fluoroquinolones and cephalosporins erode pricing power for novel agents, particularly in outpatient retail channels.
Strategic Opportunities
- Sub-Saharan Africa Access Tiers:WHO prequalification unlocks multilateral purchasing for fixed-dose combination therapies targeting malaria and tuberculosis.
- Home Infusion Migration:Long-acting injectable formulations for HIV maintenance enable channel shift from infusion centers to specialty pharmacy distribution.
- CARB-X Funding Mechanism:Non-dilutive capital from the global partnership de-risks early-stage development of Gram-negative antibiotics.
Industry Challenges
- Clinical Trial Enrollment:Patient recruitment for resistant infection studies competes with standardized-of-care arms, delaying readouts for novel mechanisms.
- Manufacturing Containment:Potent compound handling requirements for cytotoxic antivirals demand isolated facility investments that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Infectious Disease Drugs Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Antibiotics, Antivirals, Antifungals, Antiparasitics, Immunomodulators Disease Indication: Respiratory Infections, Sexually Transmitted Infections, Tropical Diseases, Bloodstream Infections, Gastrointestinal Infections Therapy Setting: Hospital Care, Outpatient Clinics, Long-Term Care Facilities, Home Healthcare Distribution Channel: Pharmacies, Hospitals, Online Pharmacies, Direct Sales, Wholesale Distributors |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., GlaxoSmithKline plc, Johnson & Johnson, Sanofi, Abbott Laboratories, Gilead Sciences, Inc., F. Hoffmann-La Roche Ltd, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Infectious Disease Drugs Market Shifts & Advancements
Biologic-antibiotic combinations and AI-guided molecular design are collapsing traditional discovery timelines while regulatory frameworks race to accommodate novel modalities.
CRISPR-based antibacterial platforms are hybridizing programmable nucleases with conventional small-molecule permeabilizers to target persistent biofilm infections. Academic consortia in the Netherlands and Denmark pilot these systems against carbapenem-resistant Enterobacteriaceae. The approach is compressing preclinical validation from years to months by bypassing traditional target-based screening.
EMA's PRIME designation for regenerative and advanced therapies now extends to bacteriophage cocktails, creating accelerated assessment pathways for personalized anti-infectives. Manufacturers in Central and Eastern Europe are restructuring quality systems to meet the agency's real-time evidence requirements. Phage banks in Poland and Georgia are consolidating to serve this regulatory channel.
Specialty pharmacy networks are capturing outpatient parenteral antimicrobial therapy volumes previously managed by hospital discharge planners. Home health agencies in Florida and Texas now coordinate directly with infectious disease specialists to administer long-acting agents. This channel migration is most visible in HIV pre-exposure prophylaxis and complicated urinary tract infection protocols.
Global Infectious Disease Drugs Market Segmentation
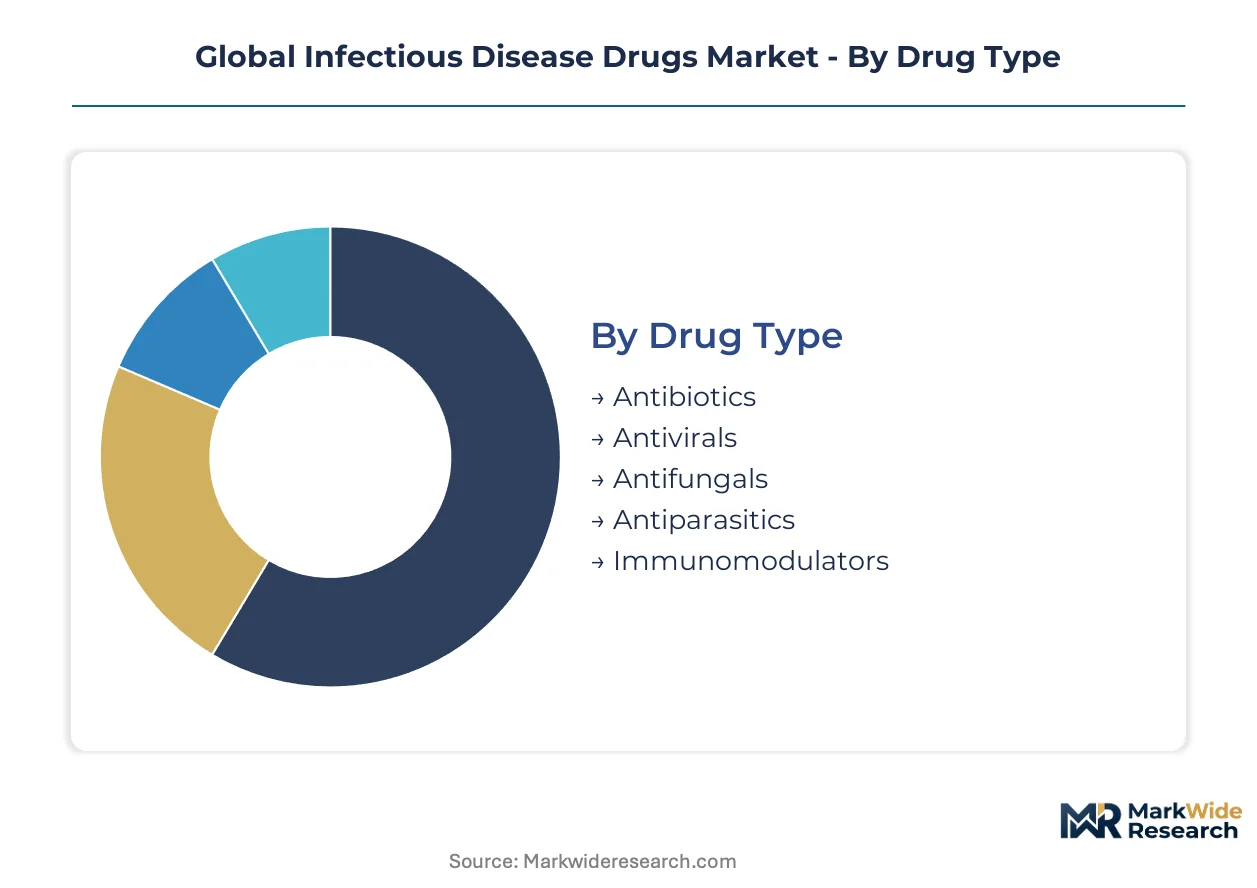
Segmentation in infectious disease drugs reveals how therapeutic modality, clinical setting, and procurement pathway interact to determine pricing power and margin architecture. Manufacturers must align formulation development with specific channel economics and resistance surveillance priorities.
Drug Type:
The use-case spectrum spans acute bacterial sepsis protocols through chronic viral suppression regimens, with each class demanding distinct manufacturing containment and regulatory validation.
- Antibiotics:Beta-lactam, macrolide, and fluoroquinolone formulations dominate hospital formularies for empiric therapy. Demand concentrates in Indian national health programs stockpiling broad-spectrum agents under AMR containment protocols, though generic substitution erodes novel agent margins.
- Antivirals:Nucleoside analogs and polymerase inhibitors target HIV, hepatitis C, and emerging RNA viruses. Gilead Sciences anchors outpatient regimens through direct-to-specialist channel control, while Southeast Asian governments pre-position reserves through centralized procurement.
- Antifungals:Azole and echinocandin classes address invasive candidiasis and aspergillosis in immunocompromised patients. Hospital infusion centers in Brazil and Mexico drive volume for parenteral formulations.
- Antiparasitics:Antimalarial and anthelmintic agents serve WHO prequalification programs across Sub-Saharan Africa. Fixed-dose combinations unlock multilateral purchasing agreements for malaria and neglected tropical disease protocols.
- Immunomodulators:Adjunctive therapies modulate host inflammatory response in severe sepsis and COVID-19 complications. Critical care units in tertiary hospitals generate concentrated demand for IV immunoglobulin and cytokine inhibitors.
The dominant share belongs to antibiotics, while antivirals are closing the gap fastest as RNA virus preparedness reshapes R&D allocation.
Disease Indication:
Cost tier stratification separates high-acuity hospital admissions from manageable outpatient conditions, with reimbursement intensity varying by mortality risk and treatment duration.
- Respiratory Infections:Community-acquired pneumonia and tuberculosis drive antibiotic and antitubercular consumption. India's Revised National Tuberculosis Control Program scales domestic manufacturing for fixed-dose regimens.
- Sexually Transmitted Infections:Gonorrhea, chlamydia, and syphilis protocols require single-dose oral therapies for compliance. Resistance profiling in Brazilian outpatient clinics guides cephalosporin selection.
- Tropical Diseases:Malaria, dengue, and Chagas disease command dedicated funding mechanisms from WHO and bilateral donors. Sub-Saharan procurement tiers prioritize artemisinin-based combination therapies.
- Bloodstream Infections:Sepsis and endocarditis demand rapid broad-spectrum coverage with subsequent de-escalation. Carbapenem-resistant Enterobacteriaceae surveillance in Dutch hospitals accelerates novel Gram-negative development.
- Gastrointestinal Infections:Clostridioides difficile and helminthiasis respond to narrow-spectrum agents and antiparasitics. Oral bioavailability enables home healthcare migration for completion therapy.
Respiratory infections command the largest revenue pool, though tropical diseases are expanding most quickly via access tier mechanisms in low-income markets.
Therapy Setting:
Volume concentration in acute care facilities is shifting as oral bioavailability improvements and site-neutral reimbursement enable channel migration.
- Hospital Care:Inpatient parenteral administration dominates severe sepsis, fungal infections, and surgical prophylaxis. Pfizer leverages distribution infrastructure to capture pull-through from antibiotic stewardship protocols.
- Outpatient Clinics:Specialist-managed HIV, hepatitis C, and uncomplicated infections transition to oral regimens. Florida and Texas specialty pharmacy networks coordinate directly with infectious disease physicians for long-acting injectables.
- Long-Term Care Facilities:Nursing homes generate recurrent urinary tract and respiratory infection episodes requiring empiric therapy. CMS antimicrobial stewardship mandates reshape formulary decisions in US skilled nursing facilities.
- Home Healthcare:Home infusion and self-administered oral regimens reduce total cost of care for stable patients. HIV pre-exposure prophylaxis and complicated UTI protocols lead this channel shift.
Hospital care retains volume leadership, while home healthcare is gaining share fastest as reimbursement neutrality collapses site-based margin spreads.
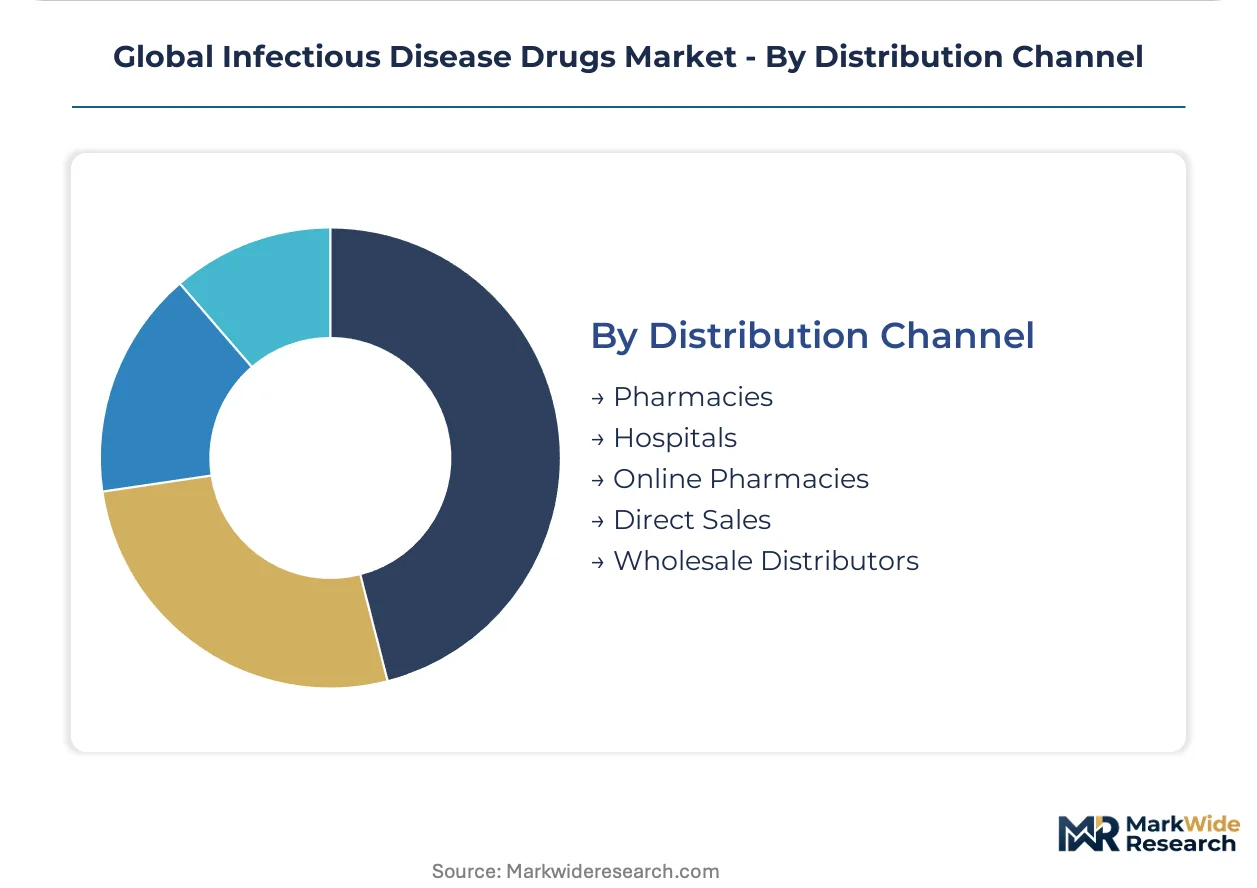
Distribution Channel:
Customer type fragmentation between institutional purchasers and retail consumers determines pricing architecture and service bundling requirements.
- Pharmacies:Community and specialty pharmacies dispense outpatient oral antibiotics and antivirals. Brazil's rapid resistance profiling adoption creates pull-through for companion diagnostic-linked regimens.
- Hospitals:Central pharmacy and ward-level stocking supports empiric therapy and surgical prophylaxis. Group purchasing organizations in Southeast Asia consolidate procurement for broad-spectrum formularies.
- Online Pharmacies:Direct-to-patient delivery expands access for chronic HIV and hepatitis maintenance. Regulatory frameworks in India and China tighten prescription verification requirements.
- Direct Sales:Manufacturer-to-institution contracts for high-value antivirals and novel antibiotics bypass wholesale markups. Gilead's specialist channel control exemplifies this model.
- Wholesale Distributors:Regional logistics networks manage cold-chain and controlled-substance requirements for hospital systems. Zhejiang and Shandong API clusters feed downstream distribution concentration.
Hospitals anchor procurement volume, though online pharmacies are climbing the fastest as digital health infrastructure penetrates emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes infectious disease drugs through national immunization programs and hospital formularies, while the United States channels demand through specialty pharmacy networks and Medicare reimbursement systems. Brazil and Germany diverge further—Brazil relies on rapid resistance profiling in outpatient clinics, whereas German academic consortia pilot CRISPR-based antibacterial platforms.
United States
Specialty pharmacy networks in Florida and Texas coordinate directly with infectious disease specialists for long-acting injectables. The FDA's QIDP pathway accelerates antibacterial candidates through priority review timelines. Home health agencies administer HIV pre-exposure prophylaxis outside traditional infusion centers.
India
Domestic manufacturing capacity scales alongside government immunization programs for broad-spectrum antibiotics. The CDSCO accelerated review tracks align with national AMR containment protocols. Zhejiang and Shandong API clusters supply beta-lactam precursors to Indian formularies despite single-source vulnerabilities.
Brazil
Outpatient clinics adopt rapid resistance profiling to guide cephalosporin selection for sexually transmitted infections. ANVISA governs pharmacogenomic testing standards at point-of-care. São Paulo's hospital infusion centers drive parenteral antifungal volumes for immunocompromised patients.
Germany
Academic consortia pilot CRISPR-based antibacterial platforms against carbapenem-resistant Enterobacteriaceae. The EMA's PRIME designation extends to bacteriophage cocktails for personalized anti-infectives. Bavaria's research clusters compress preclinical validation timelines through programmable nuclease hybridization.
China
The NMPA accelerated review tracks address domestic resistance priorities for novel anti-infectives. Centralized procurement in Southeast Asia pre-positions antiviral reserves from Chinese manufacturers. Beijing-Tianjin-Hebi biotech corridors feed nucleoside analog production for RNA virus preparedness.
Global Infectious Disease Drugs Market Competitive Landscape
Capability concentration sits with mid-cap specialists developing CRISPR-based platforms and bacteriophage cocktails; scale advantage sits with diversified pharmaceutical conglomerates commanding hospital distribution infrastructure. The market structures around three tiers: research-intensive biotechs with novel mechanisms, generic manufacturers competing on API cost, and integrated majors balancing patent-protected portfolios with established channels. Dominant competitive moves include direct-to-specialist channel control for outpatient antivirals and backward integration into active pharmaceutical ingredient production.
Within the integrated pharmaceutical tier, Pfizer Inc. and Merck & Co., Inc. exemplify divergent scale strategies—Pfizer leverages hospital distribution infrastructure for antibiotic stewardship pull-through, while Merck competes on manufacturing scale for broad-spectrum agents stocked by national health systems. Gilead Sciences, Inc. occupies a distinct position in antiviral outpatient regimens, anchoring specialist channel control for nucleoside analog platforms.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Sanofi |
| Abbott Laboratories |
| Gilead Sciences, Inc. |
| F. Hoffmann-La Roche Ltd |
| AstraZeneca plc |
| Others |
Supply & Pricing Matrix
Overcapacity in Zhejiang and Shandong API manufacturing clusters is compressing margins for beta-lactam and macrolide precursors while simultaneously enabling aggressive pricing postures among Chinese suppliers serving Indian formularies. This utilization dynamic forces Western manufacturers to choose between absorbing cost compression or accelerating backward integration into captive API production.
Pricing Analysis
Long-term offtake contracts dominate procurement between Indian national health programs and domestic manufacturers, insulating volume commitments from spot-market volatility in antibiotic precursors. Price differentiation rests on FDA QIDP designation tier and WHO prequalification status, with certified suppliers commanding premium positioning in multilateral purchasing agreements. Cost compression in off-patent fluoroquinolone segments is intensifying because generic substitution erodes novel agent margins in outpatient retail channels. National health systems exhibit lowest price sensitivity due to stockpiling mandates, while community pharmacies in emerging markets face acute margin pressure from reimbursement compression.
Supply Chain Analysis
Export-control regimes governing nucleoside analog production technologies limit technology transfer from Beijing-Tianjin-Hebi biotech corridors to Southeast Asian manufacturing partners. Active pharmaceutical ingredient supply concentrates in China, India, and select Eastern European facilities, drawing from beta-lactam precursors, polymerase inhibitor intermediates, and echinocandin fermentation feedstocks. Single-source vulnerability in Zhejiang and Shandong clusters creates structural risk for hospital formularies dependent on just-in-time replenishment. Distribution runs through wholesale distributors managing cold-chain requirements for parenteral formulations, with specialty pharmacy networks capturing direct-to-specialist channels for outpatient antiviral regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across therapy settings and procurement channels is creating defendable niches for specialists who can align formulation development with site-neutral reimbursement migration. The shift toward home healthcare and specialty pharmacy coordination is dismantling traditional hospital-centric margin pools.
For Market Incumbents: Pre-empt generic substitution pressure in fluoroquinolone and cephalosporin segments by accelerating FDA QIDP pathway submissions for novel antibacterial mechanisms. Deepen backward integration into API production to reduce exposure to Zhejiang and Shandong supply concentration. Anchor hospital distribution infrastructure against pull-through from antibiotic stewardship protocols by embedding clinical decision support tools within formulary management systems.
For New Entrants and Emerging Players: Mid-cap CRISPR-based antibacterial developers in the Netherlands and Denmark represent the most penetrable entry point for platform technology licensing. Sub-Saharan Africa access tiers for WHO-prequalified fixed-dose combinations offer procurement volume without competing against established hospital distribution networks. Pursue CARB-X funding mechanism partnerships to de-risk early-stage Gram-negative development without dilutive capital constraints.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bacteriophage cocktail manufacturing due to EMA PRIME designation quality system requirements. Long-term viability over the next decade favors acquisition targets with programmable nuclease platforms and real-time evidence generation capabilities. Monitor FDA QIDP designation velocity as the inflection indicator for regulatory pathway efficiency and subsequent valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA QIDP pathway compresses development timelines for novel antibacterial candidates through priority review. |
| Regulatory Approval Pathway | WHO prequalification unlocks multilateral purchasing agreements for malaria and tuberculosis combination therapies. |
| Manufacturing Scale-Up | Long-acting injectable capacity expansion enables channel shift from infusion centers to specialty pharmacy distribution. |
| Backward Integration | Captive API production reduces single-source vulnerability to Zhejiang and Shandong supply concentration. |
| Pipeline Diversification | CRISPR-based antibacterial platforms address carbapenem-resistant Enterobacteriaceae surveillance priorities in Dutch hospitals. |
Research Methodology
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary fieldwork captured formulary placement dynamics and reimbursement negotiation patterns across therapy settings. Secondary validation drew from hospital procurement databases, GPO contracts, and CMS Medicare claims data. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Assumptions regarding regulatory pathway efficiency, AMR surveillance intensity, and site-neutral reimbursement adoption were held fixed across baseline scenarios while API supply concentration and generic substitution velocity were stress-tested. Segmentation dimensions included drug type, disease indication, therapy setting, and distribution channel, with regional regulatory clusters modeled separately. CAGRs were derived from fitted growth curves anchored to historical volume data and policy implementation timelines. Forecast inputs incorporated FDA QIDP designation rates and WHO prequalification throughput across the analysis window.
Practitioners should monitor AMR surveillance data releases, CMS reimbursement rulemaking, and API manufacturing cluster utilization rates for early signals of forecast deviation. Forecasts reflect assumptions about regulatory pathway stability and procurement policy continuity. Material shifts in FDA QIDP review timelines or WHO prequalification standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
IVD Infectious Disease Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Global Infectious Disease Therapeutics Market
Infectious Disease
Periodic Fever Syndrome Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Bronchitis Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Gram Positive Bacterial Infections Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Herpes Infection Treatment Market