
 Periodic Fever Syndrome Market | 2026-2036
Periodic Fever Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Periodic Fever Syndrome Market Analysis
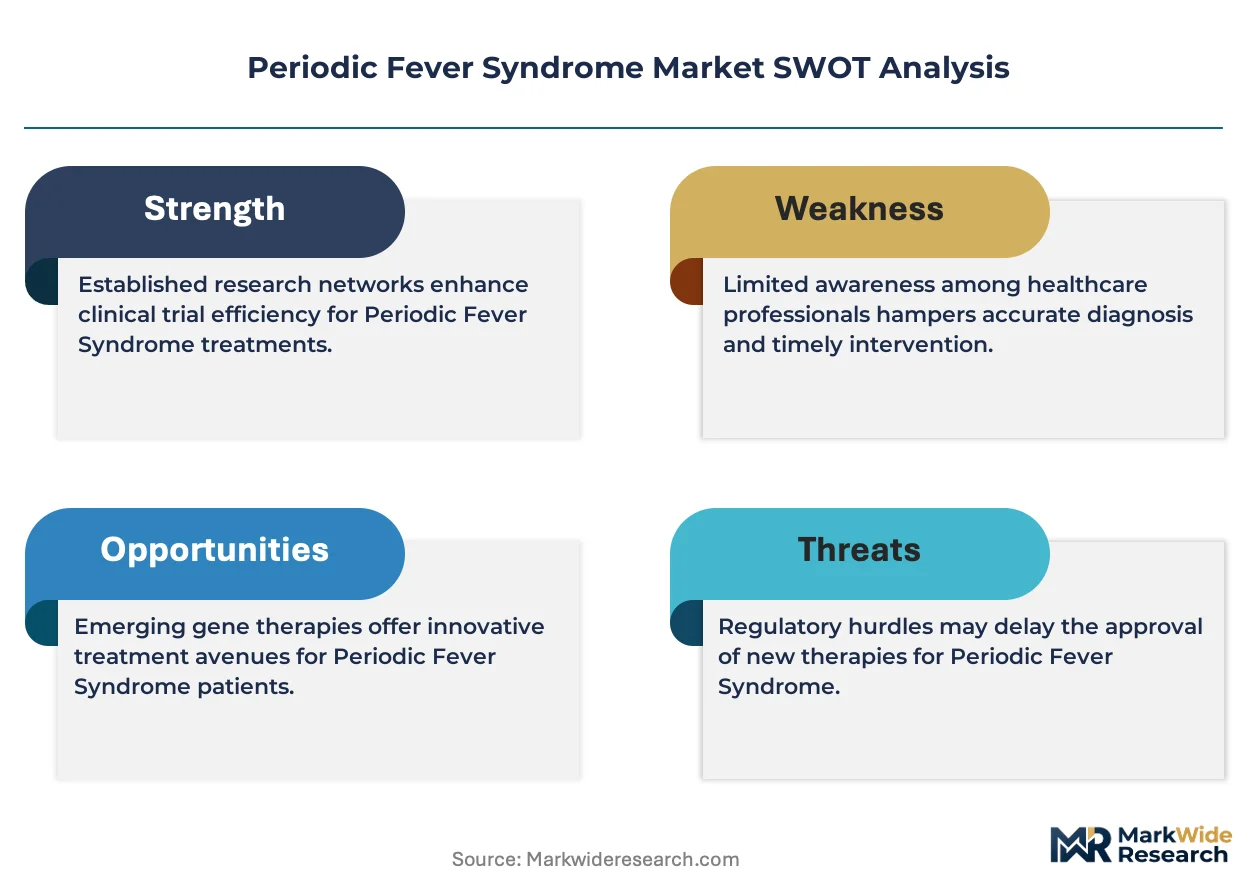
Single-source reliance on colchicine API suppliers is shifting toward multi-source qualification programs across North American and European formulation networks. Novartis AG anchors its position through captive manufacturing of canakinumab, the IL-1β monoclonal antibody approved for cryopyrin-associated periodic syndromes. Swedish Orphan Biovitrum AB specializes in rare disease distribution infrastructure, leveraging cold-chain logistics that sustain product integrity for subcutaneous biologics. Pfizer Inc. competes through R&D intensity in next-generation IL-1 pathway inhibitors, extending its inflammation franchise into autoinflammatory indications.
Periodic fever syndrome encompasses a spectrum of hereditary autoinflammatory disorders characterized by recurrent episodes of fever and serosal inflammation, driven by dysregulated innate immune pathways involving IL-1, mevalonate kinase, and pyrin inflammasome mutations; biologic therapies target specific cytokine nodes with dosing calibrated by body weight and disease severity. The therapy area dimension shows Familial Mediterranean Fever retaining the largest patient pool due to founder mutation prevalence in Mediterranean populations, while Muckle-Wells Syndrome commands premium pricing as a cryopyrinopathy with amyloidosis risk driving urgency of treatment. Among delivery modes, subcutaneous administration leads in outpatient adoption for anakinra and canakinumab, whereas intravenous infusion dominates hospital-based induction protocols for acute flares.
The FDA orphan drug program shapes clinical trial design incentives, while the EMA's Committee for Orphan Medicinal Products coordinates centralized pediatric investigation plans across EU member states. Health Canada's Special Access Programme creates alternative pathways for canakinumab in undifferentiated periodic fever presentations. Stakeholders must monitor evolving biosimilar entry timelines for anakinra and assess gene therapy candidates targeting NLRP3 and MEFV mutations that could redefine maintenance therapy paradigms.
Market Dynamics
The periodic fever syndrome market pivots on biologic therapy adoption, where IL-1 pathway inhibitors are displacing colchicine as first-line maintenance for cryopyrin-associated periodic syndromes. This shift concentrates value capture among manufacturers with cold-chain distribution infrastructure and pediatric hospital contracting relationships.
Growth Catalysts
- FDA Orphan Drug Incentives:The FDA's orphan drug designation pathway compresses clinical trial timelines and grants seven-year market exclusivity for canakinumab and anakinra candidates targeting rare autoinflammatory indications.
- Pediatric Hospital Expansion:Specialized autoinflammatory disease centers at Boston Children's Hospital, Great Ormond Street Hospital, and Necker-Enfants Malades are establishing standardized biologic induction protocols that accelerate therapy initiation.
- Founder Mutation Prevalence:Mediterranean populations carry high-frequency MEFV mutations, creating concentrated diagnosis and treatment demand across Turkey, Israel, and Italy.
Market Restraints
- API Supply Concentration:Single-source reliance on Italian and Turkish colchicine active pharmaceutical ingredient suppliers exposes formulation networks to harvest variability and export restriction risk.
- Cold-Chain Infrastructure Gaps:Subcutaneous biologics require sustained 2-8°C integrity through last-mile delivery, limiting reach into regions with unreliable refrigeration networks.
- Pricing Authority Fragmentation:Payer heterogeneity across EU member states creates reimbursement negotiation complexity that delays market access for premium-priced biologics.
Strategic Opportunities
- Undiagnosed Cohorts in North Africa:Familial Mediterranean Fever remains underdiagnosed in Algeria, Tunisia, and Egypt due to limited genetic testing infrastructure, representing addressable patient expansion.
- Gene Therapy Convergence:CRISPR-based candidates targeting NLRP3 and MEFV mutations could redefine maintenance therapy paradigms by addressing root genetic drivers rather than cytokine suppression.
- Health Canada's Special Access Programme:This alternative pathway enables canakinumab distribution for undifferentiated periodic fever presentations before formal indication expansion.
Industry Challenges
- Pediatric Trial Design Complexity:Rare disease recruitment requires multi-site international coordination across EU member states, extending study duration and regulatory submission preparation.
- Biosimilar Manufacturing Scale-Up:Anakinra biosimilar entrants face protein aggregation control challenges during high-volume subcutaneous formulation production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Periodic Fever Syndrome Market |
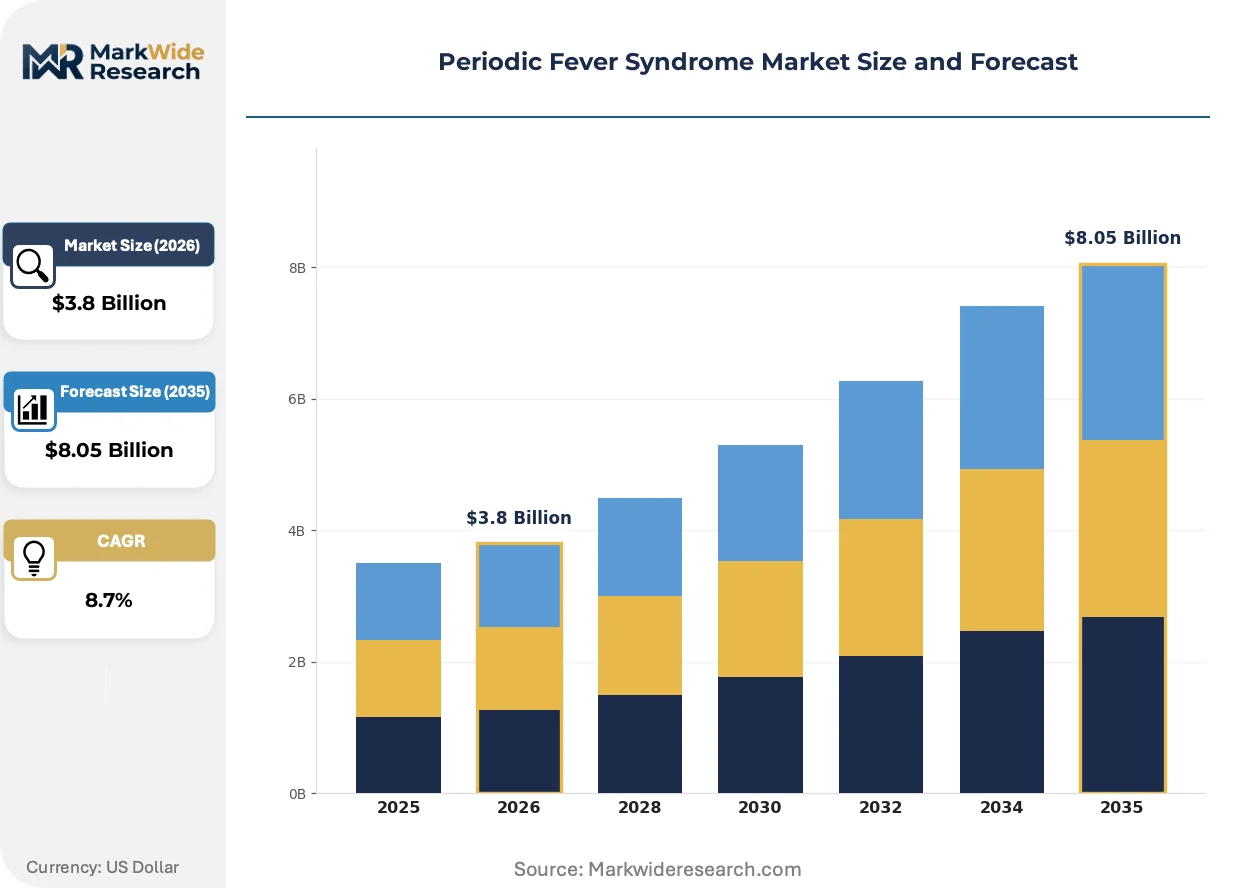
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colchicine, Anakinra, Canakinumab, Cyclosporine Therapy Area: Familial Mediterranean Fever, Still's Disease, Hyper-IgD Syndrome, Muckle-Wells Syndrome End User: Pediatric Hospitals, Research Institutions, Outpatient Clinics, Specialty Pharmacies Delivery Mode: Subcutaneous, Intravenous, Oral, Inhalation |
| Companies Covered | Amgen Inc., Pfizer Inc., Novartis AG, Hikma Pharmaceuticals, Takeda Pharmaceutical Company Limited, Regeneron Pharmaceuticals Inc., AbbVie Inc., Merck & Co., Inc., Swedish Orphan Biovitrum AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Periodic Fever Syndrome Market Emerging Trajectories
Biologic therapy administration is migrating from hospital infusion centers to home-based subcutaneous delivery, compressing the care setting and reshaping stakeholder economics across the value chain.
Subcutaneous auto-injector devices for IL-1 inhibitors are decentralizing treatment administration from hospital-based infusion suites to patient homes. Pediatric patients and their caregivers are adopting these devices at accelerating rates in the United States and Western Europe. This migration reduces hospital capacity utilization while shifting compliance monitoring and adverse event management to remote nursing infrastructure.
The EMA's Committee for Orphan Medicinal Products is coordinating centralized pediatric investigation plans that harmonize clinical data requirements across EU member states. This regulatory convergence reduces redundant trial conduct and accelerates centralized marketing authorization timelines. Biologic manufacturers are responding by prioritizing EU-first submission strategies for novel autoinflammatory indications.
Diagnostic referral networks are consolidating around specialized fever clinics that integrate genetic testing, rheumatology, and immunology expertise. Academic medical centers in the United States, France, and Japan are displacing fragmented generalist evaluation pathways. This concentration improves diagnostic yield for cryopyrin-associated periodic syndromes while creating preferred prescriber relationships that influence biologic selection.
Periodic Fever Syndrome Market Segmentation
Segmentation in the periodic fever syndrome market reveals how treatment decisions bifurcate between cost-driven maintenance protocols and premium biologic interventions. Understanding these divisions illuminates where manufacturers capture margin versus where volume concentrates.
Product Type:
Cost tier determines access pathways, with payers stratifying reimbursement across generic small molecules and specialty biologics.
- Colchicine:Oral alkaloid derived from Colchicum autumnale remains the foundational therapy for Familial Mediterranean Fever prophylaxis. Demand concentrates in Turkey, Israel, and Italy where MEFV mutation prevalence supports high-volume prescribing; API supply fragility from Italian and Turkish harvests constrains formulation security.
- Canakinumab:Human monoclonal antibody targeting IL-1β cytokine commands premium positioning for cryopyrin-associated periodic syndromes. Novartis AG's captive manufacturing and cold-chain infrastructure lock in hospital contracting relationships across the United States and Western Europe.
- Anakinra:Recombinant IL-1 receptor antagonist administered via daily subcutaneous injection.
- Cyclosporine:Calcineurin inhibitor repurposed for steroid-resistant autoinflammatory presentations.
Volume sits with colchicine; growth tilts toward canakinumab.
Therapy Area:
Genetic mutation prevalence and amyloidosis risk stratify urgency of biologic intervention across patient populations.
- Familial Mediterranean Fever:Recurrent serositis driven by MEFV gene mutations constitutes the largest addressable population. Founder effects in Mediterranean basin populations sustain diagnostic concentration in Turkey, Israel, and Italy; colchicine resistance in 5-10% of cases creates biologic upgrade pathways.
- Muckle-Wells Syndrome:Cryopyrinopathy characterized by urticaria, sensorineural hearing loss, and systemic amyloidosis risk commands the steepest pricing premium. The threat of renal failure accelerates IL-1 inhibitor initiation in pediatric and adult cohorts across referral networks at Boston Children's Hospital and Necker-Enfants Malades.
- Still's Disease:Systemic juvenile idiopathic arthritis with autoinflammatory features.
- Hyper-IgD Syndrome:Mevalonate kinase deficiency with periodic fever attacks.
Familial Mediterranean Fever carries patient volume; Muckle-Wells Syndrome delivers revenue intensity.
End User:
Care setting determines administration complexity and reimbursement mechanics for therapy delivery.
- Pediatric Hospitals:Academic medical centers with dedicated autoinflammatory disease centers anchor biologic induction protocols. Boston Children's Hospital, Great Ormond Street Hospital, and Necker-Enfants Malades integrate genetic testing, rheumatology, and immunology expertise to compress diagnostic timelines.
- Specialty Pharmacies:Cold-chain distribution hubs for subcutaneous biologics sustain product integrity through last-mile delivery. Swedish Orphan Biovitrum AB's rare disease infrastructure spans patient training, compliance monitoring, and adverse event reporting.
- Outpatient Clinics:Community-based settings for stable maintenance patients.
- Research Institutions:Sites for gene therapy and novel mechanism clinical trials.
Patient volume flows through pediatric hospitals; specialty pharmacies are gaining share fastest in subcutaneous maintenance.
Delivery Mode:
Route of administration shapes care setting economics and patient compliance profiles.
- Subcutaneous:Auto-injector devices for anakinra and canakinumab enable home-based administration. Pediatric patients and caregivers in the United States and Western Europe adopt these devices at accelerating rates, reducing hospital capacity utilization while shifting monitoring burden to remote nursing infrastructure.
- Intravenous:Hospital-based infusion suites dominate acute flare management and biologic induction. IV canakinumab every eight weeks suits patients with adherence challenges or needle phobia.
- Oral:Colchicine tablets sustain daily prophylaxis for Familial Mediterranean Fever.
- Inhalation:Investigational routes for localized autoinflammatory manifestations.
Subcutaneous holds volume leadership; intravenous retains acute episode capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Referral networks for rare fever disorders concentrate diagnostic capacity in the United States, where specialized autoinflammatory disease centers anchor biologic therapy adoption. Patient identification rates vary sharply across Mediterranean basin populations based on genetic testing infrastructure maturity.
United States
Pediatric hospitals in Boston and New York anchor the largest referral networks for cryopyrin-associated periodic syndromes. The FDA's orphan drug designation pathway compresses clinical trial timelines for canakinumab candidates. Boston Children's Hospital integrates genetic testing with rheumatology expertise to compress diagnostic timelines for Muckle-Wells Syndrome.
Turkey
Founder MEFV mutations sustain the world's largest Familial Mediterranean Fever patient pool. The country's national pharmaceutical regulator maintains export controls on colchicine API derived from indigenous Colchicum autumnale harvests. Istanbul and Ankara concentrate genetic testing capacity while regional hospitals expand biologic access programs for colchicine-resistant cases.
France
Necker-Enfants Malades in Paris anchors EU pediatric autoinflammatory research and treatment protocols. The EMA's Committee for Orphan Medicinal Products coordinates centralized pediatric investigation plans that harmonize clinical data requirements. The Île-de-France region concentrates both diagnostic expertise and cold-chain distribution infrastructure for subcutaneous biologics.
Israel
High-frequency MEFV mutations among specific populations sustain concentrated Familial Mediterranean Fever prevalence. Sheba Medical Center and Hadassah Medical Center integrate genetic screening with rheumatology services. Tel Aviv's specialty pharmacy networks sustain cold-chain integrity for anakinra distribution to maintenance patients.
Italy
Sicily and Calabria retain elevated Familial Mediterranean Fever prevalence due to historical founder effects. The national pharmaceutical regulator monitors colchicine API supply security from domestic autumn crocus cultivation. Rome and Milan concentrate pediatric rheumatology expertise while regional hospitals address diagnostic gaps in southern provinces.
Periodic Fever Syndrome Market Vendor Landscape
Strategic partnerships dominate the current landscape as biologic manufacturers secure cold-chain distribution capabilities and pediatric hospital contracting relationships. The market structure concentrates value capture among three tiers: multinational pharmaceutical conglomerates with captive biologic manufacturing, rare disease specialists with dedicated distribution infrastructure, and generic API suppliers serving colchicine prophylaxis demand. Dominant competitive moves include vertical integration into temperature-controlled logistics and portfolio diversification into gene therapy candidates targeting NLRP3 and MEFV mutations.
Within the rare disease specialist tier, Swedish Orphan Biovitrum AB exemplifies distribution-centric positioning through cold-chain logistics capabilities. Among multinational biologic developers, Novartis AG occupies a central position in IL-1 pathway inhibition. Pfizer Inc. represents the inflammation franchise extension archetype, applying R&D intensity toward next-generation autoinflammatory indications. These three entities collectively illustrate how competitive positioning bifurcates between manufacturing scale and specialized distribution infrastructure.
| Leading Market Players |
|---|
| Amgen Inc. |
| Pfizer Inc. |
| Novartis AG |
| Hikma Pharmaceuticals |
| Takeda Pharmaceutical Company Limited |
| Regeneron Pharmaceuticals Inc. |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Swedish Orphan Biovitrum AB |
| Others |
Supply Flow & Price Mechanics
Captive manufacturing of canakinumab by Novartis AG anchors both supply security and premium pricing power for IL-1β inhibitors, while colchicine API dependence on Italian and Turkish autumn crocus harvests constrains generic pricing flexibility through supply fragility.
Pricing Analysis
Service bundling separates hospital-based infusion protocols from home-based subcutaneous delivery, with canakinumab commanding premium positioning through cold-chain integrity guarantees and patient training programs while colchicine competes on unbundled commodity pricing. Price differentiation rests on amyloidosis risk stratification and pediatric indication breadth, with Muckle-Wells Syndrome patients showing lowest sensitivity due to urgency of renal protection. Cost compression in colchicine prophylaxis intensifies as multi-source qualification programs expand, though API harvest variability limits downward flexibility.
Supply Chain Analysis
FDA and EMA cold-chain certification requirements gate entry for subcutaneous biologic distribution, with only Swedish Orphan Biovitrum AB and select hospital networks qualifying for last-mile temperature integrity. API production draws from Italian and Turkish Colchicum autumnale cultivation for colchicine, while recombinant protein manufacturing centers on Swiss and German biologics facilities. Single-source vulnerability in autumn crocus harvests exposes formulation networks to export restriction risk. Distribution runs through pediatric hospital pharmacies and specialty pharmacy hubs for biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologic manufacturing capacity constraints prop pricing power for IL-1 pathway inhibitors, as sterile fill-finish capacity shortages and cold-chain qualification bottlenecks limit rapid supply expansion despite accelerating demand.
For Market Incumbents: Cement hospital contracting relationships through dedicated autoinflammatory disease center partnerships at Boston Children's Hospital and Necker-Enfants Malades, while securing backward integration into fill-finish capacity to defend against anakinra biosimilar entrants. Gene therapy candidates targeting NLRP3 mutations represent the priority R&D hedge against cytokine suppression commoditization. For New Entrants and Emerging Players: Begin with undiagnosed Familial Mediterranean Fever cohorts in Algeria, Tunisia, and Egypt where genetic testing infrastructure gaps create addressable patient expansion before competing in saturated Western referral networks. Mobile diagnostic units partnered with regional hospitals offer the most penetrable go-to-market angle for market development. For Investors and Strategic Acquirers: Exit pathways concentrate in rare disease distribution infrastructure acquisitions, with cold-chain logistics capabilities and pediatric hospital relationships commanding scarcity premiums. Long-term viability hinges on gene therapy convergence timelines; the signal to watch is CRISPR-based candidate progression through early-phase trials for MEFV mutations.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA centralized pediatric investigation plans compress EU approval timelines for cryopyrinopathy indications. |
| Manufacturing Scale-Up | Captive fill-finish capacity at Novartis AG insulates against sterile production bottlenecks affecting biosimilar entrants. |
| Regulatory Approval Pathway | Health Canada Special Access Programme creates early revenue streams for undifferentiated periodic fever presentations. |
| Pipeline Diversification | Gene therapy candidates targeting NLRP3 mutations hedge against IL-1 inhibitor commoditization. |
| Strategic Partnership | Hospital system partnerships at Great Ormond Street Hospital lock in preferred prescriber relationships for biologic selection. |
Methodological Framework
Document review covered FDA orphan drug designations, EMA Committee for Orphan Medicinal Products submissions, and ClinicalTrials.gov protocols, complemented by interviews with drug development executives at biologic manufacturers, regulatory affairs leads, hospital procurement managers at pediatric autoinflammatory centers, and payer access specialists. Secondary validation drew from formulary databases, SEC 10-K filings, and national pharmaceutical regulator export control records. Bottom-up patient population estimates triangulated against top-down therapy area revenue allocations.
Historical prescription volume trajectories cross-referenced against expert panel inputs on biologic adoption curves and colchicine resistance rates. Segmentation modeling spanned product type, therapy area, end user, and delivery mode dimensions across the projection horizon. CAGRs derived from weighted average of epidemiological growth, pricing elasticity estimates, and therapy shift assumptions. Forecast inputs incorporated MEFV mutation prevalence surveys and pediatric hospital expansion pipelines.
Underlying measurement precision varies by segment; canakinumab revenue estimates carry tighter precision than colchicine volume projections due to captive manufacturing transparency. Forecasts reflect assumptions on biosimilar entry timing, gene therapy clinical progression, and regulatory pathway harmonization. A model refresh is warranted upon material change in EMA centralized pediatric investigation plan requirements or Health Canada Special Access Programme eligibility criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Brucellosis Market
Infectious Disease
Global Infectious Disease Drugs Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Infectious Disease Treatments Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Bronchitis Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Global Infectious Disease Therapeutics Market
Infectious Disease
Measles Market
Infectious Disease
Valley Fever Market
Infectious Disease
Vaccine Management Solution Market