
 Viral Gastroenteritis Market | 2026-2036
Viral Gastroenteritis Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Gastroenteritis Market Outlook
The manufacturing-capability gap between large vaccine producers and diagnostic specialists is collapsing as platform technologies standardize production workflows. Pfizer Inc. leverages its mRNA infrastructure to accelerate enteric pathogen vaccine candidates. Takeda Pharmaceutical Company Limited anchors its position through live-attenuated rotavirus vaccine supply agreements across emerging markets. GSK plc differentiates via heat-stable formulation research that reduces cold-chain dependency in tropical climates.
Viral gastroenteritis encompasses acute inflammation of the stomach and intestinal mucosa caused by norovirus, rotavirus, adenovirus, and astrovirus, typically transmitted through fecal-oral routes with incubation periods ranging from 12 to 48 hours and characterized by vomiting, diarrhea, and dehydration requiring oral or intravenous fluid replacement. The condition drives substantial healthcare utilization through emergency department visits and hospitalization for severe dehydration, particularly among children under five and immunocompromised adults. Vaccines command the largest revenue share within product type segments due to national immunization program procurement at volume-committed prices. Diagnostic Kits represent the fastest-expanding category as multiplex PCR panels replace single-pathogen enzyme immunoassays in hospital laboratories. Hydration Solutions maintain stable margins through over-the-counter retail pharmacy dominance despite minimal product differentiation.
FDA biologics licensing requirements and WHO prequalification standards shape market access for rotavirus vaccines in low-income countries, while EMA pediatric investigation plans influence European development timelines for novel antiviral therapies. National regulatory authorities in India and China enforce localized clinical trial data requirements that extend approval timelines for multinational manufacturers. Stakeholders must monitor how decentralized manufacturing investments in Africa and Southeast Asia reshape procurement patterns and intellectual property licensing negotiations.
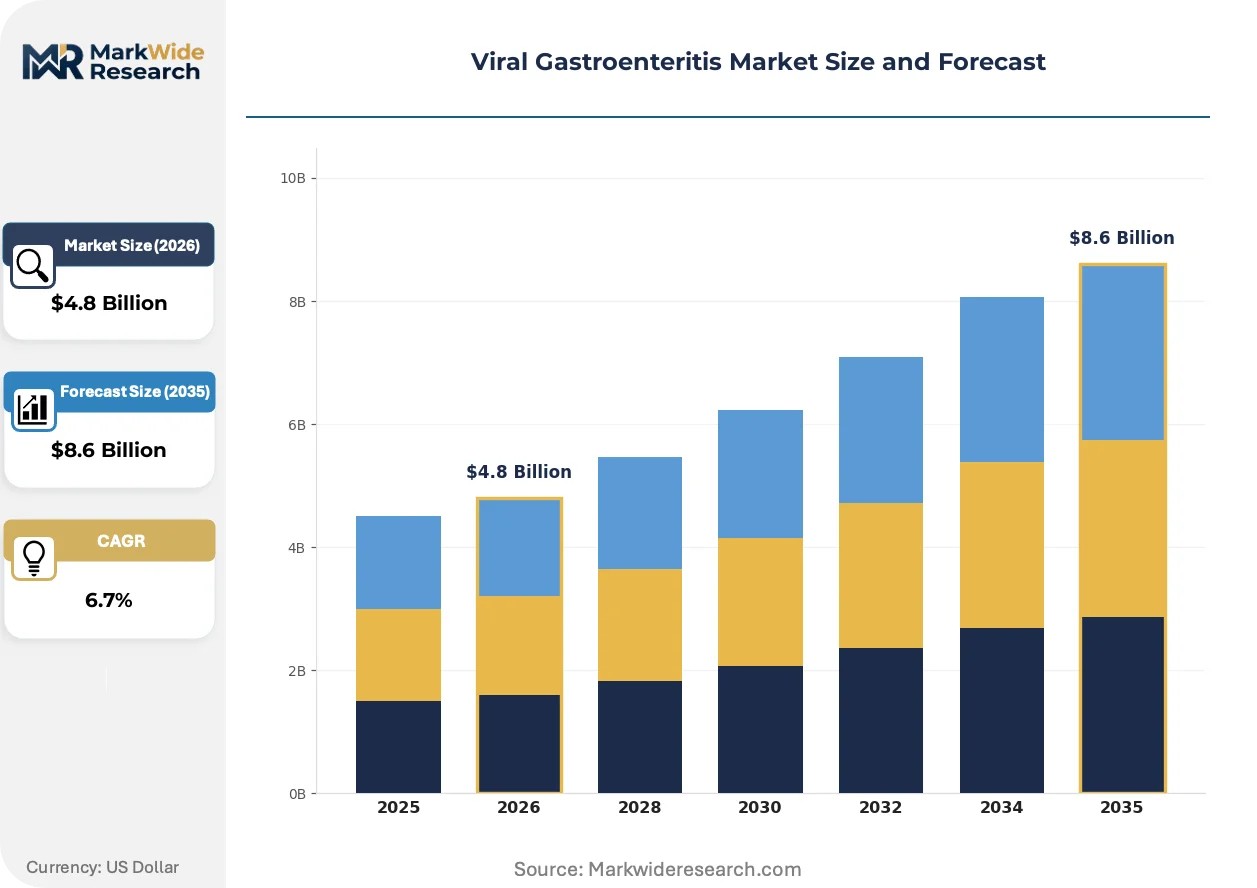
Market Dynamics
Platform technology standardization is collapsing the manufacturing-capability gap between large vaccine producers and diagnostic specialists, redrawing competitive boundaries across the viral gastroenteritis value chain.
Growth Catalysts
- Rotavirus immunization mandates:Brazil, India, and Nigeria are expanding pediatric vaccination programs through national immunization schedules. WHO prequalification pathways accelerate manufacturer entry into low-income procurement systems.
- Multiplex PCR adoption:Hospital laboratories are replacing single-pathogen enzyme immunoassays with syndromic panels. This technology convergence compresses diagnostic turnaround times and raises testing throughput.
- Sub-Saharan Africa disease burden:Sanitation infrastructure gaps sustain high transmission rates. Demand concentrates in regions where oral rehydration and vaccine access remain priority health interventions.
Market Restraints
- Cold-chain dependency:Heat-labile formulations limit rotavirus vaccine distribution to tropical climates. GSK plc and other manufacturers face formulation R&D costs to address this technical limitation.
- Regulatory fragmentation:India's CDSCO and China's NMPA enforce localized clinical trial data requirements. Multinational manufacturers encounter extended approval timelines and redundant study costs.
- Diagnostic commoditization:Hydration Solutions face minimal product differentiation in over-the-counter retail pharmacy channels. Margin compression limits reinvestment capacity for formulation innovation.
Strategic Opportunities
- Decentralized manufacturing:Investments in African and Southeast Asian production facilities reshape procurement patterns. Localized supply reduces cold-chain logistics costs and intellectual property licensing friction.
- Heat-stable formulation R&D:Reduced cold-chain dependency opens tropical climate markets currently underserved by existing rotavirus vaccines. EMA pediatric investigation plans influence European development timelines for novel candidates.
- Multiplex panel expansion:Syndromic testing platforms enable norovirus, adenovirus, and astrovirus detection alongside rotavirus. Hospital laboratory budgets are consolidating spend around integrated diagnostic workflows.
Industry Challenges
- Biologics licensing complexity:FDA requirements and WHO prequalification standards demand parallel dossier preparation. Regulatory affairs teams face timeline coordination across multiple approval pathways.
- mRNA platform adaptation:Enteric pathogen vaccine development requires gastrointestinal mucosal immunity expertise. Pfizer Inc. and other platform technology adopters must build specialized formulation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Gastroenteritis Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Diagnostic Kits, Antiviral Medications, Hydration Solutions End User: Pediatric Units, Emergency Departments, Outpatient Clinics, Home Care Distribution Channel: Pharmacies, Hospitals, Online Platforms, Clinics Application: Preventive Care, Therapeutic Treatment, Laboratory Testing, Home Rehabilitation |
| Companies Covered | Pfizer Inc., Takeda Pharmaceutical Company Limited, GSK plc, Sanofi, Abbott, Bayer AG, Merck & Co., Inc., AstraZeneca, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Gastroenteritis Market Strategic Shifts
Diagnostic technology convergence and regulatory pathway evolution are compressing product development cycles while fragmenting procurement authority across public health systems and private laboratory networks.
Multiplex PCR panels are miniaturizing enteric pathogen detection into single-cartridge formats. Reference laboratories and hospital systems are adopting these platforms to replace batch-processed immunoassays. This consolidation is miniaturizing capital equipment footprints and reducing per-test labor requirements in high-throughput settings.
WHO prequalification standards are reshaping how rotavirus vaccine manufacturers enter low-income country markets. The pathway requires stability data and manufacturing inspection protocols that diverge from FDA biologics licensing requirements. African national regulatory authorities are aligning procurement decisions around prequalified supplier lists, compressing competitive access for non-prequalified candidates.
Public health procurement is consolidating volume-committed pricing through national immunization program tenders. UNICEF and Gavi alliance purchasing pools aggregate demand from multiple countries, displacing fragmented national procurement offices. This concentration is most visible in sub-Saharan Africa and South Asia, where budget predictability enables multi-year supply agreements with extended price lock provisions.
Viral Gastroenteritis Market Segmentation
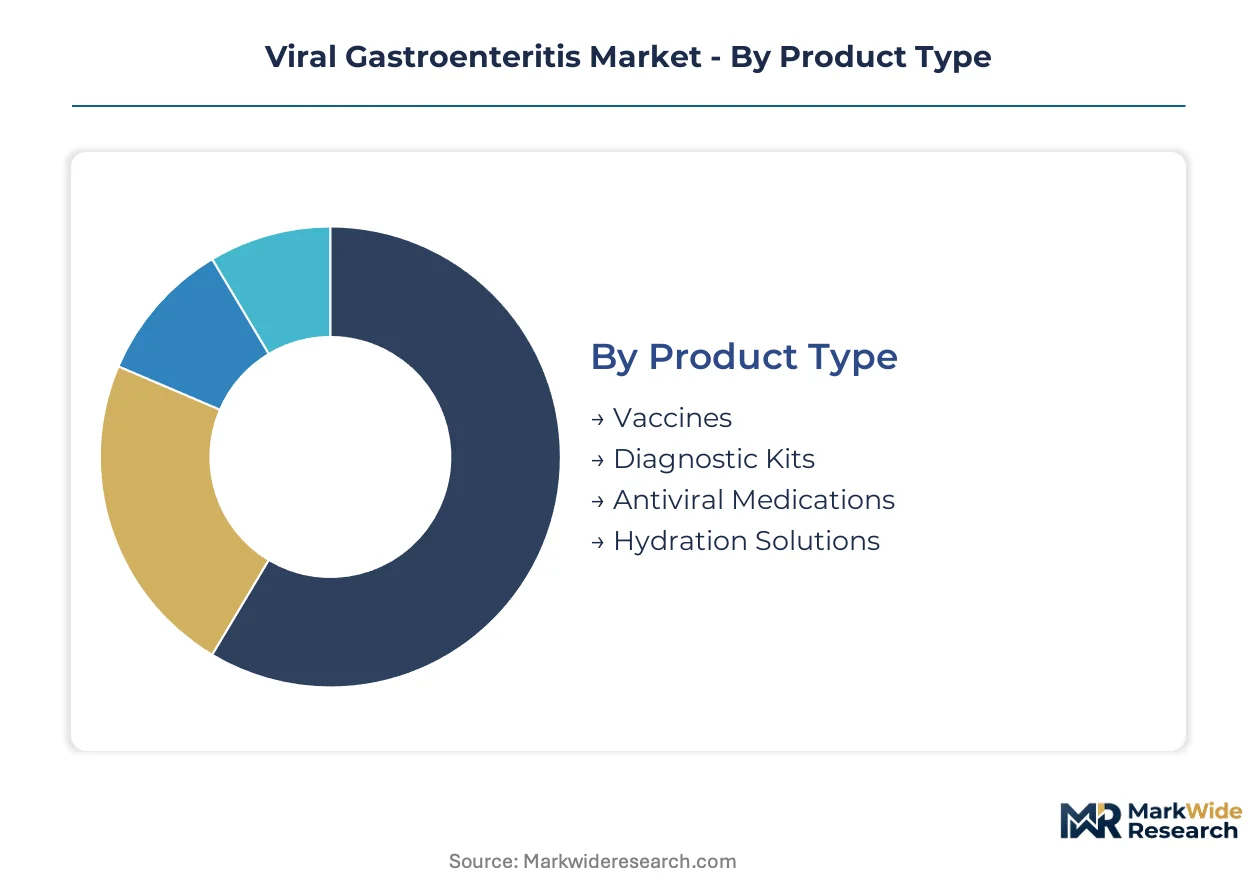
Segmentation in viral gastroenteritis reflects divergent regulatory pathways across product categories. Vaccines face WHO prequalification and FDA biologics licensing, while diagnostic kits navigate CE marking and laboratory certification standards. Understanding these structural divisions clarifies where procurement authority concentrates and how margin profiles differ across the value chain.
Product Type:
FDA biologics licensing requirements and WHO prequalification standards create divergent market access conditions across product categories, with heat-stability specifications and cold-chain protocols determining geographic reach.
- Vaccines:Live-attenuated and inactivated formulations targeting rotavirus dominate procurement through national immunization programs. Demand concentrates in Brazil, India, and Nigeria where pediatric vaccination schedules mandate coverage, though cold-chain dependency limits tropical distribution without heat-stable alternatives.
- Diagnostic Kits:Multiplex PCR panels and rapid antigen tests enable simultaneous detection of norovirus, rotavirus, adenovirus, and astrovirus. Hospital laboratories in sub-Saharan Africa and South Asia are consolidating testing workflows around syndromic panels that compress turnaround times.
- Antiviral Medications:Limited approved options exist for direct viral targeting; supportive care protocols dominate clinical practice.
- Hydration Solutions:Oral rehydration salts and intravenous fluids maintain stable retail pharmacy margins despite minimal product differentiation.
Vaccines handle the majority of throughput; Diagnostic Kits is the fastest mover on share.
End User:
Pediatric Units absorb the highest acuity caseloads, while cost tier differentiation separates institutional procurement from retail-accessible care settings.
- Pediatric Units:Specialized wards manage severe dehydration requiring intravenous fluid replacement in children under five. Rotavirus immunization programs in Brazil and Nigeria are reducing admission volumes, though baseline disease burden remains substantial in sanitation-deficient regions.
- Emergency Departments:Triage protocols for acute vomiting and diarrhea drive diagnostic testing demand. Syndromic PCR panels are replacing single-pathogen enzyme immunoassays in high-throughput hospital laboratories.
- Outpatient Clinics:Primary care settings manage moderate cases with oral rehydration and symptomatic treatment.
- Home Care:Over-the-counter hydration solutions and rapid diagnostic tests enable self-managed recovery outside institutional settings.
Pediatric Units command the highest per-case resource intensity; Home Care is climbing the fastest as self-testing and retail pharmacy access expand.
Distribution Channel:
Procurement patterns fragment between volume-committed public health tenders and fragmented retail pharmacy networks, with cold-chain logistics determining channel viability for temperature-sensitive products.
- Pharmacies:Retail and hospital-based dispensaries dominate hydration solution and rapid test distribution. Over-the-counter oral rehydration salts reach consumers directly in urban centers across India and Brazil.
- Hospitals:Central procurement offices aggregate demand for multiplex diagnostic platforms and intravenous fluids. Gavi alliance purchasing pools consolidate vaccine procurement for low-income countries through UNICEF supply channels.
- Online Platforms:Direct-to-consumer channels for rapid diagnostic tests are expanding in markets with established e-pharmacy regulation.
- Clinics:Primary care networks serve as vaccination access points in rural areas with limited hospital infrastructure.
Hospitals manage the largest contract values; Online Platforms are gaining share fastest as regulatory frameworks for digital pharmacy sales mature.
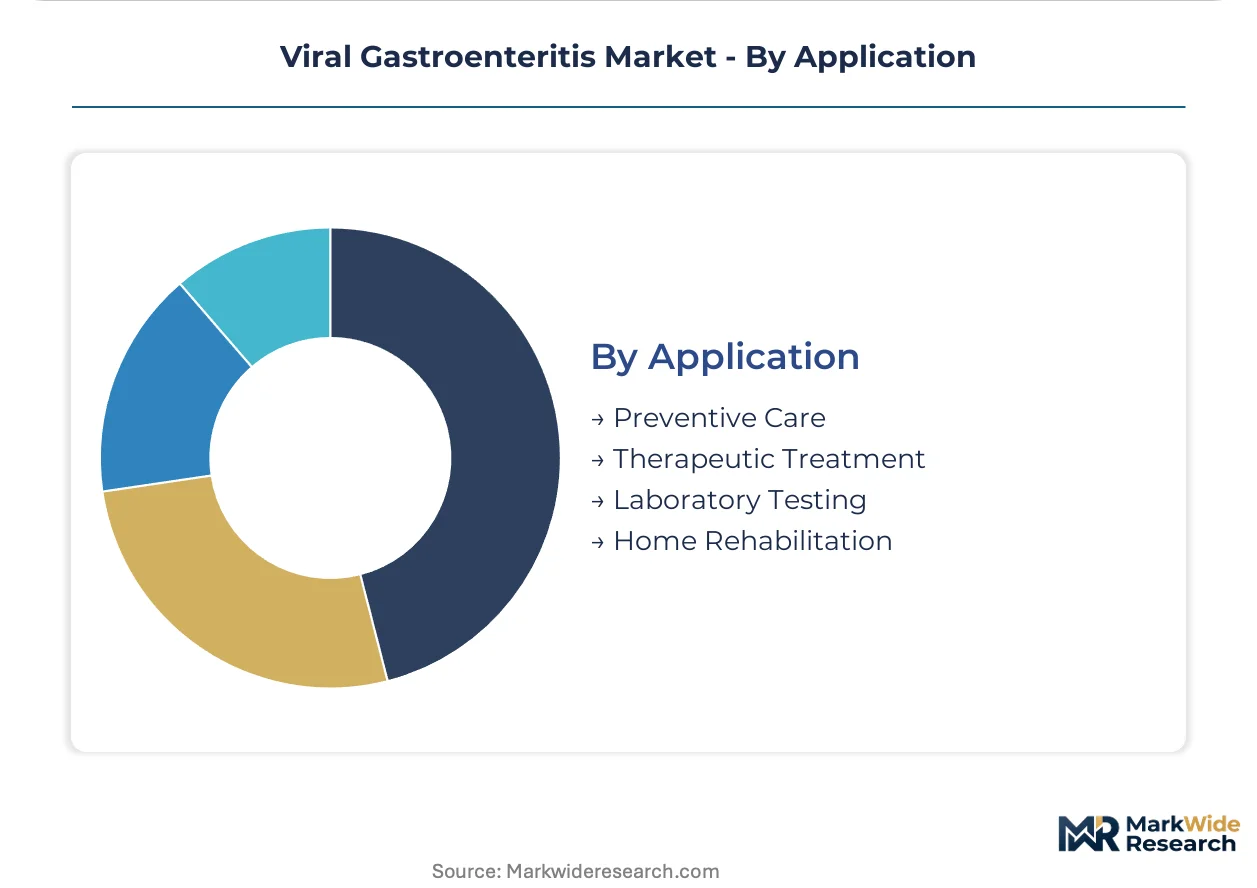
Application:
Application scope spans the prevention-treatment-recovery continuum, with regulatory oversight intensifying at the therapeutic intervention end of the spectrum.
- Preventive Care:Rotavirus vaccination programs anchor national immunization schedules in Brazil, India, and Nigeria. WHO prequalification pathways determine manufacturer eligibility for Gavi-subsidized procurement pools.
- Therapeutic Treatment:Fluid replacement protocols and symptomatic management address acute dehydration. Emergency departments prioritize intravenous access for severe cases presenting with hemodynamic compromise.
- Laboratory Testing:Multiplex PCR panels enable pathogen-specific diagnosis to guide infection control and outbreak response.
- Home Rehabilitation:Oral rehydration and gradual diet advancement complete recovery outside clinical settings.
Preventive Care captures the largest program budgets; Laboratory Testing shows the steepest expansion trajectory as syndromic panels displace legacy immunoassays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for rotavirus vaccines shapes procurement strategies across high-burden markets, while diagnostic kit exports concentrate in manufacturing hubs with established PCR platform capabilities. Brazil, India, and Nigeria anchor vaccine demand through national immunization programs. WHO prequalification pathways determine supplier eligibility for Gavi-subsidized procurement pools.
Brazil
Rotavirus immunization mandates drive pediatric vaccination coverage through the national immunization schedule. ANVISA enforces localized clinical trial data requirements for novel vaccine candidates. São Paulo anchors vaccine distribution logistics, with cold-chain infrastructure investments expanding into the Amazon region.
India
Domestic manufacturing capacity for oral rehydration salts and rapid diagnostic tests supplies regional export markets. CDSCO mandates localized stability studies for heat-stable vaccine formulations under tropical climate conditions. Hyderabad and Pune cluster pharmaceutical production, with contract research organizations supporting multinational clinical trials.
Nigeria
Sanitation infrastructure gaps sustain high rotavirus transmission rates among children under five. The national primary healthcare development agency coordinates Gavi-funded vaccine procurement through UNICEF supply channels. Lagos and Kano concentrate diagnostic testing capacity, with reference laboratories adopting syndromic PCR panels.
United States
Multiplex PCR panel adoption in hospital laboratories displaces single-pathogen enzyme immunoassays. FDA biologics licensing requirements shape rotavirus vaccine development timelines through pediatric investigation plans. Boston and San Diego anchor biotechnology R&D clusters, with mRNA platform specialists targeting enteric pathogen candidates.
Germany
Diagnostic platform manufacturers supply multiplex testing systems to European and African reference laboratories. EMA pediatric investigation plans influence European development timelines for novel antiviral therapies. Munich and Heidelberg concentrate molecular diagnostics engineering, with heat-stable formulation research addressing tropical distribution challenges.
Viral Gastroenteritis Market Competitive Environment
Concentration sits with multinational vaccine producers and diagnostic platform specialists, with procurement authority fragmenting across national immunization programs and hospital laboratory networks. Large pharmaceutical conglomerates anchor rotavirus vaccine supply through WHO-prequalified manufacturing networks. Diagnostic specialists compete on multiplex panel throughput and syndromic detection capabilities. Strategic moves center on heat-stable formulation R&D and decentralized manufacturing investments in high-burden regions.
Within the multinational pharmaceutical tier, Pfizer Inc., Takeda Pharmaceutical Company Limited, and GSK plc exemplify divergent platform strategies. Pfizer represents mRNA infrastructure adaptation for enteric pathogen candidates. Takeda occupies a position anchored through live-attenuated rotavirus vaccine supply agreements across emerging markets. GSK sits within the formulation innovation archetype, with research programs targeting reduced cold-chain dependency. These three entities collectively illustrate how platform technology choices and geographic focus differentiate competitive positioning in procurement systems shaped by WHO prequalification and national immunization program tenders.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Takeda Pharmaceutical Company Limited |
| GSK plc |
| Sanofi |
| Abbott |
| Bayer AG |
| Merck & Co., Inc. |
| AstraZeneca |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Ninety-day stability validation windows for heat-sensitive rotavirus formulations compress procurement timelines while amplifying price premiums for cold-chain-compliant suppliers across tropical distribution corridors. This lead-time rigidity concentrates pricing power with WHO-prequalified manufacturers possessing validated tropical stability dossiers, forcing buyers into volume-committed tenders with extended price lock provisions.
Pricing Analysis
The customization-premium spread between standard cold-chain formulations and heat-stable configured-to-order vaccines reaches substantial multiples in sub-Saharan procurement pools. Pricing stratifies across premium heat-stable tiers, standard cold-chain dependent formulations, and economy bulk oral rehydration salts with minimal differentiation. Cost compression in diagnostic kits is intensifying as multiplex PCR platforms commoditize single-pathogen enzyme immunoassays. National immunization programs exhibit lowest price sensitivity due to Gavi-subsidized procurement, while retail pharmacy hydration solutions face highest sensitivity from undifferentiated over-the-counter competition.
Supply Chain Analysis
Cold-chain logistics chokepoints at last-mile distribution nodes in Nigeria, India, and Brazil determine vaccine availability more than manufacturing capacity. Active pharmaceutical ingredients for oral rehydration salts draw from domestic Indian and Chinese chemical synthesis clusters, while multiplex PCR reagents rest on German and US precision manufacturing. Single-source vulnerability concentrates in temperature-controlled freight forwarding specialized for biologics. Distribution runs through UNICEF supply channels consolidating Gavi-funded procurement alongside fragmented national tender systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The viral gastroenteritis market is recovering from pandemic-era immunization program disruptions as national schedules in Brazil, India, and Nigeria restore coverage targets. This cyclical rebound is anchored by Gavi alliance replenishment cycles reopening multi-year vaccine procurement windows.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into African fill-finish capacity, securing WHO prequalification ahead of competitor dossier submissions. Defend position against mRNA platform entrants by accelerating heat-stable formulation R&D through EMA pediatric investigation pathways. Prioritize vertical control over regional distribution partnerships in sanitation-deficient high-burden corridors. For New Entrants and Emerging Players: WHO prequalification fast-track via stability data partnerships with established reference laboratories offers the most penetrable entry vector. Target diagnostic kit white space in Nigerian and Indian reference laboratory networks adopting syndromic PCR panels. Pursue go-to-market positioning around norovirus-astrovirus multiplex detection absent from incumbent rotavirus-focused portfolios. For Investors and Strategic Acquirers: Carve-out targets emerge from large pharmaceutical conglomerates divesting legacy vaccine franchises amid platform technology pivots. Long-term viability over the coming decade rests on heat-stable formulation capabilities and decentralized manufacturing footprints. Watch Gavi pledge conference outcomes as the decisive inflection signal for procurement volume trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Stable Formulation R&D | GSK plc and competitors address cold-chain dependency opening tropical climate markets currently underserved. |
| Decentralized African Manufacturing | Regional fill-finish investments reduce logistics costs and intellectual property licensing friction in procurement. |
| Multiplex PCR Platform Expansion | Syndromic panels enable norovirus, adenovirus, and astrovirus detection consolidating hospital laboratory budgets. |
| WHO Prequalification Pathway Acceleration | Prequalified supplier lists compress competitive access for non-prequalified candidates in Gavi-subsidized pools. |
| mRNA Platform Adaptation | Pfizer Inc. leverages existing infrastructure for enteric pathogen candidates requiring mucosal immunity expertise. |
Study Parameters
The analysis maps vaccine formulations, diagnostic platforms, and hydration solutions, each validated through procurement officers at national immunization programs, regulatory affairs specialists at WHO-prequalified manufacturers, hospital laboratory directors adopting multiplex panels, and Gavi alliance supply chain planners. Secondary sources include FDA biologics licensing databases, WHO prequalification inspection reports, CDSCO stability study filings, and UNICEF supply tender documentation. Bottom-up demand modeling triangulates against top-down procurement spend aggregation.
Consistency checks validated volume and value outputs against Gavi disbursement records, national immunization program budget allocations, and diagnostic platform installation bases across reference laboratory networks. The analytical framework segments by product type, end user acuity tier, distribution channel structure, and regional regulatory cluster across the projection horizon. CAGRs derive from procurement pipeline visibility and tender award trajectories, with specific inputs including rotavirus immunization schedule expansion timelines and multiplex PCR replacement rates for legacy immunoassays.
Decision-makers should treat outputs as directional under assumptions of sustained Gavi funding commitments and stable WHO prequalification standards; material deviation would warrant model refresh. Forecasts reflect documented procurement patterns and regulatory pathway timelines. Practitioners should keep alternative scenarios live as heat-stable formulation breakthroughs and mRNA platform clinical readouts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Actinomycosis Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Measles Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Periodic Fever Syndrome Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Efavirenz Market
Infectious Disease
Norovirus Infection Treatment Market