
 Communicable Diseases Treatment Market | 2026-2036
Communicable Diseases Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Communicable Diseases Treatment Market Outlook
Hospital procurement of antiviral and vaccine portfolios is consolidating as health systems prioritize formulary standardization and pandemic preparedness. Pfizer Inc. leverages its mRNA manufacturing infrastructure to sustain supply commitments across multiple therapeutic areas. GlaxoSmithKline plc anchors its position through vaccine specialization in respiratory and tropical disease franchises. Novartis AG competes via differentiated access programs that navigate pricing pressures in emerging markets.
Communicable diseases treatment encompasses pharmaceutical and biologic interventions designed to prevent, suppress, or eradicate pathogenic infections in human populations, including small-molecule drugs, recombinant proteins, and nucleic acid-based therapeutics formulated to specific potency, purity, and stability parameters. The category serves essential public health functions by reducing transmission rates, preventing severe outcomes, and limiting antimicrobial resistance propagation. Antibiotics and antivirals command the largest revenue share within product type segmentation, though vaccines generate superior margins through long-term immunization contracts and institutional purchasing agreements. Injectable delivery dominates hospital and clinic settings where bioavailability and rapid onset prove clinically critical, while oral formulations expand access in home care and outpatient disease management protocols.
FDA, EMA, and WHO prequalification standards shape clinical trial design, manufacturing compliance, and market access pathways for communicable disease therapeutics, with accelerated review mechanisms contingent upon unmet medical need designations. National regulators in India and China enforce local bioequivalence and cGMP requirements that filter import eligibility and domestic production licensing. Stakeholders must monitor evolving resistance surveillance data and regulatory harmonization initiatives to align pipeline investments with reimbursable therapeutic categories.
Market Dynamics
Antimicrobial resistance surveillance protocols are compressing development timelines and forcing hospital procurement consolidation across therapeutic portfolios, reshaping how manufacturers align pipeline investments with reimbursable categories.
Growth Catalysts
- WHO Prequalification Pathways:Accelerated review mechanisms for unmet medical need designations compress regulatory timelines for priority therapeutics targeting resistant pathogen strains.
- mRNA Manufacturing Infrastructure:Platform standardization across nucleic acid production lines enables rapid pivoting between vaccine candidates during outbreak response scenarios.
- India CDSCO Localization Mandates:Domestic bioequivalence requirements and cGMP enforcement filter import eligibility while scaling indigenous manufacturing capacity for essential medicines.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:China controls critical intermediate supply for broad-spectrum antibiotics, creating single-source vulnerability during export restriction episodes.
- Clinical Trial Cost Escalation:FDA antimicrobial resistance protocol amendments require larger non-inferiority margins and extended safety follow-up, inflating per-patient enrollment expenditures.
- Biologic Substitution Threat:Monoclonal antibody prophylaxis for respiratory pathogens displaces small-molecule antiviral prescriptions in high-risk patient cohorts.
Strategic Opportunities
- Sub-Saharan Africa Cold Chain Expansion:Solar-powered refrigeration networks and drone delivery corridors unlock rural immunization coverage previously excluded from institutional purchasing agreements.
- EMA Orphan Designation Convergence:Tropical disease indication incentives align with EMA priority medicines pathways, reducing fee burdens and accelerating centralized market access.
- CRISPR Diagnostic Integration:Point-of-care nucleic acid detection platforms converge with telemedicine prescribing workflows, compressing time-to-treatment initiation in decentralized care settings.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Viral vector manufacturing scale-up demands specialized cell culture expertise that outpaces graduate program output in major production hubs.
- Legacy System Interoperability:Hospital electronic health record architectures resist seamless integration with real-time resistance surveillance databases mandated by national health agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Communicable Diseases Treatment Market |
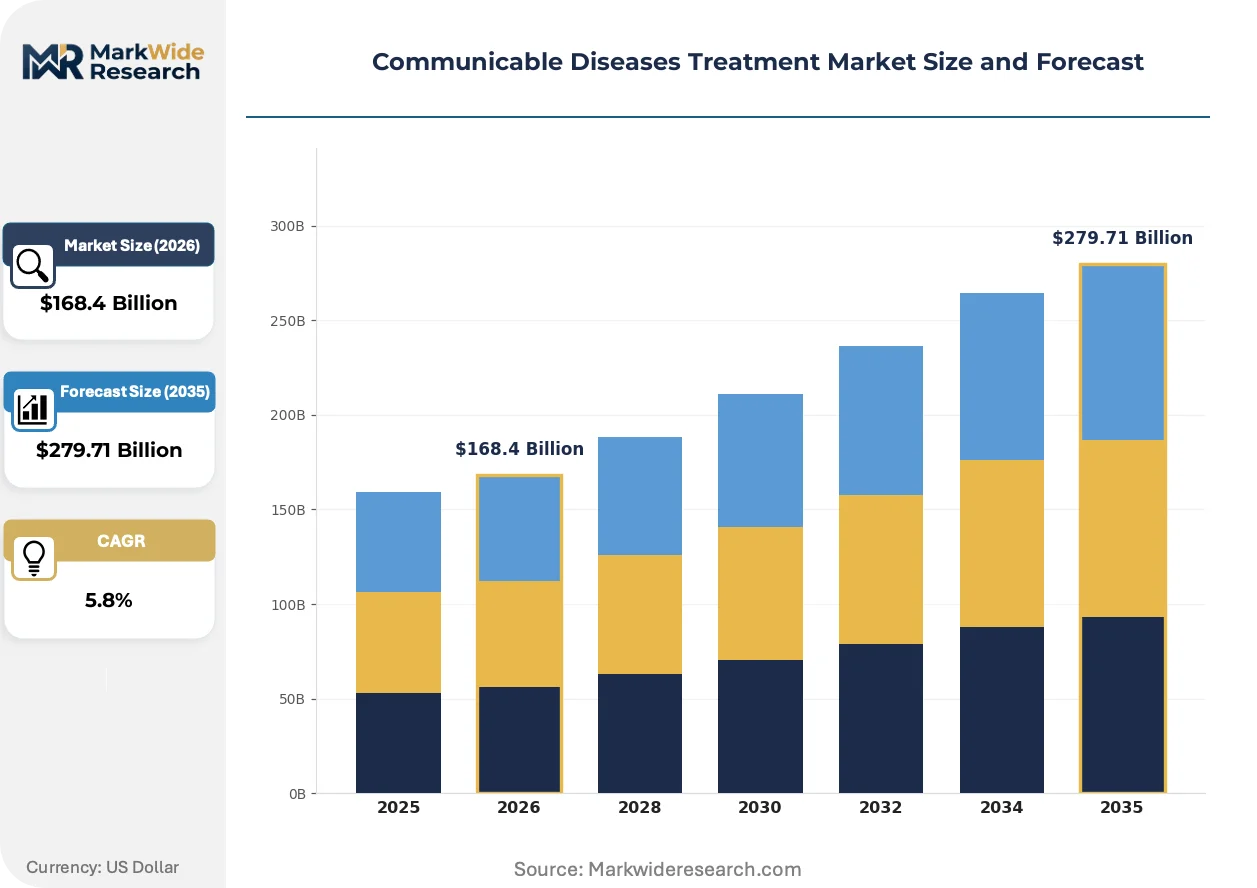
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $279.71 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antivirals, Vaccines, Antifungals Delivery Mode: Injectable, Oral, Topical, Inhalation End User: Hospitals, Clinics, Home Care, Research Labs Application: Infection Control, Symptomatic Treatment, Preventive Care, Disease Management |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Novartis AG, Merck & Co., Inc., AstraZeneca, Johnson & Johnson, Eli Lilly and Company, Sanofi, Gilead Sciences, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Communicable Diseases Treatment Market Strategic Shifts
Digital biomarker integration and distributed manufacturing networks are compressing traditional value chain structures, enabling therapeutic production closer to consumption points while surveillance data reshapes formulary decisions in real time.
Artificial intelligence-driven compound screening is automating hit-to-lead identification for novel antimicrobial scaffolds, compressing discovery timelines from years to months. Large pharmaceutical manufacturers deploy these platforms across internal pipelines and contract research partnerships simultaneously. The technology is automating target validation workflows previously bottlenecked by manual literature curation and structural biology constraints.
EMA's revised clinical trial regulation for pediatric investigation plans now mandates earlier integration of juvenile pharmacokinetic studies into adult development programs. This industrial consequence forces parallel rather than sequential trial design, elevating program complexity and cost. Vaccine developers targeting respiratory indications face the most acute timeline compression as they restructure Phase II protocols to accommodate expanded age-de-escalation requirements.
Hospital formulary committees increasingly demand outcome guarantees embedded in procurement contracts, replacing traditional volume-based purchasing with mortality and readmission performance clauses. This behavior shift disrupts long-term supply agreements that previously prioritized price stability over clinical accountability. The transformation is most visible in United States academic medical centers where CMS value-based care penalties amplify financial exposure to treatment failure costs.
Communicable Diseases Treatment Market Segmentation
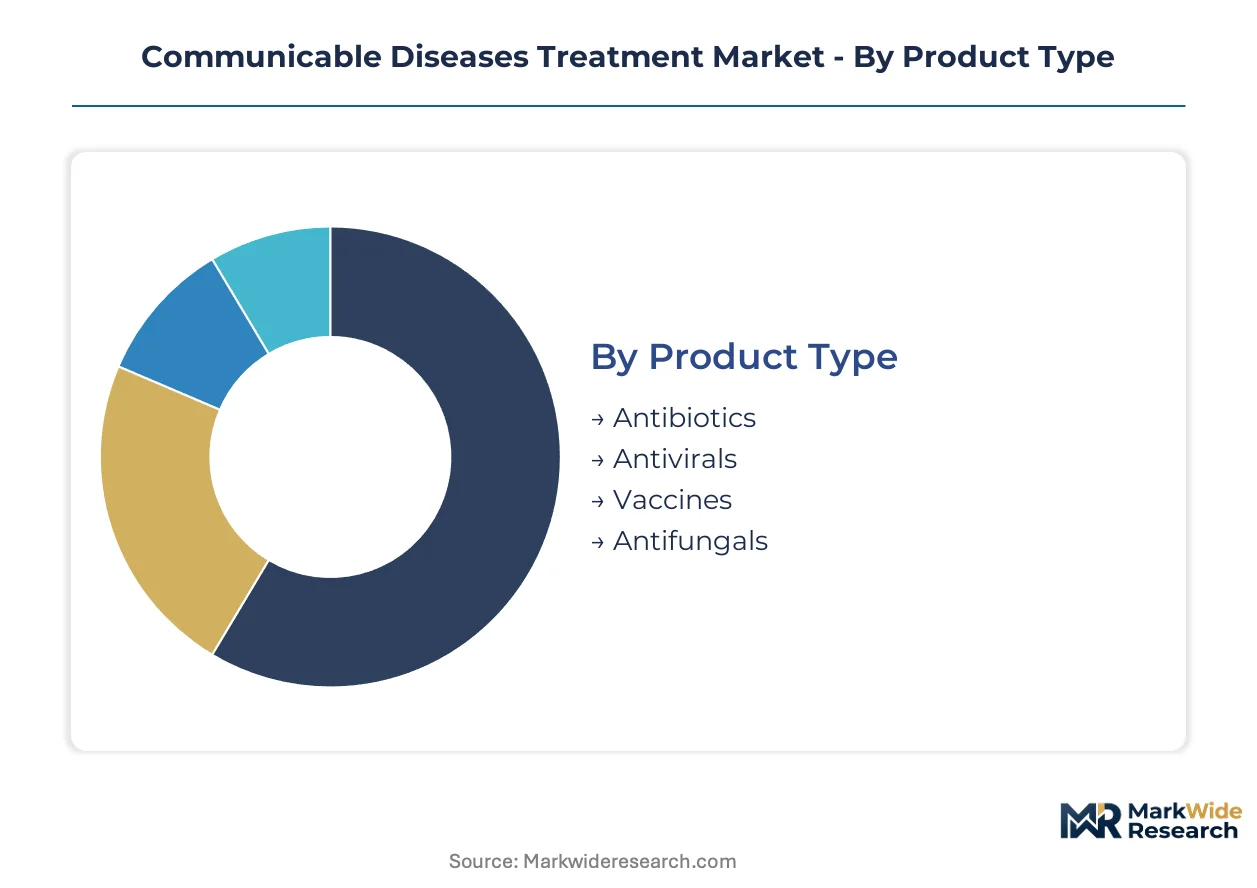
Therapeutic portfolio decisions in communicable diseases hinge on matching product specifications to care setting capabilities and patient acuity. Segmentation reveals where procurement consolidation pressures intersect with route-of-administration preferences and institutional purchasing power.
Product Type:
Replacement cycles for antimicrobial inventories accelerate as resistance surveillance updates formulary protocols and shelf-life considerations force inventory turnover.
- Antibiotics:Broad-spectrum and narrow-spectrum formulations dominate hospital procurement volumes, with carbapenem and cephalosporin classes commanding premium positioning. Demand concentrates in tertiary care centers across India and China where surgical prophylaxis protocols and sepsis management drive high-throughput consumption.
- Antivirals:Direct-acting agents and polymerase inhibitors target hepatitis C, HIV, and respiratory RNA viruses with precision mechanisms. Hepatitis C direct-acting antiviral demand clusters in United States and European specialty clinics as elimination campaigns approach completion targets.
- Vaccines:Recombinant protein and mRNA platforms generate long-term immunization contracts with superior margin profiles through institutional purchasing agreements.
- Antifungals:Azole and echinocandin classes address invasive candidiasis and aspergillosis in immunocompromised patient populations.
Volume placements concentrate in antibiotics; the faster expansion belongs to vaccines.
Delivery Mode:
Cost tier differentiation separates acute-care injectables from outpatient oral formulations, with reimbursement bandwidth determining route selection.
- Injectable:Intravenous and intramuscular formulations ensure rapid bioavailability and precise dosing in critical care scenarios. Hospital and clinic demand in Germany and Japan prioritizes IV antibiotic stewardship programs and surgical infection prophylaxis.
- Oral:Tablet and capsule formulations enable outpatient disease management and treatment completion in resource-limited settings. Home care adoption in Brazil and South Africa expands as fixed-dose combination therapies simplify adherence protocols.
- Topical:Cream, ointment, and gel preparations target localized bacterial and fungal skin infections.
- Inhalation:Nebulized and dry-powder delivery addresses respiratory viral and fungal pathogens directly at infection sites.
Procurement value clusters in injectables; oral formulations gain share fastest in decentralized care expansion.
End User:
Customer type segmentation tracks purchasing authority from centralized hospital procurement to individual patient acquisition in retail pharmacy channels.
- Hospitals:Acute care facilities and academic medical centers drive formulary standardization through antimicrobial stewardship committees. United States academic medical centers embed outcome guarantees in procurement contracts as CMS value-based penalties amplify exposure to treatment failure costs.
- Clinics:Outpatient and specialty clinics manage chronic infectious diseases and preventive immunization programs. Community health centers in Nigeria and Kenya scale rapid diagnostic integration with point-of-care prescribing workflows.
- Home Care:Self-administered therapies and visiting nurse services extend treatment access beyond institutional settings.
- Research Labs:Clinical trial sites and reference laboratories support pipeline development and resistance surveillance networks.
Contract value aggregates in hospitals; clinic networks climb the fastest as primary care capacity expands.
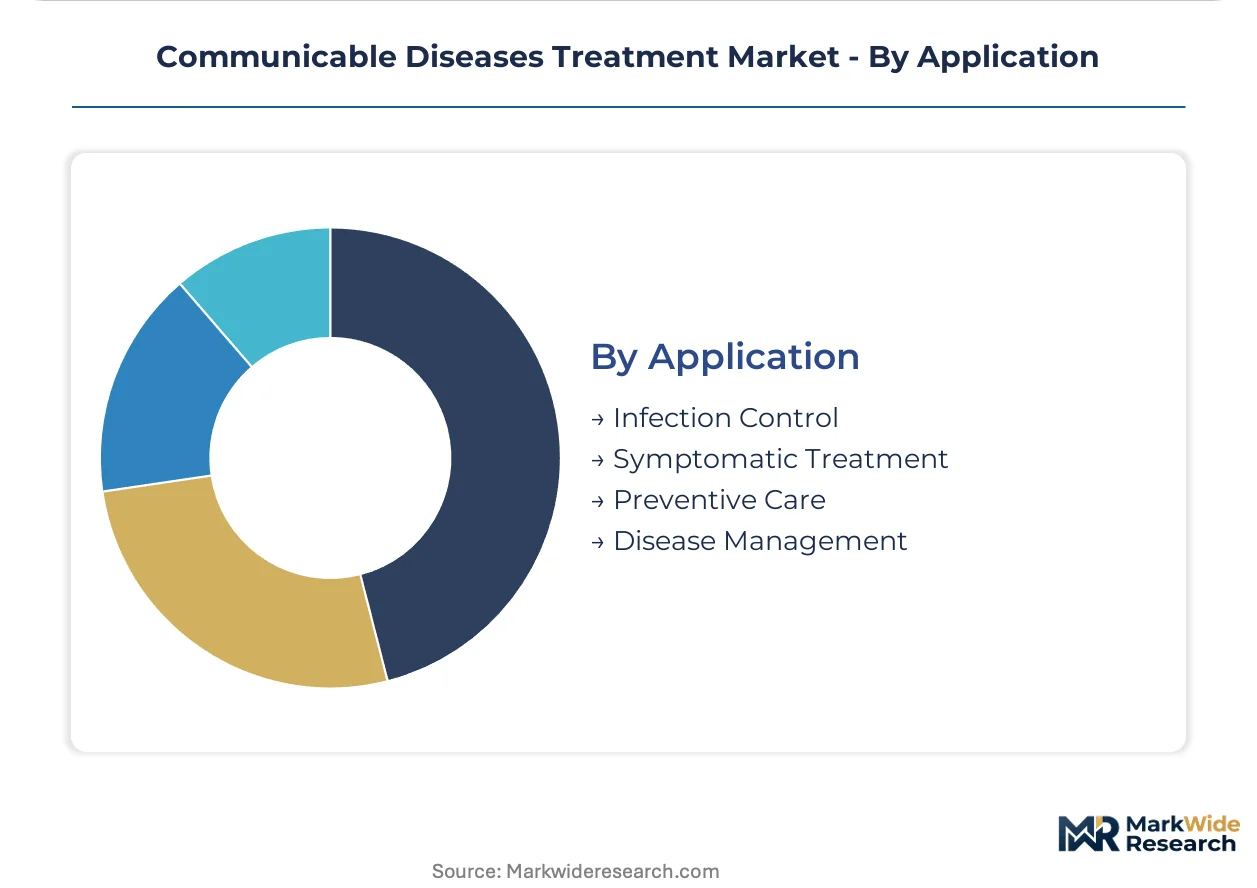
Application:
Margin structure varies sharply between acute intervention and long-term preventive contracts, shaping manufacturer portfolio prioritization.
- Infection Control:Prophylactic and empiric therapies interrupt transmission chains in outbreak settings and surgical protocols. Demand concentrates in Saudi Arabia and UAE hospital systems where healthcare-associated infection reduction targets align with national quality metrics.
- Symptomatic Treatment:Pathogen-specific and supportive therapies alleviate acute disease manifestations. Respiratory antiviral prescribing in United Kingdom and France shifts toward monoclonal antibody prophylaxis in high-risk immunocompromised cohorts.
- Preventive Care:Vaccination and pre-exposure prophylaxis reduce incidence in at-risk populations.
- Disease Management:Chronic suppressive therapies maintain viral suppression and prevent resistance emergence.
Revenue concentration sits with infection control; preventive care shows the steepest expansion trajectory as immunization programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Manaus Free Trade Zone draws pharmaceutical manufacturing through tax exemptions on imported active pharmaceutical ingredients. India's pharmaceutical special economic zones in Hyderabad and Ahmedabad accelerate bulk drug production. China's Hainan Free Trade Port enables duty-free import of biologics for domestic formulation.
United States
Academic medical centers in Boston and New York drive formulary standardization through antimicrobial stewardship committees. FDA's antimicrobial resistance protocol amendments mandate extended safety follow-up for new antibiotic approvals. The Research Triangle Park cluster in North Carolina concentrates contract manufacturing organizations serving nucleic acid therapeutic production.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia prioritize IV antibiotic stewardship programs and surgical infection prophylaxis. EMA's centralized marketing authorization procedures accelerate priority medicines pathways for tropical disease indications. The Rhine-Main biotech corridor around Frankfurt hosts viral vector manufacturing facilities scaling mRNA production capacity.
India
Government immunization programs in Maharashtra and Gujarat reshape therapeutic access through domestic manufacturing scale. CDSCO enforces local bioequivalence and cGMP requirements that filter import eligibility and production licensing. The Hyderabad-Visakhapatnam pharmaceutical belt anchors bulk drug production for broad-spectrum antibiotics and antiretrovirals.
China
Domestic manufacturers in Jiangsu and Zhejiang provinces scale recombinant protein vaccine production under national immunization program contracts. NMPA's revised drug registration regulations align with international ICH standards for clinical data acceptance. The Suzhou BioBAY cluster specializes in cell culture media and bioprocess equipment for regional vaccine developers.
Saudi Arabia
Hospital systems in Riyadh and Jeddah align healthcare-associated infection reduction targets with national quality metrics. SFDA's local bioequivalence requirements prioritize domestic manufacturing partnerships for essential medicine lists. The King Abdullah Economic City pharmaceutical zone attracts formulation facilities serving Gulf Cooperation Council markets.
Communicable Diseases Treatment Market Competitive Environment
Top-tier vendors anchor hospital procurement consolidation, while mid-cap specialists compete through differentiated access programs. The market structure reflects concentrated vaccine and antiviral portfolios held by integrated pharmaceutical conglomerates. Three archetypes dominate: mRNA platform operators, tropical disease vaccine specialists, and emerging market access navigators. Competitive moves center on manufacturing infrastructure licensing and antimicrobial resistance surveillance data partnerships.
Among US-based pharmaceutical conglomerates, Pfizer Inc. and Gilead Sciences, Inc. occupy positions within the nucleic acid therapeutic and antiviral archetypes respectively. Swiss-headquartered Novartis AG exemplifies the emerging market access navigator model through differentiated pricing frameworks. These three entities represent distinct strategic postures within a landscape where manufacturing scale and regulatory navigation capability determine procurement contract eligibility.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Novartis AG |
| Merck & Co., Inc. |
| AstraZeneca |
| Johnson & Johnson |
| Eli Lilly and Company |
| Sanofi |
| Gilead Sciences, Inc. |
| Others |
Value Chain & Pricing Dynamics
Hospital formulary consolidation under antimicrobial stewardship mandates forces manufacturers to absorb extended safety follow-up costs into contract pricing, compressing margins for antibiotics while vaccines retain premium positioning through long-term immunization agreements. This demand-side pressure reshapes supplier tiering and raw material sourcing strategies across therapeutic portfolios.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations for outbreak-response antivirals and pandemic vaccines, while spot inventory discounts apply to broad-spectrum antibiotics with approaching shelf-life thresholds. Three-tier pricing structure across premium, standard, and economy levels separates patented mRNA platforms from bioequivalent generics and government tender products. Price differentiation hinges on FDA/EMA approval tier and volume scale in institutional purchasing agreements. Cost compression in generic antibiotic tiers is intensifying because CDSCO localization mandates force dual manufacturing footprints. Government immunization programs in India and China demonstrate lowest price sensitivity; retail pharmacy channels in Brazil and South Africa show highest.
Supply Chain Analysis
Cold-chain logistics costs for mRNA vaccines and biologics consume disproportionate freight expenditure versus small-molecule antivirals, with temperature excursion risk priced into distribution contracts. Active pharmaceutical ingredient production concentrates in China, India, and Germany for distinct therapeutic classes. Finished formulation draws from Chinese recombinant protein capacity, Indian bulk drug synthesis, and German sterile injectable expertise. Single-source vulnerability pervades Chinese-controlled intermediate supply for carbapenem and cephalosporin classes. Distribution runs through hospital procurement consortia in developed markets and government central medical stores in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The communicable diseases treatment sector is transitioning from small-molecule dominance to nucleic acid platform standardization, with mRNA manufacturing infrastructure displacing legacy viral vector and egg-based production for respiratory vaccines.
For Market Incumbents: Deepen backward integration into cell culture media and lipid nanoparticle formulation to secure supply continuity against Chinese intermediate export restrictions. Expand cGMP-certified capacity in India and Germany to satisfy CDSCO and EMA localization mandates simultaneously. Anchor defensive positioning through antimicrobial resistance surveillance data partnerships that lock in formulary access. For New Entrants and Emerging Players: Begin with CRISPR diagnostic integration and point-of-care prescribing workflows in Sub-Saharan African clinic networks, where solar-powered cold chain expansion unlocks previously excluded immunization coverage. Target white-space in tropical disease prophylaxis combining EMA orphan designation incentives with drone delivery corridor partnerships. Pursue licensing arrangements with established mRNA platform operators rather than greenfield manufacturing investment. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with differentiated access programs in emerging markets and proprietary AI-driven antimicrobial discovery platforms. Long-term viability rests on regulatory navigation capability and manufacturing scale rather than single-asset pipelines. Monitor FDA antimicrobial resistance protocol amendments as the inflection signal for antibiotic development cost trajectories and portfolio restructuring decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | mRNA platform standardization enables rapid pivoting between vaccine candidates during outbreak response scenarios. |
| Regulatory Approval Pathway | EMA priority medicines and WHO prequalification convergence accelerates tropical disease market access. |
| Backward Integration | In-house lipid nanoparticle production reduces dependency on Chinese intermediate supply for nucleic acid therapeutics. |
| Licensing Agreement | Technology transfer partnerships with Indian CDSCO-compliant manufacturers satisfy localization mandates while preserving margin. |
| Pipeline Diversification | CRISPR diagnostic integration with telemedicine prescribing workflows compresses time-to-treatment in decentralized settings. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone of this analysis, cross-referenced with formulary databases and hospital procurement records. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers supplied forward-looking demand calibration. Bottom-up therapeutic volume modeling and top-down healthcare expenditure reconciliation ensured segmentation consistency across the analysis window.
Historical trendline analysis for antibiotic, antiviral, and vaccine revenue streams established baseline growth patterns without year-specific anchoring. The analytical framework segmented by product type, delivery mode, end user, and application across the modeling period, with regional regulatory clusters as an additional dimension. CAGRs derived from fitted trend extrapolation adjusted for antimicrobial resistance protocol amendments and immunization program expansion trajectories. Forecast inputs incorporated CDSCO localization enforcement timelines and EMA pediatric investigation plan integration requirements.
Underlying measurement precision varies by segment; vaccines and branded antivirals carry tighter precision than generic antibiotics subject to tender volatility. Forecasts reflect documented assumptions regarding regulatory harmonization progress and resistance surveillance network maturation. Emerging market access expansion and biologic substitution rates present specific revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Virology Market
Infectious Disease
Infectious Disease Treatments Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Valley Fever Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Q Fever Market
Infectious Disease
Human Immunodeficiency Virus Type 1 (HIV 1) Market
Infectious Disease
Global Veterinary Infectious Disease Diagnostics Market
Infectious Disease
Burkholderia Infections Market
Infectious Disease
Retropharyngeal Abscess Treatment Market
Infectious Disease
Herpes Infection Treatment Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Norovirus Infection Treatment Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Gram Positive Bacterial Infections Market