
 Uveal Melanoma Treatment Market | 2026-2036
Uveal Melanoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Uveal Melanoma Treatment Market Analytics
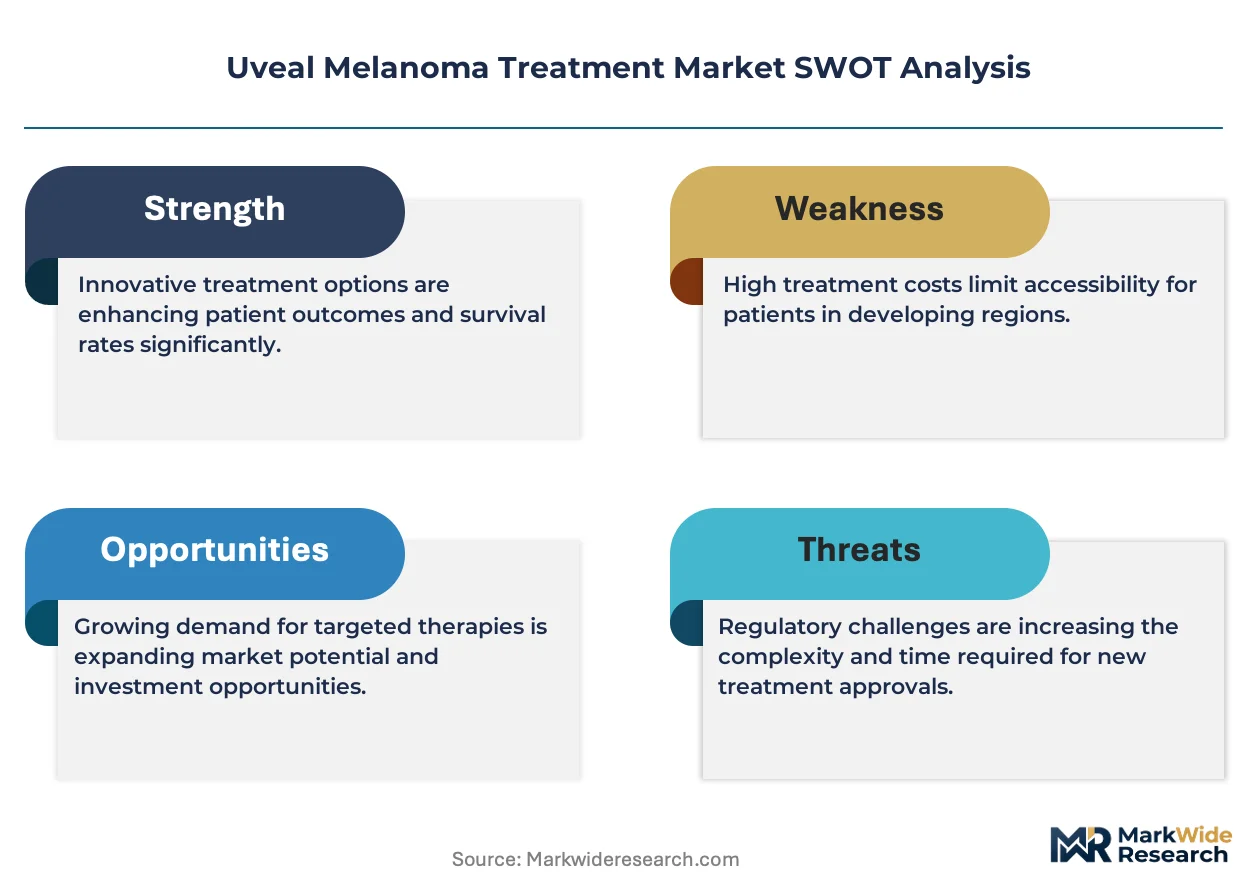
Precision-medicine grade therapeutic protocols are rotating toward mutation-directed interventions in uveal melanoma management. Immunocore Holdings leverages T-cell receptor platform technology to sustain leadership in HLA-restricted targeting of gp100-positive tumors. Aura Biosciences differentiates through virus-like drug conjugate delivery systems that dominate intraocular administration pathways.
Uveal melanoma treatment encompasses surgical resection, radiotherapy, systemic therapy, and novel biologics directed at primary intraocular malignancies arising from melanocytes of the choroid, ciliary body, or iris, with therapeutic selection governed by tumor size, genetic profile, and metastatic status. The primary purpose is local tumor control, globe preservation, and inhibition of hematogenous spread to the liver. Targeted therapy segments are capturing margin pools as GNAQ/GNA11 mutation inhibitors advance through clinical pipelines, while charged particle therapy occupies the highest-value radiotherapy tier due to Bragg peak dosimetric precision. Delivery mode stratification shows intraocular administration growing fastest as sustained-release formulations reduce systemic toxicity exposure.
FDA orphan drug designations and EMA PRIME eligibility criteria shape development incentives and reimbursement pathways for uveal melanoma therapeutics, compressing regulatory review timelines for rare disease indications. REACH compliance and ISO 13485 quality management standards govern manufacturing and distribution of ocular implantable devices and biologic drug substances across participating jurisdictions. Stakeholders must monitor liver-directed therapy integration patterns and companion diagnostic penetration to calibrate portfolio allocation between local ocular control and metastatic prevention strategies.
Market Dynamics
Charged particle therapy infrastructure deployment is bifurcating treatment access between proton-capable centers and conventional radiotherapy facilities, concentrating high-value patient flows within established referral networks while compressing margins at legacy sites.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:Compressed review timelines for novel ocular oncology agents accelerate commercialization of mutation-directed biologics targeting GNAQ/GNA11 alterations.
- Proton Beam Dosimetry:Bragg peak precision enables dose escalation to uveal tumors while sparing adjacent ocular structures, driving adoption at academic medical centers with particle therapy capital.
- Specialty Clinic Networks:Consolidated ocular oncology hubs in the United States, Germany, and Japan standardize precision-medicine protocols and concentrate high-complexity case volumes.
Market Restraints
- Cyclotron Capital Intensity:Proton therapy installation costs exceed $100 million per facility, restricting charged particle access to metropolitan academic centers with established philanthropy or federal funding.
- GNAQ/GNA11 Mutation Prevalence:Targetable oncogenic drivers occur in approximately 85% of uveal melanomas but create narrow addressable populations for mutation-specific inhibitors.
- Intraocular Delivery Complexity:Sustained-release implant manufacturing requires ISO 13485-certified cleanroom capacity that few CMOs possess, concentrating supply risk.
Strategic Opportunities
- Companion Diagnostic Integration:PRAME and HLA-A*02:01 testing platforms enable patient stratification for T-cell receptor therapies, creating pull-through for laboratory-developed test partnerships.
- Liver-Directed Therapy Sequencing:Transarterial chemoembolization and hepatic arterial infusion protocols for metastatic disease represent adjacent service line expansion for ocular oncology practices.
- EMA PRIME Eligibility:Priority medicines designation for rare ocular malignancies compresses regulatory timelines and enhances reimbursement negotiation positioning for novel mechanism agents.
Industry Challenges
- Ocular Oncology Workforce Density:Fellowship-trained specialists number fewer than 200 across all US academic centers, creating patient access bottlenecks and extending referral distances.
- Biomarker Assay Standardization:Variable HLA typing and PRAME expression quantification across CLIA laboratories complicates clinical trial enrollment and therapy selection.
- Implant Manufacturing Scale-Up:Virus-like particle conjugate production requires specialized baculovirus expression systems with limited global capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uveal Melanoma Treatment Market |
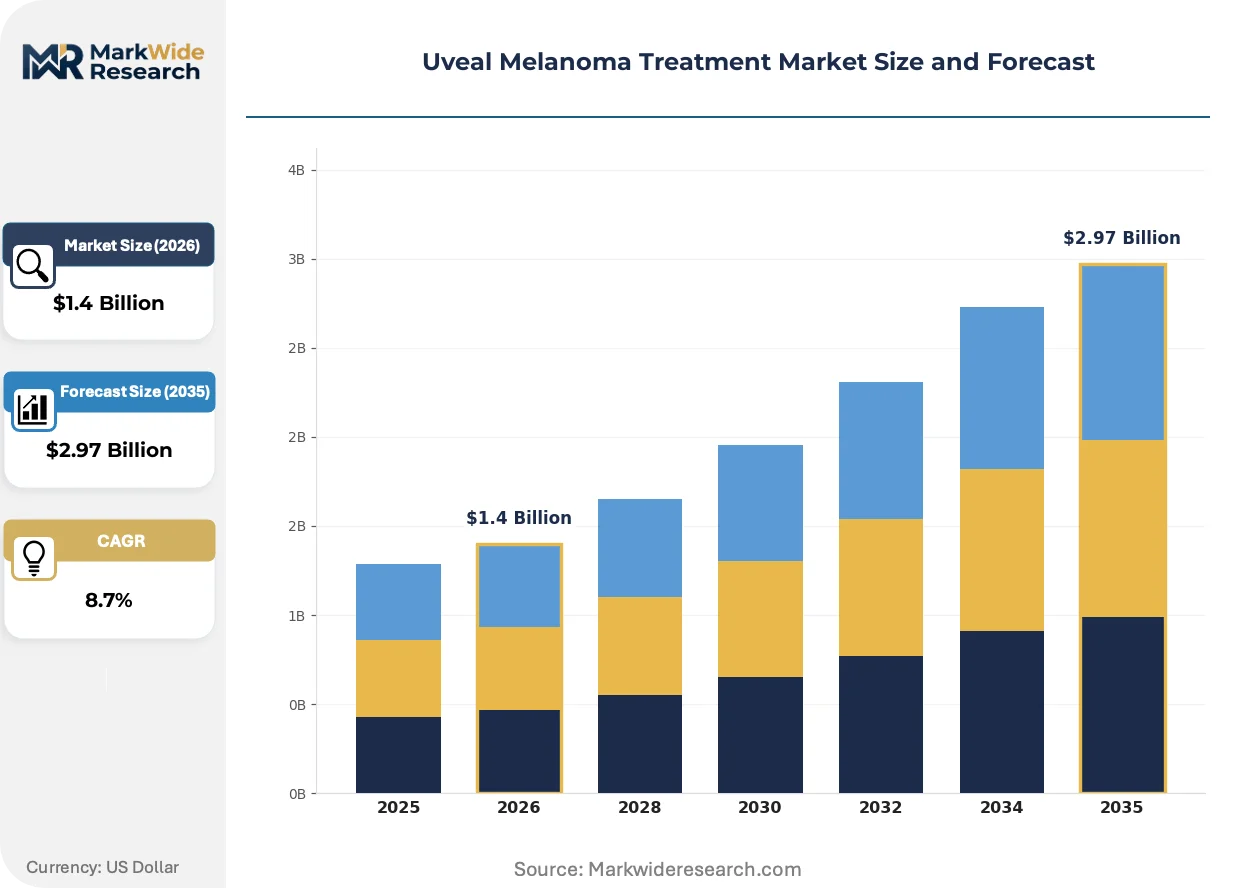
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Radiation Therapy, Chemotherapy, Targeted Therapy End User: Hospitals, Specialty Clinics, Academic Institutions, Research Centers Technology: Charged Particle Therapy, Photodynamic Therapy, Laser Therapy, High-Dose Rate Brachytherapy Delivery Mode: Intravenous, Oral, Intraocular, Topical |
| Companies Covered | Immunocore Holdings, Delcath Systems, Aura Biosciences, IDEAYA Biosciences, Novartis, Bristol-Myers Squibb, Replimune, Linnaeus Therapeutics, TriSalus Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uveal Melanoma Treatment Market Evolving Landscape
Mutation-directed therapeutic development is displacing empirical cytotoxic protocols, while intraocular drug delivery systems and liver-directed metastasis interventions reshape the care continuum. Three forces are redefining competitive positioning.
Tebentafusp and similar T-cell receptor platforms are bifurcating systemic therapy selection between HLA-restricted biologics and conventional checkpoint inhibition. Academic medical centers with integrated ocular oncology and immuno-oncology programs are adopting these agents for metastatic disease at accelerated rates. The technology is compressing market share for PD-1/PD-L1 inhibitors in PRAME-positive, HLA-A*02:01-positive patient segments.
REACH compliance and EU MDR requirements for implantable ocular devices are extending quality management system certification timelines. Manufacturers must demonstrate biocompatibility and stability data for sustained-release formulations under stricter notified body scrutiny. European specialty clinics are responding by consolidating procurement with suppliers holding dual FDA-EMA manufacturing approvals.
Integrated ocular oncology networks are consolidating previously dispersed care across retina specialists, medical oncologists, and radiation oncologists. Academic medical centers with proton beam capacity are absorbing community-based uveal melanoma cases that previously received plaque brachytherapy. This concentration is most visible in the United States, where referral patterns increasingly favor NCI-designated cancer centers with phase I trial access.
Uveal Melanoma Treatment Market Segmentation
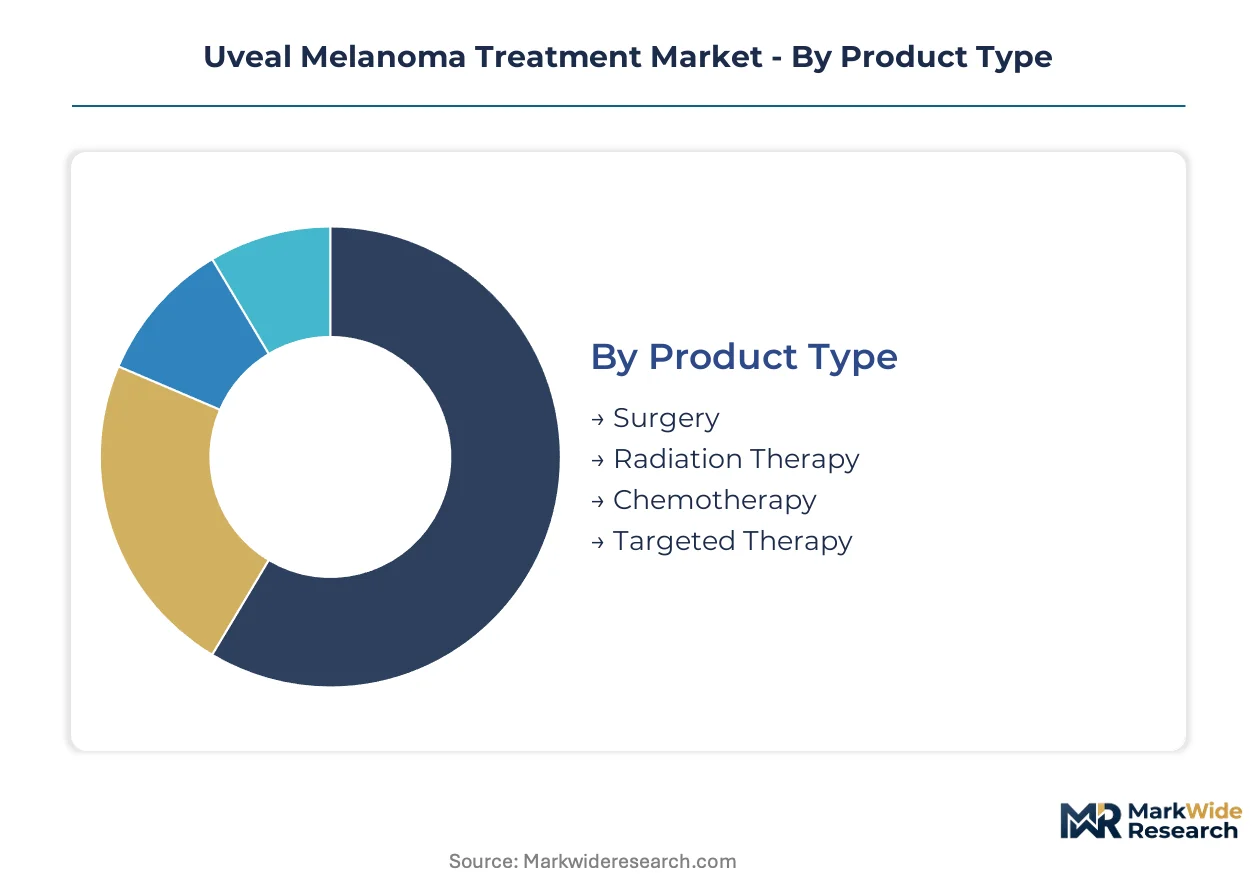
Therapeutic modality selection in uveal melanoma hinges on tumor genetics, metastatic status, and facility infrastructure. Segmentation reveals how proton beam capital concentration and mutation-directed drug development are redrawing competitive boundaries across treatment categories.
Product Type:
Targeted therapy segments face acute substitution pressure from T-cell receptor biologics that displace empirical chemotherapy protocols in metastatic settings.
- Surgery:Enucleation and transscleral resection procedures preserve anatomical outcomes for large choroidal tumors exceeding 18mm basal diameter. Demand concentrates at academic medical centers in the United States and Germany where fellowship-trained ocular oncologists manage high-complexity globe-salvage decisions.
- Radiation Therapy:Plaque brachytherapy with ruthenium-106 or iodine-125 seeds dominates medium-sized tumor management, though proton beam facilities capture premium case volumes. Charged particle centers in Boston, Heidelberg, and Tsukuba absorb referrals from conventional radiotherapy sites lacking cyclotron infrastructure.
- Chemotherapy:Systemic cytotoxic protocols have retreated to salvage settings as checkpoint inhibitors and bispecific T-cell engagers advance through regulatory pipelines.
- Targeted Therapy:GNAQ/GNA11 mutation inhibitors and MEK pathway blockers address oncogenic driver prevalence in approximately 85% of cases.
Radiation therapy retains volume leadership; targeted therapy holds the steepest expansion curve.
End User:
Capital intensity and regulatory certification requirements stratify end users into distinct tiers of service capability and patient throughput.
- Hospitals:General oncology units without dedicated ocular pathology struggle to retain uveal melanoma cases that migrate toward specialized referral networks. Community hospitals in the United States increasingly transfer patients to NCI-designated centers with integrated proton beam capacity.
- Specialty Clinics:Consolidated ocular oncology hubs in Philadelphia, London, and Osaka standardize precision-medicine protocols and concentrate high-complexity surgical volumes. These facilities command premium reimbursement through bundled episode payments for globe-preservation pathways.
- Academic Institutions:Fellowship training programs and phase I trial access attract metastatic cases seeking experimental T-cell receptor therapies.
- Research Centers:Preclinical toxicology and pharmacokinetic studies support ocular drug development pipelines.
Specialty clinics capture margin concentration; academic institutions gain share fastest through trial enrollment.
Technology:
Dosimetric precision and tissue-sparing capability determine technology substitution patterns across radiotherapy modalities.
- Charged Particle Therapy:Proton beam Bragg peak physics enables dose escalation to uveal tumors while sparing optic nerve and macula. Installation costs exceeding $100 million per facility restrict this technology to metropolitan academic centers with federal funding or philanthropic endowments.
- Photodynamic Therapy:Verteporfin-activated photochemical reactions target small choroidal melanomas and occult subretinal neovascularization. European ophthalmology departments in Paris and Milan have adopted this modality for select low-risk lesions.
- Laser Therapy:Transpupillary thermotherapy delivers sublethal hyperthermia for juxtapapillary tumors unsuitable for plaque placement.
- High-Dose Rate Brachytherapy:Customized ruthenium plaques provide localized radiation for medium-thickness tumors with shorter treatment courses than iodine-125 alternatives.
Charged particle therapy commands premium positioning; photodynamic therapy expands most quickly in European ambulatory settings.
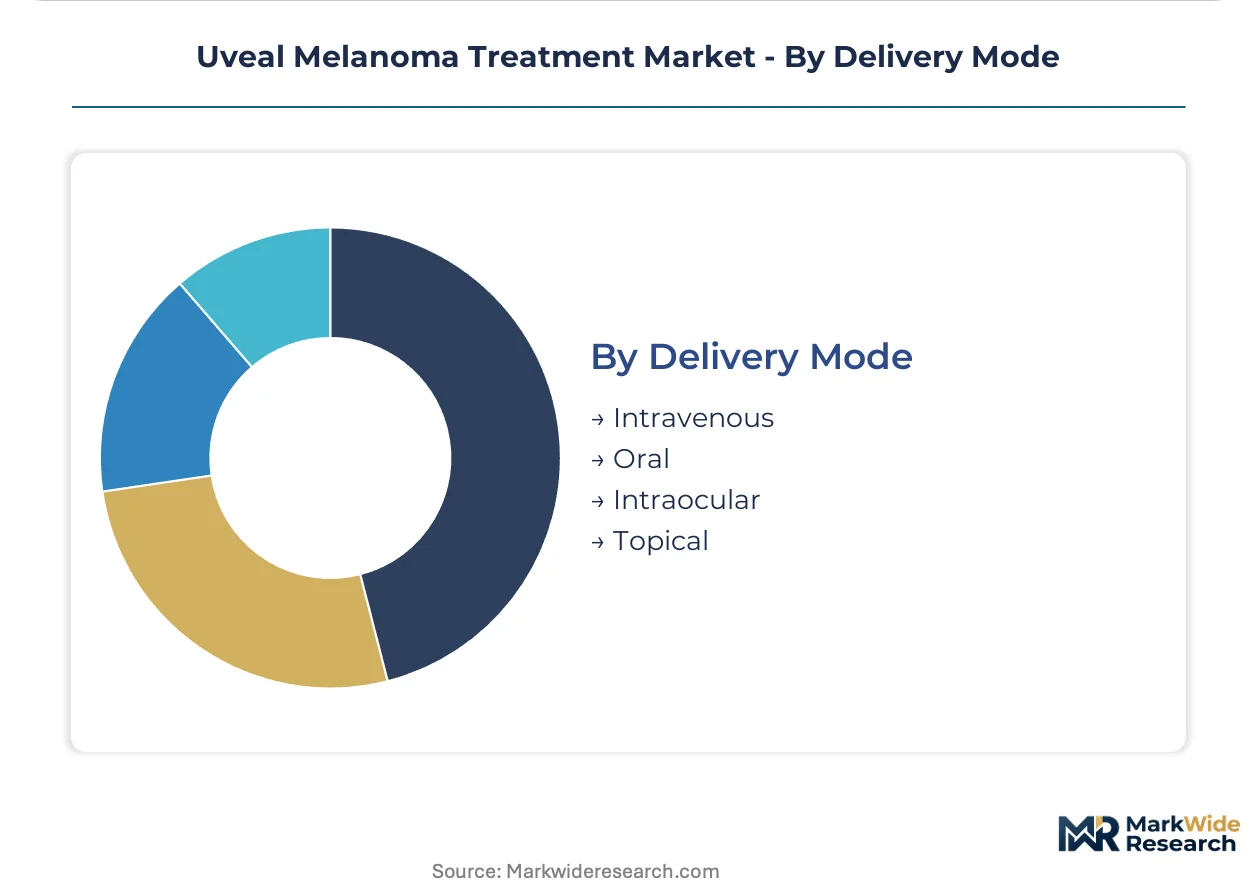
Delivery Mode:
Pharmacokinetic optimization and toxicity reduction drive route selection between systemic exposure and localized drug concentration.
- Intravenous:Tebentafusp and checkpoint inhibitors require hospital-based infusion infrastructure with HLA typing and PRAME expression screening. Infusion centers at major cancer institutes in Houston and Tokyo manage the highest volumes of metastatic uveal melanoma cases.
- Oral:MEK inhibitors and other small-molecule targeted agents offer outpatient convenience but demand rigorous hepatotoxicity monitoring given liver metastasis prevalence.
- Intraocular:Sustained-release implants and virus-like particle conjugates minimize systemic exposure while maintaining therapeutic vitreous levels.
- Topical:Limited penetration restricts this route to conjunctival melanoma adjuvant applications.
Intravenous administration dominates metastatic treatment; intraocular delivery gains share fastest through sustained-release formulation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Proton beam infrastructure and ocular oncology referral networks concentrate treatment capacity in metropolitan academic centers across three continents. FDA breakthrough designations and EMA PRIME pathways accelerate commercial access in North America and Europe, while Japan's PMDA orphan drug framework supports domestic development of mutation-directed therapies.
United States
Massachusetts General Hospital and Memorial Sloan Kettering absorb high-complexity cases from community ophthalmology practices seeking globe-preservation pathways. FDA orphan drug incentives compress development timelines for GNAQ/GNA11-targeted agents. The Philadelphia-Baltimore corridor hosts dense specialty clinic networks that standardize precision-medicine protocols for choroidal melanoma.
Germany
Heidelberg University Hospital operates Europe's highest-volume proton beam facility for ocular malignancies, drawing referrals from France, Italy, and Eastern Europe. EMA PRIME eligibility criteria enhance reimbursement positioning for novel T-cell receptor therapies manufactured under REACH-compliant quality systems. The Baden-Württemberg cluster integrates ocular pathology with immuno-oncology trial access.
Japan
Tsukuba's proton therapy center serves domestic demand for Bragg peak precision in juxtapapillary tumors unsuitable for plaque brachytherapy. PMDA Sakigake designation accelerates regulatory review for liver-directed metastasis interventions. Tokyo-based ocular oncology hubs coordinate with National Cancer Center hospitals for systemic therapy sequencing.
United Kingdom
Moorfields Eye Hospital and Royal Liverpool University Hospital concentrate surgical resection volumes for large choroidal tumors exceeding 18mm basal diameter. NHS England's specialized commissioning framework routes rare ocular malignancies to designated supraregional centers. The London-Oxford-Cambridge triangle anchors immuno-oncology trial infrastructure for metastatic disease.
Switzerland
Swissmedic's expedited access pathway for rare disease therapeutics supports early commercialization of sustained-release intraocular formulations. Basel's pharmaceutical manufacturing cluster supplies virus-like particle conjugates under ISO 13485-certified conditions. University Hospital Zurich integrates proton beam capacity with ocular oncology fellowship training programs.
Uveal Melanoma Treatment Market Competitive Landscape
Concentration sits with biotechnology developers possessing T-cell receptor platforms and intraocular drug delivery expertise. The competitive terrain divides between mutation-directed biologic innovators and radiotherapy technology operators with proton beam capital. Two strategic archetypes dominate: HLA-restricted immunotherapy specialists and virus-like particle conjugate manufacturers. Competitive moves center on companion diagnostic partnerships and liver-directed therapy service line integration.
Within the immunotherapy archetype, Immunocore Holdings exemplifies T-cell receptor platform development for PRAME-positive tumors, while Bristol-Myers Squibb occupies a position spanning checkpoint inhibition and ocular oncology trial sponsorship. Aura Biosciences represents the intraocular delivery specialization, anchoring virus-like particle technology for localized drug concentration. These three companies illustrate the bifurcation between systemic biologic approaches and localized administration technologies reshaping therapeutic selection.
| Leading Market Players |
|---|
| Immunocore Holdings |
| Delcath Systems |
| Aura Biosciences |
| IDEAYA Biosciences |
| Novartis |
| Bristol-Myers Squibb |
| Replimune |
| Linnaeus Therapeutics |
| TriSalus Life Sciences |
| Others |
Value Network & Pricing Analysis
Virus-like particle conjugate manufacturing displaces conventional small-molecule synthesis as the dominant production paradigm, simultaneously concentrating supply geography in Basel's pharmaceutical cluster and compressing pricing economics for legacy cytotoxic agents. This substitution dynamic reshapes procurement patterns as ocular oncology practices consolidate purchasing with dual FDA-EMA certified suppliers.
Pricing Analysis
EMA PRIME eligibility and FDA orphan drug designation dictate the pricing tier structure for uveal melanoma therapeutics across the European and North American markets. Three-tier pricing structure across premium, standard, and economy levels separates charged particle therapy centers from plaque brachytherapy facilities and salvage chemotherapy protocols. Price differentiation rests on proton beam capital availability and companion diagnostic integration depth. Cost compression in the standard tier is intensifying because community hospitals increasingly transfer complex cases to academic referral networks. Community oncology units exhibit highest price sensitivity; NCI-designated cancer centers with integrated proton capacity demonstrate lowest sensitivity due to bundled episode reimbursement.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg strains inbound logistics for GMP-certified active pharmaceutical ingredients destined for ocular implant manufacturing. Supply concentration sits with Switzerland, Germany, and the United States for virus-like particle conjugate production and proton therapy system assembly. Baculovirus expression systems, ruthenium-106 isotope supply, and HLA typing reagents constitute critical input dependencies. Single-source vulnerability characterizes the sustained-release implant segment where ISO 13485-certified cleanroom capacity remains scarce. Distribution runs through specialty clinic procurement consortia and academic medical center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The uveal melanoma treatment market is entering a cyclical recovery phase driven by proton beam infrastructure buildout and T-cell receptor platform maturation. Capital deployment patterns favor integrated ocular oncology networks over fragmented community-based care.
For Market Incumbents: Secure companion diagnostic partnerships and liver-directed therapy service line integration to defend against T-cell receptor platform substitution. Immunocore Holdings and Aura Biosciences have established early-mover positions in HLA-restricted biologics and intraocular delivery respectively. Incumbents should deepen backward integration into baculovirus expression manufacturing to control virus-like particle conjugate supply. FDA breakthrough therapy designation timelines compress competitive response windows. For New Entrants and Emerging Players: Metastatic disease sequencing represents the most penetrable service gap where incumbents under-serve transarterial chemoembolization coordination. New entrants should target community oncology practices in the United States Midwest and Southern Europe lacking proton beam referral relationships. A go-to-market angle emphasizing telemedicine-enabled ocular oncology consultation can capture dispersed patient populations distant from academic centers. Liver-directed therapy partnerships with interventional radiology practices offer lowest competitive density entry point. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed proton therapy facility operators seeking exit liquidity after construction-phase capitalization. The five-to-ten year viability window favors platforms with both local ocular control and metastatic prevention capabilities rather than single-modality radiotherapy pure-plays. Acquisition targets should demonstrate integrated ocular oncology and immuno-oncology trial access. The signal to watch is liver-directed therapy reimbursement coding expansion as inflection indicator for metastatic disease service line economics.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | PRAME and HLA-A*02:01 testing platforms enable patient stratification for T-cell receptor therapies at Immunocore. |
| Proton Beam Capacity Expansion | Heidelberg and Tsukuba facilities absorb referrals from conventional radiotherapy sites lacking cyclotron infrastructure. |
| Liver-Directed Therapy Integration | Transarterial chemoembolization protocols extend ocular oncology practice service lines into metastatic disease management. |
| EMA PRIME Designation Pursuit | Priority medicines eligibility compresses regulatory timelines and enhances reimbursement positioning for novel mechanism agents. |
| Baculovirus Expression Scale-Up | Specialized manufacturing capacity under ISO 13485 certification concentrates supply risk for virus-like particle conjugates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across ocular oncology fellowship directors, proton therapy facility administrators, regulatory affairs leads at biotechnology developers, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA breakthrough therapy designation filings, EMA PRIME eligibility decisions, ClinicalTrials.gov protocol registries, and hospital procurement database audits. Bottom-up patient flow modeling and top-down market sizing triangulated volume estimates.
Across the analysis window, the forecasting framework modeled therapeutic modality substitution patterns, end-user capital intensity tiers, technology adoption curves, and delivery mode pharmacokinetic optimization. Segmentation dimensions included treatment line, genetic mutation status, facility infrastructure class, and regional regulatory cluster. CAGRs were derived from patient incidence projections, facility capacity expansion schedules, and therapy penetration assumptions. Proton beam installation timelines and T-cell receptor platform regulatory milestones served as key forecast inputs.
Forecasts assume regulatory continuity in FDA breakthrough therapy pathways and EMA PRIME eligibility criteria; material policy shifts would require re-modeling. Assumptions reflect stable reimbursement coding for liver-directed therapies and sustained proton beam capital availability through federal funding mechanisms. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Global Ophthalmology PACS Market
Ophthalmology
Anterior Uveitis Market
Ophthalmology
Astigmatism Market
Ophthalmology
Artificial Iris Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Global Artificial Tear Market
Ophthalmology
Meibomian Gland Dysfunction Treatment Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Diabetic Macular Edema Treatment Market