
 Global Melanoma Therapeutics Market | 2026-2036
Global Melanoma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Melanoma Therapeutics Market Analysis
PD-1 inhibitor substitution for conventional chemotherapy is recalibrating front-line treatment economics across melanoma care. Bristol-Myers Squibb Company leverages its dual immunotherapy franchise to anchor combination protocols in academic medical centers. Merck & Co., Inc. dominates the anti-PD-1 maintenance segment through manufacturing scale and channel control in infused oncology.
Melanoma therapeutics comprise biologic and small-molecule agents engineered to interrupt oncogenic signaling or activate anti-tumor immunity, with monoclonal antibodies requiring cold-chain distribution at two to eight degrees Celsius to preserve protein stability. These agents serve the primary purpose of extending progression-free survival in metastatic and adjuvant settings. Immune checkpoint inhibitors command the largest revenue pool due to durable response profiles, while targeted therapy segments face biosimilar pressure that compresses pricing power. The intravenous delivery mode sustains hospital-centric purchasing patterns that concentrate procurement volume through group purchasing organizations.
The FDA, EMA, and Japan's PMDA each enforce distinct evidentiary standards for oncology approvals that shape clinical trial investment and label expansion strategies. REACH and the EU AI Act introduce supply-chain transparency and algorithmic diagnostic requirements that affect companion diagnostic pairing. Stakeholders must monitor how regulator divergence on surrogate endpoints influences portfolio prioritization and geographic launch sequencing.
Market Dynamics
PD-1 inhibitor substitution is compressing front-line treatment economics and recalibrating hospital procurement priorities across melanoma care pathways. The shift from cytotoxic chemotherapy to immuno-oncology infusion protocols is restructuring site-of-care economics and cold-chain logistics requirements.
Growth Catalysts
- FDA Accelerated Approval Pathway:The breakthrough therapy designation compresses clinical development timelines for novel checkpoint inhibitors, enabling earlier commercialization of combination regimens.
- Academic Medical Center Adoption:Hospital-based infusion centers are expanding dedicated immuno-oncology capacity to capture PD-1 maintenance volumes and associated diagnostic services.
- Companion Diagnostic Pairing:Algorithmic biomarker testing platforms are standardizing patient stratification protocols, expanding eligible populations for targeted BRAF/MEK inhibition sequences.
Market Restraints
- Cold-Chain Distribution Costs:Monoclonal antibodies require two-to-eight-degree Celsius preservation, constraining last-mile delivery to certified infusion centers and limiting rural access.
- Biosimilar Pricing Compression:Targeted therapy segments face erosion as BRAF and MEK inhibitor biosimilars enter European and Japanese markets, pressuring originator margins.
- EMA Evidentiary Divergence:Surrogate endpoint acceptance varies between FDA and European regulators, forcing duplicate trial investments and delaying label expansions.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered checkpoint inhibitor delivery would displace hospital-centric infusion models and capture ambulatory oncology clinic volumes.
- Japan PMDA Priority Review:Sakigake designation incentives attract early filing strategies for novel combination protocols in the world's third-largest oncology market.
- Real-World Evidence Integration:Post-marketing registry requirements under EU AI Act algorithmic transparency rules create competitive differentiation for manufacturers with robust pharmacovigilance infrastructure.
Industry Challenges
- Immuno-Oncology Manufacturing Scale-Up:Cell-line development and bioreactor capacity constraints limit rapid response to demand surges for approved checkpoint inhibitors.
- Cross-Border Reimbursement Fragmentation:Germany's AMNOG early benefit assessment creates divergent pricing outcomes versus France's HAS evaluation, complicating EU launch sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Melanoma Therapeutics Market |
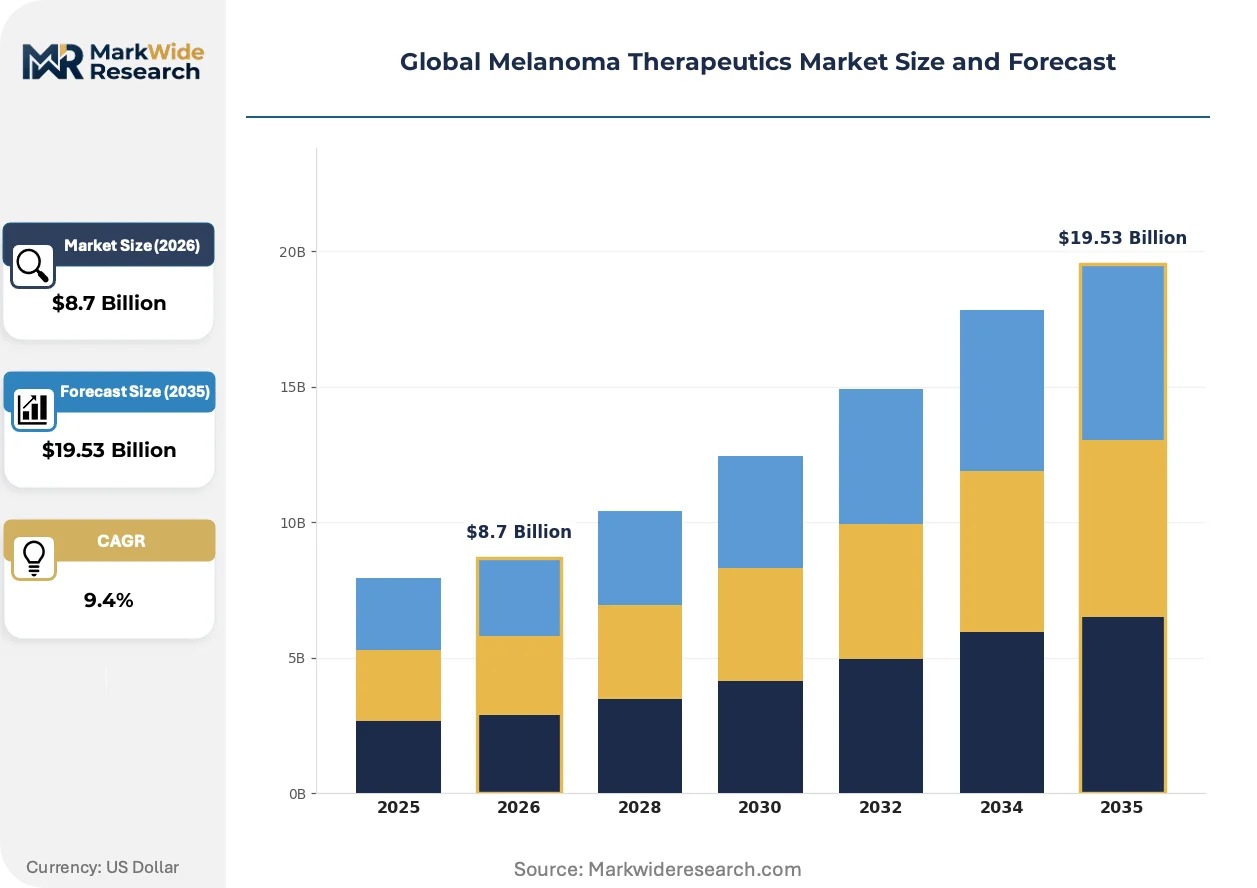
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Immune Checkpoint Inhibitors, Cytotoxic T Lymphocyte-Associated Protein 4 Inhibitors, Targeted Therapy Therapy Area: Combination Therapy, Adjuvant Therapy, Neoadjuvant Therapy, Palliative Care Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Specialty Clinics, Research Institutes, Homecare Settings |
| Companies Covered | Bristol-Myers Squibb Company, Merck & Co., Inc., F. Hoffmann-La Roche Ltd, Novartis AG, Amgen, Inc., AstraZeneca, Pfizer Inc., Abbott Laboratories, Daiichi Sankyo Company, Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Melanoma Therapeutics Market Emerging Trajectories
Bi-specific antibody engineering and tumor-infiltrating lymphocyte therapies are converging to reshape melanoma treatment sequencing beyond single-agent checkpoint blockade. These modalities promise to address acquired resistance patterns that limit durable response rates.
Bi-specific T-cell engagers are unifying CD3-directed T-cell recruitment with tumor-associated antigen binding in single constructs. Academic medical centers in the United States and Germany are initiating Phase I/II protocols for melanoma-specific targets. This unifying architecture is compressing development timelines by eliminating sequential combination trials and reducing manufacturing complexity versus co-formulation strategies.
REACH supply-chain transparency requirements and EU AI Act algorithmic diagnostic mandates are forcing companion diagnostic developers to document training data provenance and model performance across demographic subgroups. Diagnostic manufacturers must now maintain technical files demonstrating bias mitigation in AI-enabled pathology algorithms. France's ANSM and Germany's BfArM are enforcing divergent timelines for these submissions, fragmenting EU market entry coordination.
Site-of-care economics are driving hospital systems to unbundle infusion pharmacy services from inpatient oncology units. United States group purchasing organizations are consolidating biologic procurement through specialty distributor networks that capture 340B pricing advantages. This restructuring is most visible in community oncology practices across Texas and Florida, where independent infusion centers are displacing hospital outpatient departments for stable maintenance therapy administration.
Global Melanoma Therapeutics Market Segmentation
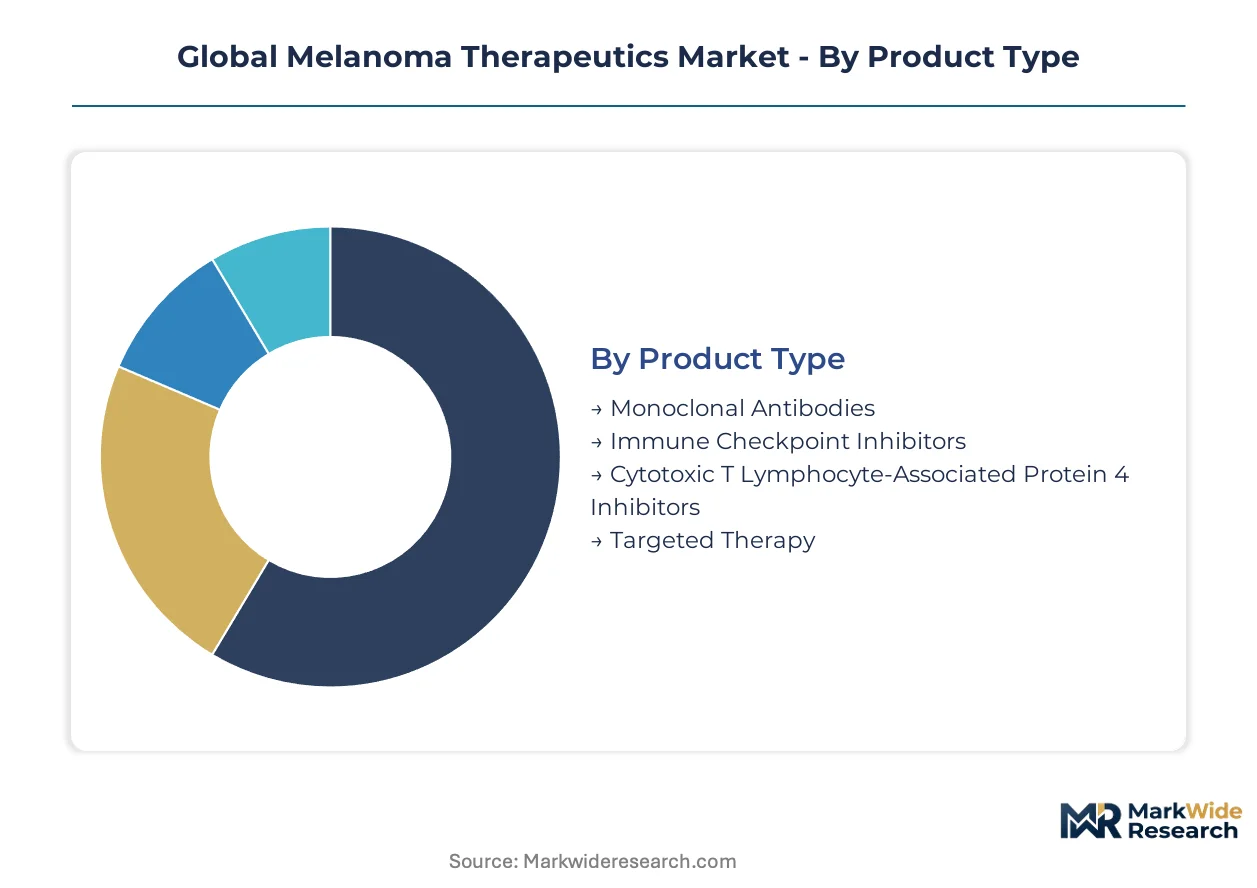
Melanoma therapeutics segmentation reveals divergent economics across administration settings and molecular modalities. Hospital infusion centers concentrate premium biologic volumes while oral formulations capture ambulatory migration. Understanding these splits enables precise resource allocation across cold-chain infrastructure and site-of-care investments.
Product Type:
Volume leadership belongs to established infusion biologics while premium pricing concentrates in next-generation checkpoint combinations.
- Monoclonal Antibodies:Engineered immunoglobulins targeting tumor-associated antigens require continuous cold-chain preservation from manufacturing through administration. Demand clusters in United States academic medical centers where 340B pricing advantages support high-volume procurement of maintenance regimens.
- Immune Checkpoint Inhibitors:PD-1 and PD-L1 directed monoclonal antibodies that disinhibit T-cell mediated anti-tumor responses. United States hospital systems capture the majority of first-line nivolumab and pembrolizumab volumes through dedicated immuno-oncology infusion suites.
- Cytotoxic T Lymphocyte-Associated Protein 4 Inhibitors:Ipilimumab-class agents blocking CTLA-4 signaling to amplify T-cell activation. Japanese PMDA priority review pathways accelerate access for combination protocols with PD-1 inhibitors.
- Targeted Therapy:Small-molecule BRAF and MEK inhibitors disrupting oncogenic kinase signaling. Oral bioavailability enables German community oncology practices to displace hospital visits for stable adjuvant patients.
Mature deployment sits with Monoclonal Antibodies. Newer deployment is concentrated in Immune Checkpoint Inhibitors.
Therapy Area:
Cost tier stratification separates curative-intent combination protocols from lower-intensity maintenance and supportive modalities.
- Combination Therapy:Concurrent or sequential administration of multiple mechanistic classes to overcome resistance pathways. United States NCCN guidelines drive rapid adoption of dual checkpoint blockade in academic centers despite toxicity management costs.
- Adjuvant Therapy:Post-surgical systemic treatment to eliminate micrometastatic disease. German AMNOG benefit assessments concentrate pembrolizumab adjuvant approvals in high-risk Stage III populations.
- Neoadjuvant Therapy:Pre-operative systemic administration to enable surgical resection or reduce recurrence risk. Japanese melanoma centers pioneer neoadjuvant checkpoint inhibitor protocols for locally advanced disease.
- Palliative Care:Symptom-directed therapy for metastatic patients beyond curative options. French HAS evaluation frameworks prioritize quality-adjusted life year thresholds for third-line targeted therapy access.
Revenue concentration follows Combination Therapy. Patient volume leadership belongs to Adjuvant Therapy.
Delivery Mode:
Supply concentration in certified infusion centers shapes access patterns across rural-urban divides.
- Intravenous:Hospital or clinic-administered infusion requiring skilled nursing supervision and adverse event monitoring. United States group purchasing organizations consolidate 80% of checkpoint inhibitor volume through specialty distributor networks.
- Subcutaneous:Self-administered or nurse-assisted injection enabling ambulatory care migration. German statutory health insurance funds pilot subcutaneous nivolumab in community oncology practices to reduce hospital day costs.
- Oral:Patient-managed small-molecule dosing with periodic monitoring. Japanese dispensing pharmacy regulations require face-to-face oncology consultations for BRAF inhibitor initiation.
- Topical:Localized application for superficial or in-transit metastases. United States dermatology clinics administer imiquimod for select Stage 0-II lesions.
Facility dependence dominates Intravenous administration. Patient autonomy is expanding fastest in Subcutaneous delivery.
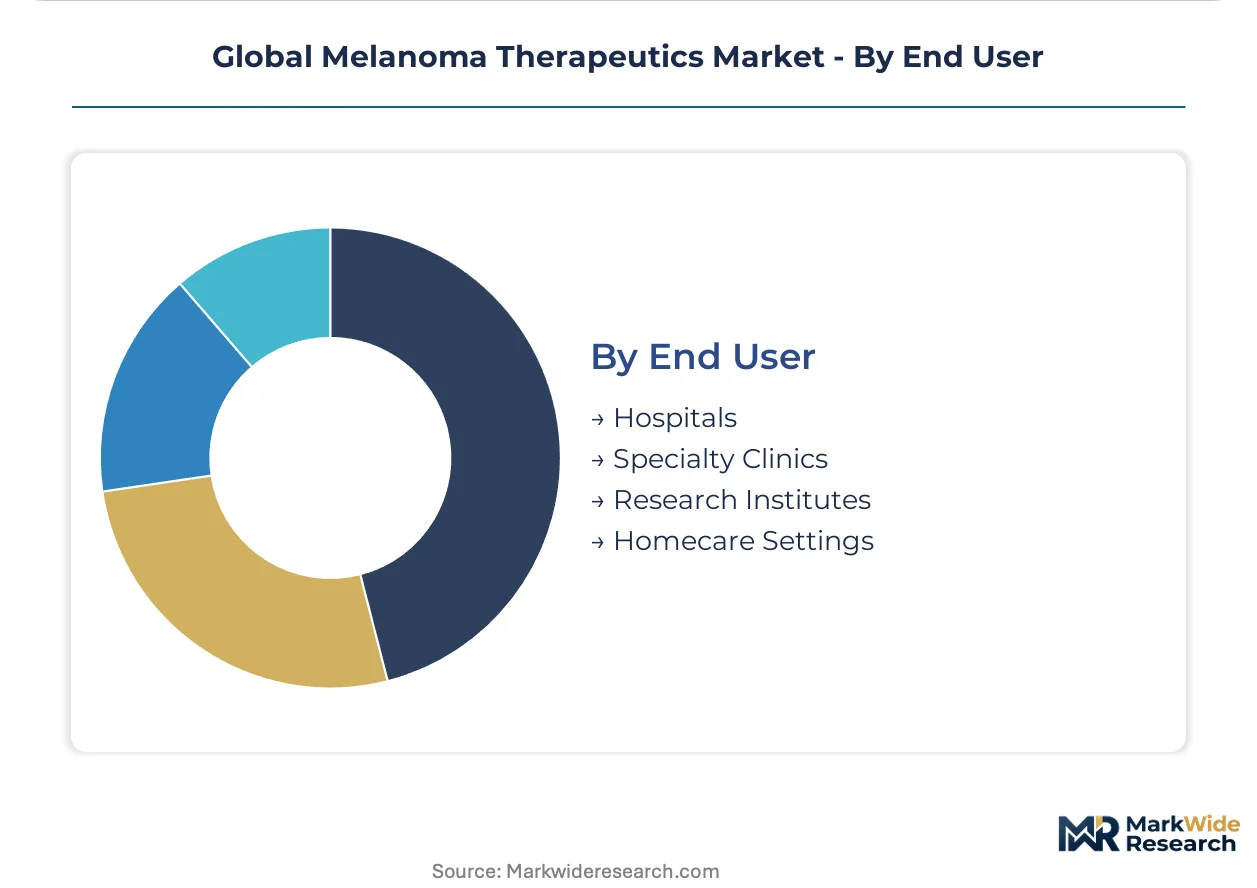
End User:
Customer type fragmentation reflects unbundling of infusion services from traditional hospital ownership.
- Hospitals:Integrated health systems capturing complex induction therapy and toxicity management. United States 340B-eligible hospitals leverage pricing advantages to anchor immuno-oncology service lines.
- Specialty Clinics:Independent oncology practices and infusion centers displacing hospital outpatient departments for stable maintenance. Texas and Florida regulatory environments favor independent clinic licensing.
- Research Institutes:Academic medical centers conducting Phase I/II trials for novel bi-specific antibodies and TIL therapies. German university hospitals coordinate EU-wide investigator-initiated studies.
- Homecare Settings:Nurse-supervised administration in residential environments for select subcutaneous regimens. Japanese home-visit nursing associations develop melanoma-specific protocols.
Procurement scale concentrates in Hospitals. Site-of-care migration is accelerating fastest in Specialty Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems capture the dominant share of checkpoint inhibitor volumes through 340B-eligible procurement networks. Germany's AMNOG framework and Japan's PMDA priority review channel concentrate premium biologic demand in these three markets.
United States
Academic medical centers in Boston and Houston anchor first-line nivolumab and pembrolizumab volumes through dedicated immuno-oncology infusion suites. FDA accelerated approval pathways compress development timelines for breakthrough therapy designations. Texas and Florida independent infusion centers are displacing hospital outpatient departments for stable maintenance therapy administration.
Germany
Community oncology practices in Bavaria and North Rhine-Westphalia leverage oral BRAF inhibitor bioavailability to reduce hospital day costs for adjuvant patients. AMNOG early benefit assessments concentrate pembrolizumab approvals in high-risk Stage III populations. German university hospitals coordinate EU-wide investigator-initiated studies for bi-specific antibody protocols.
Japan
Melanoma centers in Tokyo and Osaka pioneer neoadjuvant checkpoint inhibitor protocols for locally advanced disease. PMDA Sakigake designation incentives attract early filing strategies for novel combination regimens. Japanese home-visit nursing associations develop melanoma-specific protocols for select subcutaneous regimens in residential settings.
France
HAS evaluation frameworks in Paris and Lyon prioritize quality-adjusted life year thresholds for third-line targeted therapy access. ANSM enforces divergent timelines for EU AI Act algorithmic diagnostic submissions versus Germany's BfArM. French cancer centers concentrate companion diagnostic pairing for BRAF/MEK inhibition sequences.
United Kingdom
NHS England specialized commissioning in London and Manchester concentrates immunotherapy access through cancer drugs fund mechanisms. MHRA post-Brexit divergence from EMA evidentiary standards shapes trial investment and label expansion sequencing. UK biotech clusters in Cambridge and Oxford anchor early-stage bi-specific T-cell engager development.
Global Melanoma Therapeutics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical companies commanding checkpoint inhibitor maintenance volumes while biotechnology firms anchor novel mechanism development. The vendor base concentrates around three strategic archetypes: large-cap immunotherapy franchises with manufacturing scale, mid-cap targeted therapy specialists facing biosimilar pressure, and emerging biotechs advancing cell therapy platforms. Dominant competitive moves include subcutaneous formulation development to displace hospital-centric infusion models and real-world evidence infrastructure investments to satisfy EU AI Act algorithmic transparency requirements.
Among large-cap immunotherapy developers, Bristol-Myers Squibb Company and Merck & Co., Inc. occupy positions exemplifying the dual checkpoint blockade and anti-PD-1 maintenance archetypes respectively. Novartis AG represents the targeted therapy segment facing pricing compression from BRAF and MEK inhibitor biosimilars entering European markets. These three entities anchor distinct competitive vectors within the melanoma therapeutics landscape.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Amgen, Inc. |
| AstraZeneca |
| Pfizer Inc. |
| Abbott Laboratories |
| Daiichi Sankyo Company, Limited |
| Others |
Supply Flow & Price Mechanics
Premium checkpoint inhibitor pricing versus commoditized targeted therapy tiers bifurcates the melanoma therapeutics landscape, with cold-chain logistics requirements and infusion center certification standards reinforcing this divergence across procurement networks. The cost structure of monoclonal antibody preservation at two-to-eight degrees Celsius elevates distribution expenses for biologics while oral small-molecule agents bypass these constraints entirely.
Pricing Analysis
Volume leadership concentrates in maintenance-phase PD-1 inhibitors where manufacturing scale supports stable pricing, while margin compression runs through BRAF and MEK inhibitor segments facing European biosimilar entry. Three-tier pricing structure across premium combination regimens, standard single-agent checkpoint blockade, and economy targeted therapy tiers reflects efficacy differentiation and reimbursement tiering. Cost compression in targeted therapy is intensifying because Japanese and German statutory funds reference European biosimilar pricing in negotiations. Community oncology practices in Texas and Florida exhibit highest price sensitivity due to 340B pricing dependency, whereas academic medical centers anchor premium tier demand through research-aligned procurement.
Supply Chain Analysis
Freight costs for temperature-controlled biologics distribution constrain last-mile delivery to certified infusion centers, with United States, Germany, and Japan anchoring cold-chain infrastructure investments. Active pharmaceutical ingredient sourcing draws from Swiss and Irish contract manufacturing organizations for monoclonal antibody cell-line development. Single-source vulnerability sits with concentrated bioreactor capacity for approved checkpoint inhibitors. Distribution runs through United States group purchasing organizations and European specialty distributor networks that consolidate hospital procurement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The melanoma therapeutics sector is becoming a vertical-integration race, with manufacturers pursuing captive bioreactor capacity to secure supply continuity against demand surges for approved checkpoint inhibitors.
For Market Incumbents: Deploy manufacturing scale as the primary defensive lever. Expand bioreactor footprint in United States and German production hubs to preempt capacity constraints during demand spikes for nivolumab-class agents. Secure channel control through exclusive distribution agreements with academic medical center networks to defend against subcutaneous formulation displacement. Counter biosimilar pressure in targeted therapy through backward integration into active pharmaceutical ingredient production. For New Entrants and Emerging Players: Telemedicine-integrated diagnostic platforms offer the most penetrable entry vector. Target community oncology practices in Florida and Texas where independent infusion center licensing enables rapid site-of-care capture. Pursue subcutaneous formulation development to bypass hospital-centric procurement and capture ambulatory clinic volumes. Partner with Japanese home-visit nursing associations to pilot residential administration protocols for maintenance regimens. For Investors and Strategic Acquirers: Re-rating potential sits with bi-specific antibody developers given accelerated FDA breakthrough therapy designations compressing clinical timelines. Long-term viability favors platforms with demonstrated manufacturing scalability and companion diagnostic pairing capabilities. Monitor PMDA Sakigake designation announcements as the critical signal for Japanese market access inflection. Prioritize targets with established real-world evidence infrastructure to satisfy EU AI Act algorithmic transparency mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Self-administered delivery displaces hospital infusion models and captures ambulatory clinic volumes in Germany. |
| Bioreactor Capacity Expansion | Captive manufacturing secures supply continuity against demand surges for approved checkpoint inhibitors. |
| Companion Diagnostic Pairing | Algorithmic biomarker platforms standardize patient stratification for BRAF/MEK inhibition sequences in French cancer centers. |
| Real-World Evidence Infrastructure | Robust pharmacovigilance systems satisfy EU AI Act algorithmic transparency requirements for post-marketing registries. |
| PMDA Priority Review Filing | Sakigake designation accelerates Japanese market access for novel combination protocols in Tokyo and Osaka centers. |
Methodological Framework
Multi-period observation of FDA approval timelines, EMA label expansions, and PMDA Sakigake designations anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-volume modeling across therapy lines and administration settings was triangulated against top-down manufacturer revenue disclosures.
Segment-weighting approaches applied differential growth assumptions across intravenous, subcutaneous, and oral delivery modes, with treatment line, dosage form, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns for immuno-oncology agents. Forecast inputs incorporated AMNOG benefit assessment outcomes and 340B pricing eligibility trends.
The model holds under stable reimbursement frameworks for premium biologics; deviation in biosimilar acceleration or cold-chain logistics disruption would shift volume projections. Forecasts reflect documented assumptions regarding regulatory pathway timelines and site-of-care migration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market
Specialty Medicine
Hepatic Insufficiency/Liver Failure Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Global Childhood Absence Epilepsy Treatment Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Progressive Multifocal Leukoencephalopathy Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
Solid Tumor Therapeutics Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Immunology Market
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market