
 Anterior Uveitis Market | 2026-2036
Anterior Uveitis Market Size, Share, and Industry Trends Forecast 2026-2036
Anterior Uveitis Market Analysis
Aftermarket service revenue from sustained patient monitoring and retreatment protocols is reconfiguring profitability models across the anterior uveitis landscape. Novartis AG leverages its ophthalmology franchise breadth to sustain global distribution reach. Clearside Biomedical anchors its position through suprachoroidal delivery technology that differentiates administration precision. Santen Pharmaceutical Co., Ltd. competes on manufacturing scale across Asian and European markets.
Anterior uveitis constitutes inflammation of the iris and ciliary body, typically presenting with aqueous humor cell infiltration, flare, and variable pain or photophobia; corticosteroids remain the foundational pharmacologic intervention to suppress immune-mediated tissue damage. Biologics command expanding share among refractory non-infectious cases where conventional immunosuppressants fail. Topical therapy dominates first-line treatment, though combination therapy grows fastest as clinicians sequence multiple mechanisms to achieve durable remission.
The FDA regulates ocular corticosteroid and biologic approvals under ophthalmology-specific efficacy and safety benchmarks, while the EMA's MDR framework imposes post-market surveillance obligations on European device-drug combination products. Health Canada and Japan's PMDA maintain aligned but distinct sterility and endotoxin standards for intraocular formulations. Stakeholders must monitor evolving biosimilar entry pathways and payer evidence requirements for novel mechanisms.
Market Dynamics
The anterior uveitis market pivots on the FDA's accelerated approval pathways, which compress development timelines for ocular inflammation therapies and force competitors to front-load clinical evidence generation. This regulatory velocity is reshaping how biologics displace conventional corticosteroids in refractory care protocols.
Growth Catalysts
- Specialty clinic infrastructure:Ophthalmology clinics in the United States are expanding biologic therapy adoption for refractory non-infectious cases, creating sustained demand for advanced immunomodulators.
- EMA MDR framework:Post-market surveillance obligations on European device-drug combination products are elevating quality standards and rewarding manufacturers with robust pharmacovigilance systems.
- Suprachoroidal delivery technology:Precision administration methods are reducing systemic exposure risks and expanding the treatable patient population beyond topical-responsive cases.
Market Restraints
- Intraocular formulation sterility costs:Endotoxin testing and aseptic manufacturing requirements for intraocular products impose substantial cost premiums that limit price competitiveness.
- Biologic manufacturing concentration:Contract manufacturing for monoclonal antibodies concentrates among a limited supplier base in Switzerland and Ireland, creating supply vulnerability.
- Topical corticosteroid substitution:Low-cost prednisolone acetate formulations continue to capture first-line treatment, compressing biologic penetration in uncomplicated anterior uveitis.
Strategic Opportunities
- Japan's PMDA alignment:Converging sterility standards with Health Canada create streamlined regulatory pathways for manufacturers seeking multi-market entry.
- Retreatment protocol services:Aftermarket revenue from sustained patient monitoring and flare management represents underexploited recurring income streams.
- Biosimilar entry pathways:Evolving FDA and EMA guidance on ophthalmologic biosimilars opens white space for follow-on biologics in adalimumab-class molecules.
Industry Challenges
- Ocular immunology specialization gap:Fellowship-trained uveitis specialists remain concentrated at academic medical centers, limiting community access to advanced therapy.
- Combination therapy sequencing complexity:Clinicians face protocol fragmentation when integrating corticosteroids, immunomodulators, and biologics across variable disease trajectories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anterior Uveitis Market |
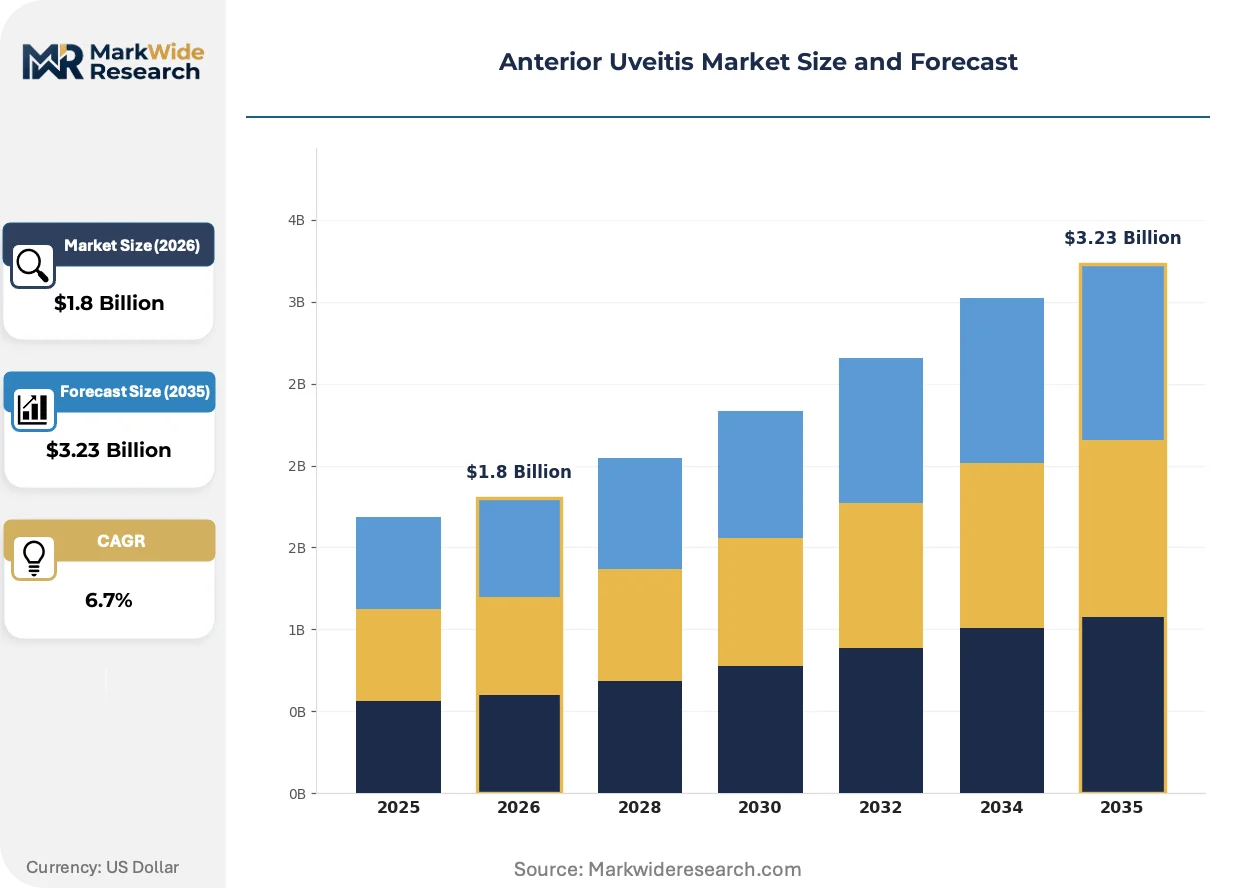
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
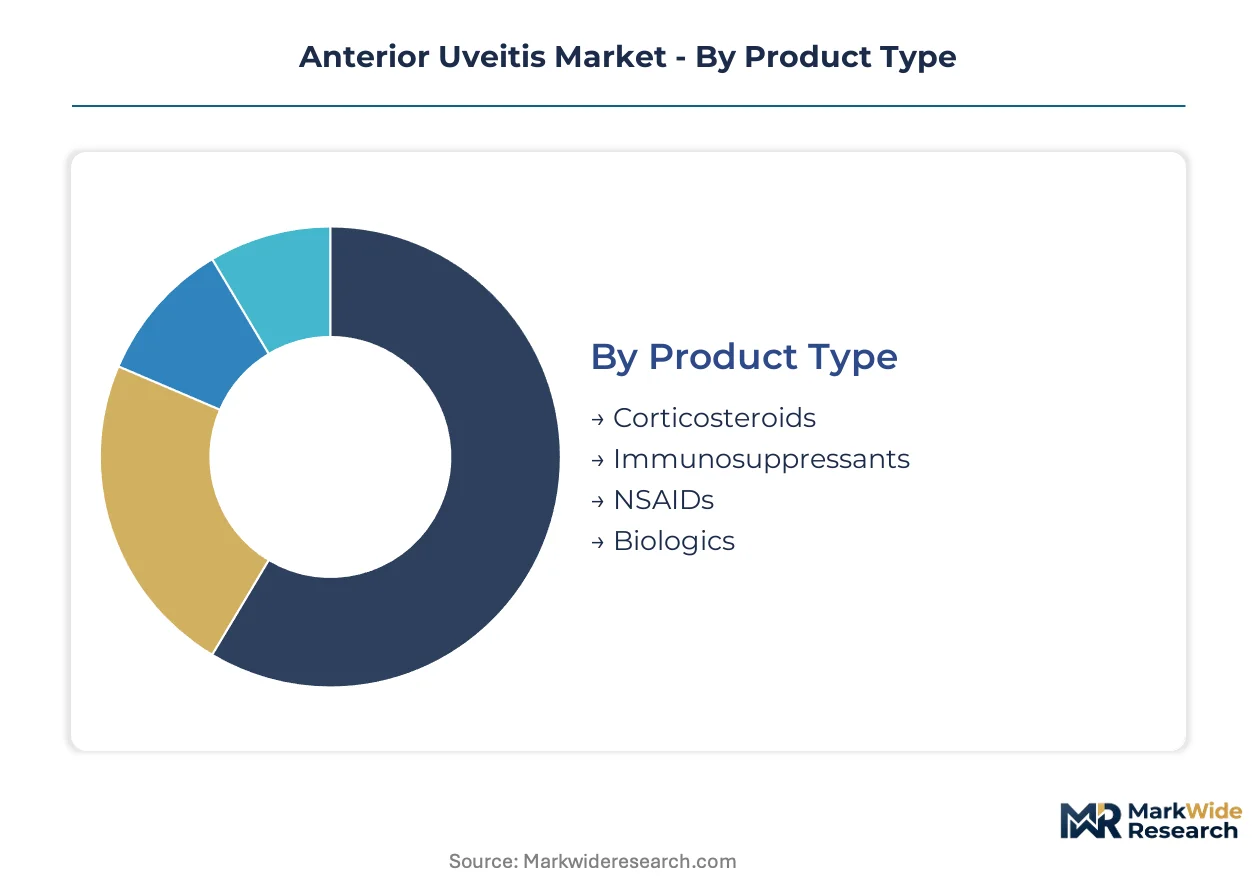
| Segmentation | Product Type: Corticosteroids, Immunosuppressants, NSAIDs, Biologics End User: Hospitals, Clinics, Specialty Eye Care Centers, Home Care Settings Treatment Approach: Topical Therapy, Systemic Therapy, Surgical Intervention, Combination Therapy Indication: Chronic Uveitis, Acute Uveitis, Non-infectious Uveitis, Secondary Uveitis |
| Companies Covered | Clearside Biomedical, Kiora Pharmaceuticals, Inc., Novartis AG, Oculis Pharma, Tarsier Pharma Ltd., Santen Pharmaceutical Co., Ltd., Aldeyra Therapeutics, Inc., Bausch Health Companies Inc., AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anterior Uveitis Market Emerging Trajectories
Delivery technology and regulatory science are converging to redefine therapeutic positioning in anterior uveitis. Three distinct vectors are compressing development cycles and reshaping competitive differentiation.
Suprachoroidal microinjection systems are migrating from experimental platforms to standard-of-care protocols in specialty ophthalmology practices. Academic medical centers in the United States and Germany are adopting these devices for posterior segment access without systemic exposure. The technology is enabling targeted corticosteroid deposition that compresses reliance on oral immunosuppressants in intermediate and panuveitis presentations.
EMA's Medical Device Regulation is imposing enhanced clinical evidence requirements on drug-eluting ocular implants. Manufacturers must now generate post-approval safety data comparable to pharmaceutical standards, elevating development costs but creating regulatory moats against undercapitalized entrants. European ophthalmology clinics are responding by consolidating procurement around established suppliers with proven pharmacovigilance infrastructure.
Academic detailing and formulary influence are displacing traditional pharmaceutical rep access in institutional purchasing decisions. Integrated delivery networks in the United States are centralizing biologic selection through pharmacy and therapeutics committees, compressing individual physician autonomy. This concentration is most visible in California and Massachusetts health systems, where outcomes-based contracting for uveitis biologics is becoming standard.
Anterior Uveitis Market Segmentation
Therapeutic complexity in anterior uveitis creates distinct service intensity profiles across product categories. Aftermarket revenue from retreatment protocols and sustained monitoring varies dramatically by segment, reshaping manufacturer profitability models.
Product Type:
After-sales-service intensity concentrates in biologics and immunosuppressants, where patient monitoring, dosing optimization, and adverse event management generate recurring revenue streams that extend well beyond initial prescription.
- Corticosteroids:Prednisolone acetate and difluprednate formulations dominate first-line intervention through topical drops and periocular injections. Demand clusters in United States community ophthalmology practices where prednisolone acetate substitution limits biologic penetration in uncomplicated presentations.
- Biologics:Adalimumab-class monoclonal antibodies and emerging IL-6 pathway inhibitors target refractory non-infectious cases with precision immunomodulation. Specialty eye care centers in Germany and the United States are expanding adoption for corticosteroid-sparing protocols, though manufacturing concentration in Switzerland and Ireland creates supply vulnerability.
- Immunosuppressants:Methotrexate, mycophenolate mofetil, and cyclosporine serve as corticosteroid-sparing bridges in intermediate-risk patients.
- NSAIDs:Ketorolac and bromfenac formulations address mild inflammatory presentations and postoperative prophylaxis.
Corticosteroids hold the largest share; momentum sits with biologics as clinicians sequence toward durable remission.
End User:
Cost tier stratification separates institutional purchasers from retail-channel buyers, with integrated delivery networks extracting volume discounts that community practices cannot match.
- Specialty Eye Care Centers:Academic medical centers and dedicated uveitis clinics concentrate fellowship-trained specialists and advanced diagnostic infrastructure. These facilities in Massachusetts and California health systems are centralizing biologic selection through pharmacy and therapeutics committees, compressing individual physician autonomy.
- Hospitals:Tertiary centers manage complex panuveitis presentations requiring multidisciplinary coordination with rheumatology and infectious disease services.
- Clinics:Community ophthalmology practices handle the majority of acute anterior uveitis presentations with topical protocols.
- Home Care Settings:Self-administered topical regimens and remote monitoring technologies are expanding treatable populations beyond clinic-dependent models.
Specialty eye care centers command premium pricing power; clinics represent the highest volume channel.
Treatment Approach:
Application severity dictates technology selection, with posterior segment involvement requiring precision delivery systems that anterior disease does not.
- Combination Therapy:Sequencing corticosteroids with immunomodulators and biologics across variable disease trajectories is gaining fastest as clinicians pursue durable remission. Academic detailing and formulary influence are displacing traditional pharmaceutical rep access in institutional purchasing decisions for these complex protocols.
- Topical Therapy:Eye drops and ointments remain the foundational administration route for anterior segment inflammation.
- Systemic Therapy:Oral corticosteroids and immunosuppressants address bilateral or posterior segment involvement.
- Surgical Intervention:Vitrectomy and implant procedures reserve for refractory cases with structural complications.
Topical therapy retains dominant volume; combination therapy is expanding most quickly as sequencing protocols mature.
Indication:
Customer risk profiles separate chronic management contracts from acute episode billing, with chronic cases generating predictable recurring revenue.
- Non-infectious Uveitis:Autoimmune and idiopathic presentations drive biologic eligibility and corticosteroid-sparing protocols. The FDA's accelerated approval pathways have compressed development timelines specifically for this indication, forcing competitors to front-load clinical evidence generation.
- Chronic Uveitis:Persistent inflammation exceeding three months requires sustained immunomodulation and generates substantial retreatment protocol revenue.
- Acute Uveitis:Sudden-onset presentations typically resolve with short-course topical therapy.
- Secondary Uveitis:Inflammation stemming from trauma, surgery, or systemic infection demands etiology-specific management.
Non-infectious uveitis anchors biologic revenue; chronic cases deliver the steadiest income streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturing for monoclonal antibodies concentrates in Switzerland and Ireland, creating supply vulnerability that shapes regional market access. Specialty eye care infrastructure and reimbursement frameworks determine therapeutic uptake across major economies. Regulatory velocity varies by jurisdiction, compressing development timelines in some markets while imposing extended surveillance obligations in others.
United States
Ophthalmology clinics expand biologic therapy adoption for refractory non-infectious cases, creating sustained demand for advanced immunomodulators. The FDA's accelerated approval pathways compress development timelines and force competitors to front-load clinical evidence generation. Massachusetts and California health systems centralize biologic selection through pharmacy and therapeutics committees, compressing individual physician autonomy in institutional purchasing.
Germany
Academic medical centers adopt suprachoroidal microinjection systems for posterior segment access without systemic exposure. The EMA's Medical Device Regulation imposes enhanced clinical evidence requirements on drug-eluting ocular implants, elevating development costs but creating regulatory moats. Berlin and Munich clusters concentrate fellowship-trained uveitis specialists and advanced diagnostic infrastructure for complex case management.
Japan
PMDA sterility standards for intraocular formulations align with Health Canada requirements, streamlining multi-market entry for manufacturers. Domestic manufacturing scale supports competitive positioning across Asian and European export markets. Tokyo and Osaka metropolitan areas host specialized ophthalmology centers that drive adoption of corticosteroid-sparing protocols in chronic management.
Switzerland
Contract manufacturing concentration for monoclonal antibodies creates supply chain leverage for biologic production serving global markets. Swissmedic maintains rigorous pharmacovigilance standards that reward manufacturers with robust post-market surveillance systems. Basel and Zurich regions anchor pharmaceutical R&D clusters with integrated ophthalmology franchise capabilities.
United Kingdom
NHS commissioning frameworks for specialty eye care create volume concentration around academic medical centers in London and the Southeast. MHRA post-Brexit regulatory pathways diverge from EMA alignment, requiring separate approval strategies for ocular inflammation therapies. Manchester and Birmingham clusters develop integrated delivery networks that centralize biologic procurement through formulary committees.
Anterior Uveitis Market Vendor Landscape
Pharmaceutical conglomerates and targeted delivery specialists split the market along technology-access and scale-manufacturing vectors. Consolidation concentrates among entities with ophthalmology franchise breadth or proprietary administration platforms. Three archetypes dominate: diversified pharma majors with global distribution reach, mid-cap biotechs with novel delivery mechanisms, and regional specialists with manufacturing scale advantages. Competitive moves center on technology licensing partnerships and geographic expansion through regulatory pathway optimization.
Within the diversified pharmaceutical tier, Novartis AG and AbbVie Inc. occupy positions anchored by ophthalmology franchise breadth and immunology pipeline depth. Clearside Biomedical exemplifies the targeted delivery specialist archetype, its suprachoroidal technology representing a distinct competitive vector. Santen Pharmaceutical Co., Ltd. sits within the regional scale-manufacturing tier, leveraging Asian and European production infrastructure. These three entities represent the strategic positioning spectrum: global distribution reach, administration precision differentiation, and multi-market manufacturing scale.
| Leading Market Players |
|---|
| Clearside Biomedical |
| Kiora Pharmaceuticals, Inc. |
| Novartis AG |
| Oculis Pharma |
| Tarsier Pharma Ltd. |
| Santen Pharmaceutical Co., Ltd. |
| Aldeyra Therapeutics, Inc. |
| Bausch Health Companies Inc. |
| AbbVie Inc. |
| Others |
Supply Flow & Price Mechanics
Monoclonal antibody contract manufacturing concentrates in Switzerland and Ireland, anchoring margin pools downstream with biologic developers who command premium positioning for refractory non-infectious anterior uveitis therapies. Endotoxin testing and aseptic manufacturing requirements for intraocular formulations impose cost premiums that limit price competitiveness in first-line corticosteroid substitution scenarios.
Pricing Analysis
FDA ophthalmology-specific efficacy benchmarks dictate the pricing tier structure across anterior uveitis therapeutics, separating premium biologics from standard corticosteroids and economy generic formulations. Price differentiation rests on certification grade for sterile manufacturing and after-sales service bundling for retreatment protocols. Pricing pressure stems from low-cost prednisolone acetate substitution in uncomplicated presentations, compressing margins for advanced immunomodulators. Community ophthalmology practices exhibit the highest price sensitivity, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates supply chain risk calculus for adalimumab-class monoclonal antibodies serving refractory anterior uveitis populations. Active pharmaceutical ingredient sourcing draws from Ireland, Switzerland, and Singapore for sterile biologic production. Single-source vulnerability concentrates in fill-finish capacity for intraocular formulations. Distribution runs through specialty pharmacy channels and integrated delivery network formularies, with hospital procurement committees exercising consolidated purchasing power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the anterior uveitis landscape creates multiple entry points, as the shift toward combination therapy sequencing splinters demand across corticosteroid, immunosuppressant, and biologic mechanisms.
For Market Incumbents: Entrench formulary position through backward integration into suprachoroidal delivery device manufacturing, securing proprietary administration platforms against emerging delivery specialists. Deepen pharmacovigilance infrastructure to satisfy EMA MDR post-market surveillance obligations, creating regulatory moats against undercapitalized competitors facing elevated clinical evidence requirements. For New Entrants and Emerging Players: Establish a beachhead in retreatment protocol services, capturing recurring revenue from sustained patient monitoring and flare management that incumbents underexploit. Target community ophthalmology practices in the United States with corticosteroid-sparing combination protocols, leveraging academic detailing to displace traditional pharmaceutical rep access. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap delivery technology specialists with FDA-cleared suprachoroidal platforms and established reimbursement pathways. Long-term viability hinges on convergence between precision administration and biosimilar entry economics. Watch for PMDA-Health Canada sterility standard alignment as the signal triggering accelerated multi-market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Suprachoroidal Delivery Platform Expansion | Clearside Biomedical's microinjection technology reduces systemic exposure risks for intermediate uveitis presentations. |
| Biosimilar Development Pathway | FDA evolving guidance on ophthalmologic adalimumab-class follow-ons opens white space for cost-competitive refractory therapy. |
| Retreatment Protocol Service Launch | Aftermarket revenue from sustained monitoring reconfigures profitability models beyond initial prescription capture. |
| EMA MDR Compliance Investment | Enhanced pharmacovigilance systems reward manufacturers with regulatory moats against undercapitalized European entrants. |
| Academic Medical Center Partnership | Massachusetts and California health system formulary centralization demands outcomes-based contracting capabilities. |
Methodological Framework
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchors the qualitative findings against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation constrain estimate variance across the analysis window.
Calibration against historical approval timelines and pricing trajectories informs the projection framework across therapeutic class, administration route, treatment line, and regional regulatory cluster dimensions. CAGRs derive from segmented growth rate aggregation and cross-referencing against immunology franchise revenue disclosures. Modeled inputs include retreatment protocol adherence rates and biosimilar penetration assumptions for adalimumab-class molecules.
Sensitivities concentrate around FDA accelerated approval pathway modifications, EMA MDR enforcement intensity, and monoclonal antibody manufacturing concentration disruptions. Forecasts reflect documented assumptions subject to revision from regulatory velocity shifts or supply chain reconfiguration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Eye Melanoma Market
Ophthalmology
Ocular Pain Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
US Ophthalmic Sutures Market
Ophthalmology
Synoptophore Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Global Tonometer Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Conjunctivitis Treatment Market