
 UV Water Sterilizer Market | 2026-2036
UV Water Sterilizer Market Size, Share, and Industry Trends Forecast 2026-2036
UV Water Sterilizer Market Insights
Commercial water treatment buyers is rotating toward UV sterilization as primary disinfrastructure, displacing legacy chemical-dependent operators in hospitality and foodservice. Trojan Technologies leverages its installed base across North American municipal contracts to sustain recurring lamp and ballast revenue. Xylem Inc. anchors its portfolio through vertical integration into UV reactor design and control software. Atlantium Technologies Ltd. differentiates via medium-pressure UV systems certified for pharmaceutical-grade water loops.
A UV water sterilizer employs ultraviolet-C radiation, typically at 254 nanometers wavelength, to inactivate microorganisms by disrupting DNA and RNA replication without chemical residual. The equipment comprises a quartz sleeve-protected mercury-vapor or LED lamp array, a stainless-steel reaction chamber, and UV intensity monitoring sensors for dose verification. Point-of-use devices command premium pricing in residential and restaurant segments where space constraints and immediate consumption patterns dominate purchasing criteria. Medium pressure systems capture expanding share in industrial use and aquaculture as operators seek single-pass log reduction at higher flow rates without chloramine formation. Whole house solutions remain volume-led through builder-channel partnerships in new construction markets.
EPA drinking water regulations and FDA food safety standards shape product certification requirements and installation protocols across the United States. NSF/ANSI 55 and 372 testing protocols govern material safety and UV dose performance claims, creating compliance barriers for uncertified imports. Stakeholders must monitor LED-UV source maturation and mercury restriction timelines to calibrate R&D allocation between incumbent lamp technologies and solid-state alternatives.
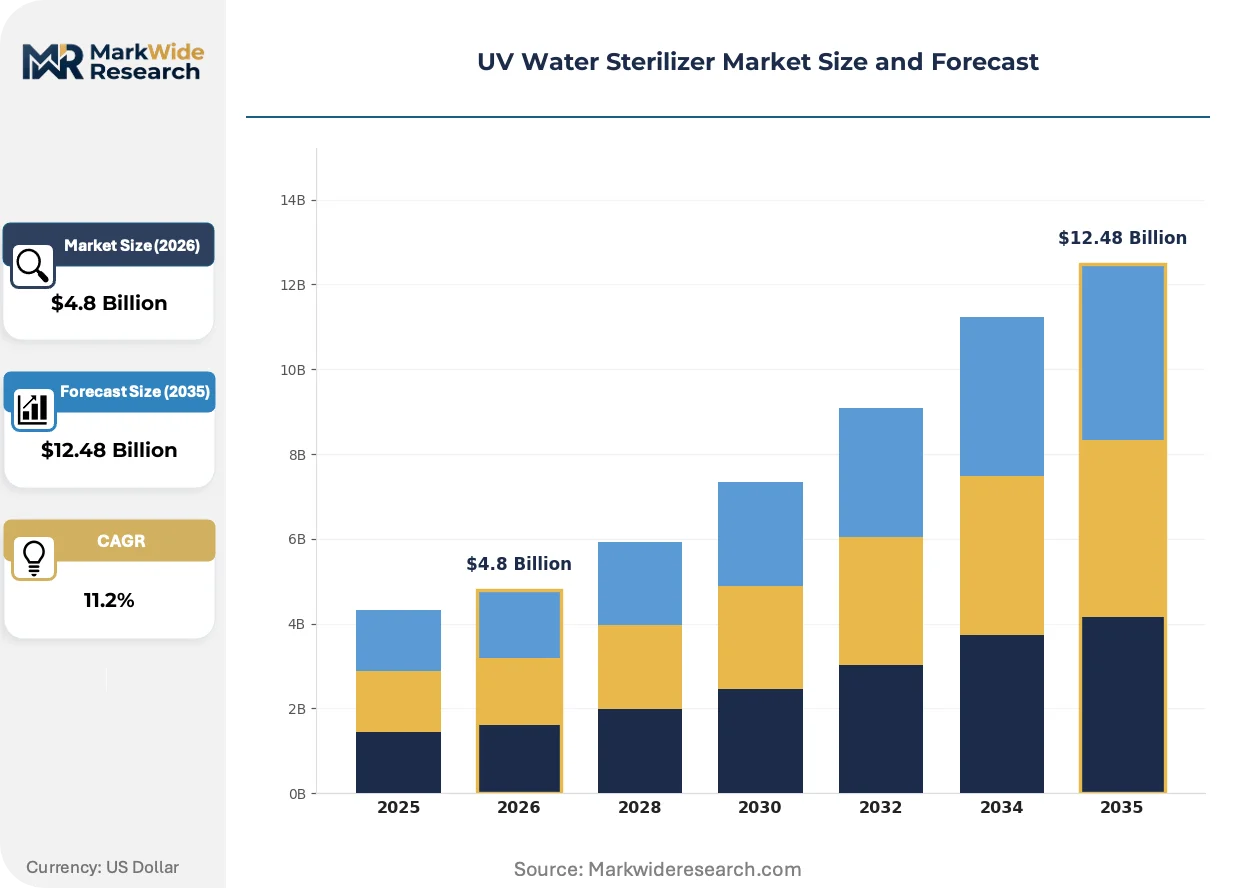
Market Dynamics
The UV water sterilizer market is restructuring around mercury-phaseout timelines and solid-state LED-UV maturation, as equipment buyers pre-position for lamp technology transitions while managing compliance with tightening drinking water mandates.
Growth Catalysts
- EPA Disinfection Mandates:Municipal water treatment plants across the United States face intensified surface water treatment rules, forcing capital deployment into UV infrastructure as primary or secondary disinfection barriers.
- Aquaculture Intensification:Recirculating aquaculture systems in Norway and Chile are adopting medium-pressure UV for pathogen control without antibiotic residues, creating specialized equipment demand.
- LED-UV Source Maturation:Solid-state ultraviolet emitters achieving 265-280 nanometer wavelengths at viable fluence rates are opening residential point-of-use segments previously unreachable by mercury-vapor constraints.
Market Restraints
- Quartz Sleeve Supply Concentration:High-purity fused quartz production concentrates among German and Chinese specialty glass manufacturers, exposing equipment makers to input bottlenecks and price volatility.
- Mercury Handling Restrictions:The Minamata Convention and EU RoHS amendments impose complex waste disposal protocols on low-pressure mercury lamp operators, elevating total cost of ownership.
- Flow Rate Limitations:Low-pressure UV systems face technical ceilings on maximum throughput per reactor volume, restricting single-pass economics for large-scale industrial users.
Strategic Opportunities
- India Smart Cities Mission:Urban water infrastructure upgrades under central government schemes are creating tender pipelines for decentralized UV treatment at district and building scales.
- Pharmaceutical Water-for-Injection Loops:FDA and EMA sterilization guidelines are widening the addressable market for validated medium-pressure systems with continuous monitoring capabilities.
- Ballast-as-a-Service Models:UV equipment OEMs are piloting subscription-based lamp replacement and intensity monitoring programs through IoT-connected reactor platforms.
Industry Challenges
- UV Dose Validation Expertise:Equipment installers and facility operators face acute shortages of technicians trained in bioassay validation and sensor calibration protocols.
- NSF/ANSI 55 Certification Timelines:Third-party testing for residential UV systems extends 12-18 months, compressing product launch windows against fast-moving LED technology cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Water Sterilizer Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Wall-Mounted Systems, Whole House Solutions, Point-of-Use Devices Application: Residential Use, Commercial Use, Industrial Use, Aquaculture Technology: Low Pressure Systems, Medium Pressure Systems, High Pressure Systems, Pulsed UV Technology End User: Households, Restaurants, Water Treatment Plants, Swimming Pools |
| Companies Covered | Xylem Inc., Trojan Technologies, Halma plc, Evoqua Water Technologies, Atlantic Ultraviolet Corporation, Atlantium Technologies Ltd., Aquafine Corporation, ProMinent GmbH, SUEZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Water Sterilizer Market Trends and Innovations
UV water sterilization technology is bifurcating between incumbent mercury-vapor optimization and solid-state disruption, with regulatory chemistry restrictions accelerating the transition timeline across all major procurement corridors.
LED-UV emitter technology is fragmenting competitive positioning in the point-of-use segment. These solid-state sources eliminate mercury handling liabilities while enabling instant-on operation and dimming control. Residential and foodservice buyers in Japan and South Korea are piloting compact under-sink units at accelerating volumes. The technology is fragmenting traditional lamp replacement revenue models toward semiconductor-style depreciation schedules.
REACH restrictions on mercury-containing products are compressing equipment procurement timelines across European municipal utilities. The ECHA authorization process is classifying certain mercury lamp categories as sunset materials, forcing early replacement cycles. German and Dutch water authorities are prioritizing LED-compatible reactor designs in tender specifications despite higher capital costs.
Specification authority is migrating from municipal engineering consultants to facility operators with direct operating cost accountability. Large hospitality chains and pharmaceutical manufacturers are internalizing UV system selection criteria, displacing traditional specifying engineer intermediaries. This concentration of decision rights is most visible in North American and Western European contract manufacturing and bottled water production facilities.
UV Water Sterilizer Market Segmentation
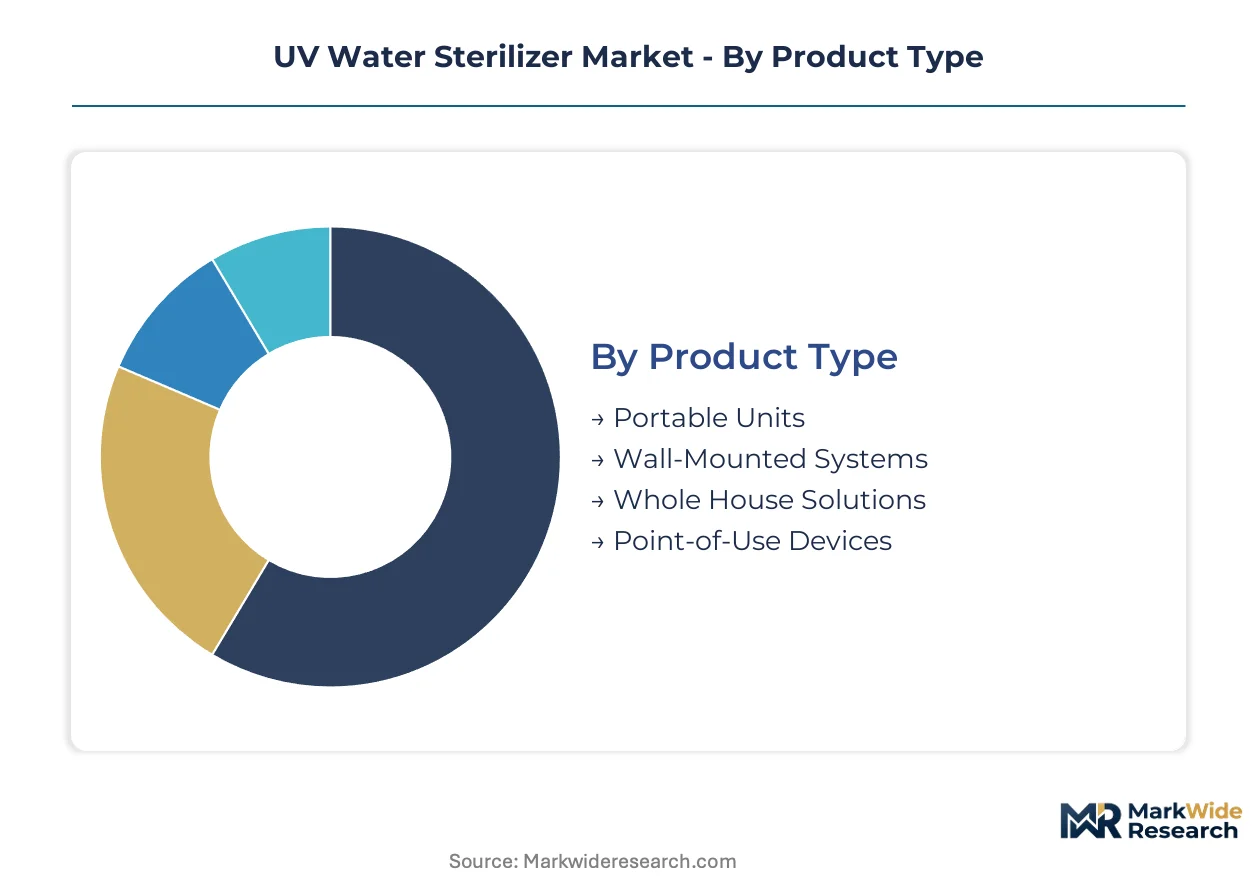
UV water sterilizer procurement patterns diverge sharply across installation scale and regulatory exposure. Equipment specification authority migrates toward end-users with direct operating cost accountability, fragmenting traditional engineering-consultant intermediation.
Product Type:
Domestic demand concentrates in permanently installed systems, while portable units serve export markets with infrastructure gaps. Commercial buyers rotate toward integrated solutions as primary disinfrastructure displaces chemical-dependent alternatives.
- Whole House Solutions:These centralized systems integrate with residential plumbing at main water entry points, processing 15-50 gallons per minute through stainless-steel reaction chambers. Builder-channel partnerships in new construction markets across the United States and Germany concentrate procurement volume, though mercury-phaseout timelines compress replacement cycles.
- Point-of-Use Devices:Compact under-sink or countertop units deliver immediate consumption sterilization through quartz-sleeved lamp arrays at 254 nanometers. Japanese and South Korean residential buyers pilot LED-UV variants at accelerating volumes, eliminating mercury handling liabilities while enabling instant-on operation.
- Wall-Mounted Systems:Fixed commercial installations serve foodservice and hospitality segments with NSF/ANSI 55 certification requirements.
- Portable Units:Mobile sterilization equipment addresses emergency response, military field operations, and developing-market infrastructure gaps.
Whole house solutions hold the largest share; momentum sits with point-of-use devices.
Application:
Cost-tier stratification separates capital-intensive municipal installations from recurring-revenue commercial service contracts. Volume concentration favors industrial-scale deployments with continuous monitoring requirements.
- Industrial Use:Pharmaceutical manufacturing and electronics fabrication demand validated medium-pressure systems with continuous UV intensity monitoring and FDA-compliant documentation protocols. German and Swiss chemical processors specify redundant reactor arrays for water-for-injection loops, creating premium equipment demand with 10-15 year validation cycles.
- Aquaculture:Recirculating systems in Norway and Chile deploy medium-pressure UV for pathogen control without antibiotic residues, addressing export market access requirements. Flow rates exceeding 500 cubic meters per hour force single-pass log reduction economics without chloramine formation byproducts.
- Commercial Use:Hospitality chains and bottled water facilities internalize UV selection criteria, displacing specifying engineer intermediaries.
- Residential Use:Homeowner procurement splits between new construction builder channels and retrofit aftermarket through plumbing contractors.
Industrial use commands premium pricing; aquaculture represents the steepest expansion trajectory.
Technology:
Supply concentration in high-purity fused quartz manufacturing exposes equipment makers to input bottlenecks from German and Chinese specialty glass producers. Technology transitions accelerate as mercury restriction timelines compress procurement decisions.
- Low Pressure Systems:Mercury-vapor lamps emitting at 254 nanometers dominate municipal procurement due to energy efficiency and established bioassay validation protocols. EPA surface water treatment rules across the United States force capital deployment into these systems as primary or secondary disinfection barriers.
- Medium Pressure Systems:Broad-spectrum mercury arc lamps achieve higher UV intensity per unit volume, enabling single-pass log reduction at elevated flow rates. ECHA authorization processes classifying certain mercury lamp categories as sunset materials force early replacement cycles in Dutch and German water authorities.
- High Pressure Systems:Specialized industrial applications requiring extreme UV flux densities for challenging wastewater matrices.
- Pulsed UV Technology:Emerging solid-state alternatives using xenon flashlamps for high-intensity, short-duration microbial inactivation.
Low pressure systems retain installed base dominance; medium pressure systems gain share in flow-rate-constrained applications.
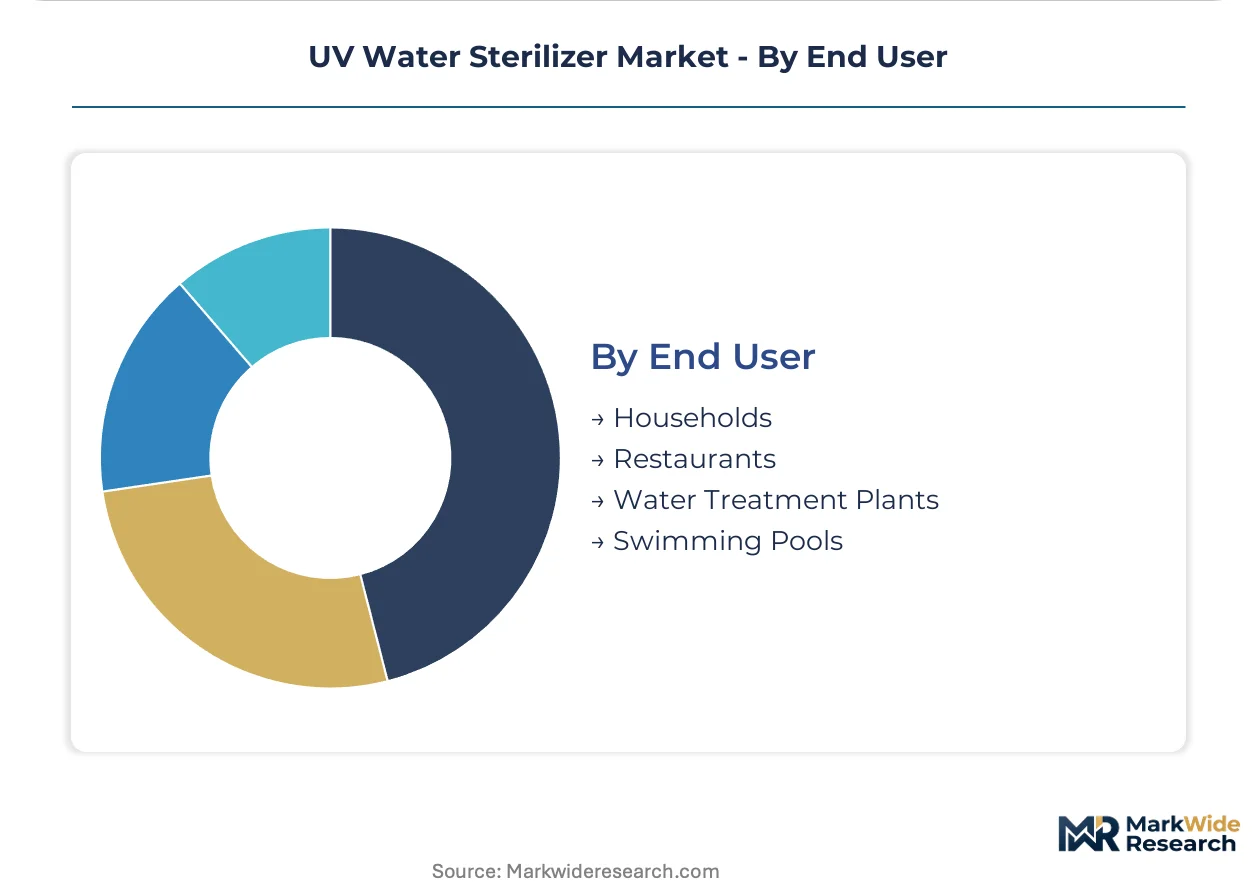
End User:
Customer-type fragmentation separates regulated utility procurement from discretionary residential purchasing. Margin structures favor institutional buyers with technical validation requirements over price-sensitive household segments.
- Water Treatment Plants:Municipal utilities across the United States face intensified EPA Long Term 2 Enhanced Surface Water Treatment Rule compliance, mandating UV infrastructure as Cryptosporidium barriers. Capital deployment concentrates in states with surface water dependence and aging combined sewer infrastructure.
- Restaurants:Foodservice operators adopt UV sterilization as primary disinfrastructure, displacing legacy chlorine-dependent systems under FDA Food Code enforcement. Large hospitality chains internalize specification authority, creating consolidated procurement volumes with standardized reactor platforms.
- Households:Residential buyers select based on space constraints and immediate consumption patterns, with LED-UV maturation opening previously unreachable segments.
- Swimming Pools:Commercial aquatics facilities deploy UV for chloramine reduction and secondary disinfection in high-occupancy environments.
Water treatment plants anchor equipment revenue; restaurants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal engineering consultants in Germany, water utility procurement officers in the United States, and district-level infrastructure planners in India concentrate equipment specification authority across the three dominant national corridors.
United States
Surface water-dependent utilities in Ohio and Pennsylvania deploy low-pressure UV reactors under EPA Long Term 2 Enhanced Surface Water Treatment Rule mandates. The regulation classifies UV as a Cryptosporidium barrier for systems serving over 10,000 persons. Trojan Technologies maintains installed base density across Great Lakes municipal contracts, capturing recurring lamp replacement revenue.
Germany
ECHA authorization processes under REACH designate certain mercury lamp categories as sunset materials, compressing replacement cycles for municipal operators. North Rhine-Westphalia water authorities prioritize LED-compatible reactor designs in tender specifications despite elevated capital expenditure. ProMinent GmbH anchors equipment supply relationships across Rhine-Ruhr industrial zones.
China
Central government water quality targets under the 14th Five-Year Plan accelerate UV adoption in Yangtze River Delta municipal networks. Shanghai and Jiangsu province utilities specify medium-pressure systems for combined sewer overflow treatment. Domestic fabricators compete on reactor vessel fabrication cost while importing high-purity quartz sleeves.
India
Smart Cities Mission funding channels capital toward decentralized UV treatment at district and building scales in Maharashtra and Karnataka. State pollution control boards mandate tertiary disinfection for sewage treatment plants in water-stressed basins. Mumbai and Bangalore municipal corporations tender compact skid-mounted systems for retrofit installation.
Japan
METI efficiency standards for water treatment equipment favor LED-UV maturation in residential point-of-use segments. Tokyo and Osaka metropolitan buyers pilot compact under-sink units with instant-on operation. Domestic semiconductor supply chains enable wavelength-optimized emitter sourcing for 265-280 nanometer applications.
UV Water Sterilizer Market Competitive Landscape
Player mix skews toward integrated water technology conglomerates with captive municipal contracting relationships. Market structure concentrates around three strategic archetypes: full-system integrators controlling reactor design and control software, component specialists dominating lamp and ballast supply, and regional fabricators competing on vessel fabrication cost. Competitive moves center on backward integration into quartz sleeve supply and IoT-enabled service subscription models.
Among North American integrated providers, Xylem Inc. and Trojan Technologies exemplify the conglomerate archetype through municipal installed base density. Atlantium Technologies Ltd. occupies a specialist position within medium-pressure system validation for pharmaceutical-grade applications. Halma plc represents the diversified industrial holding structure common among European water technology portfolios.
| Leading Market Players |
|---|
| Xylem Inc. |
| Trojan Technologies |
| Halma plc |
| Evoqua Water Technologies |
| Atlantic Ultraviolet Corporation |
| Atlantium Technologies Ltd. |
| Aquafine Corporation |
| ProMinent GmbH |
| SUEZ |
| Others |
Pricing and Supply Chain Analysis
LED-UV emitter substitution for mercury-vapor lamps simultaneously redraws procurement geography toward East Asian semiconductor supply clusters and compresses pricing premiums for solid-state systems as manufacturing scale accumulates. This technology transition fragments legacy lamp-replacement revenue models while elevating capital expenditure thresholds for reactor redesigns compatible with wavelength-optimized arrays.
Pricing Analysis
Mercury-vapor generation pricing gaps separate established low-pressure systems from emerging LED-UV alternatives and developmental pulsed-xenon platforms. Three-tier pricing structure across pharmaceutical-grade, municipal-certified, and residential-economy levels reflects NSF/ANSI 55 validation burden and quartz sleeve purity grades. Cost compression in residential point-of-use segments intensifies as Chinese LED packaging capacity expands. Municipal utilities exhibit lowest price sensitivity due to regulatory compliance mandates; household retrofit buyers demonstrate highest elasticity.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane elevate inbound logistics costs for German quartz sleeve fabricators serving North American OEMs. High-purity fused quartz production concentrates in Germany and China; mercury-arc lamp assemblies draw from Japanese phosphor coatings and American ballast electronics. Single-source vulnerability sits with specialty glass manufacturers. Distribution runs through municipal engineering consultants in developed markets and direct-to-utility procurement in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
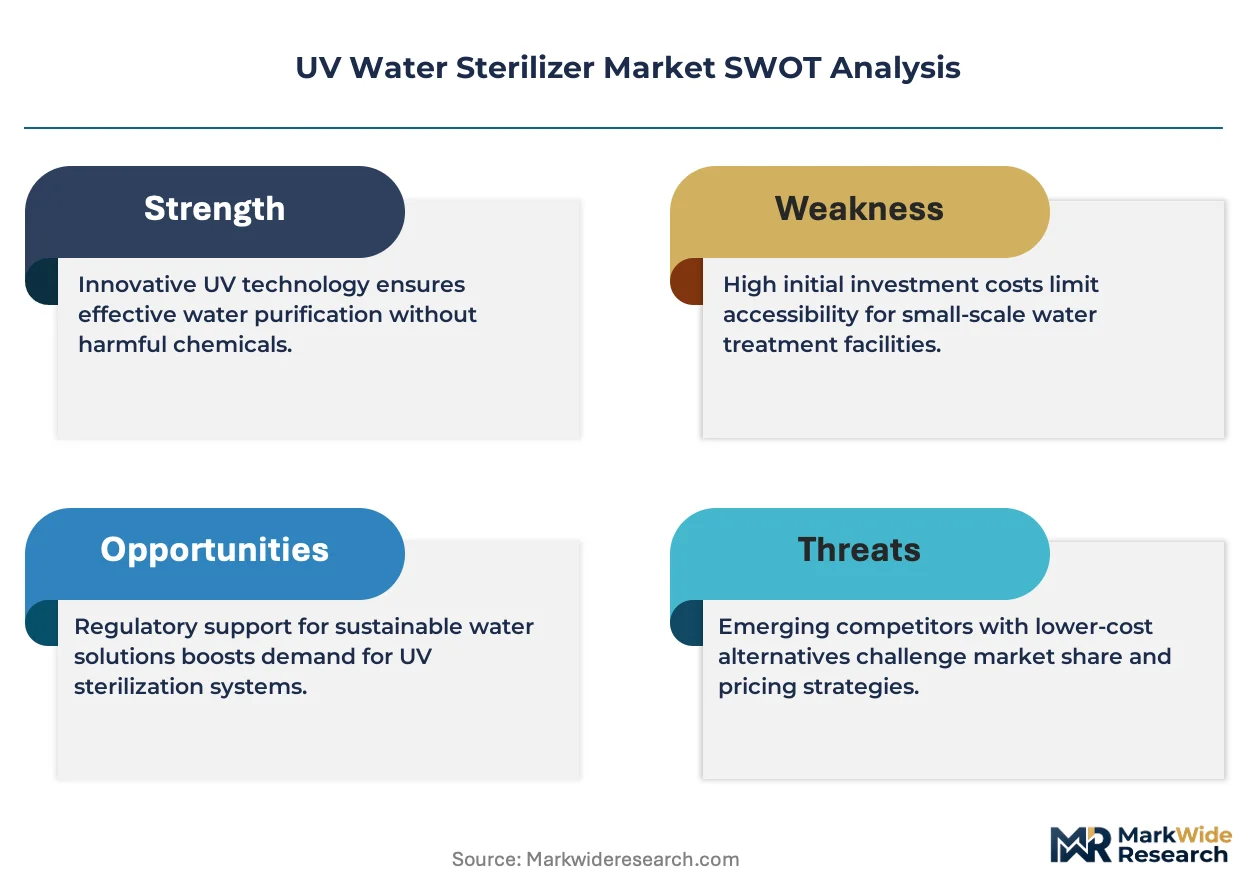
UV water sterilization represents a high-growth disruption as mercury-phaseout regulations across the European Union and Minamata Convention signatories force technology transitions ahead of natural replacement cycles.
For Market Incumbents: Shield installed base revenue by accelerating backward integration into quartz sleeve supply and pre-positioning LED-compatible reactor platforms before ECHA sunset designations broaden. Secure captive supply of high-purity fused quartz from German specialty glass manufacturers to neutralize input bottlenecks. Invest in IoT-enabled ballast monitoring to convert transactional lamp sales into recurring service subscriptions.
For New Entrants and Emerging Players: NSF/ANSI 55 certification fast-track through third-party testing partnerships opens residential point-of-use segments where validation timelines have historically blocked market access. Target Japanese and South Korean household buyers piloting LED-UV under-sink units at accelerating volumes. Pursue white-label manufacturing arrangements with domestic Chinese fabricators to compress capital requirements.
For Investors and Strategic Acquirers: The market sits at a regulatory-forced replacement phase that favors component specialists with validated medium-pressure platforms and captive quartz supply. Long-term viability centers on equipment OEMs capable of bridging mercury-vapor installed base service with LED-UV new-build capture. Monitor ECHA authorization expansion as the decisive inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Quartz Sleeve Backward Integration | German and Chinese specialty glass supply concentration creates vulnerability for equipment OEMs without captive sourcing. |
| LED-UV Platform Launch | 265-280 nanometer emitter maturation opens residential segments previously unreachable by mercury-vapor constraints. |
| IoT-Enabled Service Subscription | Ballast-as-a-Service models through connected reactor platforms convert transactional revenue to recurring streams. |
| Pharmaceutical Validation Partnership | FDA and EMA sterilization guidelines widen addressable market for continuous-monitoring medium-pressure systems. |
| Smart Cities Mission Tender Capture | India central government schemes channel capital toward decentralized UV treatment at district and building scales. |
Research Methodology
Operator-level perspectives from municipal water utility engineers, pharmaceutical facility validation managers, aquaculture system operators, and hospitality procurement directors anchored the qualitative base. Primary interview findings combined with EPA regulatory filings, ECHA authorization databases, NSF certification registries, and municipal tender documentation. Bottom-up equipment shipment analysis and top-down infrastructure spending estimates provided triangulation across data sources.
Sensitivity analysis around mercury-phaseout timelines and LED cost curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, technology generation, and end-user regulatory exposure. CAGRs derived from equipment procurement pipeline analysis and replacement cycle assumptions. Forecast inputs incorporated quartz sleeve supply constraints and REACH restriction implementation schedules.
The analysis sits within stated boundaries; outcomes outside ECHA regulatory acceleration or LED emitter cost breakthroughs would require recalibration. Forecasts reflect documented assumptions regarding municipal capital deployment timelines and residential technology adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Water Treatment Ozone Generator Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market
Water Treatment Systems
Point of Use Water Treatment Systems Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Water Treatment As a Service Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Global Residential Water Treatment Devices Market