
 Industrial Wastewater Treatment Equipment Market | 2026-2036
Industrial Wastewater Treatment Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wastewater Treatment Equipment Market Outlook
Remote monitoring subscriptions is decoupling capital equipment sales from long-term vendor relationships in this sector. Veolia Water Technologies leverages its digital service platform to anchor recurring revenue streams across municipal and industrial accounts. SUEZ SA competes through specialized chemical treatment packages that sustain margin pools in high-salinity applications. Evoqua Water Technologies differentiates with membrane bioreactor expertise that controls niche positions in pharmaceutical effluent.
Industrial wastewater treatment equipment encompasses physical, chemical, and biological systems engineered to remove contaminants from process water before discharge or reuse, typically operating at flow rates from thousands to millions of gallons per day with effluent targets measured in parts per million for suspended solids and biochemical oxygen demand. Membrane bioreactors are leading technology investments due to their compact footprint and superior effluent quality for water-stressed industrial zones. Chemical treatment maintains mature, stable demand in mining and metals processing where pH adjustment and heavy metal precipitation remain non-negotiable. Small and medium scale capacity segments concentrate margin pools in food processing and specialty manufacturing where modular, skid-mounted units reduce installation downtime.
The EPA enforces effluent limitation guidelines that force continuous capital reinvestment in treatment upgrades across U.S. manufacturing corridors. The EU Urban Wastewater Treatment Directive and REACH framework shape product chemistry approvals and discharge standards for equipment deployed across European industrial basins. China's MEE applies dual carbon goals that tighten energy-efficiency requirements for aeration and anaerobic digestion systems. Stakeholders must weigh regulatory trajectory against technology refresh cycles when committing to multi-decade equipment platforms.
Market Dynamics
Membrane bioreactor retrofits are compressing installation footprints while EPA effluent limitation guidelines force continuous capital reinvestment across U.S. manufacturing corridors, creating a dual pressure on equipment vendors to deliver higher performance at lower total cost of ownership.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:Tightened discharge standards across German chemical processing clusters are accelerating membrane bioreactor installations in Rhineland industrial basins.
- Semiconductor fabrication water reuse:Taiwan and South Korean chip foundries are prioritizing zero-liquid discharge systems to meet intensifying water recovery mandates.
- Anaerobic digestion energy capture:Food processing facilities in the Netherlands are deploying advanced biogas recovery systems to offset carbon intensity under EU Green Deal compliance pathways.
Market Restraints
- Specialized membrane supply concentration:Hollow-fiber ultrafiltration modules depend on concentrated Japanese and German polymer suppliers, exposing procurement to geopolitical friction.
- Energy cost volatility:Aeration systems consume 60-70% of biological treatment operating expenditure, making electricity price spikes a direct margin compressor.
- REACH chemical authorization delays:Novel coagulant chemistries face extended European Chemicals Agency review timelines, slowing product refresh cycles.
Strategic Opportunities
- India pharmaceutical effluent:CDSCO environmental compliance deadlines for active pharmaceutical ingredient manufacturers are opening demand for tertiary treatment skids in Hyderabad and Ahmedabad clusters.
- Digital twin convergence:Integration of computational fluid dynamics with IoT sensor networks enables predictive maintenance contracts that decouple vendor revenue from equipment replacement cycles.
- CSRD disclosure mandates:European corporates must report water stress exposure, creating advisory and monitoring service attach rates for equipment vendors.
Industry Challenges
- Process control engineering scarcity:Automated dissolved oxygen and nutrient dosing systems require specialized programming talent that outpaces vocational training pipeline output.
- Legacy SCADA integration:Brownfield chemical plants operate 1990s-era distributed control systems that resist API connectivity with modern cloud-based analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wastewater Treatment Equipment Market |
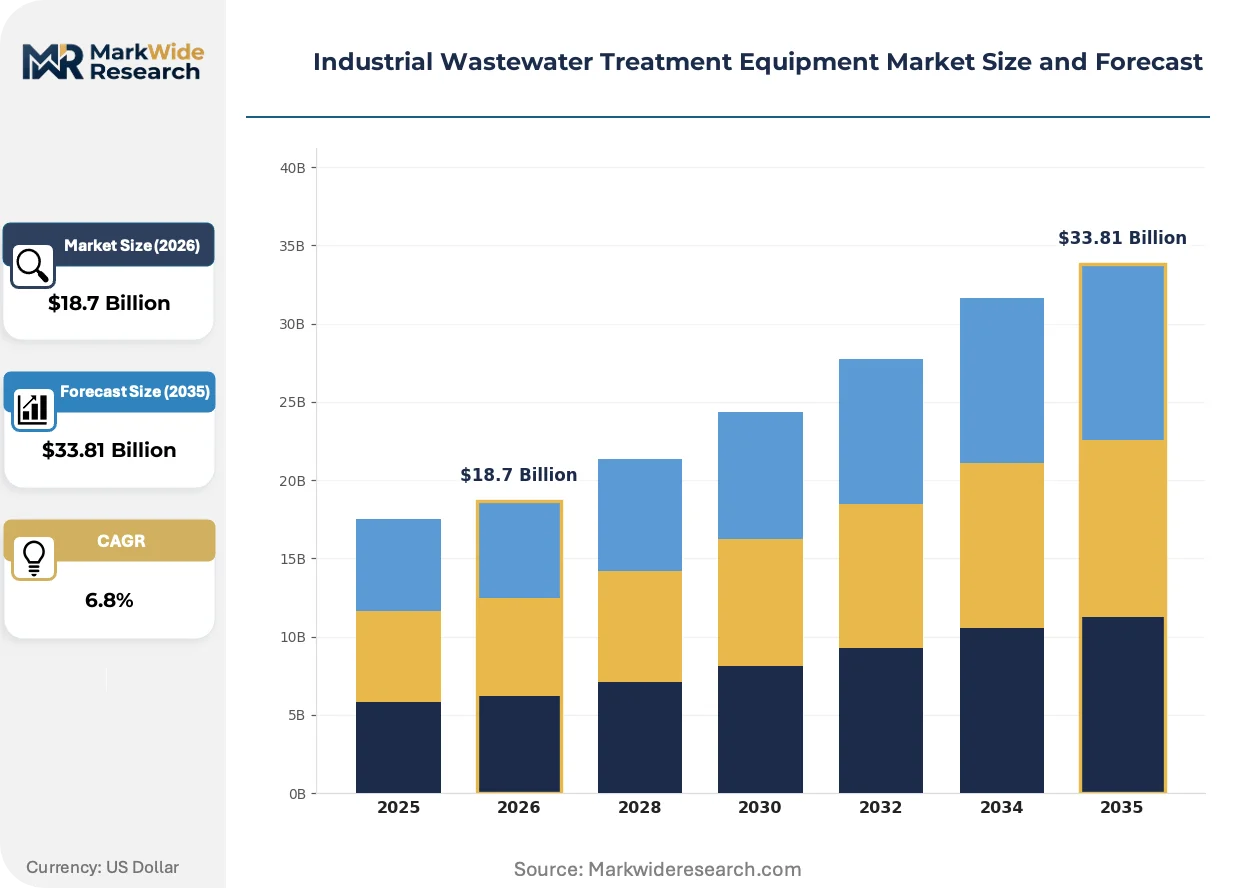
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Clarifiers, Filters, Membrane Bioreactors, Aeration Systems Technology: Aerobic Treatment, Anaerobic Treatment, Chemical Treatment, Physical Treatment End User: Manufacturing, Food Processing, Pharmaceuticals, Mining Capacity: Small Scale, Medium Scale, Large Scale, Custom Scale |
| Companies Covered | Veolia Water Technologies, SUEZ SA, Xylem Inc., Evoqua Water Technologies, Ecolab Inc., Aquatech International, Pentair plc, DuPont de Nemours, Kurita Water Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wastewater Treatment Equipment Market Strategic Shifts
Equipment vendors are rewiring revenue architecture around digital service layers while regulatory stringency compresses technology refresh cycles and buyer procurement patterns fragment across direct, distributor, and subscription channels.
Ceramic membrane filtration is rewriting competitive positioning in high-temperature industrial effluent applications. Steel mills and petrochemical complexes in Japan and Germany are piloting alumina and silicon carbide modules that withstand thermal shock and aggressive chemical cleaning protocols. These installations eliminate the polymer replacement cycles that dominate polymeric membrane life-cycle costing, compressing total cost of ownership comparisons against conventional separation technologies.
REACH framework amendments on persistent organic pollutants are forcing reformulation of anti-foam agents and biocides used in cooling tower blowdown treatment. Chemical suppliers must submit extended safety dossiers to ECHA, extending product qualification timelines from months to years. Pharmaceutical effluent treatment packages in Ireland and Belgium are most exposed, as these jurisdictions combine dense manufacturing concentration with proactive national enforcement of the updated substance restrictions.
Buyers are unbundling equipment procurement from long-term service agreements, fragmenting vendor relationships that once spanned fifteen-to-twenty-year horizons. Municipal utilities in the United Kingdom and Australian water authorities now separate capital tender evaluation from operations-and-maintenance contractor selection, enabling specialist firms to capture margin pools previously reserved for integrated suppliers. This pattern is most visible in membrane bioreactor deployments where process biology expertise and mechanical maintenance competence rarely coexist within single vendor organizations.
Industrial Wastewater Treatment Equipment Market Segmentation
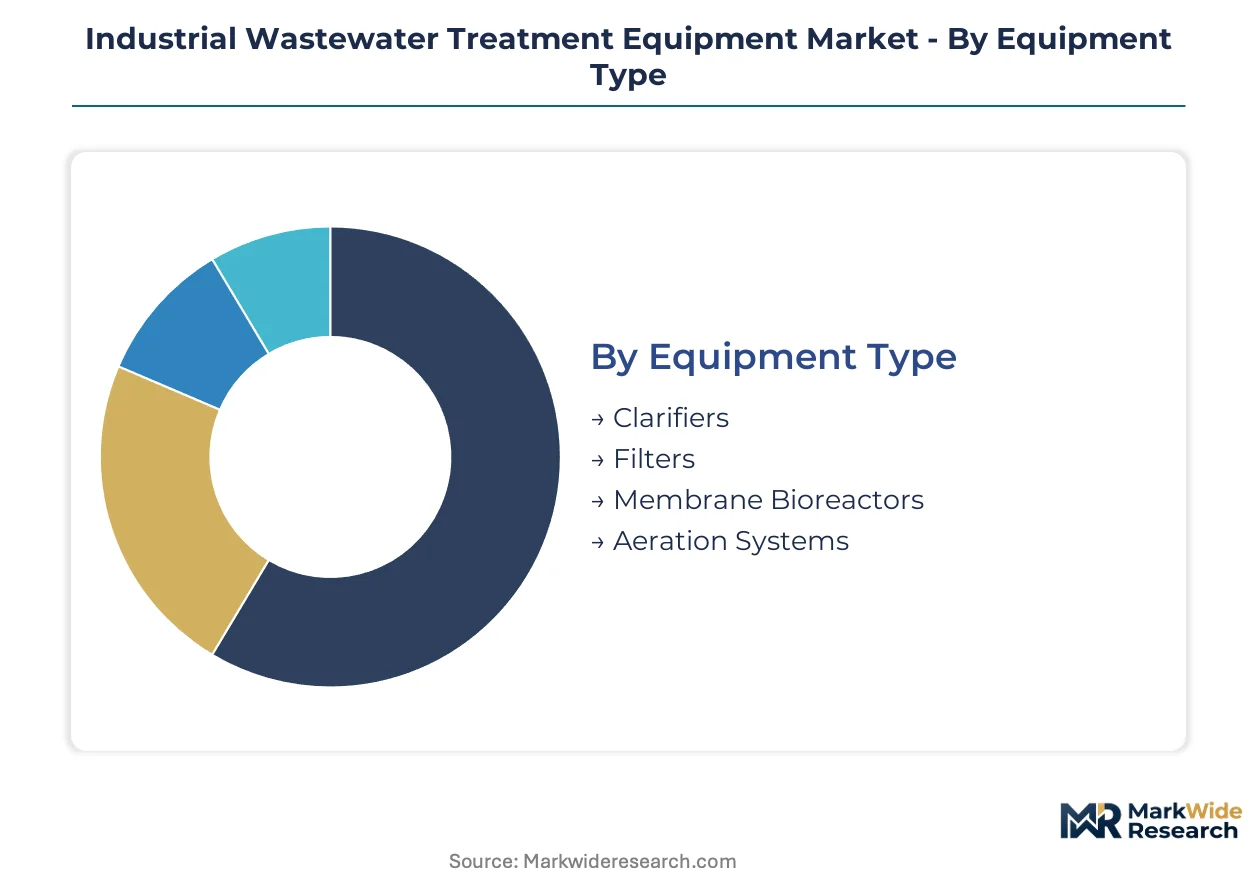
Technology refresh cycles and regulatory tightening create divergent replacement timelines across equipment categories. Vendors must align portfolio depth with the specific upgrade pressures each segment faces.
Equipment Type:
Replacement cycles vary sharply—membrane modules demand 5-7 year refresh intervals while concrete clarifiers operate 20-30 years, compressing vendor revenue windows in high-technology segments.
- Clarifiers:Gravity-driven sedimentation tanks with sludge collection mechanisms handle high-solids streams from mining and primary treatment stages. Municipal utilities in Germany and U.S. Great Lakes states prioritize these for heavy metals removal under tightened EPA effluent guidelines.
- Filters:Sand, multimedia, and activated carbon configurations target suspended solids and organic reduction. Food processing clusters in the Netherlands deploy these upstream of membrane bioreactors to protect downstream biological stages from grease and particulate loading.
- Membrane Bioreactors:Compact biological treatment with integrated ultrafiltration for pharmaceutical effluent in Ireland and Belgium.
- Aeration Systems:Fine-bubble diffusers and mechanical surface aerators dominate activated sludge plants across Taiwan semiconductor fabrication zones.
Volume placements concentrate in clarifiers; the faster expansion belongs to membrane bioreactors.
Technology:
Capital intensity and operating cost structures split procurement patterns—biological systems anchor long-term vendor relationships while chemical treatment favors commodity chemical suppliers.
- Aerobic Treatment:Activated sludge processes with oxygen-dependent microbial digestion achieve 90%+ BOD removal in food processing and municipal applications. Taiwanese chip foundries pair these with tertiary filtration to meet water reuse mandates under intensifying drought contingency protocols.
- Anaerobic Treatment:Oxygen-free digestion with biogas capture serves high-strength effluent from breweries and distilleries. Dutch food processors deploy covered lagoon and UASB configurations to offset carbon intensity under EU Green Deal compliance pathways.
- Chemical Treatment:Coagulation, flocculation, and pH adjustment systems dominate mining and metals processing in Germany and the United States.
- Physical Treatment:Screening, sedimentation, and flotation units provide primary treatment across manufacturing corridors in South Korea and Japan.
Capital deployment heaviest in aerobic systems; anaerobic configurations gain share fastest in carbon-constrained European basins.
End User:
Regulatory enforcement intensity and water stress exposure create tiered willingness-to-pay across vertical applications.
- Manufacturing:Automotive and electronics assembly plants generate metal-laden rinse waters and coolant blowdown. German chemical processing facilities in the Rhineland industrial basin invest in membrane bioreactor retrofits to meet EU Urban Wastewater Treatment Directive discharge standards.
- Food Processing:Dairy, meat, and beverage operations produce high-BOD effluent with seasonal volume spikes. Dutch anaerobic digestion installations capture biogas to offset energy costs under national carbon reduction frameworks.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturers in Hyderabad and Ahmedabad face CDSCO compliance deadlines driving tertiary treatment skid demand.
- Mining:Acid mine drainage and process water in Australian and Canadian operations require heavy metal precipitation and neutralization.
Installed base concentrates in manufacturing; pharmaceutical applications show steepest expansion trajectory.
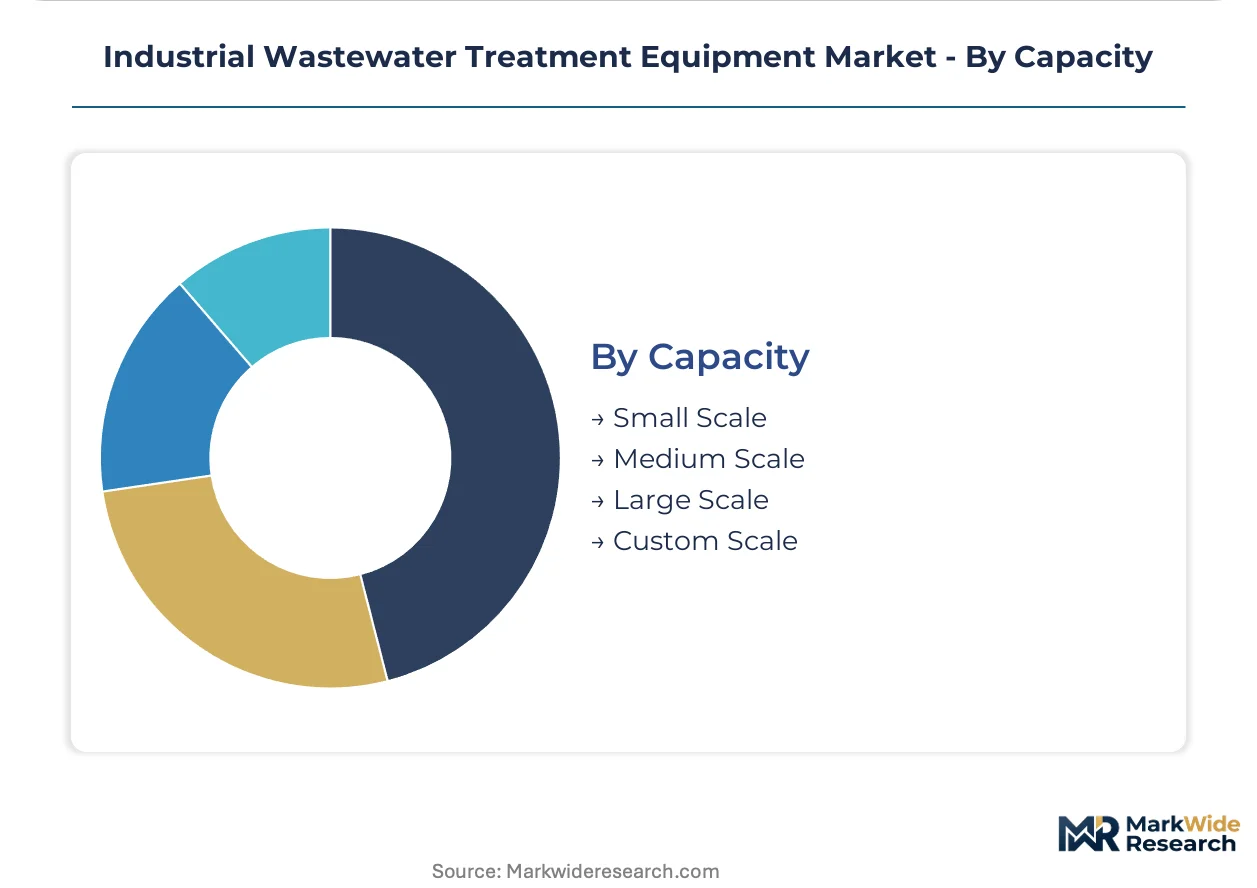
Capacity:
Project scale dictates procurement channel—direct vendor relationships dominate large installations while distributors and skid integrators capture modular opportunities.
- Small Scale:Packaged plants below 100,000 GPD serve remote mining camps and specialty food processors. Australian water authorities favor containerized membrane bioreactor units for decentralized industrial zones with limited grid infrastructure.
- Medium Scale:Skid-mounted systems from 100,000 to 1 MGD anchor food processing and specialty manufacturing. Modular configurations reduce installation downtime in Netherlands dairy operations facing seasonal production peaks.
- Large Scale:Custom-engineered facilities above 1 MGD serve petrochemical and steel complexes in Japan and Germany.
- Custom Scale:Site-specific designs for zero-liquid discharge at semiconductor clusters in Taiwan and South Korea.
Revenue pools concentrate in large-scale installations; custom-scale configurations climb fastest on chip fabrication water reuse mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in Germany, Japan, and the United States, while deployment tilts toward water-stressed manufacturing clusters in Taiwan, South Korea, and the Netherlands where semiconductor and chemical processing expansion drives absorption.
United States
EPA effluent limitation guidelines force continuous capital reinvestment across Great Lakes manufacturing corridors and Gulf Coast petrochemical complexes. Chemical processing facilities in Texas and Louisiana expand membrane bioreactor installations to meet tightened discharge standards. Pittsburgh and Cleveland industrial basins prioritize clarifier retrofits for heavy metals removal under updated EPA frameworks.
Germany
Rhineland chemical processing clusters anchor European demand for advanced biological treatment systems. EU Urban Wastewater Treatment Directive amendments accelerate membrane bioreactor deployments across North Rhine-Westphalia. Bavarian automotive plants invest in zero-liquid discharge configurations to meet REACH framework substance restrictions and CSRD water stress disclosure mandates.
Taiwan
Semiconductor fabrication water reuse mandates intensify procurement of custom-scale zero-liquid discharge systems. Hsinchu Science Park chip foundries deploy anaerobic digestion with biogas capture to offset carbon intensity under national dual carbon goals. Tainan and Taichung industrial zones prioritize ceramic membrane filtration for high-temperature effluent streams.
South Korea
Memory and logic chip fabrication clusters in Gyeonggi Province drive concentrated demand for ultrapure water recovery systems. National water reuse regulations tighten discharge limits for semiconductor process water. Busan-Ulsan petrochemical complexes pilot alumina membrane modules to withstand aggressive chemical cleaning protocols.
Netherlands
Food processing facilities in Friesland and Gelderland deploy advanced anaerobic digestion with biogas recovery to offset energy costs under EU Green Deal compliance pathways. Dairy operations facing seasonal production peaks favor modular skid-mounted configurations. Rotterdam chemical corridor investments align with REACH authorization timelines for novel coagulant chemistries.
Industrial Wastewater Treatment Equipment Market Competitive Environment
Top-tier vendors anchor integrated service platforms, while mid-scale specialists capture margin pools in membrane technology and chemical treatment niches. The vendor base stratifies across three tiers: full-service multinationals with digital service layers, regional technology specialists with process biology expertise, and commodity fabricators competing on equipment cost. Two dominant competitive moves reshape positioning: digital twin convergence decoupling vendor revenue from replacement cycles, and unbundling of equipment procurement from long-term service agreements fragmenting historical fifteen-to-twenty-year relationships.
Within the integrated service tier, Veolia Water Technologies and SUEZ SA exemplify archetypes competing through recurring revenue architectures versus specialized chemical treatment packages. Evoqua Water Technologies occupies a position among membrane bioreactor specialists controlling niche positions in pharmaceutical effluent applications. These three anchors represent divergent strategic postures: digital platform anchoring, chemical formulation depth, and membrane process expertise respectively.
| Leading Market Players |
|---|
| Veolia Water Technologies |
| SUEZ SA |
| Xylem Inc. |
| Evoqua Water Technologies |
| Ecolab Inc. |
| Aquatech International |
| Pentair plc |
| DuPont de Nemours |
| Kurita Water Industries |
| Others |
Value Chain & Pricing Dynamics
Polymer resin costs for hollow-fiber ultrafiltration modules cascade through three distinct pricing tiers, from premium ceramic configurations in Japanese steel mills to economy-grade polymeric skids for Australian mining camps, with energy-intensive aeration components amplifying regional electricity differentials.
Pricing Analysis
Margin tightening in membrane bioreactor retrofits reflects concentrated Japanese and German polymer supplier pricing power. Three-tier pricing structure across premium ceramic, standard polymeric, and economy skid-mounted configurations separates long-life alumina modules from replaceable hollow-fiber alternatives. Pricing pressure stems from energy cost volatility hitting aerobic system operating expenditure. Municipal utilities exhibit highest price sensitivity; semiconductor fabs in Taiwan and South Korea prioritize total cost of ownership over capital outlay.
Supply Chain Analysis
Process control engineering scarcity in German and U.S. manufacturing corridors constrains automation integration capacity. Equipment fabrication concentrates in Germany, Japan, and the United States, drawing from specialized polymer suppliers, precision ceramics foundries, and dissolved oxygen sensor manufacturers. Single-source vulnerability permeates hollow-fiber membrane procurement. Distribution runs through direct vendor relationships for large-scale installations and skid integrators for modular deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with captive digital service platforms, as unbundling of equipment procurement from long-term service agreements eliminates pure-play fabricators lacking recurring revenue architecture.
For Market Incumbents: Acquire predictive maintenance software capabilities to anchor subscription revenue streams. Integrate backward into ceramic membrane manufacturing to escape polymer replacement cycle dependency. Defend against specialist membrane bioreactor firms by embedding process biology expertise within digital twin platforms. For New Entrants and Emerging Players: EU CSRD disclosure mandates in Germany and the Netherlands open a window for water stress monitoring advisory services. Target pharmaceutical effluent tertiary treatment skids in Indian manufacturing clusters. Pursue channel partnerships with municipal engineering consultants to bypass entrenched vendor procurement relationships. For Investors and Strategic Acquirers: CDSCO compliance deadline acceleration in India is the leading indicator that regulatory enforcement intensity is shifting to emerging manufacturing basins. Position for five-to-ten year holding periods around membrane technology specialists with pharmaceutical vertical penetration. Watch for hollow-fiber polymer supply disruption as inflection signal for ceramic membrane substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Computational fluid dynamics convergence with IoT sensor networks enables predictive maintenance contracts at Taiwanese semiconductor facilities. |
| Ceramic Membrane Manufacturing Scale-Up | Alumina and silicon carbide module production in Japan and Germany eliminates polymer replacement cycles in high-temperature steel mill effluent. |
| Pharmaceutical Effluent Specialist Acquisition | Process biology expertise in active pharmaceutical ingredient treatment secures CDSCO compliance-driven demand in Hyderabad clusters. |
| Zero-Liquid Discharge System Expansion | Custom-scale configurations for South Korean chip foundries address intensifying national water reuse regulations. |
| Anaerobic Digestion Biogas Recovery Partnership | Covered lagoon and UASB deployments in Dutch food processing align with EU Green Deal carbon intensity offset pathways. |
Study Parameters
Multi-period observation of membrane module replacement intervals, EPA effluent guideline amendment timelines, and semiconductor fabrication water reuse mandate intensification anchored the trend analysis, supplemented by interviews with plant engineers at Rhineland chemical processing facilities, aftermarket service heads at membrane technology specialists, OEM procurement teams at Taiwanese chip foundries, and maintenance directors at U.S. Great Lakes manufacturing corridors. Secondary validation drew from EPA effluent limitation guideline dockets, EU Urban Wastewater Treatment Directive amendment records, CDSCO environmental compliance circulars, and SEC 10-K equipment vendor disclosures. Bottom-up equipment shipment tracking and top-down regulatory impact modeling were triangulated.
Input-output matrices mapped capital expenditure flows across equipment type, technology, end user, and capacity segments over the projection horizon. Modeled dimensions encompassed physical-chemical-biological treatment technology, small-medium-large-custom capacity tiers, and manufacturing-food-pharmaceutical-mining vertical applications. CAGRs were derived from regression analysis against regulatory enforcement intensity indices and water stress exposure metrics. Forecast inputs included semiconductor fabrication capacity expansion in Taiwan and South Korea and EU Green Deal carbon pricing trajectory.
The model assumes a particular technology adoption path; alternative pathways for ceramic membrane filtration would alter the outlook. Forecasts reflect assumptions around regulatory enforcement consistency, polymer supply chain stability, and energy cost normalization. Material deviation in EPA effluent guideline acceleration, REACH authorization delays, or hollow-fiber membrane supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
UV Water Sterilizer Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Commercial Water Filter Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
MENA Point of Use Water Purifiers Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market
Water Treatment Systems
Global RO Water Purifier Market
Water Treatment Systems
Water Desalination Equipment Market