
 Wastewater Recovery Systems Market | 2026-2036
Wastewater Recovery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Wastewater Recovery Systems Market Analysis
Food and beverage processing is broadening its share of wastewater recovery system procurement as discharge compliance costs escalate. Veolia leverages its integrated service model across European industrial clusters. Evoqua Water Technologies LLC anchors its position through specialized electrochemical treatment platforms for high-strength effluent. Koch Separation Solutions competes via membrane specialization in hydrocarbon-heavy process streams.
Wastewater recovery systems encompass engineered assemblies of physical, chemical, and biological treatment units designed to extract reusable water, energy, and nutrients from municipal or industrial effluent, typically achieving total dissolved solids reduction below 500 mg/L for non-potable reuse applications. These systems serve industries and utilities facing freshwater scarcity, discharge permit constraints, and circular economy mandates. Membrane bioreactor installations command premium pricing due to their compact footprint and consistent effluent quality, while activated sludge retrofits dominate mature municipal markets where operators seek incremental capacity without greenfield construction. Reverse osmosis skids concentrate margin pools in semiconductor and pharmaceutical end users demanding ultrapure feedwater generation from recovered sources.
The EPA enforces National Pollutant Discharge Elimination System permits that mandate technology-based effluent limits, directly compelling industrial facilities to upgrade recovery infrastructure or face operational shutdowns. China's MEE implements increasingly stringent surface water quality standards that redirect municipal investment toward advanced oxidation trains for emerging contaminant destruction. Stakeholders must monitor regulatory calibration cycles across these jurisdictions to anticipate capital deployment timing and technology specification shifts.
Market Dynamics
Membrane bioreactor technology is compressing treatment footprints and forcing activated sludge retrofits across industrial clusters, while EPA discharge enforcement tightens capital deployment timelines for food and beverage processors.
Growth Catalysts
- EPA NPDES permit enforcement:Industrial facilities face technology-based effluent limits that mandate recovery infrastructure upgrades or operational shutdowns.
- Semiconductor fabrication demand:Reverse osmosis skids for ultrapure feedwater generation are expanding procurement from recovered sources.
- China surface water standards:MEE mandates redirect municipal investment toward advanced oxidation trains for emerging contaminant destruction.
Market Restraints
- Membrane supply concentration:Polymeric membrane manufacturing clusters in select Asian economies create input vulnerability for system integrators.
- Energy cost volatility:Electrochemical treatment platforms face margin pressure from electricity price swings in European industrial zones.
- Technical limitation:High-strength hydrocarbon streams degrade conventional biological units, restricting applicability in petrochemical effluent.
Strategic Opportunities
- India municipal utilities:Water reuse infrastructure gaps in tier-2 cities create deployment white space for compact MBR packages.
- EU Green Deal circular economy mandates:Nutrient recovery from digestate streams opens revenue pools for phosphorus and nitrogen extraction technologies.
- Digital twin convergence:Real-time sensor networks fused with predictive algorithms enable outcome-based service contracts for remote monitoring.
Industry Challenges
- Process integration complexity:Legacy activated sludge basins require hydraulic reconfiguration to accommodate membrane train retrofits without greenfield construction.
- Certification timeline compression:NSF/ANSI 350 and ISO 30500 validation cycles delay commercialization for novel anaerobic membrane bioreactor designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wastewater Recovery Systems Market |
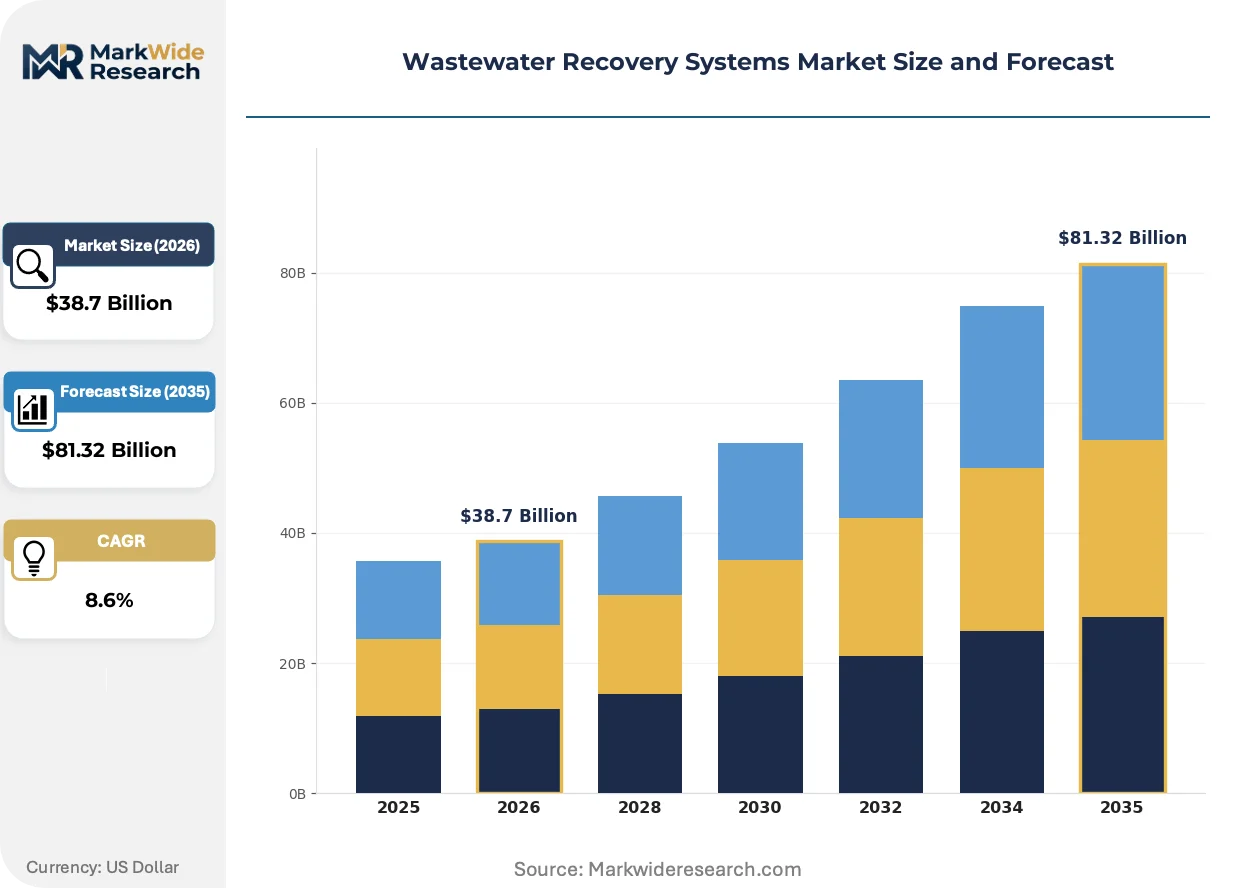
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Bioreactors, Activated Sludge, Reverse Osmosis, Advanced Oxidation End User: Municipalities, Industrial Facilities, Agriculture, Commercial Establishments Application: Recycling, Reuse, Treatment, Desalination Service Type: Consulting, Operation & Maintenance, Installation, System Integration |
| Companies Covered | Veolia, Evoqua Water Technologies LLC, Pall Corporation, Koch Separation Solutions, ClearBlu Environmental, Xylem Inc., SUEZ, Aquatech International LLC, Calgon Carbon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wastewater Recovery Systems Market Emerging Trajectories
Containerized treatment skids are collapsing project delivery timelines and enabling rapid deployment models that bypass traditional civil construction bottlenecks.
Forward osmosis draw-solute regeneration systems are decentralizing brine management economics for inland desalination and zero-liquid-discharge applications. Food and beverage processors in water-stressed regions are piloting these units to avoid costly deep-well injection permits. The technology is decentralizing the capital intensity barrier that previously restricted membrane-based recovery to coastal utilities with ocean discharge access.
REACH restrictions on per- and polyfluoroalkyl substances are forcing membrane manufacturers to reformulate hydrophobic coating chemistries. Industrial buyers now specify PFAS-free fluoropolymer alternatives in procurement tenders. European pharmaceutical and semiconductor end-users are accelerating qualification timelines for ceramic and polymeric substitutes.
Performance-based contracting is displacing equipment-only sales in municipal procurement. German and Dutch water authorities now structure payments around guaranteed effluent quality metrics rather than capital expenditure milestones. This shift compresses vendor cash conversion cycles but locks in decade-long service revenue streams.
Wastewater Recovery Systems Market Segmentation
Wastewater recovery systems fragment across four orthogonal dimensions that determine procurement patterns and vendor positioning. Technology selection dictates capital intensity and footprint constraints. Service packaging separates equipment suppliers from lifecycle revenue capture. Understanding these cross-currents reveals where margin pools concentrate and where commoditization threatens.
Technology:
Customization intensity spans from standardized modular skids to site-engineered process trains requiring extensive hydraulic reconfiguration.
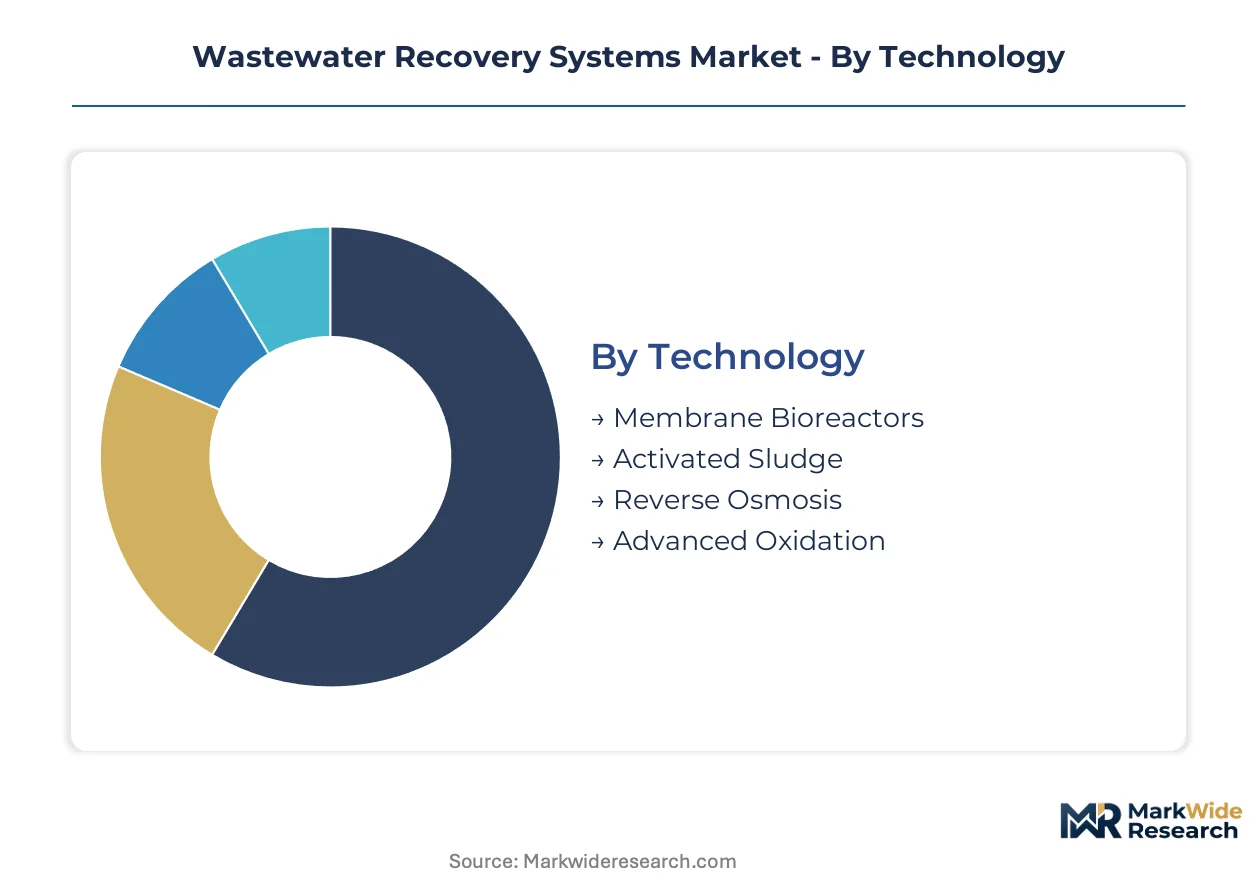
- Membrane Bioreactors:Compact aerobic biological treatment coupled with submerged or sidestream membrane filtration achieves consistent effluent below 5 mg/L TSS. Food and beverage processors in Germany and California deploy these units where footprint constraints block activated sludge expansion and EPA discharge limits tighten enforcement timelines.
- Reverse Osmosis:Spiral-wound or hollow-fiber membrane arrays operating at 10-80 bar generate permeate suitable for ultrapure feedwater applications. Semiconductor fabs in Taiwan and Arizona source these skids to convert municipal recovered water into process-grade supply, driven by fab water intensity exceeding 2,000 gallons per wafer.
- Activated Sludge:Conventional suspended-growth biological treatment remains the volume backbone for municipal utilities seeking incremental capacity without greenfield construction.
- Advanced Oxidation:Hydroxyl radical generation via ozone/UV or Fenton chemistry destroys emerging contaminants including pharmaceuticals and PFAS precursors.
Most installed capacity flows through Activated Sludge. Expansion is steepest in Membrane Bioreactors.
End User:
Procurement sophistication varies from municipal tender boards with decade-long amortization horizons to industrial operators optimizing for 18-month payback periods.
- Industrial Facilities:Process-integrated recovery systems addressing high-strength effluent from chemical, pharmaceutical, and hydrocarbon operations. Refineries in the US Gulf Coast and petrochemical clusters in Rotterdam deploy zero-liquid-discharge trains to eliminate discharge permit exposure entirely.
- Municipalities:Large-scale water reuse infrastructure serving populations exceeding 100,000, typically combining biological treatment with tertiary filtration and disinfection. Utilities in India and China prioritize these investments where surface water stress intersects with urban population growth.
- Agriculture:Nutrient recovery and irrigation-grade water production from livestock operations and food processing residuals.
- Commercial Establishments:Building-scale greywater and blackwater recovery for hotels, data centers, and institutional campuses seeking LEED certification or corporate sustainability targets.
Industrial Facilities command the highest unit pricing due to effluent complexity. Municipalities represent the largest aggregate contract value.
Application:
End-use water quality specifications stratify from irrigation-grade to ultrapure, determining pretreatment depth and monitoring intensity.
- Treatment:Discharge compliance-focused systems achieving regulatory effluent limits without reuse intent. Conventional activated sludge dominates this segment where receiving water body assimilation capacity remains adequate.
- Reuse:Non-potable applications including cooling tower makeup, toilet flushing, and landscape irrigation requiring tertiary filtration and disinfection. Singapore's NEWater program and California's Title 22 regulations establish the technical and regulatory template globally.
- Recycling:Closed-loop process water recovery within industrial facilities, particularly prevalent in semiconductor wafer fabrication and pharmaceutical manufacturing where water costs exceed $10 per cubic meter.
- Desalination:Brackish and seawater conversion for potable or industrial supply, typically employing reverse osmosis with energy recovery devices.
Treatment absorbs the majority of current capital deployment. Recycling is gaining share fastest as industrial water stress intensifies.
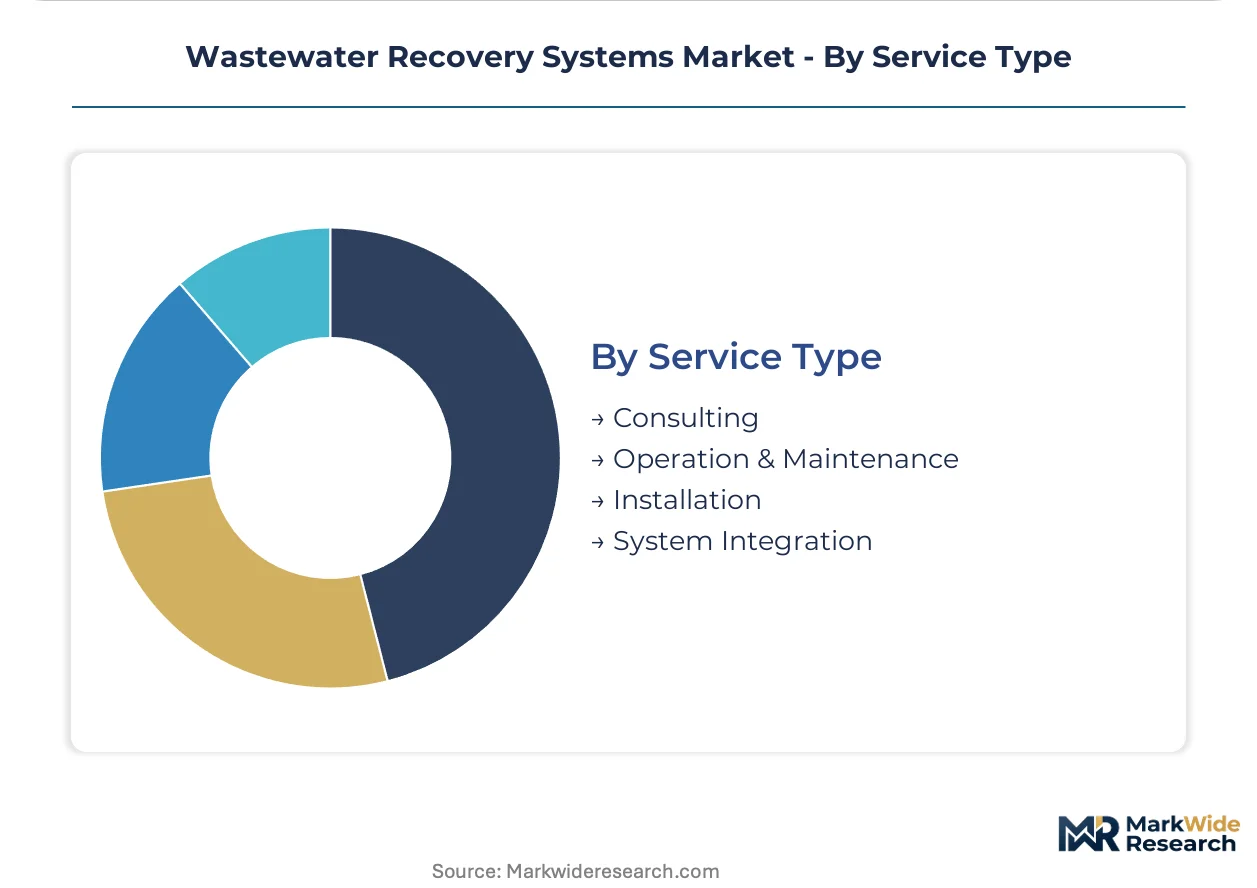
Service Type:
Revenue model evolution shifts from equipment margin capture toward annuity streams tied to performance outcomes.
- Operation & Maintenance:Long-term service contracts covering membrane replacement, chemical supply, and biological process optimization. German and Dutch water authorities increasingly structure 10-15 year agreements with payments indexed to effluent quality metrics rather than availability.
- System Integration:Turnkey design-build contracts combining process engineering, equipment procurement, and commissioning. Industrial clusters in the US Midwest and China's Yangtze River Delta favor this packaging to accelerate project timelines.
- Consulting:Feasibility studies, pilot testing, and regulatory permitting support preceding capital commitment.
- Installation:Civil works, mechanical erection, and control system integration for self-performing utilities or engineering-procurement-construction contractors.
System Integration captures the largest project value per contract. Operation & Maintenance delivers the most predictable recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial clusters in Germany's Ruhr Valley and China's Yangtze River Delta anchor procurement intensity for advanced membrane systems as discharge standards tighten across manufacturing belts.
United States
EPA NPDES permit enforcement drives capital deployment timelines for food and beverage processors in California's Central Valley. The agency's technology-based effluent limits compel facility upgrades. Semiconductor fabs in Arizona source reverse osmosis skids to convert municipal recovered water into ultrapure feedwater.
Germany
EU Green Deal circular economy mandates redirect municipal investment toward nutrient recovery from digestate streams. REACH restrictions on PFAS force membrane manufacturers to reformulate hydrophobic coating chemistries. Industrial clusters in North Rhine-Westphalia deploy zero-liquid-discharge trains to eliminate discharge permit exposure.
China
MEE surface water quality standards redirect municipal investment toward advanced oxidation trains for emerging contaminant destruction. Dual carbon goals accelerate membrane bioreactor deployments in water-stressed manufacturing zones. Petrochemical clusters in the Yangtze River Delta pilot containerized treatment skids to bypass civil construction bottlenecks.
India
Water reuse infrastructure gaps in tier-2 cities create deployment white space for compact MBR packages. Municipal utilities prioritize non-potable reuse systems where surface water stress intersects with urban population growth. Pharmaceutical manufacturers in Gujarat and Maharashtra pilot forward osmosis units to avoid costly deep-well injection permits.
Wastewater Recovery Systems Market Vendor Landscape
Strategic partnerships dominate the current landscape as system integrators seek membrane supply security and technology access. The vendor base organizes into three tiers: multinational water conglomerates with integrated service platforms, specialized membrane technology houses, and regional engineering contractors. Two archetypes define competitive positioning: full-lifecycle service providers capturing annuity revenue through performance-based contracts, and technology specialists commanding premium pricing in high-specification end uses. M&A activity concentrates membrane manufacturing assets, while capacity expansion targets containerized skid production for rapid deployment models.
Within the multinational tier, Veolia and SUEZ exemplify integrated service models spanning European industrial clusters. Xylem Inc. occupies a position among technology-forward specialists targeting digital twin convergence. Koch Separation Solutions sits within the membrane specialization archetype, competing in hydrocarbon-heavy process streams. These anchors reflect the market's bifurcation between scale-driven platform players and focused technology houses.
| Leading Market Players |
|---|
| Veolia |
| Evoqua Water Technologies LLC |
| Pall Corporation |
| Koch Separation Solutions |
| ClearBlu Environmental |
| Xylem Inc. |
| SUEZ |
| Aquatech International LLC |
| Calgon Carbon Corporation |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up membrane specialists have consolidated polymeric manufacturing assets across Japan, South Korea, and Germany, compressing supplier diversity while enforcing rigid price discipline on system integrators who lack backward integration into membrane production.
Pricing Analysis
Distributor margins on membrane bioreactor skids typically absorb 12-18 points before reaching municipal utilities, while direct-to-OEM channels for semiconductor-grade reverse osmosis units command steeper discounts tied to volume commitments. Project-based pricing stratifies across premium, standard, and economy tiers based on effluent quality guarantees and after-sales service bundling. Pricing pressure stems from energy cost volatility in European electrochemical treatment platforms, squeezing margins for operators without captive renewable supply. Municipal tender boards exhibit highest price sensitivity due to decade-long amortization horizons, whereas semiconductor fabs prioritize performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for containerized treatment skids, bypassing traditional engineering-procurement-construction intermediaries. Polymeric membrane manufacturing concentrates in Japan, South Korea, and Germany, with ceramic alternatives emerging from French and US specialty producers. Raw material dependencies span fluoropolymers for hydrophobic coatings, high-purity alumina for ceramic substrates, and specialty steel alloys for pressure vessel fabrication. Single-source vulnerability in perfluorinated membrane chemistries intensifies as REACH restrictions force formulation changes. Distribution runs through regional system integrators who bundle process engineering with equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through performance-based contracting shifts that capture decade-long service revenue streams, while containerized delivery models collapse project timelines and reduce customer acquisition costs.
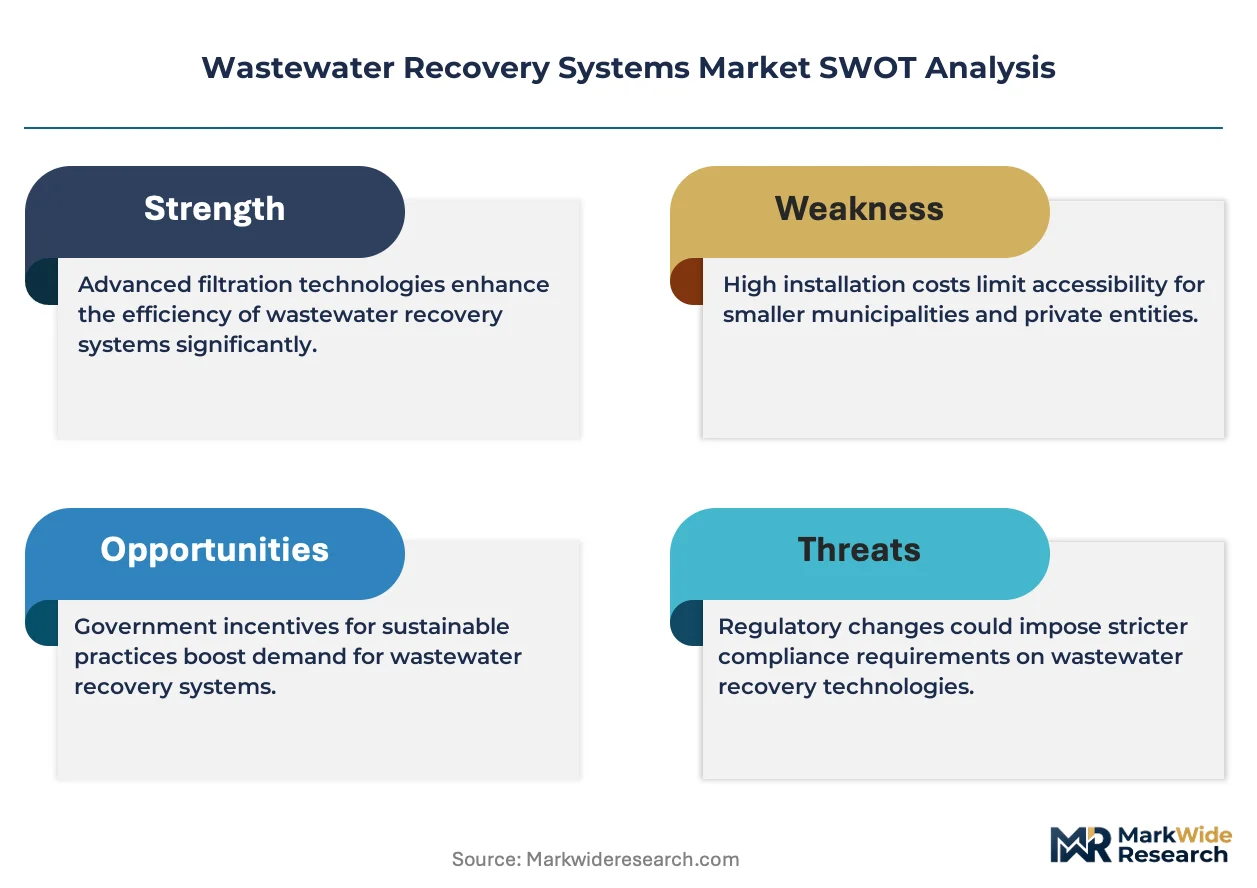
For Market Incumbents: Cement membrane supply security through captive manufacturing partnerships or tolling arrangements with Japanese and German specialty producers, insulating against REACH-driven formulation disruptions. Deepen vertical integration into digital twin platforms to lock in outcome-based service contracts before competitors replicate predictive algorithm capabilities. Prioritize certification investment in NSF/ANSI 350 validation to accelerate commercialization timelines for novel anaerobic membrane bioreactor designs. For New Entrants and Emerging Players: Enter via India's tier-2 municipal utilities where water reuse infrastructure gaps exceed incumbent service capacity, deploying compact MBR packages with rapid-deployment containerized formats. Target pharmaceutical manufacturers in Gujarat and Maharashtra piloting forward osmosis units to avoid deep-well injection permits, offering PFAS-free fluoropolymer alternatives under accelerated qualification timelines. Pursue white-label partnerships with established German system integrators lacking indigenous membrane manufacturing. For Investors and Strategic Acquirers: Valuations sit cheapest among regional engineering contractors with installed base access but no membrane technology ownership, offering bolt-on acquisition targets for multinational platform builders. Long-term viability hinges on exposure to circular economy mandate enforcement across EU member states and China's dual carbon goal implementation. Watch MEE surface water standard calibration cycles as the inflection signal for municipal capital deployment acceleration in China's Yangtze River Delta.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Supply Security Partnership | Captive access to Japanese and German polymeric production insulates against REACH formulation disruptions. |
| Containerized Skid Manufacturing Scale-Up | Collapses project delivery timelines for China's petrochemical clusters bypassing civil construction bottlenecks. |
| Performance-Based Contracting Transition | Locks in decade-long service revenue streams with German and Dutch water authorities. |
| Digital Twin Platform Integration | Enables outcome-based remote monitoring contracts through real-time sensor network fusion. |
| PFAS-Free Membrane Qualification | Accelerates European pharmaceutical and semiconductor procurement timelines ahead of regulatory deadlines. |
Methodological Framework
Coverage spans the United States, Germany, China, and India, with primary inputs from each combining structured interviews with municipal utility planning officers, industrial plant engineers, membrane technology R&D directors, and aftermarket service heads with secondary validation. Primary fieldwork drew from EPA NPDES permit databases, MEE surface water quality filings, EU Green Deal implementation trackers, and customs records of membrane import flows. Secondary sources integrated SEC 10-K disclosures from listed water technology conglomerates, trade association capacity surveys, and patent filing trend analysis. Bottom-up unit deployment tallies triangulated against top-down addressable market sizing.
Segmentation granularity modeled technology selection, end-user archetype, application water quality tier, and service packaging at the country level across the projection horizon. Technology splits captured membrane bioreactor, reverse osmosis, activated sludge, and advanced oxidation process economics. End-user dimensions separated municipal tender behavior from industrial procurement patterns. CAGRs derived from regression against regulatory enforcement intensity indices and industrial water stress metrics. Forecast inputs incorporated semiconductor fab water intensity benchmarks and food and beverage discharge compliance cost trajectories.
Inputs from utility planning officers and membrane manufacturing technical directors were available through the study window; gaps in forward-looking municipal budget appropriation data introduce uncertainty bands around India and China deployment timelines. Forecasts reflect documented assumptions regarding regulatory calibration cycles and energy price trajectory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Water Desalination Equipment Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Commercial Water Filter Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Zero Liquid Discharge Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Global RO Water Purifier Market
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market
Water Treatment Systems
GCC Water Purifier Market