
 Point of Use Water Treatment Systems Market | 2026-2036
Point of Use Water Treatment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Point of Use Water Treatment Systems Market Intelligence
Subscription and leasing models for water purification systems are reconfiguring the market's competitive structure by lowering upfront consumer costs. This service-oriented approach allows new entrants to challenge established players. Pentair plc leverages its vast network of specialty dealers and professional installers to maintain a strong market presence. A. O. Smith Corporation competes through its powerful brand recognition and multi-channel distribution strategy in North America and Asia. Coway Co., Ltd. differentiates with its combination of advanced filtration technology and a successful rental business model.
Point of use water treatment systems are compact devices installed at a single tap or faucet to purify water immediately before consumption or use. These systems employ multi-stage filtration technologies to achieve specific purification goals, such as reducing total dissolved solids (TDS). Their primary purpose is to remove or significantly reduce contaminants including chlorine, lead, cysts, bacteria, and volatile organic compounds from tap water. Reverse Osmosis systems command a significant share of the market due to their effectiveness against a wide spectrum of impurities. The residential application segment represents the fastest-growing area, driven by homeowner concerns about health and water aesthetics.
Regulatory frameworks are critical in shaping product standards and building consumer confidence. In the United States, the EPA sets maximum contaminant levels for drinking water, while NSF/ANSI standards provide third-party certification for product performance claims. Similarly, the European Union's Drinking Water Directive establishes quality parameters that influence system design and marketing across member states. Navigating these diverse international standards while managing filter replacement logistics and sustainability will be a central challenge for manufacturers.
Market Dynamics
The market's central dynamic is the transition from a product-centric sales model to service-oriented business structures. Subscription and leasing options are lowering entry barriers for consumers, fundamentally altering the competitive landscape and prioritizing long-term customer relationships over single transactions.
Growth Catalysts
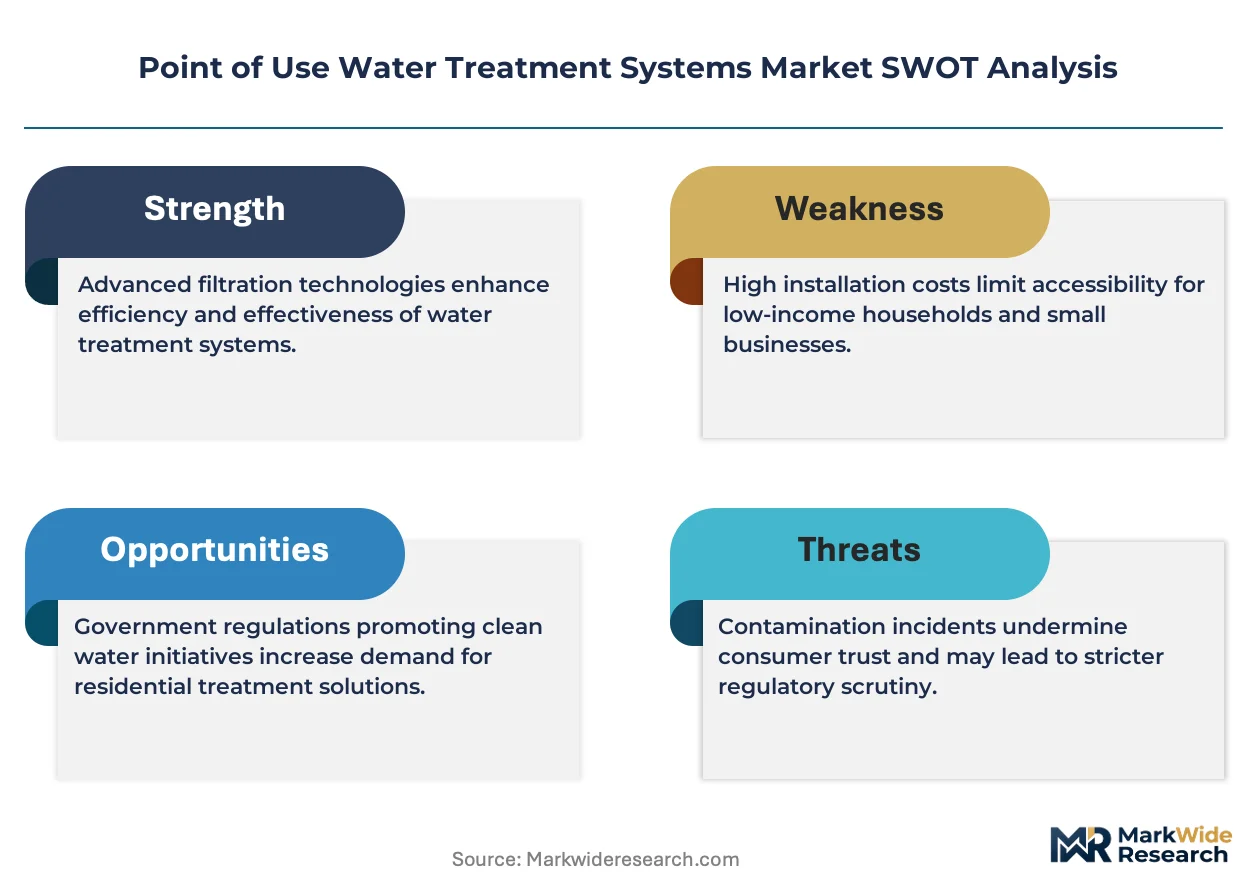
- Regulatory Mandates:Stricter water quality standards, such as the European Union's Drinking Water Directive, compel municipalities and consumers to adopt more advanced purification technologies to meet compliance for specific contaminants.
- Smart Home Integration:The incorporation of IoT sensors for real-time filter life monitoring and water quality tracking is a significant catalyst, appealing to tech-savvy residential users seeking convenience and performance assurance.
- Expanding Middle Class:In developing economies like India, rising disposable incomes combined with persistent concerns over the safety and taste of municipal water supplies are spurring strong residential demand for POU systems.
Market Restraints
- High Initial Investment:The upfront cost of high-performance systems, particularly those using Reverse Osmosis technology, remains a significant barrier for many households, even with the availability of financing and leasing models.
- Technical Inefficiency:Reverse Osmosis systems are known for producing a considerable amount of wastewater or brine reject, creating environmental concerns and increasing operational water costs for users.
- Filter Media Dependency:The industry relies on a concentrated supply base for critical components like activated carbon and RO membranes, exposing manufacturers to price volatility and potential supply chain disruptions.
Strategic Opportunities
- Geographic Expansion:There is significant untapped demand in underpenetrated markets across Southeast Asia and Latin America, where inconsistent municipal water infrastructure creates a clear need for localized treatment solutions.
- Niche Application Development:Manufacturers can develop specialized systems tailored for emerging residential uses, such as home coffee brewing, craft beer making, or small-scale hydroponics, which require specific water mineral profiles.
- Advanced Disinfection Technologies:Integrating compact, mercury-free UV-C LED technology with multi-stage filtration offers a path to create highly effective, low-maintenance systems that meet demand for chemical-free purification.
Industry Challenges
- Complex Certification Pathways:Navigating the divergent requirements of global standards, such as NSF/ANSI in the United States and various national standards within the EU, creates significant compliance costs and lengthens time-to-market.
- Reverse Logistics Management:Implementing efficient and sustainable filter replacement and end-of-life take-back programs at scale presents a major operational challenge, especially for subscription-based business models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point of Use Water Treatment Systems Market |
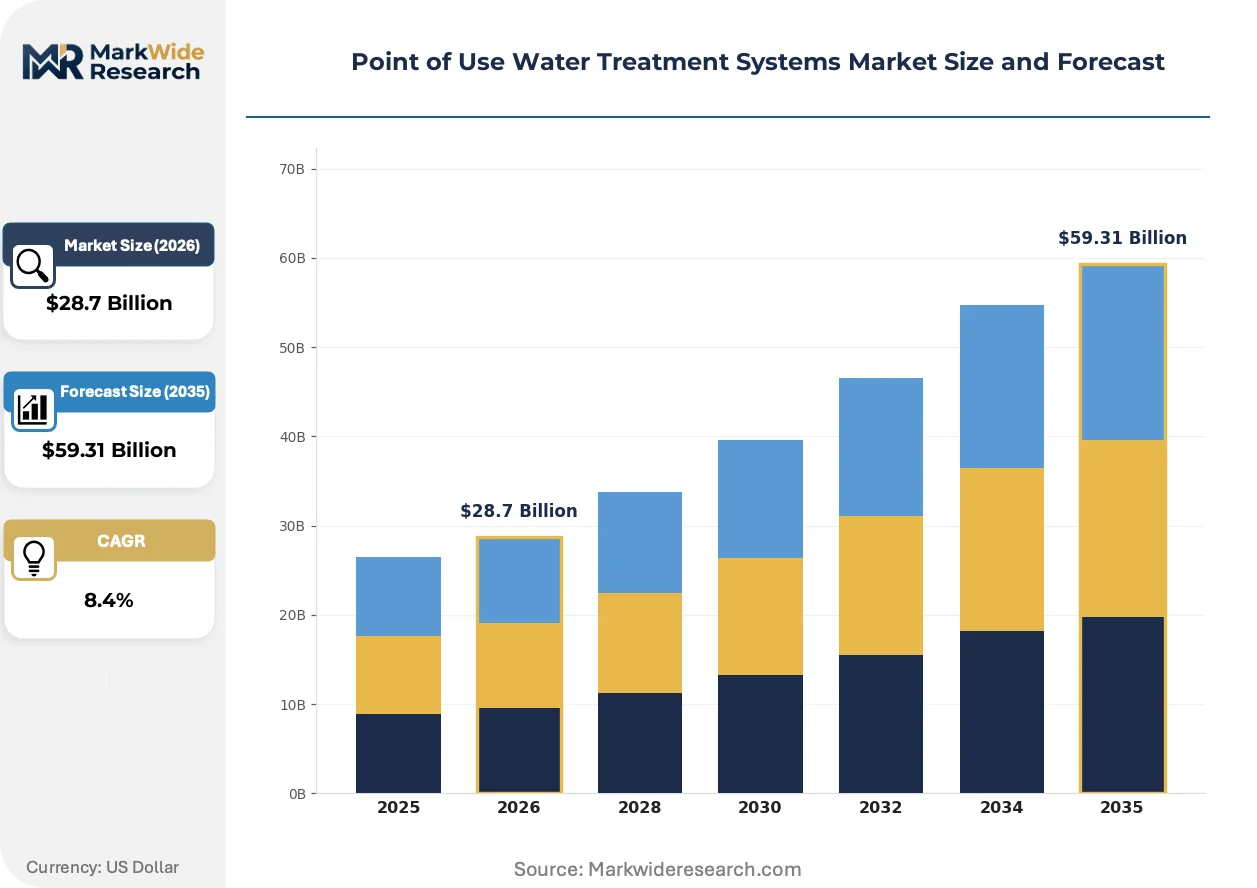
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Ultrafiltration, Activated Carbon, UV Purification, Ion Exchange Application: Residential, Commercial Facilities, Educational Institutions, Food & Beverage Processing, Hospitality End User: Homeowners, Office Buildings, Restaurants, Laboratories, Retail Stores Distribution Channel: Direct Sales, Online Retailers, Wholesale Distributors, Specialty Dealers, Home Improvement Centers |
| Companies Covered | LG Electronics Inc., Coway Co., Ltd., Pentair plc, Whirlpool Corporation, Kent RO Systems Ltd., A. O. Smith Corporation, Panasonic Holdings Corporation, BRITA GmbH, Eureka Forbes Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point of Use Water Treatment Systems Market Strategic Shifts & Innovations
System design is evolving toward greater efficiency, intelligence, and modularity. This shift is driven by a convergence of component miniaturization, consumer demand for verifiable performance, and a push for more sustainable product lifecycles through service-based relationships.
Advanced UV-C LED disinfection technology provides instant, chemical-free water sterilization. Residential and light commercial segments are rapidly adopting this innovation due to its compact form factor and long operational lifespan compared to traditional mercury-vapor lamps. This solid-state technology is collapsing the physical footprint and maintenance complexity previously associated with ultraviolet purification modules within POU systems.
Heightened enforcement of performance standards, such as the NSF/ANSI 53 and 58 certifications in the US, mandates third-party validation of contaminant reduction claims. This regulatory pressure forces manufacturers to invest in rigorous testing, increasing product credibility. The residential segment is most affected, as these certifications become a critical differentiator and a proxy for trust for consumers.
Consumer purchasing behavior is moving away from one-time hardware sales toward service-based models like filter subscriptions and full-system leasing. This change disrupts traditional retail and dealer-installer channels by fostering a direct, ongoing service relationship between brands and end-users. The trend is most visible in North American and South Korean residential markets, where convenience and total cost of ownership are key considerations.
Point of Use Water Treatment Systems Market Segmentation
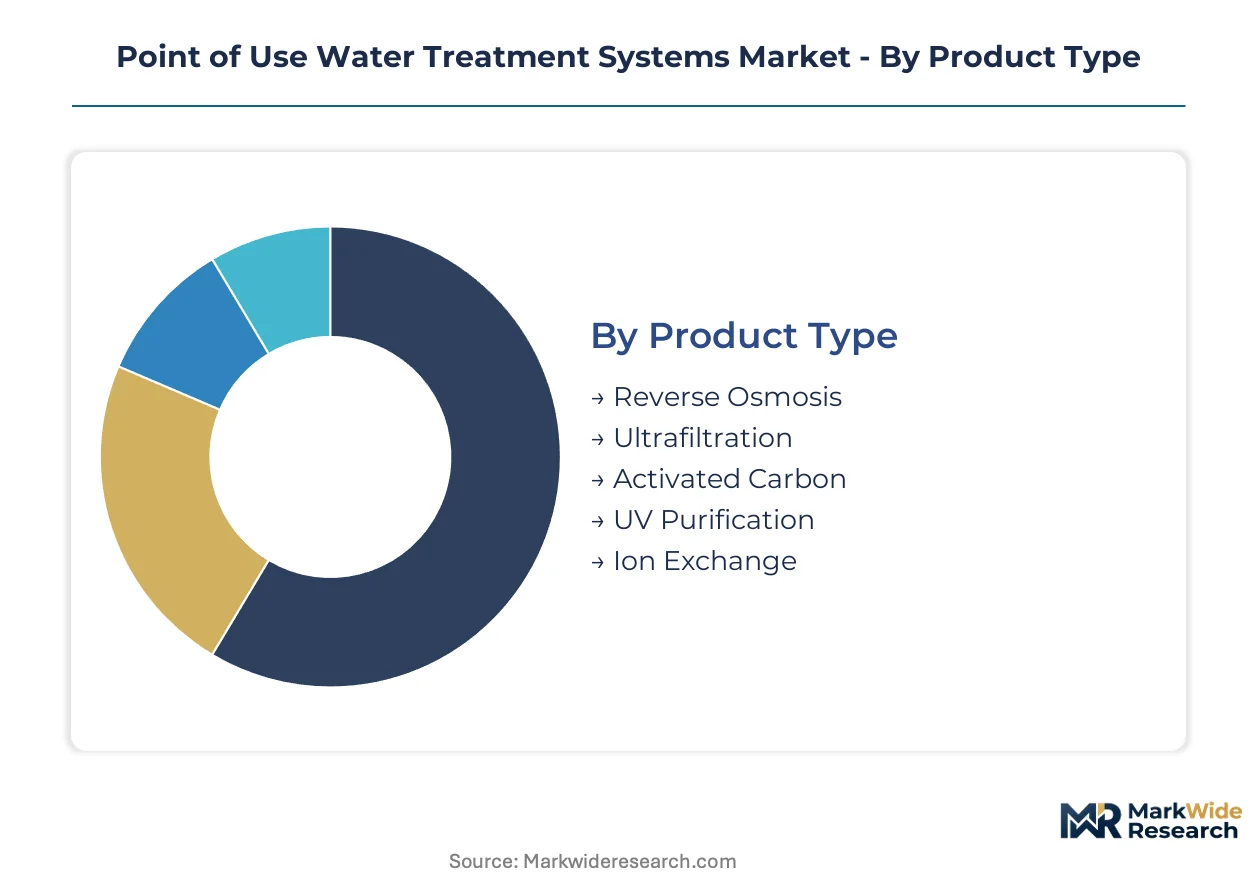
Market segmentation provides a structured view of the diverse product types, applications, end-users, and distribution channels shaping the point of use water treatment systems industry. Understanding these distinct segments helps manufacturers tailor offerings to specific consumer needs and operational environments.
Product Type:
The product type segmentation reveals a mix of established and emerging purification technologies, each addressing specific contaminant concerns and performance requirements.
- Reverse Osmosis:These systems utilize a semi-permeable membrane to remove dissolved solids, heavy metals, and various contaminants, producing highly purified water. Demand concentrates in residential settings and laboratories, where comprehensive contaminant reduction is a primary concern.
- UV Purification:This technology employs ultraviolet light to inactivate bacteria, viruses, and other microorganisms without using chemicals, offering a compact and effective disinfection solution. Residential users and light commercial facilities are rapidly adopting UV-C LED solutions for their enhanced safety and extended lifespan.
- Activated Carbon:Activated carbon filters effectively remove chlorine, sediment, volatile organic compounds, and odors, improving water taste and clarity. Many entry-level systems and pre-filters incorporate activated carbon for basic water quality enhancement.
- Ultrafiltration:Ultrafiltration membranes physically remove suspended solids, colloids, and large molecules, including bacteria and viruses, while retaining beneficial minerals. This technology finds use in both residential and some commercial applications, balancing filtration effectiveness with flow rate.
- Ion Exchange:Ion exchange systems primarily target water hardness by replacing undesirable ions like calcium and magnesium with less harmful ones, often used in water softeners. Industrial and specialized residential applications benefit from ion exchange for specific mineral removal.
Reverse Osmosis technology handles the majority of purification throughput; UV Purification is the fastest mover on share.
Application:
Application segmentation highlights the diverse environments where point of use systems are deployed, each with unique water quality expectations and usage patterns.
- Residential:This segment encompasses systems installed in homes to provide purified water for drinking, cooking, and other household uses, driven by homeowner health concerns and water aesthetics. Homeowners in markets like India are increasingly investing in these systems due to municipal water safety issues.
- Commercial Facilities:Systems in commercial facilities provide purified water for employees, customers, and specific operational needs, including offices and retail spaces. Office buildings often integrate POU systems for drinking water stations, enhancing employee well-being.
- Food & Beverage Processing:Water treatment systems in this sector ensure water quality meets stringent health and safety standards for product formulation, cleaning, and equipment protection. Breweries and cafes require specific water profiles for optimal product quality.
- Hospitality:Hotels, restaurants, and resorts utilize POU systems to provide high-quality drinking water for guests and for use in food preparation, enhancing customer experience. Restaurants often employ POU filters for ice machines and beverage dispensers.
- Educational Institutions:Schools and universities install POU systems in cafeterias, laboratories, and drinking fountains to provide safe water for students and staff. Laboratories within these institutions require precise water purity for experiments.
Residential applications collectively drive significant volume; Food & Beverage Processing demonstrates specific high-value demand.
End User:
End user segmentation reflects the varied specific needs driving system adoption across different customer types, from individual consumers to specialized institutional buyers.
- Homeowners:Individual households purchase and install POU systems to enhance the safety, taste, and quality of their drinking and cooking water. Concerns over tap water contaminants and rising disposable incomes motivate homeowners in developing economies.
- Office Buildings:Commercial offices integrate POU systems to offer purified water to employees and visitors, often replacing bottled water coolers for sustainability and cost efficiency. These environments prioritize convenience and consistent water quality.
- Restaurants:Food service establishments employ POU systems for beverage preparation, ice production, and cooking, ensuring consistent product quality and protecting equipment from scale buildup. Water quality directly impacts the taste of coffee and other beverages.
- Laboratories:Research and testing laboratories require highly purified water for experiments, instrument calibration, and sample preparation, demanding systems capable of ultra-pure water production. Stringent regulatory standards dictate water quality in these settings.
- Retail Stores:Retail outlets, particularly those selling food or beverages, may use POU systems for specific in-store operations or to offer purified water to customers. Convenience stores often use POU filters for coffee machines and soda fountains.
Homeowners represent the largest user base; Laboratories require the most stringent purification standards.
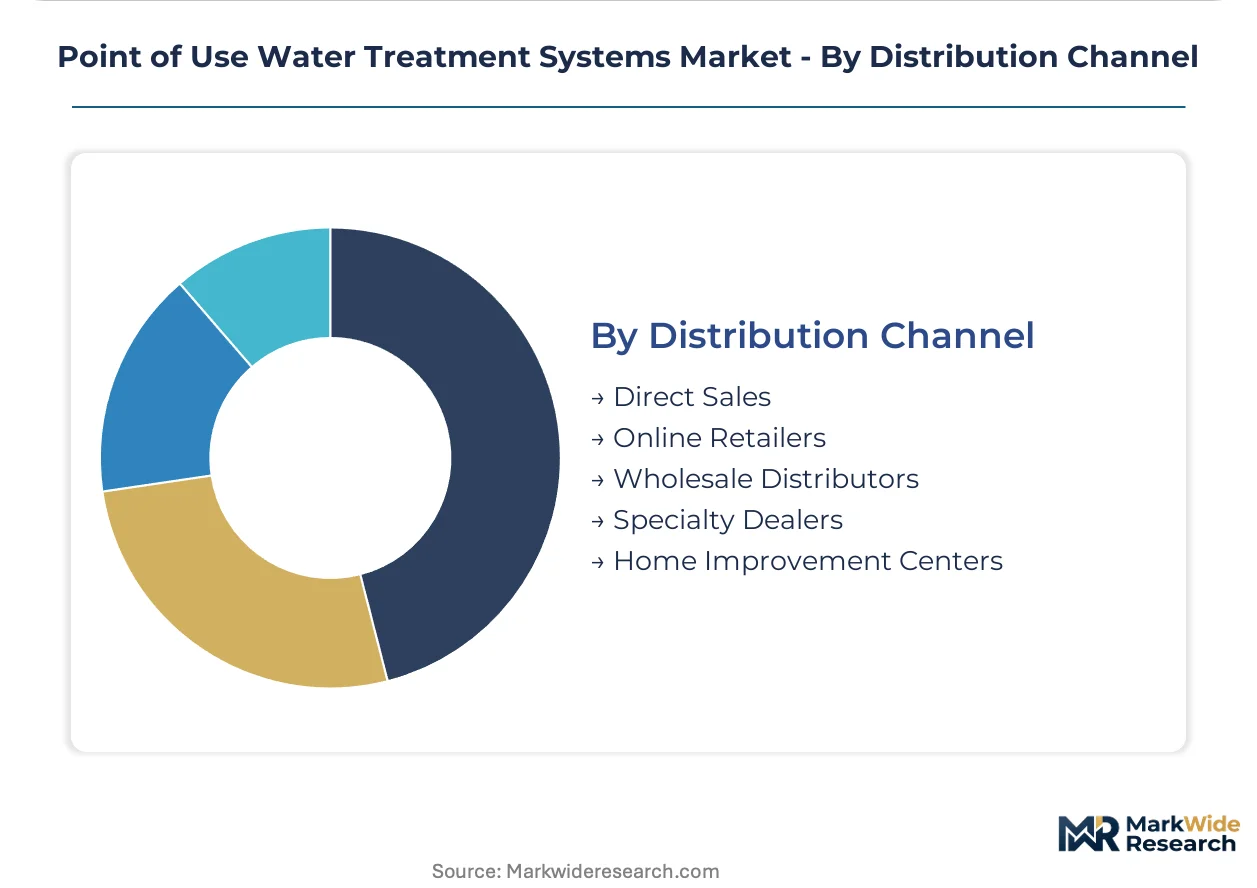
Distribution Channel:
Distribution channel segmentation illustrates the varied pathways through which these systems reach end-users, reflecting diverse purchasing behaviors and service requirements.
- Specialty Dealers:These channels involve dedicated water treatment companies and professional installers who offer expert advice, customized solutions, and installation services. Pentair plc leverages specialty dealers for its market presence, emphasizing professional service.
- Online Retailers:E-commerce platforms provide a convenient and accessible channel for consumers to purchase POU systems, often featuring a wide range of products and competitive pricing. Subscription models for filter replacements are increasingly common through online platforms.
- Wholesale Distributors:These intermediaries supply POU systems to retailers, contractors, and other businesses in bulk, facilitating broad market reach and inventory management. Large-scale residential developments or commercial projects source through wholesale channels.
- Direct Sales:Manufacturers or their authorized representatives sell directly to consumers or businesses, often involving in-home consultations or business-to-business engagements. Coway Co., Ltd. utilizes a direct sales model for its rental business.
- Home Improvement Centers:Large retail chains specializing in home goods and renovations offer POU systems to DIY consumers, providing accessibility and a physical shopping experience. These centers cater to homeowners seeking self-installation options.
Wholesale Distributors manage substantial product flow; Online Retailers are expanding most quickly in direct-to-consumer engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global point of use water treatment systems market exhibits varying dynamics based on regional self-sufficiency and import dependencies. Countries with robust domestic manufacturing capabilities often see different competitive landscapes than those reliant on imported technologies. This balance significantly influences market access and product availability across diverse geographies.
India
India's residential sector drives substantial demand for POU systems due to persistent municipal water safety concerns and increasing disposable incomes. The Bureau of Indian Standards (BIS) sets critical benchmarks for water purification system performance and safety. Major metropolitan areas like Delhi-NCR exhibit concentrated consumer interest in multi-stage purifiers.
United States
United States homeowners prioritize health and water aesthetics, driving demand for certified POU systems. The Environmental Protection Agency (EPA) mandates maximum contaminant levels, while NSF/ANSI standards provide crucial product performance validation. Consumers in states like California frequently invest in advanced filtration solutions due to regional water quality challenges.
Germany
Germany's market benefits from stringent water quality standards and a consumer preference for advanced, chemical-free purification methods. The European Union's Drinking Water Directive establishes comprehensive quality parameters impacting system design and marketing. Urban centers such as Munich and Berlin exhibit significant adoption of compact UV-C LED disinfection systems.
South Korea
South Korea's market is characterized by successful rental business models and a strong preference for advanced filtration technology. The Ministry of Environment enforces strict drinking water quality standards, influencing product development. In metropolitan areas like Seoul, consumers widely adopt POU systems through convenient subscription and leasing services.
China
China experiences substantial demand for POU systems driven by rapid urbanization and concerns about municipal water safety. National GB standards regulate drinking water quality and purification equipment specifications. Large urban centers like Shanghai and Guangzhou represent significant markets for residential POU systems.
Point of Use Water Treatment Systems Market Key Industry Players
On the supply side, the industry is moderately consolidated at the top tier but fragmented across mid-sized and niche players. This structure supports both large appliance manufacturers and specialized water treatment providers focused on specific contaminant removal. Strategic archetypes include technology innovators, service-oriented rental providers, and traditional hardware suppliers emphasizing broad product portfolios. Dominant competitive moves involve geographic expansion into underpenetrated markets and strategic partnerships for distribution and technology integration.
Within the service-oriented archetype, Coway Co., Ltd. exemplifies a successful rental business model, integrating advanced filtration technology for residential consumers. Pentair plc, a global player, anchors its market presence through an extensive network of specialty dealers and professional installers who provide expert service. A. O. Smith Corporation, a prominent North American and Asian-focused entity, leverages its powerful brand recognition across multi-channel distribution strategies to reach a broad customer base. These entities collectively represent diverse approaches to market penetration, product innovation, and long-term customer engagement within the POU water treatment systems sector.
| Leading Market Players |
|---|
| LG Electronics Inc. |
| Coway Co., Ltd. |
| Pentair plc |
| Whirlpool Corporation |
| Kent RO Systems Ltd. |
| A. O. Smith Corporation |
| Panasonic Holdings Corporation |
| BRITA GmbH |
| Eureka Forbes Ltd. |
| Others |
Cost & Logistics Intelligence
Commodity price volatility for activated carbon and RO membranes determines both pricing tier spreads and supply chain shape for point of use water treatment systems.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for core components. Pricing stratifies across premium, standard, and economy tiers based on certification level, such as NSF/ANSI 53 or 58, and brand premium. Pricing softness stems from the influx of new entrants offering service-based subscription models, increasing competitive pressure. Residential homeowners represent the most price-sensitive segment, while laboratories require highly specialized systems with lower price sensitivity.
Supply Chain Analysis
Single-source vulnerability for specialized filtration media dominates the supply chain for point of use systems. Supply largely centers on China for generic components and specialized manufacturing, alongside South Korea and the United States for advanced membranes and smart technologies. Activated carbon, RO membranes, and UV-C LED components are critical material dependencies. Wholesale distributors manage substantial product flow to various downstream channels, including specialty dealers and home improvement centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market's future hinges on addressing a critical capability gap in managing complex reverse logistics for filter replacement and end-of-life take-back programs.
For Market Incumbents:
Pre-empt competitive threats from service-oriented new entrants by aggressively expanding subscription and leasing models. Invest in robust digital platforms for real-time filter monitoring and predictive maintenance, enhancing customer retention. Secure long-term supply agreements for critical components like RO membranes to mitigate commodity price volatility. Leverage existing specialty dealer networks for efficient filter replacement and system maintenance.
For New Entrants and Emerging Players:
Underpenetrated residential markets across Southeast Asia and Latin America represent the most penetrable entry point for new market players. Focus on developing localized, affordable solutions that address specific regional water quality concerns. Implement flexible subscription models with easy installation and maintenance to overcome high initial investment barriers for consumers. Partner with local service providers to ensure effective last-mile delivery and support.
For Investors and Strategic Acquirers:
The market sits at a growth phase that favors technology innovators with strong intellectual property in advanced filtration and disinfection. Long-term viability remains robust, driven by persistent water quality concerns and rising consumer awareness. Target mid-sized firms specializing in UV-C LED technology or smart IoT integration to enhance portfolio capabilities. The acceleration of smart home integration standards is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Modular Filter Cartridges | This initiative simplifies maintenance and supports sustainability goals for subscription models. |
| Expand Service-Based Rental Models | These models lower consumer entry barriers and foster long-term customer relationships in residential segments. |
| Acquire Specialized UV-C LED Technology Firms | This move integrates advanced disinfection capabilities, reducing system footprint and chemical use. |
| Establish Regional Compliance Hubs | These hubs streamline product certification processes across diverse international regulatory frameworks. |
| Partner with Smart Home Platform Providers | This collaboration enhances system convenience and data-driven performance for tech-savvy consumers. |
Research Approach
A standing panel of water treatment engineers, product managers, distribution channel executives, and regulatory compliance specialists provided ongoing calibration for market insights. Primary interviews with these industry stakeholders were triangulated with secondary data from EPA water quality reports, NSF/ANSI certification databases, and EU Drinking Water Directive documents. This approach ensured a comprehensive understanding of market dynamics and validated initial findings through bottom-up and top-down analyses.
Scenario-bracketing frames the analytical framework across the analysis window, modeling market progression under varying conditions. The forecast framework segments the market by product type, application, end-user, distribution channel, and regional regulatory compliance level. Compound annual growth rates were derived from historical trends, identified market drivers, and expert projections. Consumer disposable income trends and municipal water quality indices served as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global trade policies or consumer spending power would shift the trajectory of the market. Forecasts reflect assumptions regarding technological advancements and regulatory stability over the projection horizon. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market
Water Treatment Systems
Commercial Water Filter Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Water Treatment Ozone Generator Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Portable Water Purifier Market
Water Treatment Systems
Wastewater Recovery Systems Market