
 Solar Outdoor LED Lighting Market | 2026-2036
Solar Outdoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Outdoor LED Lighting Market Outlook
The split between premium solar outdoor LED systems and commodity-grade alternatives is realigning procurement patterns across public infrastructure. Signify Holding leverages its Philips lighting heritage to dominate European municipal tenders with integrated smart-control architectures. Greenshine New Energy anchors its position in North American commercial installations through all-in-one system designs that reduce field labor. SOKOYO Solar Lighting Co., Ltd. competes on manufacturing scale from its Jiangsu production base, supplying pole-mount street lights to Belt and Road corridor projects.
Solar outdoor LED lighting comprises photovoltaic panels, solid-state LED arrays, rechargeable battery storage, and charge controllers engineered to convert sunlight into stored electrical energy for autonomous nighttime illumination, typically achieving 150-200 lumens per watt efficacy in modern chip-on-board designs. Street lights command the largest installed base among product types, though flood lights capture disproportionate margin pools in perimeter security and industrial compound applications. Pole mount installations lead volume globally, while wall mount configurations grow fastest in dense urban retrofit markets where underground trenching proves cost-prohibitive.
EPA Energy Star certification and FCC Part 15 emissions compliance shape product design for US-bound equipment, while EU Green Deal carbon-neutrality targets and Ecodesign Directive efficiency thresholds accelerate LED-only mandates across member states. India's Bureau of Energy Efficiency standards and MNRE off-grid solar programs create parallel certification pathways that favor domestic assembly. Stakeholders must monitor evolving battery chemistry regulations and circular economy disposal requirements as jurisdictions tighten hazardous material controls on lithium-based storage systems.
Market Dynamics
The solar outdoor LED lighting market is undergoing a fundamental reconfiguration as lithium iron phosphate battery chemistry displaces lead-acid storage across humid subtropical installations, compressing total cost of ownership curves and reshaping supplier qualification requirements for municipal procurement frameworks.
Growth Catalysts
- India's MNRE off-grid solar programs:Urban local bodies in smart city corridors now mandate autonomous solar street lighting for peripheral roads and public parks, creating standardized procurement volumes that reduce per-unit system costs.
- MPPT charge controller integration:Maximum power point tracking electronics are improving energy harvest efficiency in variable cloud-cover climates, extending daily operational hours and reducing battery cycling depth.
- Southeast Asian renewable transition mandates:National energy agencies across Vietnam, Thailand, and Indonesia are embedding solar LED street lighting into municipal infrastructure budgets with dedicated renewable procurement quotas.
Market Restraints
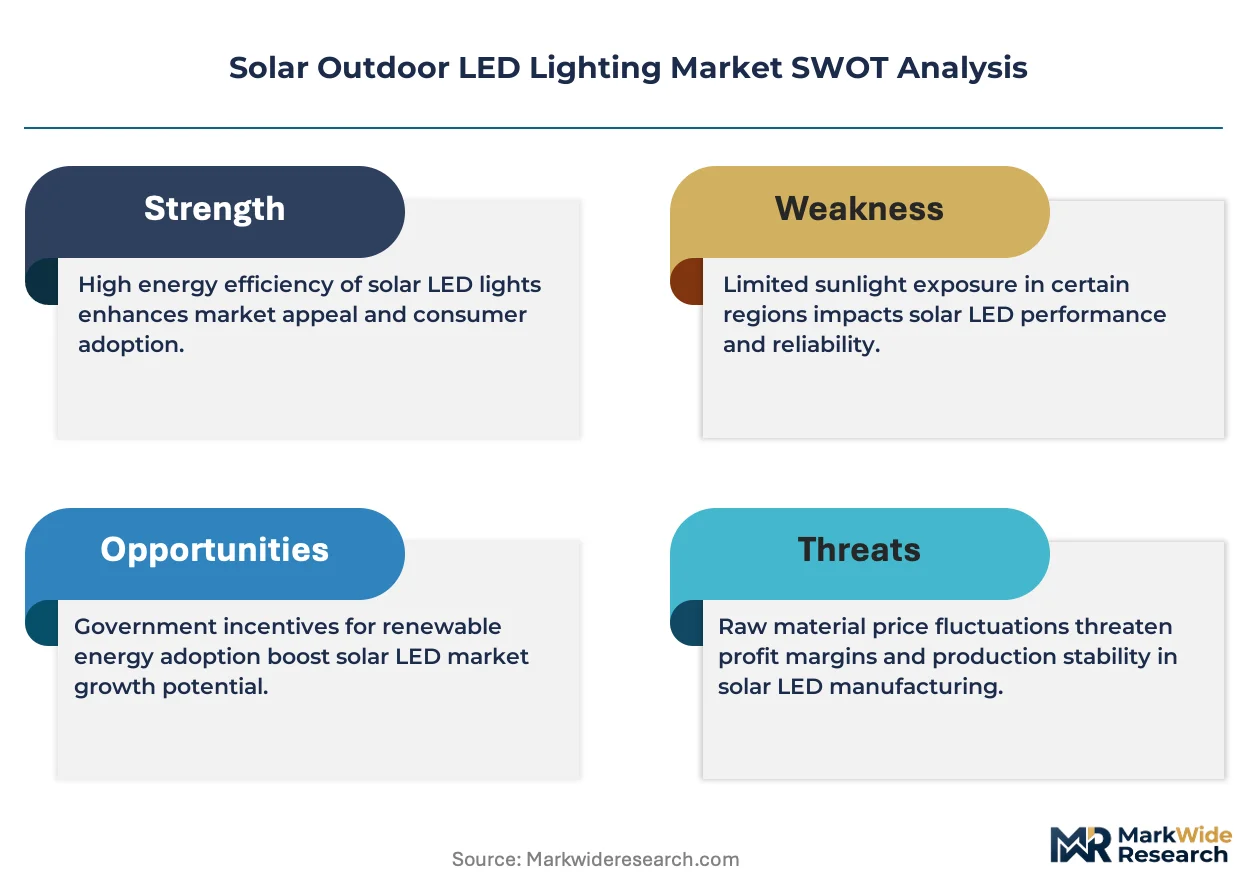
- Lithium supply concentration:Battery-grade lithium carbonate processing concentrates in Chilean and Australian upstream operations, exposing system integrators to raw material price volatility and offtake contract renegotiation cycles.
- Technical limitation in low-solar irradiance zones:Northern latitude installations above 50 degrees face winter autonomy gaps that require oversized panel arrays and battery banks, degrading project economics.
- EU Ecodesign Directive compliance friction:Circular economy disposal requirements for lithium-based storage systems impose end-of-life collection obligations that increase total system cost accounting complexity.
Strategic Opportunities
- Perimeter security flood light applications:Industrial compounds and critical infrastructure operators are specifying high-lumen solar LED arrays for off-grid perimeter illumination, capturing disproportionate margin pools versus street lighting commoditization.
- Wall mount retrofit channels:Dense urban markets where underground trenching proves cost-prohibitive are driving fastest-growing demand for facade-mounted solar LED systems in European and North American heritage districts.
- Smart-control architecture convergence:Integrated IoT-enabled dimming and remote monitoring capabilities are opening software-recurring revenue streams for hardware suppliers with municipal maintenance contracts.
Industry Challenges
- Field commissioning skill scarcity:Proper MPPT configuration and battery management system calibration require trained technicians that remain scarce in remote deployment zones, elevating installation defect rates and warranty claim volumes.
- Multi-certification timeline compression:Simultaneous EPA Energy Star, FCC Part 15, and EU CE marking pathways for US-bound and European-bound equipment extend product launch cycles and strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Outdoor LED Lighting Market |
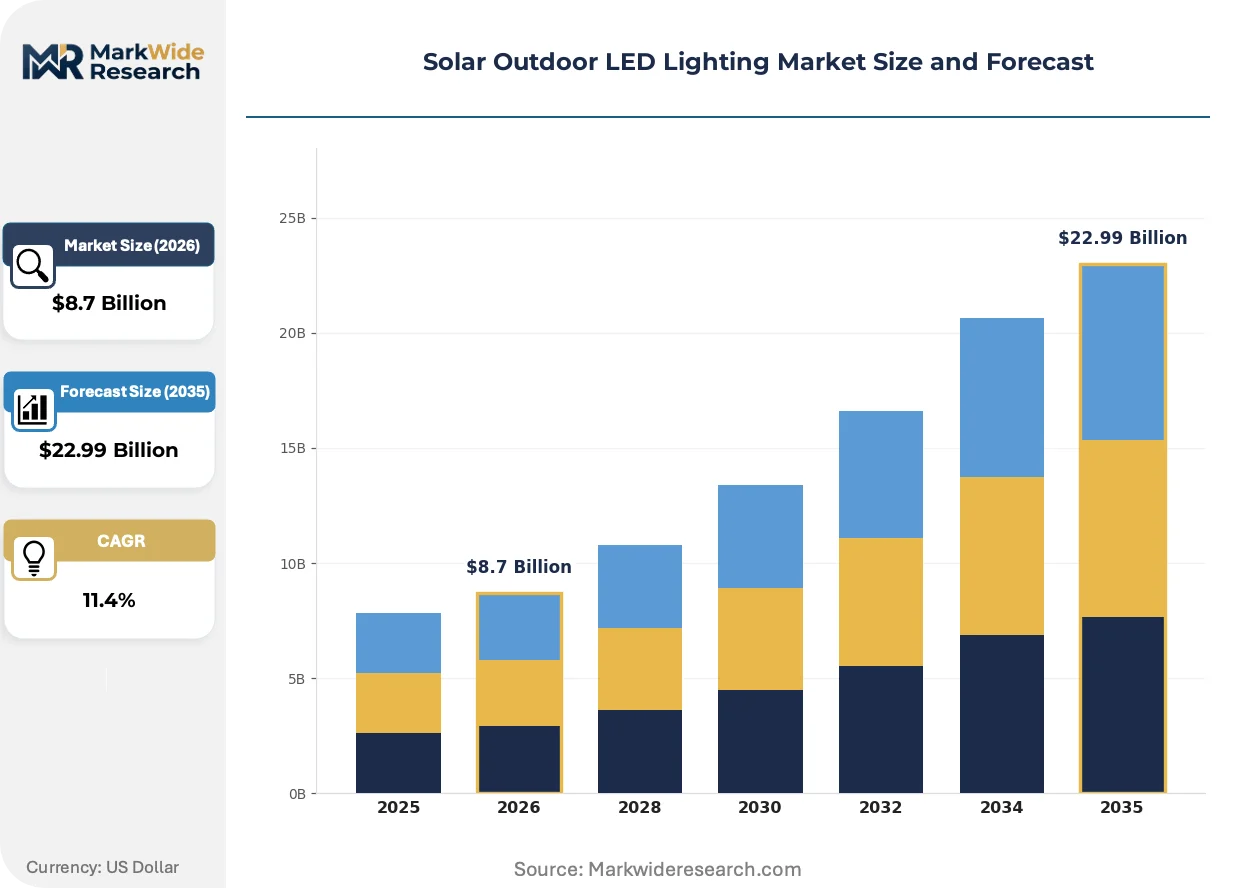
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Lights, Garden Lights, Flood Lights, Street Lights Application: Parks, Pathways, Patios, Commercial Spaces Power Rating: Low Power, Medium Power, High Power, Ultra High Power Installation Type: Ground Mount, Pole Mount, Wall Mount, Ceiling Mount |
| Companies Covered | Signify Holding, Wipro Lighting, Greenshine New Energy, SOKOYO Solar Lighting Co., Ltd., SEPCO Solar Electric Power Company, Sunna Design, LEADSUN, Polybrite - SBM NewTech Co., Ltd., Solar Street Lights USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Outdoor LED Lighting Market Strategic Shifts
Chip-on-board LED architectures and solid-state battery chemistries are compressing form factors while extending operational lifespans, enabling new mounting configurations that bypass traditional infrastructure dependencies.
Chip-on-board LED arrays with 150-200 lumens per watt efficacy are converging with integrated photovoltaic-thermal hybrid collectors that harvest waste heat from illumination surfaces. Municipal engineers in India's smart city projects are specifying these dual-function systems for traffic intersections and transit shelters. The technology is converging with conventional split-system designs by collapsing separate thermal management and power generation subassemblies into unified pole-mount enclosures.
The EU Green Deal carbon-neutrality targets are accelerating LED-only mandates across member state public procurement frameworks. Ecodesign Directive efficiency thresholds now exclude legacy high-pressure sodium retrofits from tender eligibility. Street lighting product categories face the most stringent compliance timelines, with German and French municipal buyers already requiring embodied carbon disclosure documentation.
Urban local bodies are consolidating vendor relationships around integrated system suppliers capable of delivering pole, luminaire, battery, and control electronics as unified packages. Traditional electrical contractors are ceding specification influence to specialized solar lighting integrators with in-house civil engineering capabilities. This consolidation pattern is most visible in India's peripheral road projects where single-source accountability reduces interface risk between civil, electrical, and renewable work packages.
Solar Outdoor LED Lighting Market Segmentation
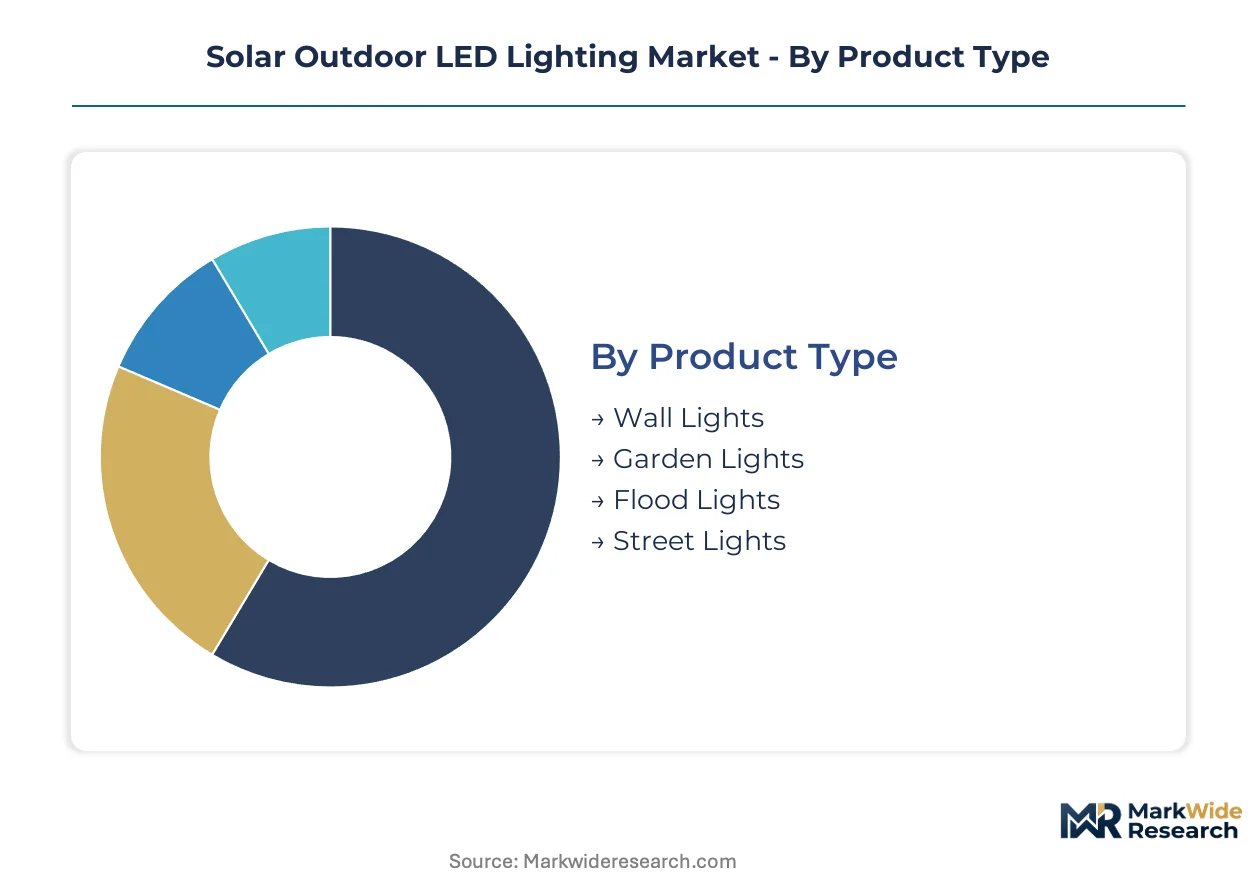
Solar outdoor LED lighting procurement frameworks diverge sharply by segment, with municipal tender specifications embedding distinct certification requirements for street infrastructure versus residential applications. Product type and installation method determine whether systems must satisfy EPA Energy Star, FCC Part 15, or EU Ecodesign Directive thresholds.
Product Type:
Street lights and flood lights carry the heaviest regulatory burden, requiring FCC Part 15 emissions compliance for US municipal contracts and EU CE marking for European public procurement, while garden and wall lights face lighter self-certification pathways.
- Street Lights:These systems integrate photovoltaic panels, lithium iron phosphate battery storage, and chip-on-board LED arrays achieving 150-200 lumens per watt efficacy. Demand concentrates in India's smart city infrastructure projects, where urban local bodies mandate autonomous solar lighting for peripheral roads and public parks to satisfy MNRE off-grid solar program requirements.
- Flood Lights:High-lumen solar LED arrays designed for perimeter security and industrial compound illumination capture disproportionate margin pools relative to commoditized street lighting. Southeast Asian renewable transition mandates in Vietnam, Thailand, and Indonesia are accelerating procurement for critical infrastructure protection.
- Wall Lights:Compact facade-mounted systems for residential and light commercial applications.
- Garden Lights:Decorative autonomous luminaires for landscape illumination with minimal certification overhead.
Street lights sit at the top of the volume ranking, with flood lights climbing the fastest.
Application:
Cost tier stratification separates premium-specified commercial installations from standardized public infrastructure deployments, with patios and pathways occupying mid-market positioning.
- Commercial Spaces:Industrial compounds and critical infrastructure operators specify high-lumen solar LED arrays with integrated IoT-enabled dimming and remote monitoring capabilities. North American installations favor all-in-one system designs that reduce field labor and enable software-recurring revenue streams through municipal maintenance contracts.
- Parks:Municipal green space illumination requires pole-mount configurations with extended battery autonomy for seasonal operational reliability. India's urban local bodies prioritize off-grid lighting for public parks under standardized procurement volumes that reduce per-unit system costs.
- Pathways:Pedestrian route lighting with moderate lumen output requirements.
- Patios:Residential outdoor living space illumination with decorative form factor preferences.
Commercial spaces command the highest average system values, with parks expanding most quickly.
Power Rating:
Volume concentration in medium and high power brackets reflects municipal street lighting dominance, while ultra high power systems serve specialized perimeter security applications with constrained addressable market scope.
- High Power:Systems engineered for arterial road illumination and large-area commercial security applications. Northern latitude installations above 50 degrees face winter autonomy gaps that require oversized panel arrays and battery banks, degrading project economics in these configurations.
- Medium Power:Standard municipal street lighting and pathway illumination specifications. Humid subtropical climates in Southeast Asia favor lithium iron phosphate battery chemistry with MPPT charge controller integration to improve system reliability under variable cloud-cover conditions.
- Low Power:Residential garden and accent lighting with minimal storage requirements.
- Ultra High Power:Specialized industrial perimeter and critical infrastructure applications.
Medium power systems dominate unit shipments, with high power configurations gaining share fastest.
Installation Type:
Supply concentration among pole-mount specialists contrasts with fragmented wall-mount retrofit channels, where heritage district contractors compete on civil engineering integration capabilities.
- Pole Mount:Traditional infrastructure deployment for street lighting and large-area illumination. German and French municipal buyers already require embodied carbon disclosure documentation under EU Green Deal carbon-neutrality targets, with Ecodesign Directive efficiency thresholds excluding legacy high-pressure sodium retrofits from tender eligibility.
- Wall Mount:Facade-mounted configurations for dense urban retrofit markets where underground trenching proves cost-prohibitive. European and North American heritage districts are driving steepest expansion trajectory for these systems as single-source accountability reduces interface risk between civil, electrical, and renewable work packages.
- Ground Mount:Landscape-integrated luminaires for garden and pathway applications.
- Ceiling Mount:Covered structure illumination for transit shelters and covered walkways.
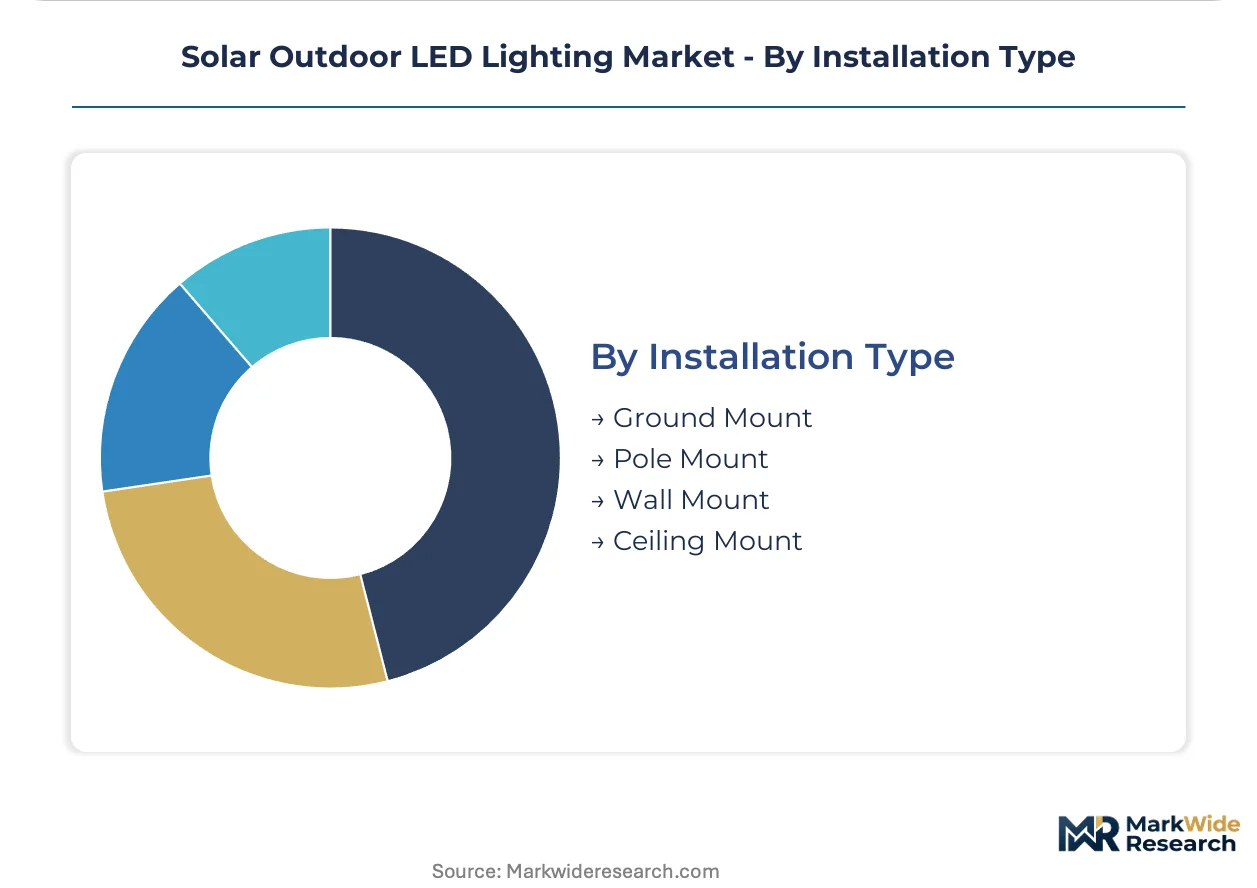
Pole mount installations lead absolute volume, with wall mount configurations expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's municipal procurement volumes exceed Vietnam's national infrastructure budgets by an order of magnitude, while Germany's embodied carbon disclosure requirements outpace regulatory stringency elsewhere in Europe.
India
Urban local bodies in smart city corridors mandate autonomous solar street lighting for peripheral roads and public parks under MNRE off-grid solar programs. The Bureau of Energy Efficiency standards create parallel certification pathways favoring domestic assembly. Maharashtra and Gujarat industrial clusters concentrate manufacturing scale for pole-mount systems serving Belt and Road corridor exports.
Germany
Municipal buyers already require embodied carbon disclosure documentation under EU Green Deal carbon-neutrality targets. Ecodesign Directive efficiency thresholds exclude legacy high-pressure sodium retrofits from tender eligibility. Bavaria and North Rhine-Westphalia anchor demand for wall-mount retrofit configurations in heritage districts where underground trenching proves cost-prohibitive.
Vietnam
National energy agencies embed solar LED street lighting into municipal infrastructure budgets with dedicated renewable procurement quotas. Variable cloud-cover climates drive MPPT charge controller integration specifications. Ho Chi Minh City and Hanoi concentrate procurement volumes for arterial road illumination with lithium iron phosphate battery chemistry.
United States
EPA Energy Star certification and FCC Part 15 emissions compliance shape product design for municipal contracts. North American commercial installations favor all-in-one system designs that reduce field labor. California and Texas lead specification influence for perimeter security flood light applications in industrial compounds.
France
EU Green Deal carbon-neutrality targets accelerate LED-only mandates across public procurement frameworks. French municipal buyers require embodied carbon disclosure documentation ahead of German compliance timelines. Île-de-France and Provence-Alpes-Côte d'Azur concentrate demand for smart-control architectures with IoT-enabled dimming capabilities.
Solar Outdoor LED Lighting Market Competitive Environment
Top-tier vendors anchor municipal tender specifications, while mid-tier fabricators compete on manufacturing scale and regional distribution density. The vendor base stratifies across integrated system suppliers, component specialists, and project engineering firms. Three archetypes dominate: heritage lighting conglomerates with smart-control portfolios, pure-play solar lighting integrators with civil engineering capabilities, and Asian manufacturing scale players serving export corridors. Competitive moves concentrate on geographic expansion through Belt and Road project participation and technology licensing for MPPT charge controller integration.
Among heritage lighting conglomerates, Signify Holding occupies a position exemplifying integrated smart-control architectures for European municipal tenders. Greenshine New Energy and SOKOYO Solar Lighting Co., Ltd. represent contrasting geographic anchors—North American commercial installation focus versus Jiangsu-based manufacturing scale for export markets. SEPCO Solar Electric Power Company and Sunna Design sit within the specialized integrator tier, reflecting the consolidation pattern around single-source accountability for unified pole, luminaire, battery, and control electronics packages.
| Leading Market Players |
|---|
| Signify Holding |
| Wipro Lighting |
| Greenshine New Energy |
| SOKOYO Solar Lighting Co., Ltd. |
| SEPCO Solar Electric Power Company |
| Sunna Design |
| LEADSUN |
| Polybrite - SBM NewTech Co., Ltd. |
| Solar Street Lights USA |
| Others |
Value Chain & Pricing Dynamics
Lithium iron phosphate battery chemistry adoption simultaneously compresses total cost of ownership curves and concentrates procurement qualification power among integrated system suppliers with captive cell sourcing. Municipal tender frameworks now embed battery chemistry specifications that disqualify lead-acid dependent vendors, reshaping both manufacturing investment patterns and pricing leverage across humid subtropical deployment zones.
Pricing Analysis
Bundled all-in-one system designs command premium positioning against unbundled component procurement, with integrated pole-luminaire-battery-control packages reducing field labor costs that municipal buyers now internalize in total project accounting. Pricing stratifies across premium smart-control architectures, standard MPPT-enabled configurations, and economy-grade PWM systems, with EU Ecodesign Directive compliance and FCC Part 15 certification tiers driving differentiation. Cost compression in standard configurations is intensifying because Jiangsu-based manufacturing scale players are exporting at volume price points that strain North American commercial installation margins. Municipal procurement officers exhibit lowest price sensitivity due to standardized MNRE program budgets, while residential garden light consumers demonstrate highest elasticity.
Supply Chain Analysis
Battery-grade lithium carbonate supply rests on Chilean and Australian upstream processing operations, exposing system integrators to raw material price volatility and offtake contract renegotiation cycles. Photovoltaic cell production concentrates in China, Vietnam, and Malaysia, while chip-on-board LED arrays source predominantly from Taiwanese and South Korean semiconductor fabricators. Single-source vulnerability in lithium refining creates procurement risk for vendors without diversified cathode material agreements. Distribution runs through specialized solar lighting integrators with civil engineering capabilities rather than traditional electrical contractor channels, particularly in India's smart city corridors where single-source accountability reduces interface risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through lithium iron phosphate chemistry standardization that collapses warranty cost reserves and enables premium smart-control tier pricing. Battery cost curves and MPPT controller integration are shifting procurement toward integrated suppliers capable of unified system accountability.
For Market Incumbents: Deepen backward integration into lithium iron phosphate cell sourcing to secure supply continuity against Chilean and Australian concentrate volatility. Anchor pole-mount manufacturing scale in Maharashtra and Gujarat industrial clusters to defend position against Jiangsu-based export competitors. Prioritize MPPT charge controller firmware development as a certification-locked differentiator that commodity assemblers cannot replicate without engineering bandwidth investment. For New Entrants and Emerging Players: Enter via wall-mount retrofit channels in European heritage districts where underground trenching economics favor facade-mounted configurations and civil engineering integration capabilities remain scarce. Target perimeter security flood light applications in Southeast Asian industrial compounds, where high-lumen specifications capture disproportionate margin pools versus commoditized street lighting. Pursue technology licensing partnerships with established MPPT controller specialists to bypass multi-year firmware development cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier fabricators with regional distribution density but lacking smart-control architecture portfolios. Long-term viability hinges on software-recurring revenue streams from municipal maintenance contracts rather than hardware transactional margins. Acquisition targets should demonstrate in-house civil engineering capabilities and existing Belt and Road corridor export relationships. Watch lithium carbonate price volatility as the primary inflection indicator for system integrator margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Sourcing | Captive lithium iron phosphate supply secures qualification for MNRE and EU tender frameworks. |
| Smart-Control Architecture Licensing | IoT-enabled dimming capabilities open software-recurring revenue through municipal maintenance contracts. |
| Wall-Mount Retrofit Channel Expansion | Heritage district civil engineering capabilities address fastest-growing installation configuration demand. |
| MPPT Controller Firmware Development | Maximum power point tracking integration improves energy harvest in variable cloud-cover climates. |
| Belt and Road Corridor Export Scaling | Jiangsu-based manufacturing positions for Vietnam, Thailand, and Indonesia renewable procurement quotas. |
Study Parameters
Multiple input streams — municipal procurement officer interviews, solar lighting integrator field assessments, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary conversations captured specification evolution in India's smart city corridors, Germany's heritage district retrofit programs, and Vietnam's national energy agency procurement frameworks. Secondary validation drew from Bureau of Energy Efficiency standards documentation, EU Ecodesign Directive threshold publications, and MNRE off-grid solar program disbursement records. Bottom-up unit economics modeling and top-down infrastructure budget allocation analysis were cross-referenced to anchor volume projections.
Historical deployment trajectories were cross-referenced against panel input from EPC contractors and battery system suppliers to calibrate adoption curve assumptions across the projection horizon. Segmentation modeling captured product type, installation configuration, power rating tier, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves rather than linear extrapolation, with lithium iron phosphate cost curves and MPPT controller penetration rates serving as key forecast inputs alongside municipal infrastructure budget growth assumptions.
The model holds under stable lithium carbonate supply conditions and continued MNRE program funding; deviation in raw material price volatility or Indian central government renewable allocation shifts would revise trajectory assumptions. Forecasts reflect documented procurement patterns and technology substitution elasticities rather than macroeconomic projections. A small set of named triggers — lithium supply concentration events, EU circular economy disposal requirement enforcement timelines, and MPPT configuration skill scarcity in remote deployment zones — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Art and Museum Lighting Market
Lighting
Tritium Light Source Market
Lighting
US Indoor LED Lighting Market
Lighting
Bacteriological Light Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Global Flame Proof Lighting Market
Lighting
Intelligent Lighting Market
Lighting
Industrial OLED Lighting Market
Lighting
Dimmers Market
Lighting
Wireless Lighting Market
Lighting
Bulb Market
Lighting
Ambient Lighting Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
COB Photo Light Market
Lighting
EV Lighting Market
Lighting
Smart Lighting Market