
 Solid State Lighting System Market | 2026-2036
Solid State Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Solid State Lighting System Market Analytics
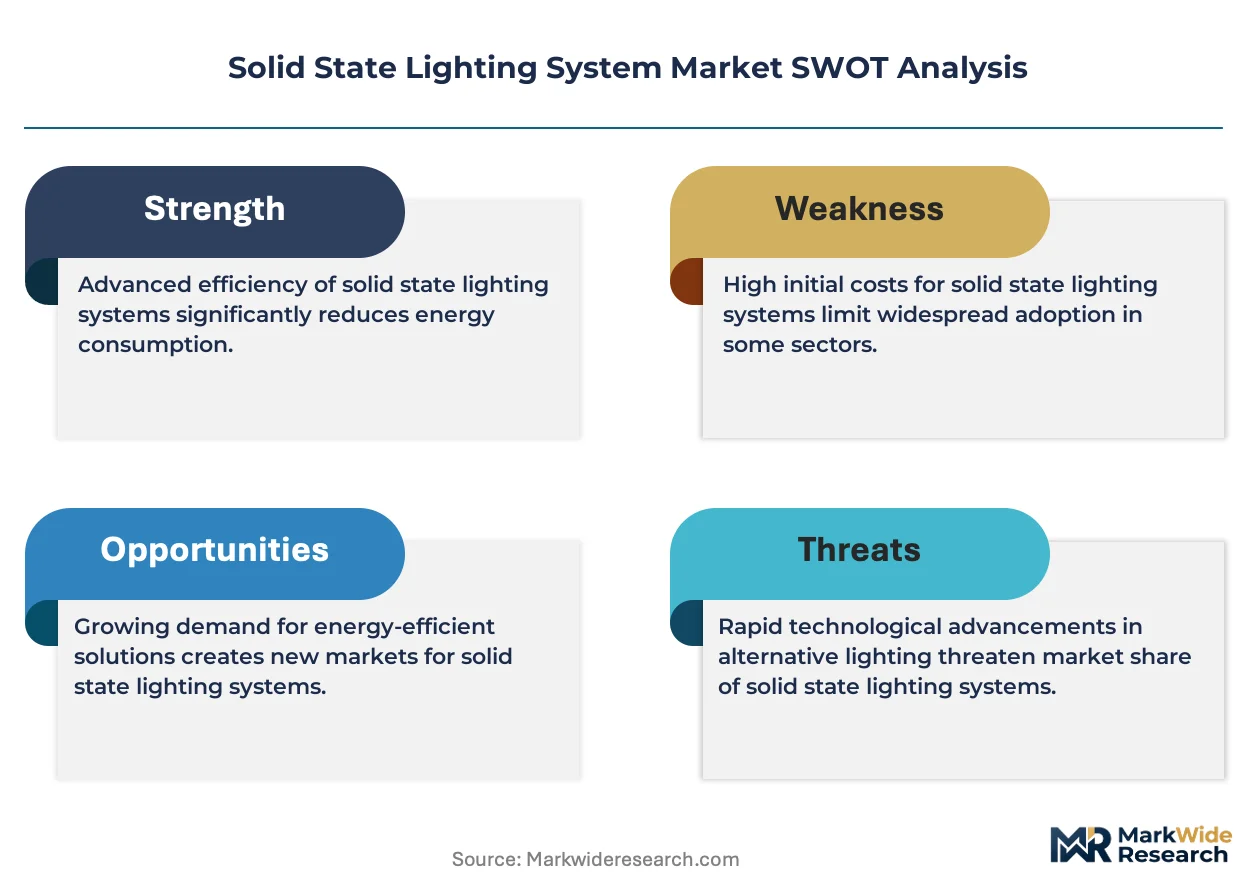
Energy Star and DLC Premium qualification cycles are bifurcating the competitive landscape into specification-grade suppliers and undifferentiated volume producers. Signify Holding leverages its vertical control over phosphor and driver supply chains to sustain qualification across both tiers. OSRAM Licht AG anchors its position through deep specialization in automotive and projection-grade emitters where thermal stability requirements exceed standard certification thresholds.
Solid state lighting systems employ semiconductor junctions—typically indium gallium nitride on sapphire or silicon carbide substrates—to generate photons through electroluminescence rather than thermal radiation, with efficacy ratings routinely exceeding 150 lumens per watt in commercial packages. LED product categories dominate installed value owing to unit economics and retrofit compatibility, while OLED segments occupy premium architectural niches where surface-area emission and thin-form factors justify cost premiums. Smart lighting technology is expanding fastest as building management systems integrate occupancy sensing and daylight harvesting protocols into unified control architectures.
The US Department of Energy maintains efficacy and color-quality benchmarks through CALiPER testing protocols, while the EU Ecodesign Directive and associated CE marking enforce minimum performance thresholds and mercury-free construction. China's GB standards and NEEA labeling program impose parallel efficiency floors that shape export-competitive manufacturing. Stakeholders must monitor divergence between regional flicker standards and circadian-health metrics as these criteria migrate from voluntary specification to codified procurement requirements.
Market Dynamics
Retrofit mandates under the EU Ecodesign Directive and parallel efficiency standards in China and the United States are systematically dismantling installed bases of fluorescent and halogen infrastructure, redirecting capital flows toward semiconductor-based luminaire platforms.
Growth Catalysts
- EU Green Deal phase-out schedules:Ecodesign requirements banning mercury-containing lamps from September 2023 onward have triggered wholesale replacement cycles across commercial building portfolios.
- Municipal smart-city procurement:China's NEEA labeling program and urban lighting digitization initiatives are concentrating demand through consolidated tender processes.
- Indium gallium nitride efficacy gains:Commercial packages now exceeding 150 lumens per watt are collapsing payback periods for high-burn-hour installations.
Market Restraints
- Phosphor supply concentration:Rare-earth processing capacity clusters in China's Jiangxi and Inner Mongolia provinces, exposing downstream manufacturers to export quota volatility.
- Thermal management complexity:High-lumen-density COB arrays require aluminum or copper heat sinks that inflate bill-of-materials costs relative to legacy lamp retrofits.
- Driver semiconductor lead times:Silicon carbide MOSFET and GaN controller shortages extend production schedules for specification-grade fixtures.
Strategic Opportunities
- Human-centric lighting protocols:Circadian-rhythm tuning systems integrating melanopic lux metrics are penetrating healthcare and education verticals.
- India's UJALA program expansion:State-level distribution of LED bulbs at subsidized rates is building residential familiarity that transfers to commercial specification.
- Li-Fi convergence:Visible-light communication modules embedding data transmission into luminaire infrastructure are opening dual-revenue models for installation contractors.
Industry Challenges
- CALiPER testing backlog:US Department of Energy qualification queues delay product listing timelines, compressing launch windows against code-compliance deadlines.
- Legacy control protocol fragmentation:Integration of DALI-2, 0-10V, and emerging wireless mesh standards requires field-configurable drivers that inflate SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid State Lighting System Market |
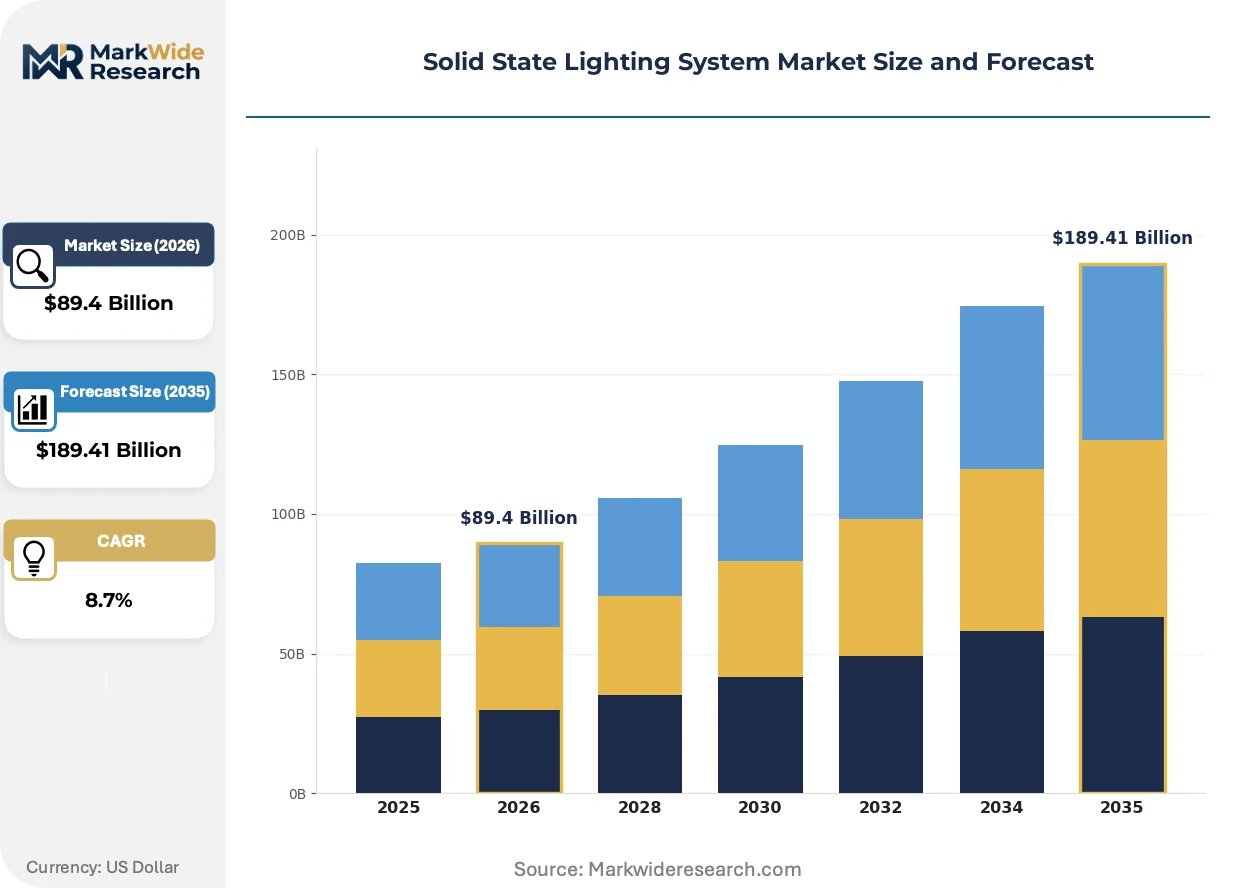
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $189.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, SSL Modules, Fixtures Application: Indoor Lighting, Outdoor Lighting, Automotive, Street Lighting Technology: Smart Lighting, RGB, Dimming Systems, Control Systems End User: Residential, Commercial, Industrial, Agriculture |
| Companies Covered | Signify Holding, Samsung Electronics, OSRAM Licht AG, General Electric Lighting, Nichia Corporation, Cree, Inc., Acuity Brands Lighting, Seoul Semiconductor, LG Innotek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid State Lighting System Market Evolving Landscape
Semiconductor packaging advances and converging building-automation protocols are compressing form factors while expanding functional integration, shifting competitive advantage from lumen output to system-level energy orchestration.
Chip-on-board LED modules are miniaturizing optical engines into sub-5mm profiles that enable luminaire designs previously impractical with discrete SMD packages. Architectural lighting manufacturers are adopting these platforms for cove and millwork integration where recess depth constraints previously mandated fiber optic or remote-phosphor solutions. The technology is miniaturizing the boundary between visible fixture and invisible infrastructure, collapsing the distinction between architectural element and light source.
China's GB standards for flicker-free operation and harmonic distortion are tightening ahead of anticipated alignment with IEC TR 63158 metrics, forcing driver redesigns for export-bound manufacturers. Domestic producers serving the NEEA labeling program must now certify to Pst LM limits below 1.0 and SVM thresholds under 0.4, specifications that filter undifferentiated suppliers from municipal tender eligibility. The policy is compressing the supplier base in favor of vertically integrated manufacturers with captive driver design capabilities.
Facility managers are unbundling lighting maintenance from comprehensive service contracts, shifting toward performance-guarantee models where contractors retain ownership of installed assets and sell illumination-as-a-service. This reconfiguration transfers capex burden to specialized ESCOs while aligning contractor incentives with actual energy savings rather than equipment throughput. The model is concentrating most visibly in Germany and the Netherlands, where energy service company licensing frameworks and metering infrastructure support verified savings claims.
Solid State Lighting System Market Segmentation
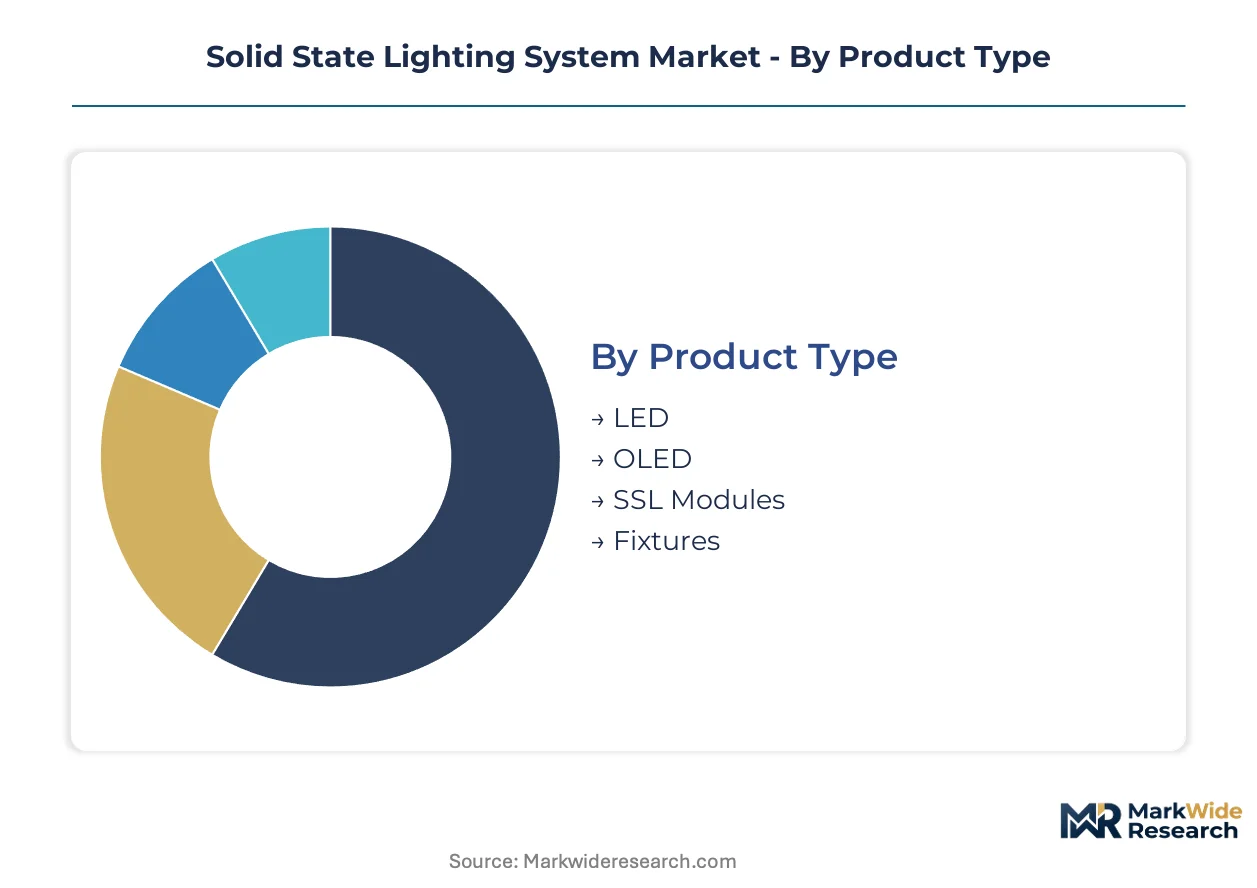
Segmentation in solid state lighting reveals how regulatory thresholds and efficacy benchmarks reshape procurement patterns across product categories. The EU Ecodesign Directive and comparable efficiency mandates in China and the United States partition demand into specification-grade and undifferentiated tiers, with certification status determining tender eligibility and retrofit financing access.
Product Type:
Regulatory differentiation separates mercury-free semiconductor platforms from legacy lamp technologies, with efficacy floors and flicker standards filtering supplier participation across each product category.
- LED:Indium gallium nitride junctions on sapphire or silicon carbide substrates generate photons through electroluminescence, routinely delivering efficacy above 150 lumens per watt in commercial packages. Demand concentrates in China's municipal smart-city programs and North American commercial retrofits, where high-burn-hour installations collapse payback periods against fluorescent and halogen legacy infrastructure.
- OLED:Organic semiconductor thin-film architectures enable surface-area emission across flexible substrates, eliminating point-source glare through Lambertian distribution patterns. Architectural niches in Germany and the Netherlands absorb premium pricing for millwork integration and cove applications where form factor constraints exclude discrete LED packages.
- SSL Modules:Integrated optical engines combining emitters, phosphor conversion layers, and thermal management substrates ship as sub-assemblies for luminaire OEMs. Module procurement clusters with vertically integrated manufacturers possessing captive driver design capabilities.
- Fixtures:Complete luminaire assemblies incorporating housing, optics, and control interfaces face divergent certification requirements across Energy Star, DLC Premium, and China's NEEA labeling program tiers.
Established volume favors LED; emerging adoption favors OLED.
Application:
Cost tier stratification separates high-volume replacement cycles from specification-grade installations, with payback sensitivity and maintenance access determining technology selection.
- Indoor Lighting:Commercial building retrofits dominate installed value as facility managers replace fluorescent troffers and downlights with semiconductor platforms. China's GB standards for flicker-free operation and harmonic distortion filter undifferentiated suppliers from municipal and institutional tender processes.
- Outdoor Lighting:Street and area illumination deployments prioritize lumen maintenance and thermal stability across extreme ambient temperature ranges. India's UJALA program expansion builds residential familiarity that transfers to commercial and municipal specification channels.
- Automotive:Headlamp and interior cabin applications demand thermal stability exceeding standard certification thresholds, with OSRAM Licht AG and comparable specialists anchoring position through projection-grade emitter qualification.
- Street Lighting:Municipal procurement consolidation through China's NEEA labeling program and urban digitization initiatives concentrates demand through tender processes specifying Pst LM limits below 1.0 and SVM thresholds under 0.4.
Replacement economics favor Indoor Lighting; connected infrastructure investment favors Street Lighting.
Technology:
Customer type segmentation separates building automation integrators from standalone retrofit contractors, with protocol compatibility determining specification lock-in.
- Smart Lighting:Building management systems integrating occupancy sensing, daylight harvesting, and circadian-rhythm tuning protocols expand fastest as healthcare and education verticals adopt melanopic lux metrics. Germany and the Netherlands lead performance-guarantee contracting models where ESCOs retain asset ownership.
- RGB:Multi-channel emitter architectures enable dynamic color temperature adjustment and saturated color rendering for entertainment and architectural accent applications. Hospitality and retail verticals in the United States specify RGB platforms for brand-aligned ambient programming.
- Dimming Systems:0-10V analog and DALI-2 digital control interfaces require field-configurable drivers that inflate SKU complexity for fixture manufacturers serving fragmented legacy infrastructure.
- Control Systems:Wireless mesh and Power-over-Ethernet architectures converge lighting networks with broader building automation platforms, with BACnet and KNX protocol integration determining specification for commercial new construction.
Standalone retrofit favors Dimming Systems; integrated building automation favors Smart Lighting.
End User:
Supply concentration shapes margin structure across end-user segments, with scale economies and certification burden determining competitive participation.
- Commercial:Facility managers unbundling maintenance from comprehensive service contracts shift toward illumination-as-a-service models. Performance-guarantee frameworks in Germany and the Netherlands align contractor incentives with verified energy savings rather than equipment throughput.
- Industrial:High-bay and hazardous-location applications demand thermal management robustness and ingress protection ratings that concentrate specification with vertically integrated manufacturers.
- Residential:India's UJALA program distributes LED bulbs at subsidized rates, building familiarity that transfers to commercial specification channels and export-competitive manufacturing scale.
- Agriculture:Horticultural lighting for controlled-environment agriculture applies specific photosynthetic photon flux density protocols, with spectral tuning for vegetative versus flowering growth stages penetrating greenhouse operations in the Netherlands and China.
Service-contract maturity favors Commercial; subsidy-driven volume favors Residential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility managers and municipal procurement offices concentrate demand across distinct national regulatory environments, with each geography imposing unique efficacy thresholds and flicker standards that filter supplier participation.
China
Municipal smart-city programs and domestic LED manufacturing scale create self-reinforcing procurement concentration. GB standards for flicker-free operation and NEEA labeling impose Pst LM limits below 1.0 that filter undifferentiated suppliers from tender eligibility. Jiangxi and Inner Mongolia provinces host rare-earth phosphor processing clusters that expose downstream manufacturers to export quota volatility.
Germany
Performance-guarantee contracting models align ESCO incentives with verified energy savings rather than equipment throughput. EU Ecodesign Directive phase-out schedules for mercury-containing lamps trigger wholesale replacement cycles across commercial building portfolios. Bavaria and North Rhine-Westphalia concentrate architectural OLED specification for millwork integration where form factor constraints exclude discrete LED packages.
United States
Commercial building retrofits redirect capital flows toward semiconductor-based luminaire platforms as facility managers replace fluorescent troffers. US Department of Energy CALiPER testing protocols maintain efficacy and color-quality benchmarks that compress product launch windows against code-compliance deadlines. Pacific Northwest and Northeast Corridor metros lead unbundling of lighting maintenance toward illumination-as-a-service frameworks.
India
State-level UJALA program distribution of LED bulbs at subsidized rates builds residential familiarity that transfers to commercial specification channels. Central Electricity Authority efficiency mandates shape export-competitive manufacturing scale for domestic producers. Maharashtra and Gujarat host vertically integrated fixture manufacturers with captive driver design capabilities serving municipal tender processes.
Netherlands
Energy service company licensing frameworks and metering infrastructure support verified savings claims under performance-guarantee models. Horticultural lighting for controlled-environment agriculture applies photosynthetic photon flux density protocols penetrating greenhouse operations. Randstad and Eindhoven Region concentrate circadian-rhythm tuning system adoption across healthcare and education verticals integrating melanopic lux metrics.
Solid State Lighting System Market Competitive Landscape
Player mix skews toward vertically integrated conglomerates with captive phosphor and driver supply chains alongside specialized emitters focused on automotive and projection-grade thermal stability requirements. The competitive structure bifurcates across specification-grade suppliers sustaining Energy Star and DLC Premium qualification cycles versus undifferentiated volume producers serving price-sensitive replacement demand. Two strategic archetypes dominate: conglomerates with backward integration into semiconductor substrates and specialists with deep thermal management expertise. Competitive moves concentrate on portfolio diversification into human-centric lighting protocols and strategic partnerships for Li-Fi convergence modules.
Within the conglomerate tier, Signify Holding and Samsung Electronics represent archetypes of upstream control over critical supply chain nodes, while OSRAM Licht AG exemplifies specialization in segments where thermal stability requirements exceed standard certification thresholds. Seoul Semiconductor occupies a position bridging volume scale and specification-grade qualification. These three anchors illustrate how competitive positioning depends on regulatory navigation capabilities across divergent regional flicker standards and circadian-health metrics.
| Leading Market Players |
|---|
| Signify Holding |
| Samsung Electronics |
| OSRAM Licht AG |
| General Electric Lighting |
| Nichia Corporation |
| Cree, Inc. |
| Acuity Brands Lighting |
| Seoul Semiconductor |
| LG Innotek |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements for rare-earth phosphor feedstock lock Chinese fixture manufacturers into price visibility corridors that shield against Jiangxi province export quota volatility while compressing margin buffers for undifferentiated volume producers dependent on spot-market indium gallium nitride wafer procurement.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange rare-earth oxide benchmarks dominate raw material procurement, with three-tier pricing structure across premium, standard, and economy levels separating DLC Premium-qualified suppliers from NEEA-labeled domestic producers and uncertified volume manufacturers. Pricing pressure stems from silicon carbide MOSFET shortages extending production schedules for specification-grade drivers. Municipal procurement offices in China exhibit lowest price sensitivity due to consolidated tender processes, while residential retrofit contractors in India face acute cost compression under UJALA program subsidy ceilings.
Supply Chain Analysis
Strategic stockpiling of aluminum and copper heat sink alloys prevails among German and Dutch ESCOs managing performance-guarantee contracts, while just-in-time inventory governs Chinese export-bound manufacturers serving fragmented North American specification channels. Supply concentrates in China for phosphor conversion materials, sapphire substrates, and driver assembly, with secondary clustering in South Korea for gallium nitride epitaxy equipment. Single-source vulnerability runs through Jiangxi province rare-earth processing capacity. Distribution runs through vertically integrated OEMs with captive luminaire assembly rather than modular component wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through China's NEEA municipal tender consolidation and Germany's ESCO licensing frameworks, fragmenting procurement access for undifferentiated suppliers while rewarding specification-grade qualification holders.
For Market Incumbents: Compound qualification advantages by accelerating captive driver design capabilities ahead of anticipated IEC TR 63158 flicker standard alignment, while defending against emerging Chinese domestic producers through Energy Star and DLC Premium portfolio breadth. Backward integration into phosphor supply chains mitigates Jiangxi export quota exposure.
For New Entrants and Emerging Players: Anchor in India's commercial retrofit channel where UJALA-program residential familiarity transfers to institutional specification, exploiting underpenetrated circadian-rhythm tuning verticals in healthcare and education. Pursue partnership-based entry with established ESCOs in Germany and the Netherlands rather than direct luminaire manufacturing.
For Investors and Strategic Acquirers: Driver-design specialists with field-configurable DALI-2 and wireless mesh capabilities represent the most defensible acquisition archetype as protocol fragmentation inflates SKU complexity. Watch for inflection when China's GB flicker standards tighten Pst LM limits below current 1.0 thresholds, filtering marginal suppliers from municipal eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Phosphor Supply Backward Integration | Captive rare-earth processing in Jiangxi insulates against export quota volatility disrupting driver production. |
| Human-Centric Lighting Protocol Development | Melanopic lux certification penetrates Dutch healthcare verticals ahead of codified procurement requirements. |
| Li-Fi Module Convergence Partnership | Visible-light communication embedding creates dual-revenue streams for German installation contractors. |
| NEEA Labeling Program Pre-Qualification | Early certification to sub-1.0 Pst LM standards secures tender eligibility in China's municipal smart-city procurement. |
| Performance-Guarantee ESCO Licensing | Verified savings frameworks in the Netherlands align contractor incentives with actual energy reduction outcomes. |
Research Methodology
The analysis maps LED, OLED, and SSL module sub-sectors, each validated through facility managers, municipal procurement officers, luminaire OEM technical directors, and phosphor supply chain specialists, combining primary interviews with secondary validation from US Department of Energy CALiPER testing protocols, EU Ecodesign Directive implementation reports, China GB standard filings, and NEEA labeling program databases, with bottom-up and top-down triangulation across product category and application dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical framework modeling technology adoption curves, regulatory phase-out schedules, and retrofit payback sensitivity by burn-hour intensity. CAGRs derive from segment-level unit economics and replacement cycle timing, incorporating indium gallium nitride efficacy improvement trajectories and rare-earth oxide price index movements as industry-specific forecast inputs.
Material uncertainties — regulatory divergence in circadian-health metrics, phosphor export quota disruptions, and silicon carbide MOSFET supply normalization — sit outside the modeled envelope. Forecasts reflect assumptions regarding municipal procurement consolidation rates and ESCO contract penetration. Revision becomes warranted when China's GB flicker standard alignment with IEC TR 63158 accelerates beyond anticipated timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Global Commercial Lighting Market
Lighting
Circadian Lighting Market
Lighting
Solar Rope Light Market
Lighting
Lighting Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Portable Lamps Market
Lighting
North America Street Lighting Market
Lighting
Wireless Lighting Market
Lighting
India Lighting Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Lamps and Lighting Market
Lighting
Smart Lamp Market
Lighting
OLED Lightening Panels Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Connected (Smart) Street Lighting Market
Lighting
Solid-State Lighting Source Market