
 Lighting Fixture Market | 2026-2036
Lighting Fixture Market Size, Share, and Industry Trends Forecast 2026-2036
Lighting Fixture Market Intelligence
Manufacturing expansion in Southeast Asian nations, particularly Vietnam and Malaysia, is reshaping the competitive positioning of established producers. This shift alters global supply chain dynamics. Signify N.V. leverages its extensive portfolio in professional and consumer lighting to maintain market leadership. Acuity Brands Inc. specializes in lighting and building management solutions for North American commercial markets, while Panasonic Holdings Corporation competes through its integrated electronics.
A lighting fixture is an electrical device containing a lamp holder and components to position, protect, and connect the light source to a power supply. These fixtures are engineered to control light distribution, with specifications for lumen output, color rendering index, and beam angle being critical performance metrics. The transition to LED technology continues to dominate, displacing older fluorescent and incandescent options. Within applications, the commercial sector shows significant momentum, while recessed lighting and pendant lights lead product type adoption.
Product design and market access are governed by stringent energy efficiency and material safety regulations. Frameworks such as the EU's Ecodesign Directive, the EPA's ENERGY STAR program in the United States, and China's GB standards for lighting mandate specific performance and safety thresholds. Key stakeholder decisions will increasingly center on integrating connectivity and data analytics capabilities while navigating emerging cybersecurity and privacy concerns within advanced smart lighting networks.
Market Dynamics
The integration of connectivity into solid-state lighting defines the market's central structural force. This shift moves the value proposition from simple illumination toward data generation and network-centric control within smart buildings and urban infrastructure, altering product design and competitive strategy.
Growth Catalysts
- Government Mandates:Energy efficiency regulations, including the EU's Ecodesign Directive and the EPA's ENERGY STAR program in the United States, compel the adoption of LED technology by setting performance floors that older technologies cannot meet.
- Smart City Initiatives:Large-scale urbanization projects, particularly in China and India, create substantial demand for connected street lighting and public space illumination, serving as foundational infrastructure for broader smart city networks.
- LED Technology Maturation:Continuous improvements in lumen-per-watt efficacy, coupled with decreasing production costs for LED chips and drivers, make advanced lighting systems economically viable for mass-market commercial and residential retrofits.
Market Restraints
- High Initial Investment:The upfront capital cost for networked smart lighting systems, including fixtures, sensors, and control software, remains a significant barrier for budget-constrained end-users compared to conventional, non-connected alternatives.
- Component Supply Volatility:A dependency on the global semiconductor industry for drivers, microcontrollers, and connectivity chips exposes fixture manufacturers to price fluctuations and supply chain disruptions, impacting production schedules and costs.
- Interoperability Standards:A lack of universal communication protocols across different manufacturers' smart lighting ecosystems creates complexity and integration challenges for installers and building managers, leading to vendor lock-in concerns.
Strategic Opportunities
- Horticultural Lighting:The expansion of controlled environment agriculture creates a significant opportunity for specialized LED fixtures optimized for crop-specific light spectra, driving yield and energy efficiency in vertical farms and greenhouses.
- Human-Centric Lighting:Developing tunable lighting systems that can dynamically adjust color temperature and intensity to support human circadian rhythms presents a high-value opportunity in corporate offices, healthcare facilities, and educational institutions.
- Lighting-as-a-Service (LaaS):Offering subscription-based models that bundle hardware, software, installation, and maintenance provides a recurring revenue stream and lowers the adoption barrier for customers by shifting costs from capex to opex.
Industry Challenges
- Cybersecurity Vulnerabilities:Securing connected lighting networks against potential breaches presents a major operational challenge, requiring manufacturers to build expertise in network security, encryption, and secure software development lifecycle practices. *Regulatory Compliance Complexity: Navigating the fragmented and evolving landscape of energy, safety, and material standards, such as RoHS and China's GB standards, across multiple jurisdictions increases testing time and certification costs.
- Skilled Labor Shortages:The industry faces a talent gap for professionals with combined expertise in lighting science, software engineering, and data analytics, which is critical for developing and deploying advanced lighting control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lighting Fixture Market |
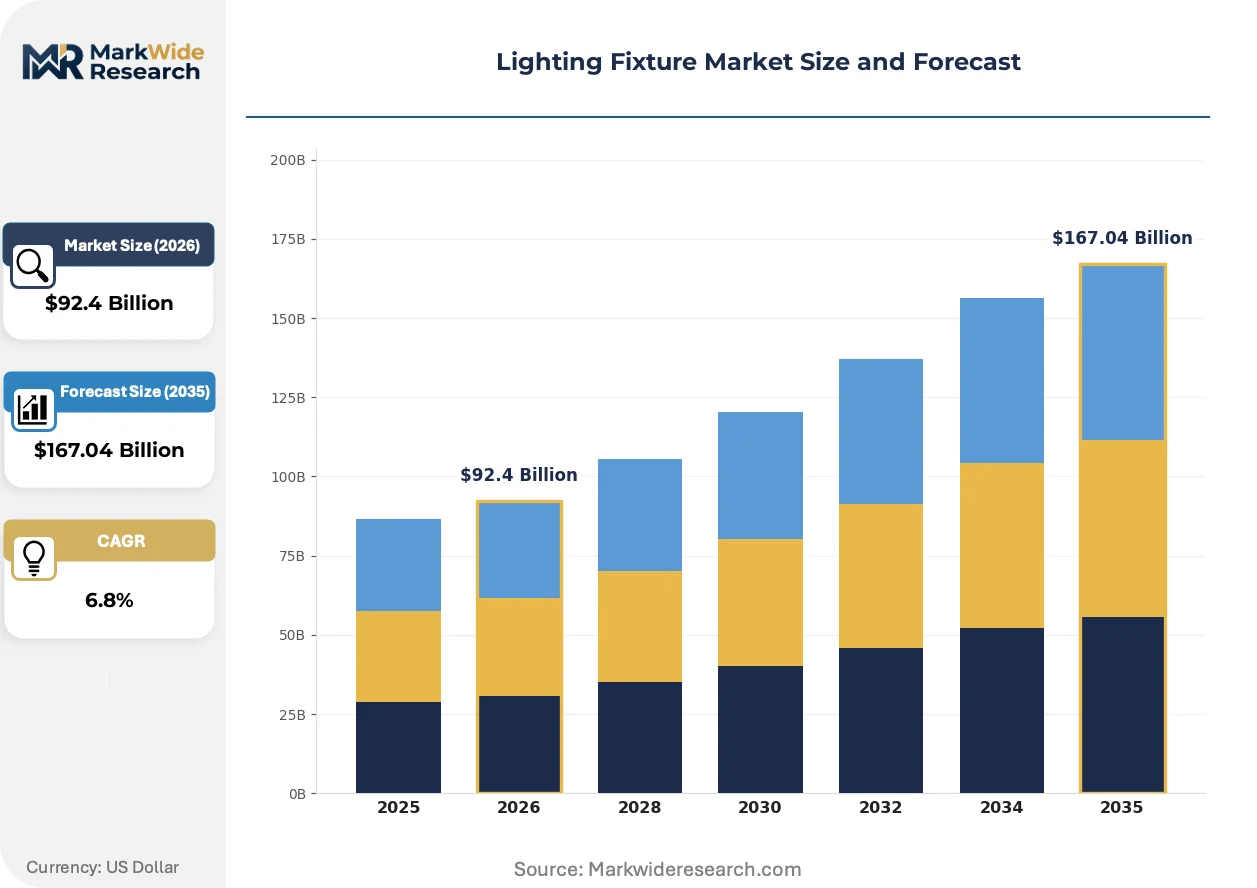
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $167.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chandeliers, Pendant Lights, Wall Sconces, Recessed Lighting Technology: LED, Fluorescent, Incandescent, Halogen Application: Residential, Commercial, Industrial, Outdoor Size: Compact, Standard, Oversized, Custom |
| Companies Covered | Signify N.V., Acuity Brands Inc., Hubbell Incorporated, Panasonic Holdings Corporation, Zumtobel Group AG, ams OSRAM AG, Eaton Corporation plc, LEDVANCE GmbH, Cree Lighting USA LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lighting Fixture Market Strategic Shifts & Innovations
The market's evolution is defined by the fixture's transformation from a standalone electrical device into an intelligent, data-collecting node within a larger building or city ecosystem. This transition prioritizes software, connectivity, and data analytics as core components of product value and differentiation.
Digital twin technology provides a complete virtual replica of a physical lighting installation, including fixtures, sensors, and wiring. Commercial facility managers and municipal planners are the primary adopters, using the models for energy consumption simulation and predictive maintenance scheduling. This technology is virtualizing the entire lifecycle of system management, from initial design validation to remote troubleshooting, significantly reducing the need for on-site commissioning and physical inspections.
Circular economy principles are gaining regulatory traction, exemplified by the European Union's Ecodesign Directive. The regulation mandates that fixtures be designed for disassembly, repair, and component replacement, directly targeting the "throwaway" nature of early-generation integrated LED products. Commercial and industrial lighting segments are most impacted, pushing manufacturers to develop modular designs and provide long-term availability of spare parts like drivers and light engines.
End-user purchasing behavior is evolving from a focus on one-time capital expenditure to a preference for total cost of ownership and performance-based outcomes. This change disrupts the traditional distributor-contractor sales channel, favoring manufacturers who can offer integrated solutions and service contracts directly to large enterprise clients. The shift is most pronounced in the North American and European commercial real estate sectors, where energy and operational efficiency are key procurement drivers.
Lighting Fixture Market Segmentation
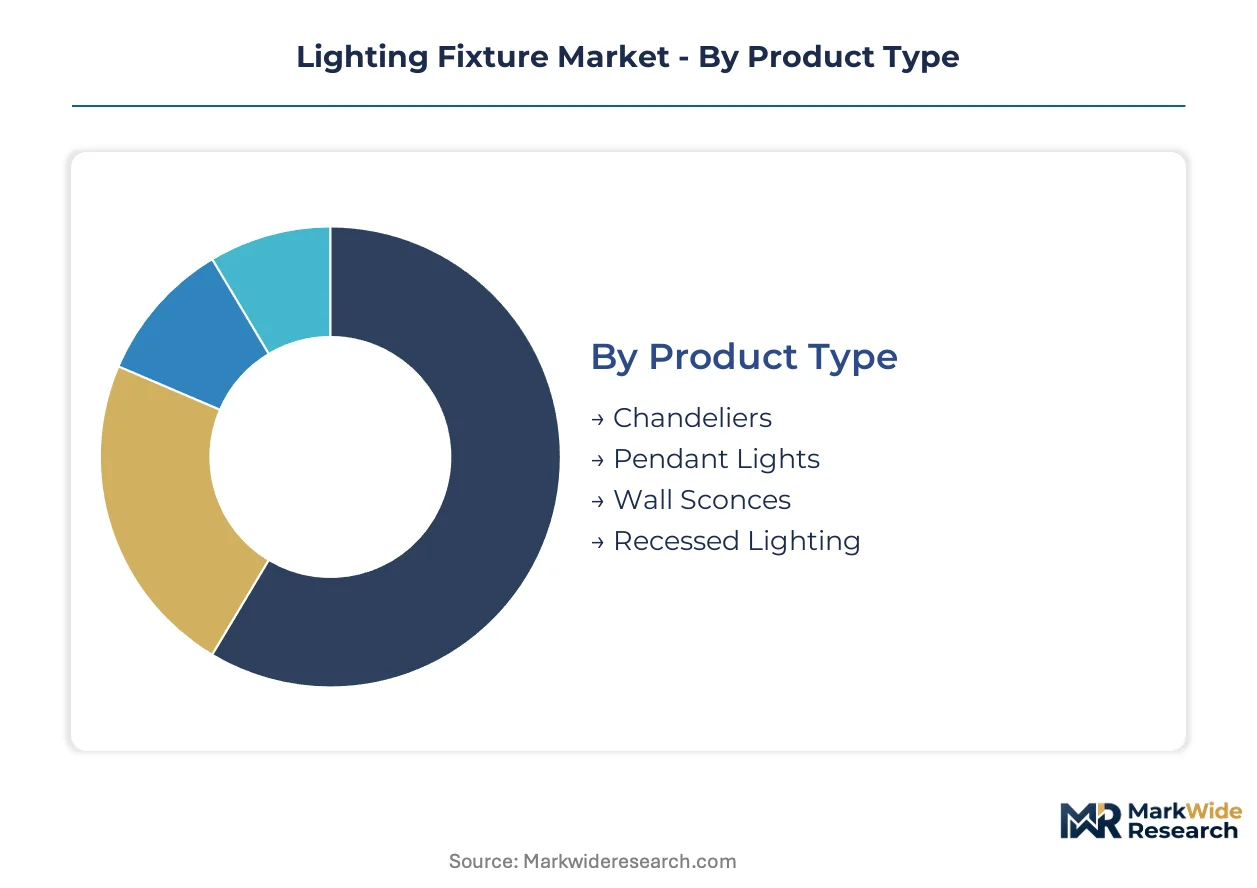
The Lighting Fixture Market's segmentation provides a granular view of product evolution and end-user adoption patterns. Understanding these divisions helps stakeholders identify areas of high growth, technological shifts, and specific market needs across diverse applications.
Product Type:
The product type segmentation reveals a market with both mature offerings and emerging design trends shaping consumer and commercial spaces.
- Recessed Lighting:These fixtures are installed within a ceiling or wall, providing a clean, unobtrusive aesthetic with controlled light distribution. Demand concentrates in the commercial sector for smart building retrofits, driven by the need for integrated control systems and energy efficiency.
- Pendant Lights:Suspended from the ceiling by a rod or chain, these fixtures often serve as focal points, combining illumination with decorative appeal. Demand is strong in residential and hospitality environments, where design flexibility and aesthetic integration are key drivers.
- Chandeliers:Ornamental, multi-arm light fixtures suspended from the ceiling, typically featuring multiple lamps and decorative elements.
- Wall Sconces:Decorative or functional light fixtures mounted directly to a wall, providing ambient or accent lighting.
Recessed Lighting retains volume leadership; Pendant Lights hold the steepest expansion curve.
Technology:
The technology segmentation highlights the market's transition from legacy illumination sources to advanced, integrated systems.
- LED:Light Emitting Diode technology utilizes semiconductors to produce light, offering high energy efficiency, long lifespan, and compact form factors. Widespread adoption concentrates in commercial and smart city initiatives, driven by government mandates and continuous improvements in lumen-per-watt efficacy.
- Fluorescent:These gas-discharge lamps produce light by exciting mercury vapor, commonly used in older commercial and industrial settings due to their broad light output. Regulatory phase-outs and lower energy efficiency compared to modern alternatives constrain their demand.
- Incandescent:Traditional lighting technology producing light from a heated filament, characterized by warm light but low energy efficiency.
- Halogen:A type of incandescent lamp using a halogen gas capsule to improve light output and lifespan compared to standard incandescent bulbs.
LED technology dominates the market, displacing older, less efficient alternatives.
Application:
Application segmentation illustrates how varied end-user environments drive distinct demand patterns for lighting fixtures.
- Commercial:This segment encompasses lighting solutions for offices, retail spaces, hospitality venues, and healthcare facilities, often requiring advanced control and integration. Demand is particularly strong in North American and European commercial real estate sectors, driven by operational efficiency and smart building retrofits.
- Outdoor:Fixtures designed for public spaces, street lighting, architectural facades, and landscape illumination, engineered for durability and environmental resistance. Demand concentrates in China and India for urban infrastructure projects, serving as foundational elements for broader smart city networks.
- Residential:Lighting products for homes, including living rooms, bedrooms, kitchens, and bathrooms, focusing on aesthetics, comfort, and personalized control.
- Industrial:Robust and high-lumen output fixtures for factories, warehouses, and manufacturing plants, prioritizing durability, visibility, and safety.
The commercial sector drives significant market value, while outdoor applications exhibit strong growth potential.
Size:
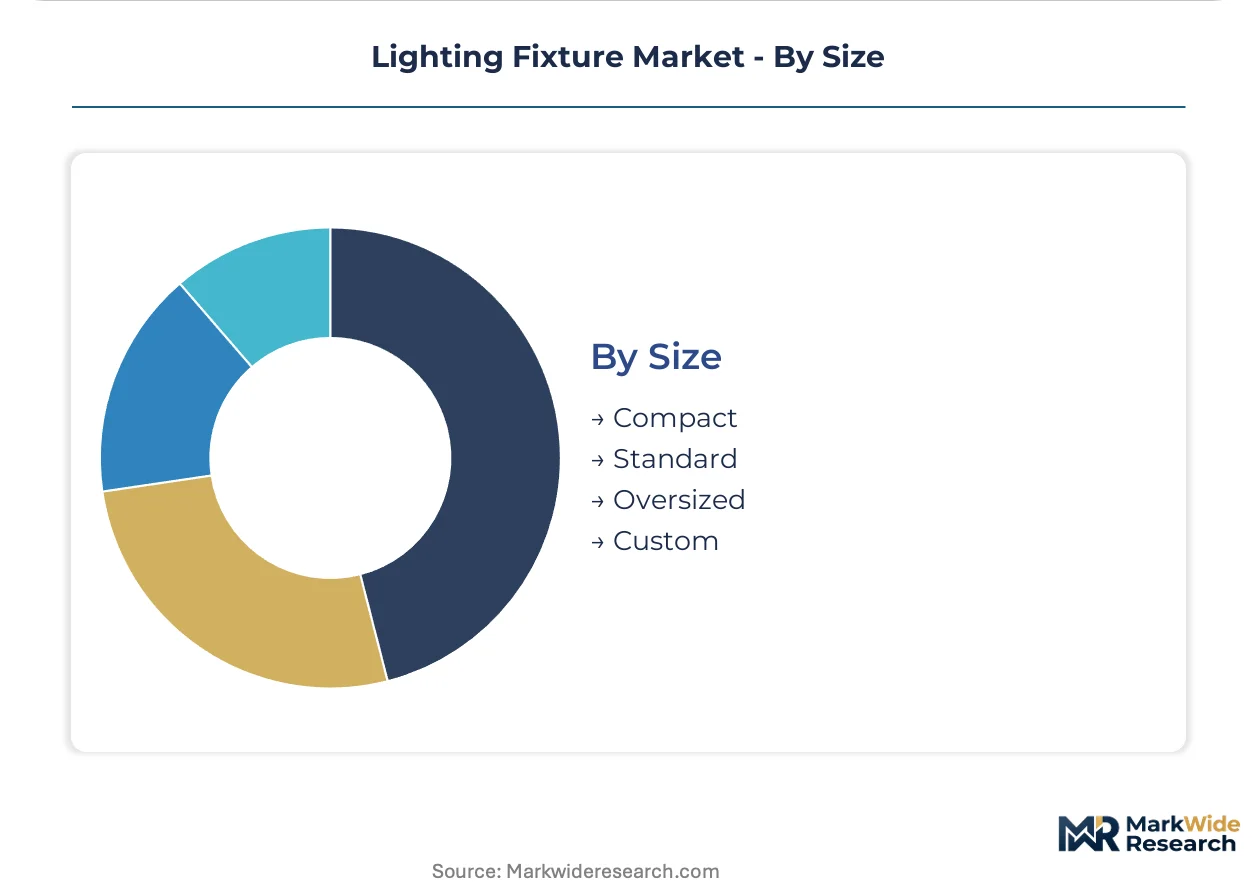
Size segmentation reflects diverse customer preferences and architectural requirements across different installation environments.
- Standard:Commonly available fixture sizes that fit typical residential and commercial installation dimensions, offering broad compatibility and ease of procurement. Demand is widespread across residential and small commercial projects, primarily driven by cost-effectiveness and readily available options.
- Custom:Bespoke lighting fixtures designed and manufactured to specific client requirements for dimensions, aesthetics, or performance. Demand concentrates in luxury hospitality and high-end architectural projects, where unique design and seamless integration are paramount.
- Compact:Small-footprint lighting fixtures designed for discreet installation or tight spaces, often used for accent lighting or under-cabinet applications.
- Oversized:Large-scale lighting fixtures making a significant visual statement, typically found in grand commercial lobbies or large public spaces.
Standard sizes meet broad market needs, with custom solutions catering to niche architectural demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards for lighting products significantly influence regional market dynamics. These stringent regulations mandate specific performance and safety thresholds, compelling manufacturers to adopt advanced technologies. This regulatory environment, combined with large-scale urbanization, shapes demand.
China
Large-scale urbanization initiatives and smart city projects drive substantial demand for connected street lighting and public space illumination. The country's dual carbon goals accelerate the adoption of energy-efficient LED solutions. Industrial zones in the Yangtze River Delta actively integrate smart lighting networks for operational efficiency.
India
Government-led infrastructure development and significant urbanization initiatives create a robust market for outdoor and commercial lighting fixtures. The Bureau of Indian Standards (BIS) promotes quality and energy efficiency. Major metropolitan areas like Mumbai and Delhi are foundational for broader smart city networks.
United States
Commercial sector retrofits and new construction projects underpin demand for energy-efficient lighting solutions. The Environmental Protection Agency's (EPA) ENERGY STAR program incentivizes high-performance LED fixtures. Technology hubs in California and the Northeast corridor lead in integrating advanced smart building management systems.
Germany
The European Ecodesign Directive mandates drive the adoption of energy-efficient and modular lighting fixtures across commercial and industrial applications. Demand for human-centric lighting solutions is pronounced in corporate offices. The Rhine-Ruhr region, a major industrial hub, focuses on sustainable and intelligent lighting infrastructure.
Vietnam
Manufacturing expansion in Southeast Asian nations is reshaping global supply chain dynamics for lighting fixtures. Government support for industrial development attracts foreign direct investment into electronics manufacturing. Production clusters around Ho Chi Minh City and Hanoi are becoming significant hubs for component and fixture assembly.
Lighting Fixture Market Key Industry Players
Diversified conglomerates and specialized solution providers split the Lighting Fixture Market. The market structure exhibits a tiered consolidation, with a few large players holding significant portfolio breadth across various applications. Established producers leverage extensive portfolios to maintain market leadership, while agile specialists target niche applications like human-centric or horticultural lighting. Competitive moves include strategic partnerships for smart technology integration and continuous portfolio diversification into advanced lighting systems.
Within the diversified conglomerate tier, Signify N.V. exemplifies broad market leadership with its extensive professional and consumer lighting portfolio. Acuity Brands Inc., an Inc.-structured entity, occupies a strong position as a specialized solution provider focusing on lighting and building management systems for North American commercial markets. Panasonic Holdings Corporation, a Japanese Holdings Corporation, represents another integrated electronics giant competing through its wide-ranging technological offerings. These entities anchor distinct segments of the market through their strategic approaches.
| Leading Market Players |
|---|
| Signify N.V. |
| Acuity Brands Inc. |
| Hubbell Incorporated |
| Panasonic Holdings Corporation |
| Zumtobel Group AG |
| ams OSRAM AG |
| Eaton Corporation plc |
| LEDVANCE GmbH |
| Cree Lighting USA LLC |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes significantly impact lighting fixture pricing, as their cost dynamics link Asian manufacturing concentration to regional price differentiation. Volatility in freight rates directly influences the final cost structure for end-users.
Pricing Analysis
Geographic price spreads for lighting fixtures are evident between high-demand Western markets and lower-cost Asian manufacturing hubs. Project-based pricing dominates commercial installations, with per-unit transactional models prevailing in residential segments. Price differentiation stems from certification level requirements, such as ENERGY STAR, and bundled after-sales service offerings. Pricing softness reflects continuous LED technology maturation. Residential buyers exhibit higher price sensitivity compared to commercial clients prioritizing total cost of ownership.
Supply Chain Analysis
Contract manufacturing in Vietnam and Malaysia holds significant capacity for lighting fixture assembly, anchoring global supply. Geographic supply concentration also includes China for LED chips and various components. The industry draws from the global semiconductor industry for drivers and microcontrollers, where component supply volatility represents a structural risk. Distribution runs through traditional distributor-contractor channels, with a growing shift towards direct manufacturer-to-enterprise service contracts for integrated solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lighting Fixture Market is witnessing a significant shift in buyer power, driven by the evolving procurement patterns of large enterprise clients. Commercial real estate sectors in North America and Europe increasingly consolidate demand around total cost of ownership.
For Market Incumbents: Entrench existing market share by accelerating portfolio diversification into advanced lighting systems and smart building solutions. Form strategic partnerships for seamless smart technology integration, countering agile specialists targeting niche applications like human-centric lighting. Invest in robust cybersecurity expertise to mitigate vulnerabilities within advanced lighting networks. Deepen vertical integration into software and data analytics capabilities to reinforce long-term competitive advantage.
For New Entrants and Emerging Players: Establish a beachhead in underserved, high-growth segments such as horticultural lighting, leveraging specialized LED fixtures. Target human-centric lighting solutions in corporate offices and healthcare facilities, emphasizing tunable light spectra for circadian rhythm support. Penetrate the market with Lighting-as-a-Service (LaaS) models, lowering initial investment barriers for budget-constrained end-users. Focus on developing integrated control software to differentiate from traditional hardware-centric offerings.
For Investors and Strategic Acquirers: Circular economy principles, exemplified by the EU's Ecodesign Directive, reshape the acquisition landscape for lighting fixture manufacturers. Long-term value creation hinges on firms with strong R&D in connectivity and data analytics. Target agile specialists in human-centric or horticultural lighting, or those with robust software integration capabilities. Watch for increasing adoption rates of Lighting-as-a-Service models as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding manufacturing in Southeast Asian nations optimizes production costs for Signify N.V. and other large players. |
| Strategic Partnership | Forming alliances for smart technology integration enhances Acuity Brands Inc.'s building management solutions. |
| Product Launch | Introducing tunable human-centric lighting systems captures high-value opportunities in healthcare facilities. |
| Service Model Introduction | Offering Lighting-as-a-Service reduces upfront investment for commercial clients like Panasonic Holdings Corporation. |
| Green Manufacturing Transition | Adopting circular economy principles ensures compliance with the EU's Ecodesign Directive. |
Research Approach
Operator-level perspectives from commercial facility managers, municipal planners, and lighting engineers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from sources such as EPA's ENERGY STAR program data and EU Ecodesign Directive reports. This approach employed both bottom-up and top-down triangulation to ensure comprehensive market understanding. Company annual reports and industry association publications also informed the data collection process.
Scenario-bracketing techniques were applied to project market trajectories across the modeling period, accounting for various growth accelerators and restraints. The analytical framework modeled market dynamics across product type, technology, application, and geographic region. Compound annual growth rates were derived from historical data and projected adoption curves, considering factors like LED efficacy improvements. Urbanization rates in China and India served as key forecast inputs.
Stress conditions across component supply volatility and interoperability standards fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory stability and sustained investment in smart infrastructure. Quarterly review of semiconductor supply chain health and smart city project funding is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
High Bay Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
Lighting Management System Market
Lighting
Lamps and Lighting Market
Lighting
US Indoor LED Lighting Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Street Lighting Market
Lighting
Global Headlight Control Module Market
Lighting
Intelligent Lighting Controls Market
Lighting
Ultraviolet Lamps Market
Lighting
Ambient Lighting Market
Lighting
Global Plasma Lamp Market
Lighting
Global Work Lights Market
Lighting
North America Smart Lighting Market
Lighting
Global Machine Vision Lighting Market
Lighting
Vintage Bulb Market