
 Radiometric Detectors Market | 2026-2036
Radiometric Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Radiometric Detectors Market Analytics
Modular detector configurations are shifting buyer choice toward field-swappable sensor heads and interchangeable scintillation crystals. Thermo Fisher Scientific Inc. leverages its semiconductor fabrication depth to produce high-purity germanium detectors for nuclear safeguards applications. Mirion Technologies, Inc. dominates military and homeland security channels through long-term service contracts. Berthold Technologies GmbH & Co. KG specializes in process-control radiometry for chemical and mining operations.
Radiometric detectors are instruments that measure ionizing radiation intensity, energy distribution, or particle flux through scintillation light emission, gas ionization, or solid-state charge collection, typically specified by energy resolution in keV and detection efficiency across defined energy windows. Their primary purpose spans personnel safety assurance, regulatory compliance verification, and quantitative material analysis in hazardous or controlled environments. Semiconductor technology captures premium margin pools due to superior energy resolution in spectroscopic applications, while scintillation systems retain volume leadership in portal monitoring and environmental surveillance. Gas-filled detectors maintain a stable niche in legacy industrial gauging where cost sensitivity outweighs performance demands.
The FDA oversees medical imaging device performance standards under 21 CFR 1020, while the EPA administers environmental radiation monitoring protocols through RadNet and NESHAP frameworks. ISO 4037 calibration standards and IEC 60580 dose-meter specifications shape product interoperability and cross-border market access for manufacturers. Stakeholders must weigh capital allocation between semiconductor R&D and scintillation supply chain security as detector architectures diverge across end-use requirements.
Market Dynamics
Semiconductor-based detector architectures are compressing development cycles while fragmenting procurement specifications across medical, industrial, and security end-uses. The divergence between high-resolution spectroscopy requirements and cost-sensitive portal monitoring is forcing manufacturers to maintain dual technology roadmaps without scale economies.
Growth Catalysts
- FDA 510(k) pathway compression:The streamlined clearance mechanism for radiation-emitting medical devices accelerates product commercialization timelines for semiconductor detector arrays in diagnostic imaging networks.
- German research infrastructure modernization:Helmholtz centers and industrial metrology firms are replacing legacy scintillation systems, creating concentrated demand for high-purity germanium detectors in nuclear safeguards and materials analysis.
- Scintillation crystal interchangeability:Field-swappable sensor head designs reduce downtime in continuous process-control environments, particularly in chemical and mining operations requiring rapid crystal replacement.
Market Restraints
- Germanium supply concentration:High-purity germanium crystal growth capabilities concentrate among limited specialty semiconductor foundries, exposing detector manufacturers to single-source supply risk.
- EPA RadNet interoperability mandates:Environmental radiation monitoring networks require legacy-compatible data formats, slowing adoption of next-generation solid-state detectors with superior energy resolution.
- Gas-filled detector cost floor:Industrial gauging applications in emerging markets maintain demand for ionization chambers where scintillation or semiconductor alternatives cannot match unit economics.
Strategic Opportunities
- India nuclear power expansion:The country's reactor construction program and associated safeguards infrastructure create demand for portal monitors and spent fuel verification systems.
- IEC 60580 dose-meter convergence:Harmonized international calibration standards enable cross-border service contracts and reduce certification duplication for multi-national hospital networks.
- Artificial intelligence integration:Machine learning-based spectral deconvolution algorithms are expanding addressable applications for lower-cost scintillation detectors in materials identification.
Industry Challenges
- Cryogenic engineering talent scarcity:High-purity germanium detector manufacturing requires specialized low-temperature physics expertise that concentrates among aging workforce cohorts in established nuclear science centers.
- ISO 4037 calibration facility capex:Accredited reference radiation fields require substantial capital investment in certified sources and shielded enclosures, creating barriers to service network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiometric Detectors Market |
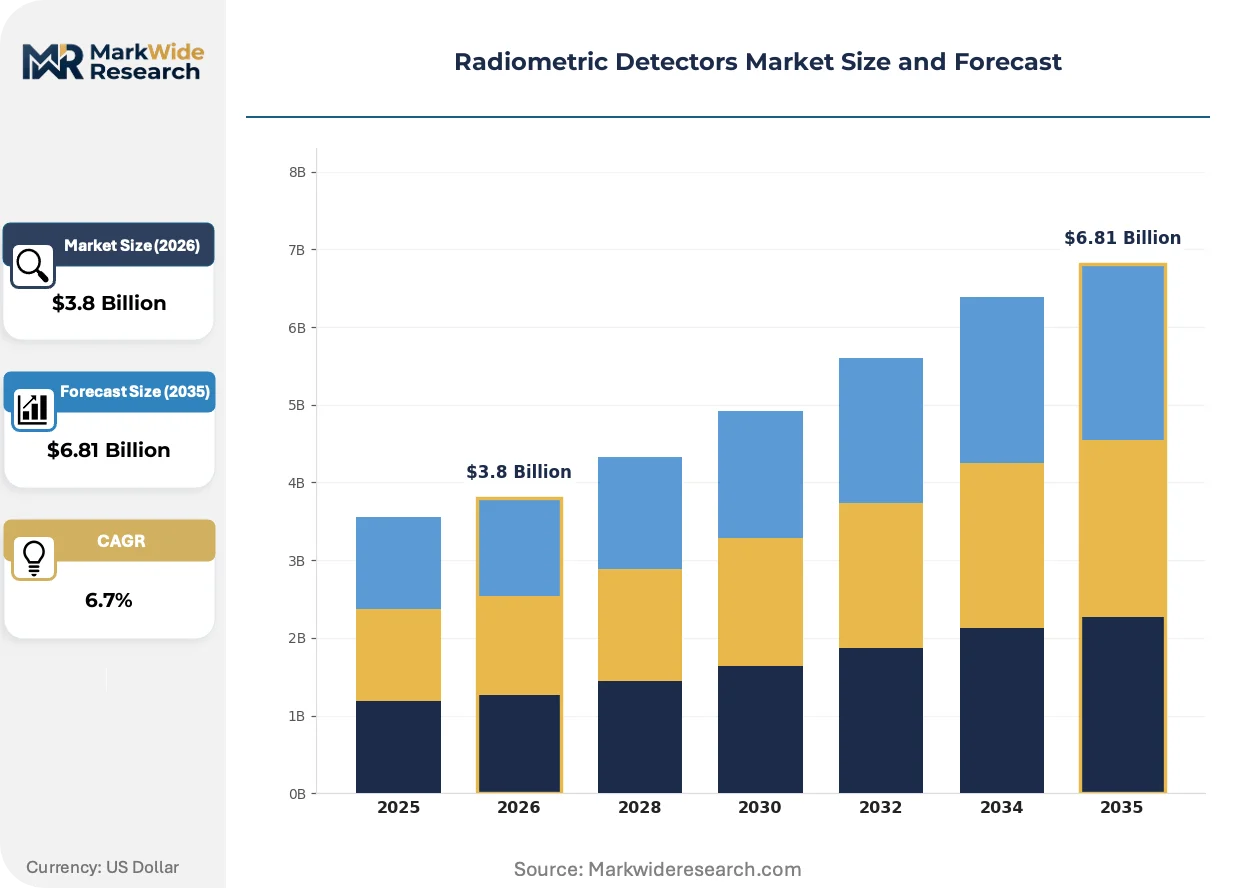
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gamma Detectors, Neutron Detectors, X-ray Detectors, Particle Detectors End User: Industrial, Medical, Research Institutions, Defense Technology: Scintillation, Gas-filled, Semiconductor, Thermal Application: Nuclear Safety, Environmental Monitoring, Medical Imaging, Security |
| Companies Covered | PerkinElmer Inc., Mirion Technologies, Inc., Ludlum Measurements, Inc., Thermo Fisher Scientific Inc., AMETEK, Inc., Gigahertz-Optik, Inc., Berthold Technologies GmbH & Co. KG, Gamma Scientific Inc., Sierra Olympic Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiometric Detectors Market Evolving Landscape
Cadmium-zinc-telluride (CZT) semiconductor arrays are penetrating clinical modalities previously dominated by scintillation cameras, while regulatory frameworks accelerate device convergence across medical and industrial applications. Procurement specifications increasingly mandate interoperability with legacy infrastructure alongside performance thresholds.
CZT direct-conversion detectors eliminate light-collection inefficiencies inherent in scintillation-based architectures, enabling single-photon counting at room temperature. Cardiac SPECT departments in tertiary hospital networks are retrofitting Anger camera gantries with tiled CZT modules to improve energy resolution and reduce radiopharmaceutical dose. The technology is expanding into portable gamma spectroscopy instruments for field-deployed nuclear safeguards verification.
Europe's MDR implementation for radiation-emitting medical devices is harmonizing performance documentation requirements across member states. Manufacturers must now maintain technical files demonstrating compliance with essential safety and performance criteria that previously varied by national competent authority. German notified bodies are processing the majority of Class IIa and IIb device certifications, creating geographic concentration in regulatory service provision.
Hospital procurement consortia are unbundling detector hardware from long-term service agreements that previously locked buyers into single-vendor maintenance networks. Large US health systems now negotiate separate contracts for semiconductor array replacement, calibration services, and software upgrades. This disintermediation is most advanced in California and Texas, where integrated delivery networks operate sufficient imaging fleet scale to justify in-house physics support staff.
Radiometric Detectors Market Segmentation
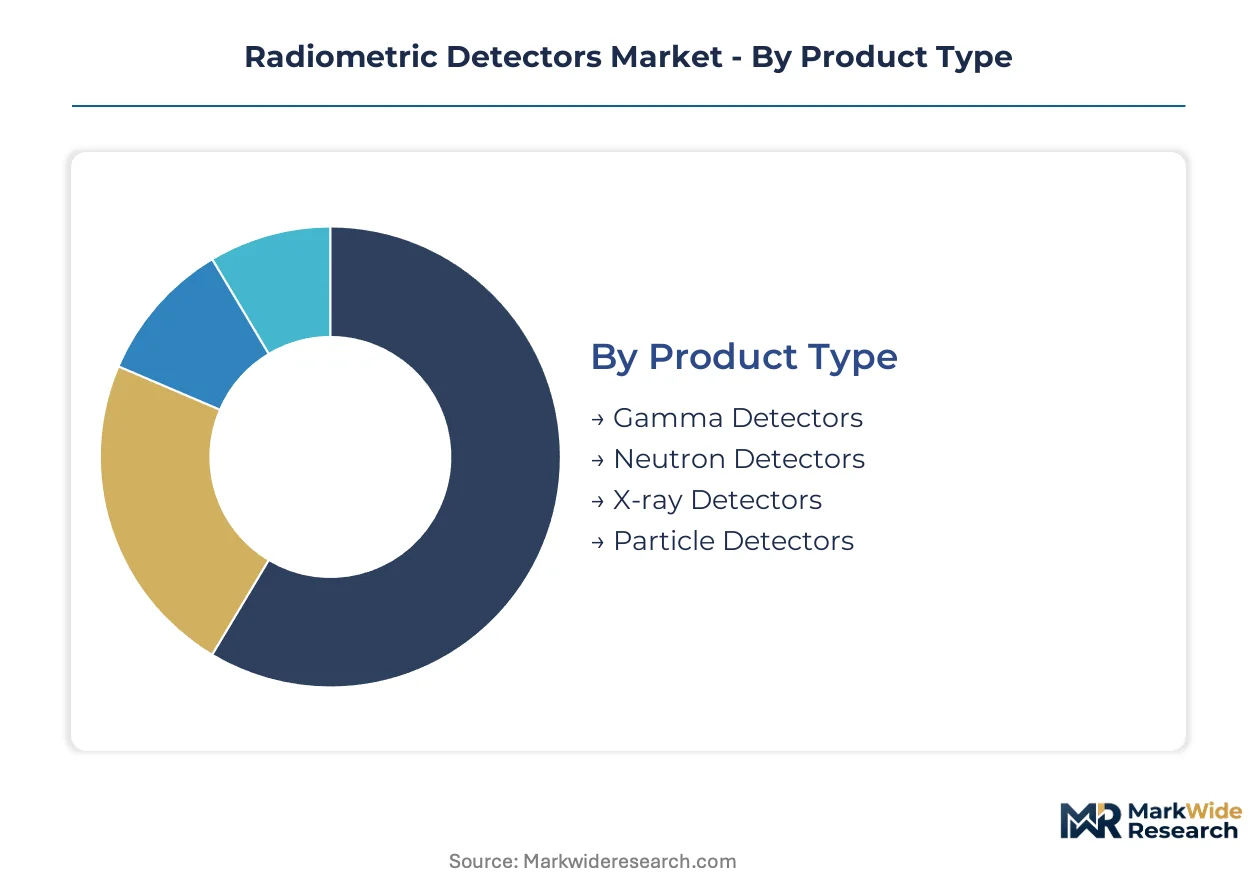
Radiometric detector procurement specifications fragment sharply across end-use requirements. Buyers prioritize resolution, portability, or cost depending on whether deployment targets clinical SPECT suites, portal monitors at border crossings, or process-control environments in chemical plants.
Product Type:
Detection physics and shielding requirements differentiate product architectures more than any other axis.
- Gamma Detectors:These instruments measure photon emissions across keV to MeV energy ranges through scintillation crystals, semiconductor diodes, or gas ionization chambers. Hospital networks in Germany and the United States are retrofitting nuclear medicine departments with high-purity germanium arrays for improved spectroscopic accuracy in radiopharmaceutical verification.
- X-ray Detectors:Direct-conversion semiconductor tiles, particularly cadmium-zinc-telluride modules, are displacing legacy scintillation cameras in cardiac SPECT systems. The FDA's 510(k) pathway compression accelerates commercialization timelines for these semiconductor arrays in diagnostic imaging networks.
- Neutron Detectors:Helium-3 proportional counters and boron-lined ionization chambers dominate safeguards verification and reactor instrumentation.
- Particle Detectors:Solid-state tracking arrays and time-projection chambers serve high-energy physics installations and space radiation monitoring.
Gamma detectors lead on scale; X-ray detectors lead on momentum.
End User:
Customer procurement sophistication and service contract structures vary dramatically by institutional type.
- Medical:Tertiary hospital networks negotiate unbundled contracts separating hardware, calibration, and software maintenance. California and Texas integrated delivery networks now employ in-house medical physics staff to manage semiconductor array replacement cycles independently.
- Defense:Long-term service agreements with fixed-price maintenance provisions characterize military and homeland security procurement. Mirion Technologies holds dominant position through multi-year sustainment contracts covering portable spectroscopy and portal monitoring systems.
- Industrial:Chemical and mining operations prioritize field-swappable sensor heads to minimize process downtime during crystal replacement.
- Research Institutions:Helmholtz centers and comparable facilities drive demand for cryogenic germanium systems in nuclear safeguards and materials analysis applications.
Medical end users lead on scale; defense end users lead on contract duration.
Technology:
Performance thresholds and cost floors diverge across detection mechanisms, forcing manufacturers to maintain parallel development roadmaps.
- Semiconductor:High-purity germanium and cadmium-zinc-telluride arrays deliver superior energy resolution for spectroscopic applications. Cryogenic engineering talent scarcity concentrates manufacturing among established nuclear science centers with aging workforce cohorts.
- Scintillation:Sodium iodide and lanthanum bromide crystals retain volume leadership in portal monitoring and environmental surveillance where cost sensitivity limits semiconductor penetration. Field-swappable crystal designs reduce downtime in continuous process-control operations.
- Gas-filled:Ionization chambers and proportional counters maintain stable niche in legacy industrial gauging applications.
- Thermal:Thermoluminescent dosimeters and optically stimulated luminescence systems serve passive personnel monitoring requirements.
Scintillation leads on scale; semiconductor leads on margin expansion.
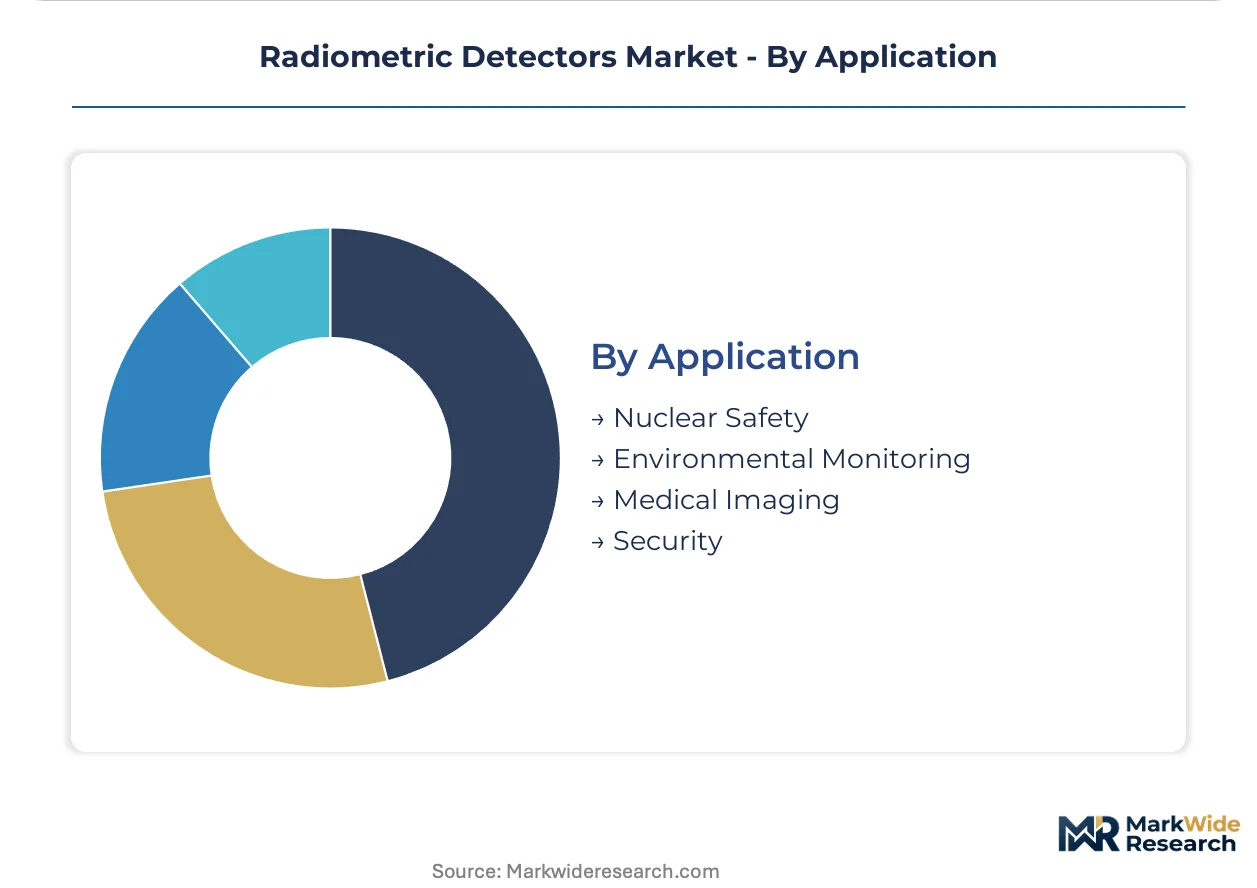
Application:
Regulatory compliance mandates and interoperability requirements shape product specifications more than technical performance alone.
- Medical Imaging:Cardiac SPECT and PET departments require detectors compatible with reduced radiopharmaceutical dosing protocols. Europe's MDR implementation harmonizes performance documentation requirements across member states, with German notified bodies processing the majority of Class IIa and IIb device certifications.
- Nuclear Safety:Reactor instrumentation and spent fuel verification demand detectors meeting stringent calibration traceability standards. India's expanding reactor construction program creates concentrated demand for portal monitors and safeguards infrastructure.
- Security:Border screening and event protection applications prioritize throughput over energy resolution.
- Environmental Monitoring:EPA RadNet interoperability mandates slow adoption of next-generation solid-state detectors despite superior performance characteristics.
Medical imaging leads on scale; nuclear safety leads on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The radiometric detectors industry traces its commercial origins to German nuclear physics laboratories and US national laboratory complexes during the mid-twentieth century. These foundational research ecosystems established the technical standards and manufacturing protocols that persist in today's semiconductor and scintillation detector architectures.
United States
Tertiary hospital networks in California and Texas drive procurement of cadmium-zinc-telluride arrays for cardiac SPECT retrofit programs. The FDA's 510(k) clearance pathway compresses commercialization timelines for radiation-emitting diagnostic devices. Integrated delivery networks in these states now employ in-house medical physics staff to manage unbundled hardware and service contracts independently.
Germany
Helmholtz research centers and industrial metrology firms are modernizing legacy scintillation systems with high-purity germanium detectors for nuclear safeguards applications. The EU MDR implementation harmonizes performance documentation requirements across member states, with German notified bodies processing the majority of Class IIa and IIb device certifications. Bavaria and North Rhine-Westphalia concentrate manufacturing capabilities for cryogenic detector systems.
India
Reactor construction programs and associated safeguards infrastructure create concentrated demand for portal monitors and spent fuel verification systems. The Atomic Energy Regulatory Board oversees radiation monitoring equipment standards for civilian nuclear facilities. Maharashtra and Gujarat host emerging industrial clusters supplying detector components to domestic power generation and border security applications.
Japan
Decommissioning activities at Fukushima Daiichi and ongoing reactor restarts sustain demand for environmental radiation monitoring networks. METI administers calibration protocols and interoperability standards for fixed-site and portable detection equipment. The Kanto region around Tokyo maintains specialized foundry capacity for semiconductor detector substrates.
United Kingdom
Research institutions and defense establishments procure neutron detection arrays for safeguards verification and reactor instrumentation. The Office for Nuclear Regulation enforces compliance with IEC 60580 dose-meter specifications for personnel monitoring equipment. The Oxfordshire and Berkshire corridor hosts specialist engineering firms supporting cryogenic detector development.
Radiometric Detectors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the resolution-portability-cost spectrum, with semiconductor-based architectures commanding superior pricing power in spectroscopic applications while scintillation systems compete on unit economics in high-volume portal monitoring. The vendor base stratifies into three tiers: diversified conglomerates with captive semiconductor fabrication, specialized detector engineering houses with deep cryogenic expertise, and regional assemblers serving cost-sensitive industrial gauging markets. Dominant competitive moves include backward integration into high-purity crystal growth capabilities and geographic expansion of accredited calibration service networks.
Among diversified technology conglomerates, Thermo Fisher Scientific Inc. and AMETEK, Inc. exemplify the scale-driven archetype with broad analytical instrumentation portfolios. Mirion Technologies, Inc. and Berthold Technologies GmbH & Co. KG represent specialized engineering houses with concentrated expertise in radiation detection and measurement systems. PerkinElmer Inc. occupies a position bridging these tiers with dual capabilities in life science instrumentation and analytical detection technologies.
| Leading Market Players |
|---|
| PerkinElmer Inc. |
| Mirion Technologies, Inc. |
| Ludlum Measurements, Inc. |
| Thermo Fisher Scientific Inc. |
| AMETEK, Inc. |
| Gigahertz-Optik, Inc. |
| Berthold Technologies GmbH & Co. KG |
| Gamma Scientific Inc. |
| Sierra Olympic Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Tertiary hospital procurement consortia in California and Texas concentrate buying power for semiconductor detector arrays, locking in contract-based long-term offtake agreements that bundle hardware replacement cycles with calibration service tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates cryogenic germanium systems from room-temperature CZT modules and legacy scintillation detectors. Price differentiation hinges on ISO 4037 calibration certification grade and after-sales service bundling intensity. Cost compression in the scintillation tier is intensifying because Indian and Chinese component assemblers are expanding capacity for sodium iodide crystal production. Chemical and mining operations exhibit highest price sensitivity, while nuclear safeguards agencies demonstrate lowest sensitivity due to specification non-negotiability.
Supply Chain Analysis
IEC 60580 dose-meter qualification requirements and FDA 510(k) certification gating restrict vendor eligibility to established players with accredited calibration facilities. High-purity germanium crystal growth concentrates in Germany and the United States, while CZT semiconductor substrate fabrication anchors in Japan and the United Kingdom. Raw material dependencies include germanium metal feedstock, cadmium-zinc-telluride ingots, and lanthanum bromide scintillation crystals. Single-source vulnerability in specialty semiconductor foundries exposes detector manufacturers to supply disruption. Distribution runs through direct OEM partnerships for medical imaging and defense service contracts for homeland security applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as hospital networks shift procurement specifications toward semiconductor-based detectors with superior energy resolution for reduced radiopharmaceutical dosing protocols.
For Market Incumbents: Acquire cryogenic engineering talent pools in Bavaria and North Rhine-Westphalia to secure manufacturing continuity against workforce aging. Backward integration into high-purity germanium crystal growth capabilities reduces single-source supply risk from specialty semiconductor foundries. Expand accredited calibration service networks into India to capture reactor construction program demand for portal monitors and spent fuel verification systems. For New Entrants and Emerging Players: Mid-tier integrated delivery networks in Texas and California present underserved buyer archetypes lacking in-house medical physics staff to manage unbundled contracts. Field-swappable sensor head designs for chemical process-control applications offer the most penetrable segment given incumbent focus on medical and defense channels. Pursue partnership routes with established calibration facilities to bypass ISO 4037 facility capex barriers. For Investors and Strategic Acquirers: Diversified analytical instrumentation conglomerates are the most active acquirer in this space, seeking radiation detection capabilities to complement existing semiconductor fabrication depth. Long-term viability over a five-to-ten year window rests on CZT penetration into clinical modalities previously dominated by scintillation cameras. Target acquisition archetypes include specialized detector engineering houses with cryogenic expertise and established German notified body relationships. Monitor FDA 510(k) clearance velocity for semiconductor arrays as inflection indicator for medical segment pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Engineering Talent Acquisition | Bavaria's aging workforce concentration threatens germanium detector manufacturing continuity. |
| Backward Integration into Crystal Growth | In-house high-purity germanium production mitigates single-source supply risk from specialty foundries. |
| Calibration Network Geographic Expansion | Accredited service facilities in India capture reactor construction program demand for safeguards infrastructure. |
| CZT Module Clinical Penetration | Cardiac SPECT retrofit programs in tertiary hospital networks displace legacy scintillation camera architectures. |
| Field-Swappable Sensor Head Development | Interchangeable crystal designs reduce process downtime for chemical and mining operations. |
Research Methodology
Direct dialogue with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and nuclear safeguards instrumentation specialists grounded qualitative findings in procurement decision dynamics. Secondary validation drew from FDA 510(k) filings, EPA RadNet technical documentation, IEC 60580 calibration standards, and hospital procurement database records. Bottom-up and top-down triangulation reconciled unit shipment estimates with aggregate market value assessments.
Segment-level projections across product type, end user, technology, and application dimensions fed into consolidated market sizing across the analysis window. CAGRs were derived from regression analysis against nuclear power construction pipelines, medical imaging capital expenditure cycles, and defense appropriation trends. Industry-specific inputs included Helmholtz center modernization timelines, Indian reactor commissioning schedules, and CZT manufacturing yield improvements.
Underlying measurement precision varies by segment; semiconductor detector forecasts carry tighter precision than scintillation systems due to concentrated vendor transparency. Forecasts reflect assumptions regarding FDA clearance velocity, germanium supply continuity, and MDR implementation compliance costs. A model refresh is warranted upon material change in IEC 60580 harmonization progress or cryogenic engineering workforce availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Global Label-Free Detection Market
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Volatile Organic Compound (VOC) Detector Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Global Ultrasonic Air Bubble Detectors Market
Detection and Regulation Devices
Audio Signaling Devices Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market
Detection and Regulation Devices
Negative Temperature Coefficient (NTC) Thermistor Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
Indeflator Devices Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Leak Detection Equipment Market