
 Global Lamps Market | 2026-2036
Global Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lamps Market Outlook
Commercial building retrofits is realigning procurement volumes toward high-efficiency LED systems and connected lighting platforms. Signify leverages its vertical integration across LED chips, drivers, and control software to sustain pricing power in project-based channels. OSRAM GmbH anchors its position through deep specialization in automotive and industrial wavelength-specific applications. Acuity Brands competes by controlling specification-grade distribution across North American commercial infrastructure.
Lamps are electromechanical devices that convert electrical energy into visible light through incandescent filaments, gas discharge, or solid-state semiconductor junctions, with luminous efficacy, color rendering index, and rated lifespan serving as core performance parameters. LED segments now lead value generation as thermal management and phosphor formulations extend operational life beyond legacy alternatives. Smart lighting technology is capturing the fastest expansion as building automation systems demand tunable white, occupancy-responsive, and daylight-harvesting capabilities. Traditional technology occupies residual but stable demand in price-sensitive replacement cycles across developing markets.
The EU Ecodesign Directive and REACH frameworks enforce mercury limits and recyclability standards that reshape product architecture and material selection across European supply chains. China's GB standards and MIIT efficiency labeling programs govern domestic manufacturing while creating export compliance thresholds for foreign suppliers. The US EPA and DOE maintain ENERGY STAR and Lighting Facts programs that influence specification behavior in commercial and institutional procurement. Stakeholders must monitor regulatory phase-out calendars against inventory positions and certification pipelines to avoid stranded product exposures.
Market Dynamics
The global lamps market is experiencing a fundamental restructuring as regulatory phase-out mandates collide with the operational lifespan of installed incandescent and halogen inventories, forcing simultaneous replacement cycles across commercial, residential, and industrial channels.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency standards are accelerating LED retrofit programs across European commercial real estate portfolios, eliminating legacy product availability at the distribution level.
- Smart city infrastructure:Municipal procurement in China is absorbing connected lighting platforms with integrated sensors for traffic management and public safety applications.
- Phosphor formulation advances:Improved thermal stability in ceramic-converted LEDs is extending operational lifespan in high-temperature industrial environments, opening specification-grade opportunities.
Market Restraints
- Rare earth element concentration:Chinese dominance in europium and terbium supply chains creates input cost volatility for phosphor-dependent LED manufacturers.
- Technical limitation in dimming compatibility:Legacy TRIAC dimmers exhibit flicker and dropout with low-load LED retrofits, constraining residential replacement rates.
- Substitution threat from OLED panels:Thin-form organic emitters are capturing architectural accent and display backlighting applications previously served by point-source lamps.
Strategic Opportunities
- Human-centric lighting:Circadian-tunable systems combining melanopic-rich daytime spectra with warm evening outputs are penetrating healthcare and education facilities.
- India's UJALA program:Government-subsidized LED distribution is creating volume foundations for premium product upselling as grid reliability improves.
- Li-Fi convergence:Visible light communication modules integrated into luminaires are enabling data transmission in RF-restricted environments including aircraft cabins and hospitals.
Industry Challenges
- Electromagnetic compatibility certification:Divergent FCC, CE, and GB standards for conducted emissions create multi-jurisdictional testing burdens and timeline delays.
- Integration complexity with Building Management Systems:Proprietary control protocols from incumbent automation vendors fragment interoperability, requiring custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lamps Market |
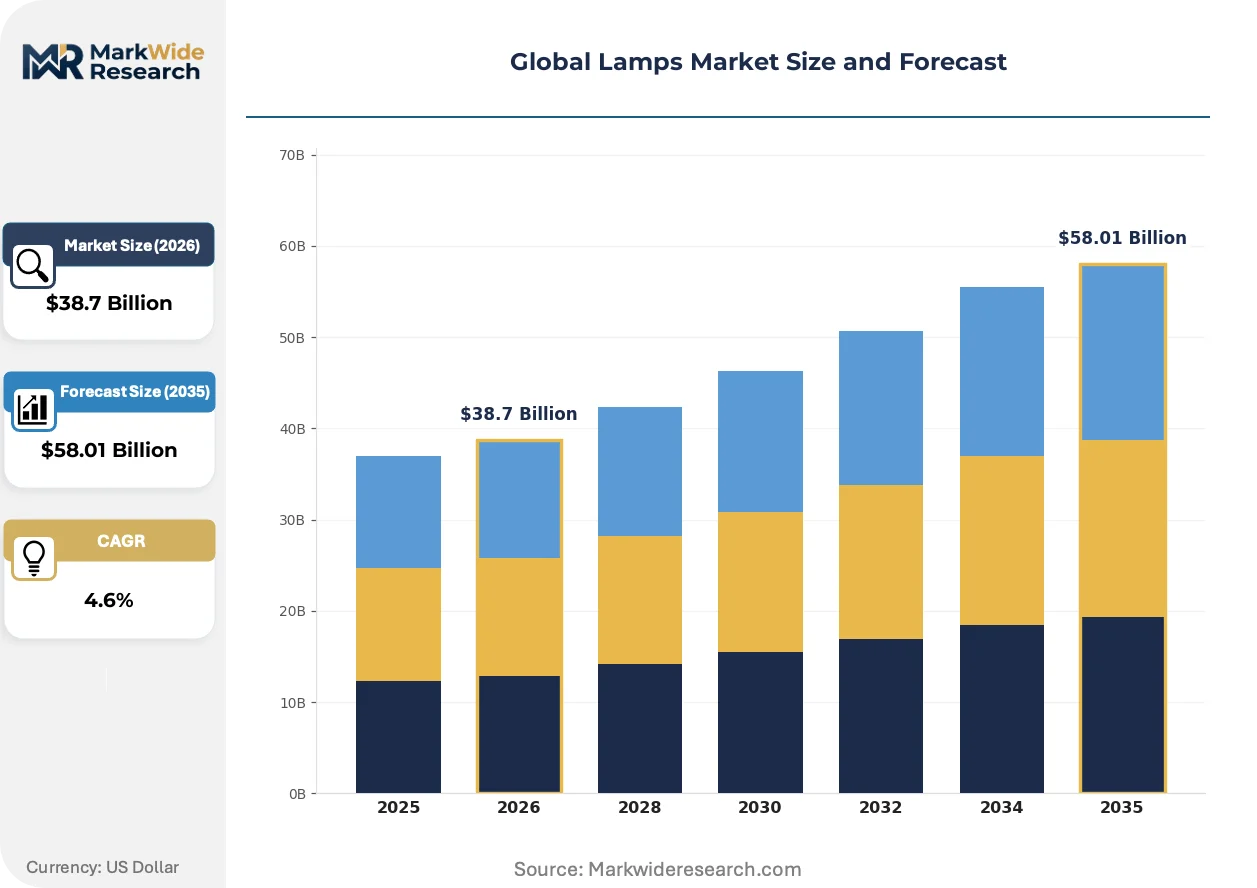
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incandescent, CFL, LED, Halogen Application: Residential, Commercial, Industrial, Outdoor Technology: Smart Lighting, Dimming Control, Solar, Traditional Distribution Channel: Online Retail, Offline Retail, Distributors, Wholesalers |
| Companies Covered | Signify (Philips Lighting), OSRAM GmbH, Acuity Brands, Herman Miller Inc., Inter IKEA B.V., Artemide S.p.A., Lutron Electronics, Zumtobel Group, Flos S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lamps Market Strategic Shifts
Product architecture is converging around semiconductor-based platforms with embedded intelligence, while regulatory frameworks and procurement behaviors co-evolve to prioritize lifecycle performance over first-cost minimization.
Chip-on-board LED arrays with direct thermal bonding to aluminum substrates are absorbing lumen maintenance requirements previously addressed by discrete packaged emitters. High-bay industrial operators in Germany and the Netherlands are specifying these configurations for 100,000-hour maintenance intervals. The technology is absorbing specification-grade market share from mid-power plastic packages by eliminating solder joint failure modes.
REACH restrictions on mercury content are forcing architectural redesign of compact fluorescent lamp manufacturing lines serving residual replacement demand. European recyclers are scaling automated crushing and phosphor separation capacity to handle incoming end-of-life volumes. The regulation most affects price-sensitive Eastern European residential channels, where distributors are clearing remaining inventory ahead of enforcement deadlines.
Building owners are consolidating lighting procurement under facility management outsourcing contracts that bundle installation, energy management, and maintenance into single-source agreements. This model displaces traditional distributor-led specification relationships in North American commercial real estate. The shift is most visible in Class A office properties in New York, Chicago, and Toronto, where landlords seek operational expenditure predictability for net lease structures.
Global Lamps Market Segmentation
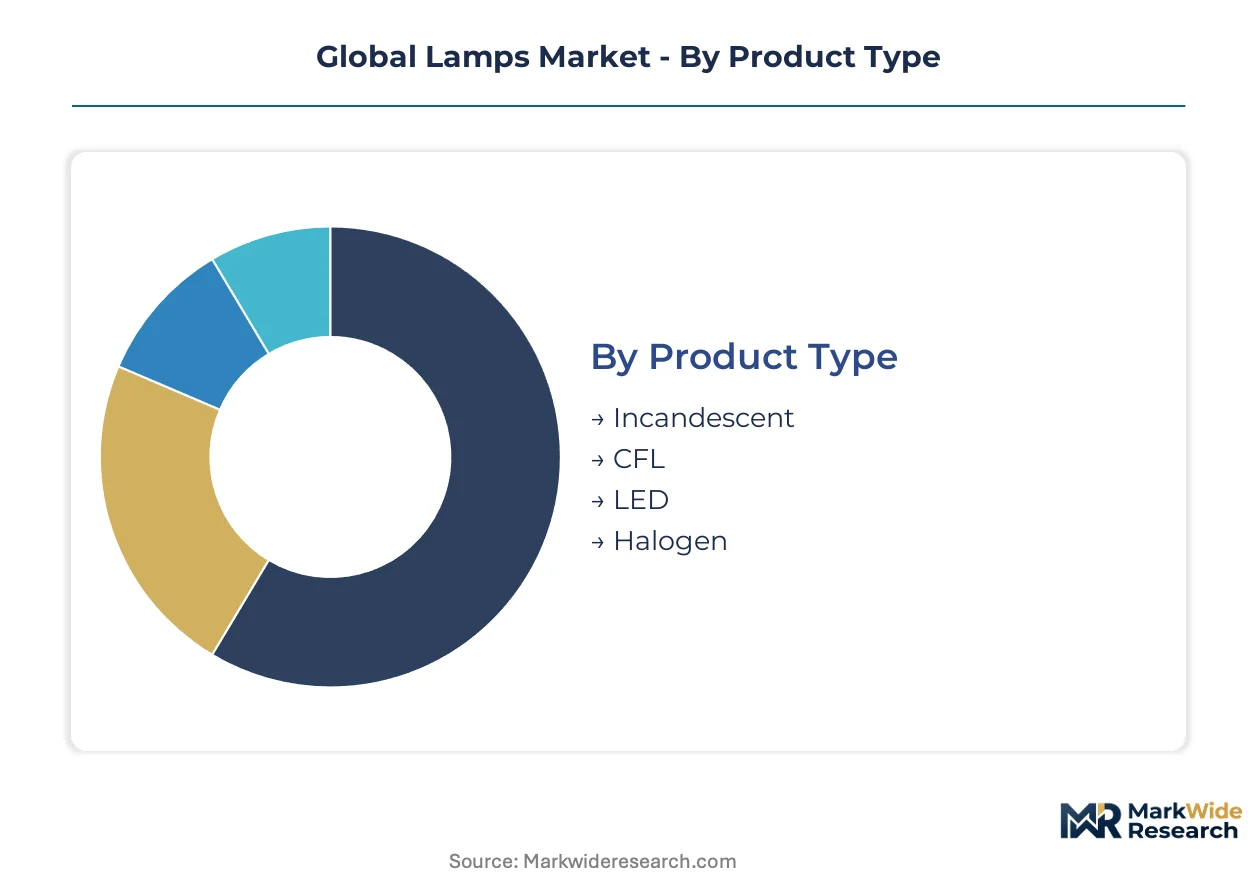
Lamp segmentation reveals divergent value capture across efficiency tiers and control architectures. Procurement patterns split sharply between replacement cycles in legacy sockets and specification-driven new construction. Understanding these fault lines exposes where margin concentrates versus where volume merely sustains factory utilization.
Product Type:
LED volumes dominate shipment tonnage while premium pricing persists in specialized halogen applications where color fidelity commands specification loyalty.
- LED:Solid-state semiconductor junctions with ceramic-converted phosphor architectures now deliver lumen maintenance exceeding 100,000 hours in industrial specifications. Demand concentrates in Chinese smart city deployments where municipal procurement bundles connected infrastructure with energy performance contracting.
- Halogen:Tungsten-halogen regenerative cycle lamps retain specification-grade footholds in theatrical, medical, and premium residential accent lighting where CRI 100 and instant dimming response outweigh efficiency penalties. European Ecodesign phase-out calendars are compressing remaining inventory windows.
- CFL:Mercury-vapor fluorescent tubes with integrated ballasts face REACH-mandated recycling infrastructure requirements across European supply chains.
- Incandescent:Residual demand persists in price-sensitive replacement cycles across developing markets with limited grid reliability.
Mature deployment sits with incandescent and CFL in residential replacement channels. Newer deployment is concentrated in LED across commercial retrofit and connected infrastructure programs.
Application:
Commercial building automation is absorbing the fastest-expanding product configurations, while residential channels fragment across price tiers and retrofit compatibility constraints.
- Commercial:Office, retail, and hospitality specifications prioritize tunable white systems with daylight harvesting and occupancy-responsive controls. Class A properties in New York, Chicago, and Toronto are consolidating procurement under facility management outsourcing contracts that bundle installation with energy performance guarantees.
- Industrial:High-bay manufacturing and warehousing specifications demand chip-on-board arrays with direct thermal bonding to aluminum substrates, eliminating solder joint failure modes in 24/7 operational environments.
- Residential:Retrofit compatibility with legacy TRIAC dimmers constrains LED adoption rates where flicker and dropout persist with low-load installations.
- Outdoor:Municipal street and area lighting in China integrates traffic management sensors and public safety monitoring into connected luminaire platforms.
Specification-grade deployment concentrates in commercial and industrial channels. Volume scaling is accelerating fastest in outdoor infrastructure with integrated sensor convergence.
Technology:
Control intelligence is bifurcating the market between connected platforms with embedded software and commodity replacement lamps where cost minimization dominates.
- Smart Lighting:Networked luminaires with embedded sensors and programmable spectral output are penetrating healthcare and education facilities seeking circadian-tunable melanopic-rich daytime spectra. Building Management System integration complexity from proprietary protocols creates custom gateway development burdens.
- Dimming Control:Phase-cut and 0-10V architectures face interoperability constraints across legacy and LED-native fixture portfolios.
- Solar:Off-grid and grid-hybrid photovoltaic-integrated luminaires serve rural electrification programs in India and sub-Saharan Africa.
- Traditional:Non-connected, non-dimmable commodity lamps retain volume in price-sensitive replacement cycles and emergency backup inventories.
Established deployment remains concentrated in traditional and basic dimming configurations. Connected platform deployment is expanding most quickly in institutional and healthcare specifications.
Distribution Channel:
Channel power is shifting from distributor-led specification relationships toward direct procurement by facility management consolidators and e-commerce platforms.
- Distributors:Specification-grade commercial channels in North America retain influence through lighting design services and project logistics coordination.
- Online Retail:Amazon and Alibaba platforms are absorbing residential replacement volume with private-label LED offerings and compatibility-filtered search tools.
- Offline Retail:Home improvement chains and electrical wholesalers serve emergency replacement demand and contractor pickup traffic.
- Wholesalers:Volume procurement for new construction and multi-site retrofit programs flows through electrical supply houses with project financing capabilities.
Legacy deployment sits with offline retail and traditional wholesale channels. Channel migration is concentrating fastest in online retail for residential segments and distributor-direct models for commercial outsourcing contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of lamp components while Western Europe and North America absorb premium-tier finished goods. This production-consumption divide shapes trade flows and regulatory compliance burdens across supply chains.
China
Domestic manufacturing scale and government-backed smart city programs are reshaping procurement patterns. MIIT efficiency labeling programs govern domestic production while creating export compliance thresholds for foreign suppliers. Municipal procurement in Shenzhen and Shanghai absorbs connected lighting platforms with integrated sensors for traffic management.
Germany
High-bay industrial operators specify chip-on-board LED arrays for 100,000-hour maintenance intervals. The EU Ecodesign Directive and REACH frameworks enforce mercury limits and recyclability standards that reshape product architecture. Manufacturing clusters in Bavaria and North Rhine-Westphalia serve specification-grade commercial channels across continental Europe.
United States
Class A office properties in New York, Chicago, and Toronto consolidate procurement under facility management outsourcing contracts. The EPA and DOE maintain ENERGY STAR and Lighting Facts programs that influence specification behavior. Distribution power concentrates in specification-grade channels with lighting design services and project logistics coordination.
India
Government-subsidized LED distribution through the UJALA program creates volume foundations for premium product upselling. BIS standards and CEA regulations govern grid-interconnected lighting installations. Industrial corridors in Gujarat and Maharashtra are absorbing connected infrastructure as grid reliability improves.
Japan
Healthcare and education facilities seek circadian-tunable melanopic-rich daytime spectra. METI and JIS standards govern spectral quality and flicker metrics in institutional applications. Manufacturing concentration in the Kanto region around Tokyo supplies precision phosphor formulations for wavelength-specific applications.
Global Lamps Market Competitive Environment
Top-tier vendors anchor premium specification channels, while mid-scale fabricators compete on retrofit compatibility and price-sensitive replacement cycles. The vendor base stratifies across semiconductor-integrated platforms, wavelength-specialized industrial suppliers, and commodity residential producers. Strategic archetypes include vertically integrated lighting conglomerates, component-specialized technology licensors, and distributor-captive regional brands. Competitive moves concentrate on M&A for control software capabilities and capacity expansion in ceramic-converted LED arrays.
Among Netherlands-based and German lighting conglomerates, Signify (Philips Lighting) and OSRAM GmbH exemplify divergent strategic positioning within the premium tier. Signify occupies a position emphasizing connected lighting platforms and building automation integration, while OSRAM anchors wavelength-specific industrial and automotive applications. North American specification-grade distribution is represented by Acuity Brands, which sits within the distributor-captive archetype controlling commercial infrastructure channels.
| Leading Market Players |
|---|
| Signify (Philips Lighting) |
| OSRAM GmbH |
| Acuity Brands |
| Herman Miller Inc. |
| Inter IKEA B.V. |
| Artemide S.p.A. |
| Lutron Electronics |
| Zumtobel Group |
| Flos S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Municipal procurement programs in China and facility management consolidators in North America command project-based pricing with energy performance guarantees, compressing margins for specification-grade vendors while rewarding volume-scaled ceramic-converted LED producers.
Pricing Analysis
Cost-down pressure on commodity LED retrofits accelerates because e-commerce platforms and private-label offerings erode brand premiums in residential replacement channels. Three-tier pricing structure across premium specification-grade, standard commercial, and economy residential levels separates vendors by certification tier and thermal management performance. Price differentiation traces to ENERGY STAR qualification and MIIT efficiency labeling as threshold requirements for commercial procurement eligibility. Residential retrofit buyers exhibit highest price sensitivity where TRIAC compatibility failures drive return rates, while healthcare and industrial specification buyers prioritize lumen maintenance warranties over first-cost minimization.
Supply Chain Analysis
Rare earth phosphor supply rests on Chinese separation and refining capacity for europium and terbium, tethering LED manufacturers to volatile input costs. Ceramic substrate fabrication concentrates in Japan and Germany, while aluminum heat sink extrusion and final luminaire assembly cluster in China and Mexico. Single-source vulnerability in rare earth processing creates margin exposure when export quotas tighten. Distribution runs through electrical supply houses with project financing capabilities for commercial retrofits, direct OEM relationships for automotive wavelength-specific applications, and Amazon-Alibaba platforms for residential replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Ecodesign Directive phase-out calendars and REACH mercury restrictions erect compliance barriers that favor incumbents with certified product pipelines and stranded-asset avoidance capabilities.
For Market Incumbents: Anchor specification-grade positioning through captive control over ceramic-converted LED array production and embedded sensor integration software. Deepen backward integration into phosphor formulation to offset rare earth cost volatility. Defend against OLED panel substitution in architectural accent applications by emphasizing tunable white and circadian programmability in healthcare specifications. For New Entrants and Emerging Players: The mid-market gap between premium connected platforms and economy retrofit lamps offers white-space entry through TRIAC-compatible LED engines with flicker-free dimming performance. Target India's UJALA program upgrade cycle as grid reliability improves and commercial facilities seek human-centric lighting. Pursue Li-Fi module integration as a differentiated go-to-market angle for RF-restricted environments including aircraft and hospital deployments. For Investors and Strategic Acquirers: The window for entry favors component-specialized technology licensors with wavelength-specific IP and control protocol software assets. Long-term viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Monitor Ecodesign enforcement calendar acceleration and rare earth export policy shifts as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Converted LED Capacity Expansion | Captures specification-grade industrial demand for 100,000-hour maintenance intervals in German and Dutch high-bay operations. |
| Control Software Acquisition | Resolves Building Management System interoperability fragmentation through proprietary gateway development capabilities. |
| Phosphor Formulation Backward Integration | Insulates margin from Chinese rare earth supply volatility in europium and terbium dependency. |
| Li-Fi Module Development Partnership | Opens data transmission applications in RF-restricted aircraft cabins and hospital environments. |
| Facility Management Outsourcing Alliance | Consolidates procurement influence in Class A office properties across New York, Chicago, and Toronto. |
Study Parameters
Independent corroboration across lighting design consultants, electrical contractor procurement leads, municipal smart city program directors, and facility management outsourcing executives underwrites the qualitative findings. Primary fieldwork combined structured interviews with specification-grade distributors and OEM procurement teams with secondary validation through ENERGY STAR certification databases, MIIT efficiency labeling registries, EU Ecodesign implementing measure texts, and customs trade flow records. Bottom-up shipment modeling and top-down energy consumption projections triangulate volume estimates across product type, application, and technology segments.
Comparable-period anchoring to historical LED penetration curves and regulatory phase-out implementation timelines structured the projection horizon. Segmentation modeling spanned product architecture, control intelligence tier, end-use vertical, and regional regulatory cluster dimensions. CAGRs derived from installed base replacement cycle analysis and new construction absorption rates incorporate phosphor efficiency improvement curves and smart city infrastructure deployment schedules as industry-specific inputs.
Underlying measurement precision varies by segment; connected lighting and specification-grade industrial applications carry tighter precision than commodity residential replacement channels. Forecasts reflect documented assumptions regarding regulatory enforcement timing, rare earth supply stability, and TRIAC dimmer compatibility resolution rates. Regulatory acceleration, supply disruption, and technology substitution thresholds warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Lighting Product Market
Lighting
Smart Street Lighting Systems Market
Lighting
Bulb Market
Lighting
Photocell Market
Lighting
Battery Operated Lights Market
Lighting
Global Flame Proof Lighting Market
Lighting
Europe Decorative Lighting Market
Lighting
Global Work Lights Market
Lighting
Graphene Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
North America Smart Lighting Market
Lighting
North America Street Lighting Market
Lighting
Architectural Lighting Market
Lighting
Bacteriological Light Market
Lighting
Industrial Lighting Cybersecurity Market
Lighting
Programmable Stage Lighting Market