
 Plasma Lighting Market | 2026-2036
Plasma Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Lighting Market Outlook
REACH compliance is pivoting the cost-of-entry calculus for plasma lamp manufacturers selling into European industrial channels. Ceravision Limited leverages its electrodeless lamp architecture to sustain technical differentiation against conventional HID alternatives. Ushio Inc. anchors its position through captive ceramic metal-halide supply chains and precision manufacturing scale in Japanese production facilities. Hive Lighting Inc. competes in North American entertainment verticals where color-rendering index requirements exceed standard fluorescent capabilities.
Plasma lighting generates illumination by exciting a gas-filled bulb through radio-frequency or microwave energy, producing a high-intensity arc without electrodes and achieving luminous efficacies above 90 lumens per watt with correlated color temperatures spanning 5600K to 10000K. The technology serves applications requiring broad-spectrum output, extended operational lifespan, and minimal lumen depreciation across industrial processing, large-area commercial illumination, and broadcast-grade entertainment environments. The HID product category retains structural dominance in heavy-industrial deployments where initial capital constraints outweigh lifecycle efficiency calculations, while smart lighting integration represents the fastest-expanding segment as facilities managers demand networked controls and predictive maintenance protocols. Entertainment end users concentrate margin pools through specialized spectral-tuning requirements and low-volume, high-specification procurement patterns.
The EU F-Gas Regulation and Ecodesign Directive constrain mercury-content thresholds and minimum efficiency standards for lamps placed on European markets, directly influencing plasma lighting product roadmaps and qualification testing burdens. The US EPA oversees hazardous waste classifications for spent lamps under Universal Waste rules, while China's GB standards through SAMR establish electromagnetic compatibility and safety testing protocols for domestically manufactured and imported plasma systems. Stakeholders must monitor evolving efficiency benchmarks and material-restriction schedules to align R&D allocation with compliance timelines across their prioritized geographic markets.
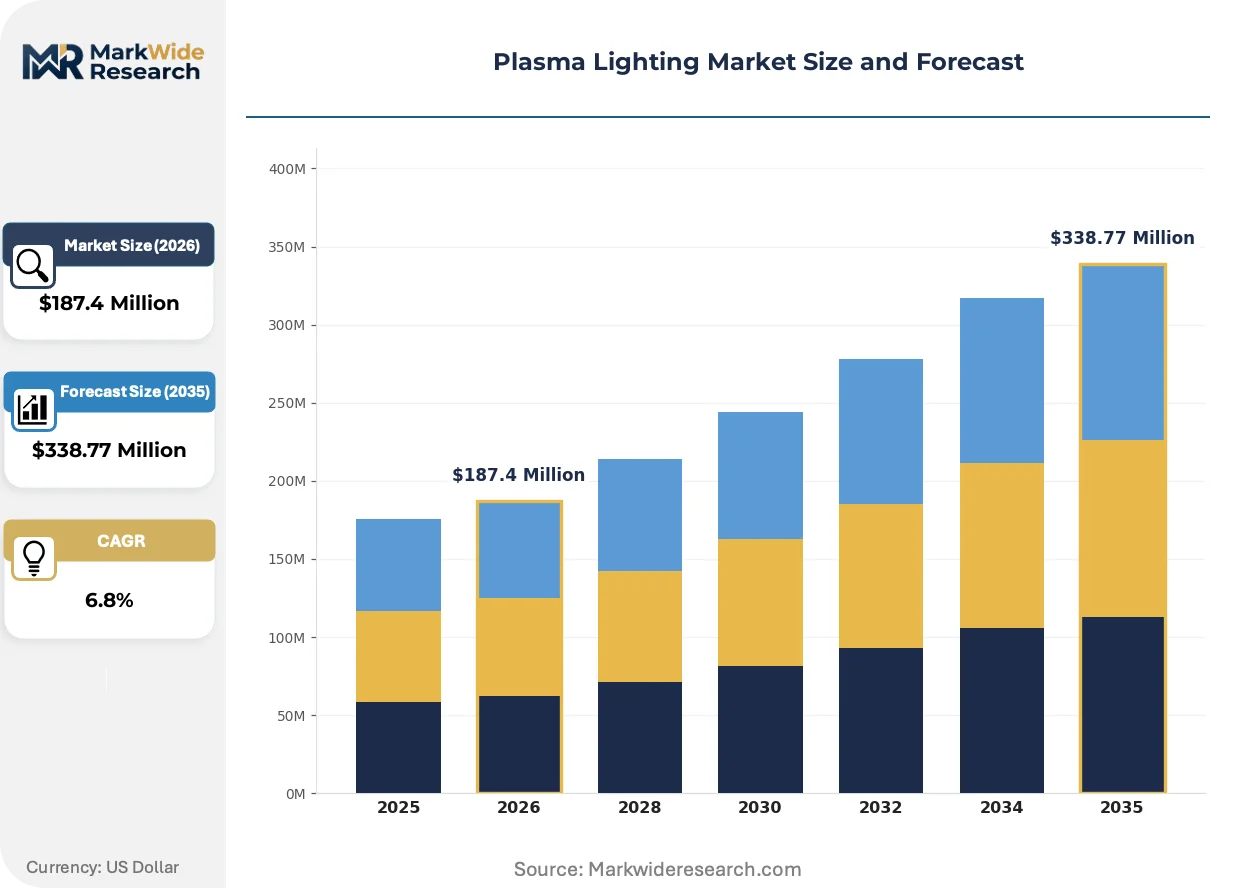
Market Dynamics
The EU Green Deal efficiency mandates are compressing replacement cycles for legacy high-intensity discharge installations across European industrial facilities, forcing operators to evaluate electrodeless plasma architectures against ceramic metal-halide retrofits.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency thresholds for industrial luminaires are disqualifying conventional mercury-vapor systems from new procurement in German automotive plants and Dutch greenhouse complexes.
- Precision horticulture:Japanese vertical farming operators are specifying plasma sources for tunable-spectrum crop acceleration, replacing fixed-spectrum LED arrays in high-value cultivar propagation.
- Smart-city retrofits:Municipal procurement frameworks in China are bundling networked plasma floodlighting with IoT-enabled maintenance protocols for highway and tunnel infrastructure.
Market Restraints
- RF generator cost structure:Magnetron and solid-state microwave power supplies constitute 35-40% of bill-of-materials, constraining price competitiveness against commodity LED drivers.
- Mercury-content thresholds:REACH authorization requirements for sulfur plasma chemistries are extending qualification timelines by 18-24 months for European market entry.
- Technical limitation:Electrodeless bulb geometries cannot achieve the form-factor miniaturization required for residential downlighting, capping addressable market expansion.
Strategic Opportunities
- Underpenetrated geography:Saudi Arabia's giga-project construction pipeline lacks qualified plasma lighting installers, creating first-mover positioning for technical service partnerships.
- Technology convergence:Integration of plasma sources with LiDAR-based adaptive dimming is converging with autonomous vehicle testing facility specifications in Michigan and Stuttgart.
- Regulatory tailwind:China's dual carbon goals are accelerating SAMR efficiency labeling requirements that favor high-efficacy plasma over legacy HID in state-owned enterprise procurement.
Industry Challenges
- RF engineering talent scarcity:Microwave plasma design expertise concentrates in legacy semiconductor and radar equipment sectors, complicating recruitment for lighting OEMs.
- Certification timeline compression:Parallel GB standard testing for electromagnetic compatibility and IEC photobiological safety is extending product launch schedules for Chinese market entry.
- Legacy system integration friction:Existing DALI and 0-10V control infrastructures in European industrial facilities require protocol bridging hardware, complicating retrofit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Lighting Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, HID, Fluorescent, Other Application: Industrial, Commercial, Residential, Automotive Technology: Direct Lighting, Indirect Lighting, Smart Lighting, Conventional Lighting End User: Retail, Manufacturing, Hospitality, Entertainment |
| Companies Covered | Gavita International B.V., Ushio Inc., Ceravision Limited, Hive Lighting Inc., Signify Holding, ams-OSRAM AG, KA Shui International Holdings, LG Electronics, Pure Plasma Lighting Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Lighting Market Strategic Shifts
Plasma lighting technology is undergoing architectural transformation as solid-state RF generation and spectral-tuning capabilities expand addressable applications beyond traditional high-bay industrial deployment.
Sulfur-based plasma chemistry is converging with machine-vision inspection requirements in semiconductor fabrication cleanrooms, where broad-spectrum output eliminates multi-source shadowing. Taiwan-based foundry operators are specifying these systems for wafer defect detection lines. The technology is converging with metrology-grade illumination standards previously served by filtered xenon arc lamps.
REACH authorization schedules for mercury-containing lamps are forcing reformulation roadmaps across European-manufactured plasma product lines. Industrial end-users in Germany and France are front-loading procurement of compliant inventory ahead of 2027 restriction deadlines. Horticultural operators are accelerating qualification of sulfur-based alternatives to maintain EU market access.
Specification authority is migrating from facilities managers to sustainability compliance officers in Fortune 500 industrial portfolios. Third-party energy service companies are capturing procurement decisions through performance-contracting structures that internalize lifecycle cost calculations. This shift is most pronounced in California and New York state manufacturing installations subject to aggressive decarbonization mandates.
Plasma Lighting Market Segmentation
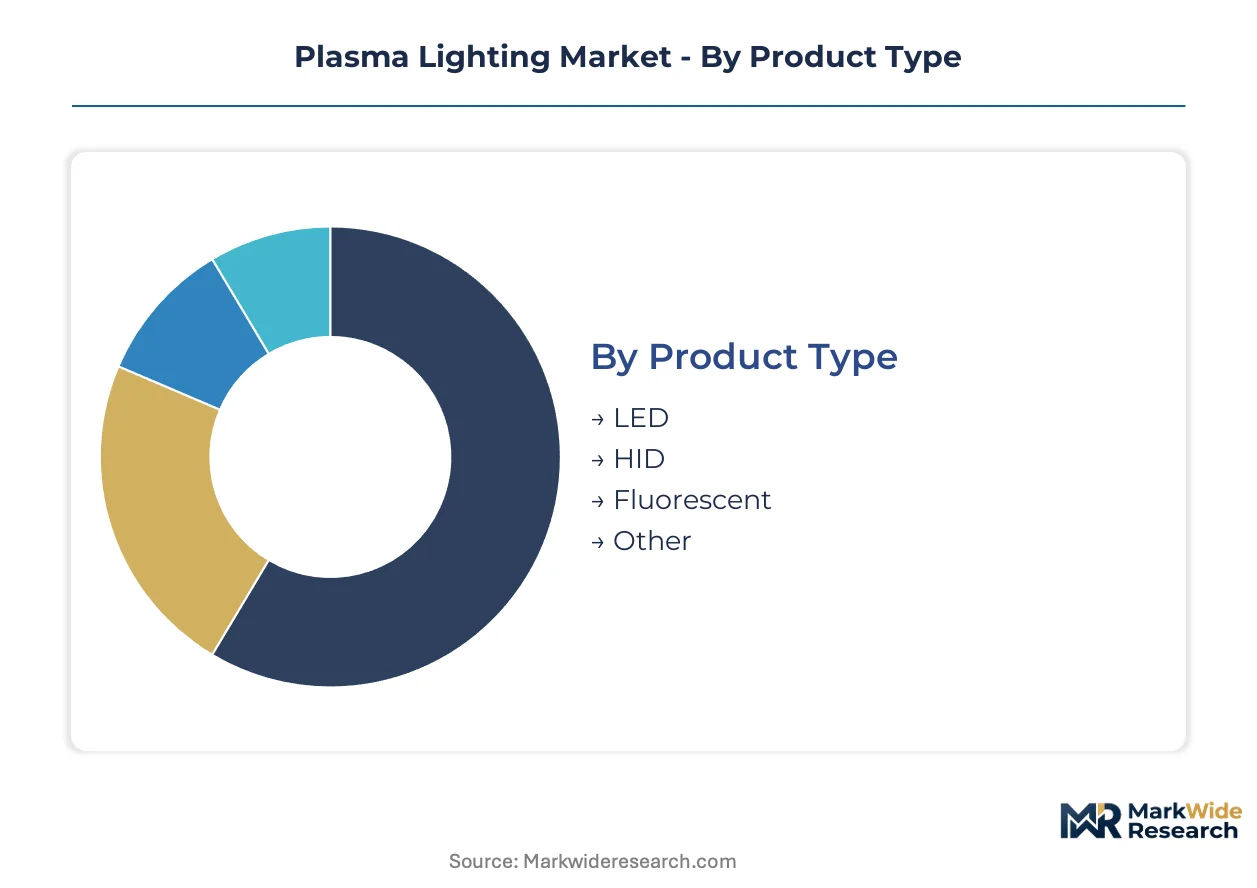
Plasma lighting procurement decisions bifurcate across technical specifications and regulatory compliance requirements. Segment boundaries shift as solid-state RF generation displaces magnetron architectures and sustainability officers override traditional facilities management authority.
Product Type:
Supply concentration for RF power electronics and bulb chemistries concentrates manufacturing leverage among semiconductor foundries and specialty gas suppliers.
- LED:Solid-state electroluminescence dominates residential retrofits and commercial downlighting where form-factor flexibility outweighs spectral breadth. Municipal procurement in Chinese smart-city frameworks favors LED for networked streetlight infrastructure despite inferior color-rendering metrics.
- HID:Ceramic metal-halide and mercury-vapor systems retain installed base in heavy-industrial facilities across Germany and Poland where capital replacement cycles extend. EU Ecodesign Directive efficiency thresholds are disqualifying conventional mercury-vapor from new procurement in Dutch greenhouse and German automotive plant installations.
- Fluorescent:Linear tube configurations persist in legacy commercial retrofit markets.
- Other:Sulfur-based electrodeless plasma and induction systems serve niche metrology and horticultural applications.
HID absorbs the bulk of installed capacity; smart lighting integration is expanding most quickly.
Application:
Cost tier differentiation separates specification-grade installations from commodity replacement markets.
- Industrial:High-bay warehousing and manufacturing floors demand 90+ lumens per watt efficacy with minimal lumen depreciation across operational lifespans. German automotive plants and Japanese semiconductor foundries specify plasma sources for machine-vision inspection lines requiring broad-spectrum shadow elimination.
- Commercial:Retail and office environments balance initial fixture cost against lifecycle maintenance burdens. French hypermarket operators are front-loading procurement of REACH-compliant inventory ahead of mercury restriction deadlines.
- Residential:Form-factor miniaturization constraints exclude electrodeless plasma from mainstream downlighting.
- Automotive:LiDAR-based adaptive dimming convergence creates specification opportunities in autonomous vehicle testing facilities across Michigan and Stuttgart.
Industrial deployments command premium pricing; commercial retrofits are climbing the fastest.
Technology:
Customer type migration from facilities managers to sustainability compliance officers reshapes procurement authority structures.
- Direct Lighting:Point-source illumination serves high-ceiling industrial and sports stadium applications. German sports venue operators are expanding procurement of plasma-based floodlighting to meet EU Green Deal efficiency mandates.
- Indirect Lighting:Coves and luminous ceilings dominate commercial office specifications.
- Smart Lighting:Networked controls with predictive maintenance protocols represent the steepest expansion trajectory as Chinese municipal frameworks bundle IoT-enabled plasma floodlighting for highway infrastructure.
- Conventional Lighting:Standalone fixtures without connectivity retain residual replacement demand.
Conventional lighting retains legacy installed base; smart lighting integration gains share fastest.
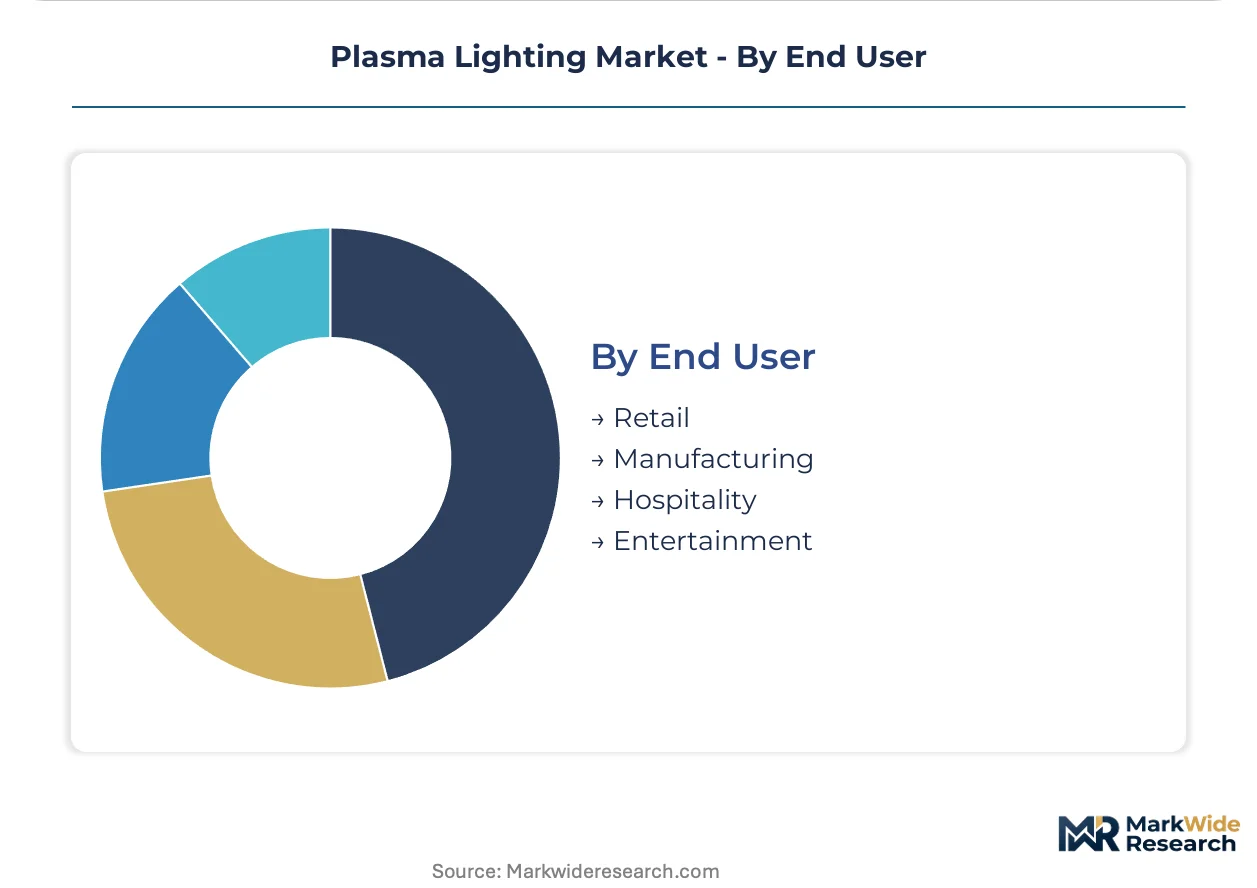
End User:
Geography-driven demand concentration centers on East Asian precision manufacturing and European regulatory compliance markets.
- Retail:Color-rendering index requirements above 90 drive specification authority in luxury goods presentation. North American big-box operators evaluate plasma against ceramic metal-halide for high-bay merchandise illumination.
- Manufacturing:Cleanroom and metrology applications require spectral stability beyond LED capabilities. Taiwan-based semiconductor foundry operators specify sulfur plasma for wafer defect detection lines.
- Hospitality:Tunable spectrum and dimming responsiveness serve restaurant and hotel ambient lighting.
- Entertainment:Broadcast and theatrical applications demand 5600K-10000K correlated color temperatures with precise dimming curves. North American production studios specify plasma for color-critical cinematography where LED arrays exhibit spectral gaps.
Manufacturing absorbs dominant procurement volume; entertainment verticals sustain premium margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial parks and Dutch greenhouse clusters concentrate plasma lighting procurement under EU Ecodesign Directive deadlines. Chinese smart-city infrastructure and Japanese precision manufacturing anchor East Asian demand concentration.
Germany
Automotive plants in Stuttgart and Wolfsburg specify electrodeless plasma for machine-vision inspection lines requiring broad-spectrum shadow elimination. The EU Green Deal efficiency mandates compress replacement cycles for legacy mercury-vapor installations in Bavarian and North Rhine-Westphalian industrial zones. Sports venue operators in Munich and Dortmund expand plasma-based floodlighting procurement to meet 2030 decarbonization targets.
China
Municipal procurement frameworks bundle networked plasma floodlighting with IoT-enabled maintenance protocols for highway and tunnel infrastructure across the Yangtze River Delta. SAMR efficiency labeling requirements under dual carbon goals favor high-efficacy plasma over legacy HID in state-owned enterprise procurement. Semiconductor foundry operators in Shanghai and Shenzhen specify sulfur plasma chemistries for wafer defect detection lines.
Japan
Vertical farming operators in Chiba and Osaka prefectures specify plasma sources for tunable-spectrum crop acceleration, replacing fixed-spectrum LED arrays in high-value cultivar propagation. METI industrial efficiency standards accelerate ceramic metal-halide displacement in Kansai manufacturing corridors. Precision horticulture installations concentrate demand through municipal smart-city retrofits in Greater Tokyo.
United States
Broadcast production studios in Los Angeles and New York specify plasma for color-critical cinematography where LED arrays exhibit spectral gaps. EPA Universal Waste rules govern hazardous waste classifications for spent lamps in Michigan autonomous vehicle testing facilities. LiDAR-based adaptive dimming convergence creates specification opportunities in Detroit-area automotive proving grounds.
Netherlands
Greenhouse complexes in Westland and Aalsmeer front-load procurement of REACH-compliant plasma inventory ahead of 2027 mercury restriction deadlines. The EU F-Gas Regulation constrains sulfur plasma qualification timelines for Dutch horticultural exporters. Agricultural technology clusters concentrate specification authority for tunable-spectrum crop acceleration in high-value flower propagation.
Plasma Lighting Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across differentiated application tiers. The vendor base spans lighting incumbents with captive ceramic supply chains, electrodeless technology specialists, and entertainment-vertical pure-plays. Three archetypes dominate: diversified electronics conglomerates leveraging manufacturing scale, RF engineering specialists with magnetron or solid-state power electronics expertise, and horticultural/entertainment vertical specialists. Competitive moves concentrate on REACH-compliant reformulation roadmaps and smart-city partnership frameworks.
Within the electrodeless technology tier, Ceravision Limited and Pure Plasma Lighting Inc. occupy positions defined by RF generator architectures and bulb chemistry specialization. Ushio Inc. anchors the diversified industrial lighting segment through Japanese manufacturing presence. Hive Lighting Inc. exemplifies the entertainment-vertical specialist archetype, representing North American production studio specification channels where color-rendering index requirements exceed standard capabilities.
| Leading Market Players |
|---|
| Gavita International B.V. |
| Ushio Inc. |
| Ceravision Limited |
| Hive Lighting Inc. |
| Signify Holding |
| ams-OSRAM AG |
| KA Shui International Holdings |
| LG Electronics |
| Pure Plasma Lighting Inc. |
| Others |
Value Chain & Pricing Dynamics
Solid-state RF generator adoption is compressing magnetron-dependent cost structures while concentrating procurement leverage among semiconductor foundries in Japan and Taiwan. This transition simultaneously elevates upfront capital requirements for plasma lamp OEMs and rewards early movers with captive power electronics supply.
Pricing Analysis
Lead-time premiums distinguish REACH-compliant sulfur plasma inventory from spot-market mercury-based alternatives in European industrial channels. Three-tier pricing structure across premium specification-grade, standard commercial, and economy retrofit tiers separates machine-vision installations from commodity warehouse replacements. Cost compression in solid-state RF tiers is intensifying because semiconductor foundry capacity allocation favors automotive lidar over lighting applications. Municipal procurement offices in China exhibit lowest price sensitivity; independent horticultural operators in the Netherlands face acute margin pressure.
Supply Chain Analysis
Reverse-logistics flows for spent mercury-containing lamps are constraining distributor working capital under EPA Universal Waste rules and EU WEEE directives. Magnetron and solid-state RF power electronics concentrate in Japan, South Korea, and Taiwan; specialty sulfur and argon gas chemistries source from industrial gas majors in Germany and the United States. Single-source vulnerability in ceramic bulb substrate supply creates qualification bottlenecks for new market entrants. Distribution runs through technical service partnerships for industrial installations and direct OEM relationships for municipal smart-city frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plasma lighting market reads as a cost-of-compliance story where REACH authorization schedules for mercury chemistries erect barrier-to-entry moats for reformulation-ready incumbents.
For Market Incumbents: Anchor defensive positioning through backward integration into ceramic bulb substrate production and captive RF generator assembly in Japanese manufacturing corridors. Threat substitution from tunable-spectrum LED arrays in horticultural verticals demands accelerated sulfur plasma qualification timelines. Certification investment in parallel GB standard and IEC photobiological safety testing preserves Chinese market access against extending launch schedules.
For New Entrants and Emerging Players: Technical service partnerships in Saudi Arabia's giga-project construction pipeline represent the most penetrable white-space target given absent qualified installer networks. Autonomous vehicle testing facilities in Michigan and Stuttgart offer specification-grade entry points through LiDAR-adaptive dimming integration. Go-to-market execution should emphasize RF engineering talent recruitment from legacy radar equipment sectors rather than conventional lighting channels.
For Investors and Strategic Acquirers: Re-rating potential sits with electrodeless technology specialists given solid-state RF generator cost curves and REACH-compliant reformulation roadmaps. Long-term viability over the next decade hinges on smart-city partnership framework capture in Chinese municipal procurement. The signal to watch is SAMR efficiency labeling acceleration under dual carbon goals favoring plasma over legacy HID in state-owned enterprise procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation | Sulfur plasma chemistry investment preserves EU market access against 2027 mercury restriction deadlines. |
| Smart-City Partnership Framework | IoT-enabled maintenance protocol bundling captures Chinese municipal highway and tunnel infrastructure procurement. |
| RF Engineering Talent Acquisition | Recruitment from semiconductor and radar equipment sectors addresses microwave plasma design expertise scarcity. |
| Technical Service Partnership | Installer network development in Saudi Arabia giga-projects creates first-mover positioning in underpenetrated geography. |
| Solid-State RF Generator Scale-Up | Magnetron displacement reduces bill-of-materials concentration and improves price competitiveness against LED alternatives. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with RF engineering directors, municipal procurement officers, horticultural facility managers, and semiconductor foundry lighting specification leads combined with secondary validation from ECHA REACH authorization databases, SAMR GB standard publications, and EPA Universal Waste guidance documents. Bottom-up installation volume estimates and top-down market sizing triangulated across product type and application segmentations.
Shipment volume reconciliation against RF power electronics import data and sulfur gas consumption patterns validated forward projections across the analysis window. Segmentation dimensions modeled include product architecture, end-use application, technology integration level, and geographic regulatory cluster. CAGRs derived from regression analysis of historical adoption curves and policy-driven replacement cycle compression. Forecast inputs incorporated EU Ecodesign Directive efficiency threshold schedules and METI industrial efficiency standard acceleration timelines.
Revisions become necessary when REACH authorization timelines shift, solid-state RF generator cost curves steepen, or Chinese dual carbon policy implementation accelerates beyond baseline assumptions. Practitioners should monitor SAMR efficiency labeling announcements and sulfur plasma chemistry qualification progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Human Centric Lighting Market
Lighting
Art and Museum Lighting Market
Lighting
Solar Spotlights Market
Lighting
Programmable Stage Lighting Market
Lighting
Architectural Lighting Market
Lighting
LED Eye Protection Desk Lamp Market
Lighting
Europe Lighting Control Systems Market
Lighting
Connected Lighting Platform Market
Lighting
Photography Light Box Market
Lighting
UV Lamps Market
Lighting
Portable Lamps Market
Lighting
Explosion Proof Lighting Market
Lighting
Xenon Lights Market
Lighting
Xenon Headlights Market
Lighting
Cleanroom Lighting Market
Lighting
UAE Smart Lighting Market