
 North America Outdoor Lighting Market | 2026-2036
North America Outdoor Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Outdoor Lighting Market Insights
Market Context
Aftermarket service revenue is reshaping margin capture across the North America outdoor lighting value chain as municipalities extend asset life cycles through retrofit programs and predictive maintenance contracts. Signify Holding leverages its Interact connected lighting platform to secure recurring software revenue streams alongside hardware sales. Acuity Brands Lighting sustains competitive positioning through deep vertical integration into LED driver and control component manufacturing. Eaton Intelligent Lighting anchors its presence in utility-scale roadway projects through specification-grade engineering and channel partnerships with electrical distributors.
Technical Definition and Segment Structure
North America outdoor lighting encompasses luminaires, poles, control systems, and ancillary electrical components engineered for exterior illumination across public infrastructure, commercial properties, and residential environments, typically rated for IP65 or higher ingress protection and operating temperatures spanning -40°C to 50°C. LED technology dominates new installations while solar-integrated systems represent the fastest-expanding sub-category as battery chemistry improvements and photovoltaic efficiency gains reduce total cost of ownership in off-grid and remote applications. Street and roadway applications command the largest volume share, though commercial segment margins concentrate in specification-grade architectural and facade lighting where customization and brand premium differentiate commodity competitors.
Regulatory Framework
The US Department of Energy's SSL Quality Advocates program and ENERGY STAR certification requirements shape product eligibility for utility rebate programs across American states, while Canada's Natural Resources Canada (NRCan) regulates minimum efficacy standards through the Energy Efficiency Regulations. The US Federal Communications Commission (FCC) governs radio frequency emissions from networked lighting controls, creating compliance thresholds for smart city deployments that integrate cellular and mesh communication protocols. Stakeholders must monitor evolving dark sky legislation and Buy America domestic content requirements as these frameworks increasingly determine specification eligibility and procurement scoring in publicly funded projects.
Market Dynamics
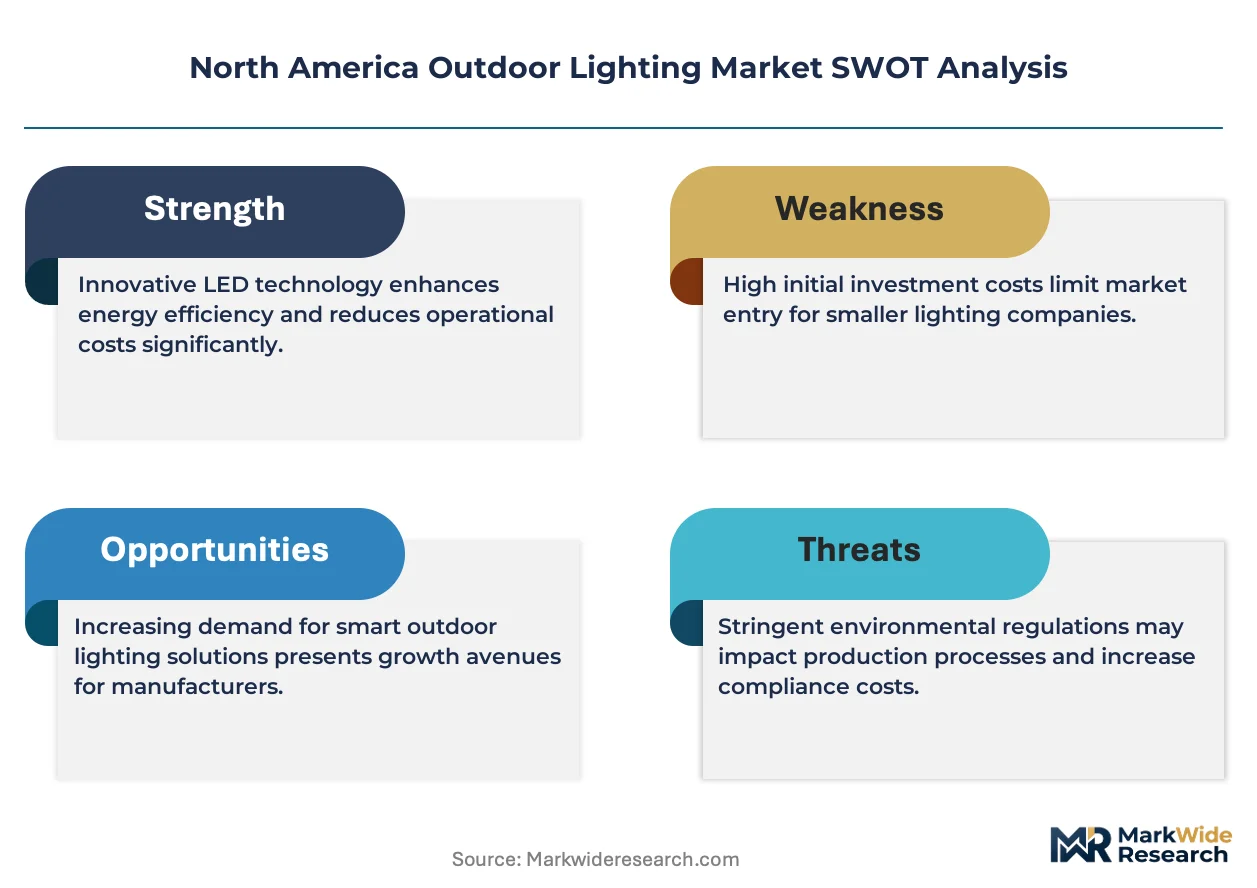
The US Department of Energy's tightening efficacy mandates and Buy America domestic content requirements are forcing manufacturers to reconfigure supply chains and accelerate LED driver localization.
Growth Catalysts
- Utility Rebate Programs:ENERGY STAR certification unlocks state-level incentive pools that compress payback periods for municipal LED retrofits.
- Dark Sky Ordinances:Arizona, Colorado, and Texas municipalities now mandate shielded luminaires, creating specification pull for low-glare optical designs.
- Smart City Integration:Networked lighting controls in Toronto and Chicago are merging with traffic management and public safety data streams.
Market Restraints
- Aluminum and Copper Volatility:Raw material price swings in pole and housing fabrication squeeze fixed-price contract margins.
- Driver Component Concentration:Asian-sourced LED drivers create supply vulnerability for US-based fixture assemblers.
- FCC Certification Friction:Radio frequency emission testing for mesh and cellular controls extends product launch timelines.
Strategic Opportunities
- Rural Solar-Integrated Deployments:Battery chemistry improvements and photovoltaic gains are opening off-grid roadway and park applications across the Canadian Prairies.
- Predictive Maintenance Contracts:Connected lighting platforms enable recurring software revenue streams alongside hardware sales.
- Buy America Compliance Engineering:Domestic content scoring in federally funded infrastructure creates competitive differentiation for US-based component sourcing.
Industry Challenges
- RF Engineering Talent Scarcity:Mesh network and cellular control integration requires specialized firmware expertise that outpaces vocational pipeline output.
- Legacy HID Ballast Compatibility:Retrofit programs must engineer around existing pole and wiring infrastructure without full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Outdoor Lighting Market |
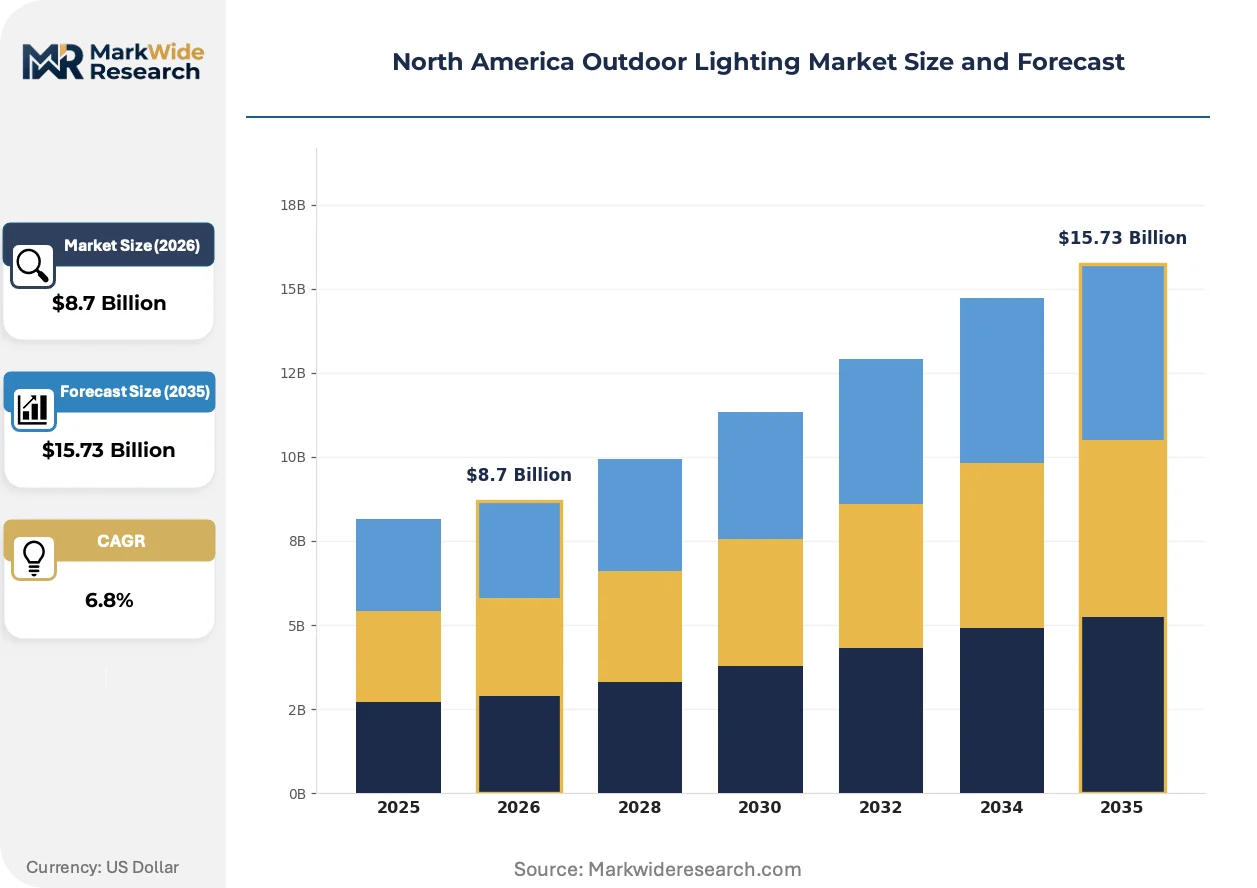
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Flood Lights, Decorative Lights, Wall Lights Technology: LED, HID, Solar, Fluorescent Application: Street & Roadway, Parks, Commercial, Residential End User: Municipalities, Commercial Developers, Homeowners, Contractors |
| Companies Covered | Signify Holding, Acuity Brands Lighting, Eaton Intelligent Lighting, Cree Lighting, ams-OSRAM AG, Hubbell, GE Current, Dialight, Ideal Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Outdoor Lighting Market Trends and Innovations
Digital twin and remote diagnostics capabilities are compressing service response times while enabling new outcome-based contracting models across municipal and commercial accounts.
LiDAR-enabled adaptive street lighting is virtualizing traffic-responsive illumination by embedding pedestrian and vehicle detection directly into luminaire nodes. California DOT pilots are deploying these systems along high-collision corridors. The technology is virtualizing the traditional fixed-schedule photocell model into dynamic, event-driven energy optimization.
The US Federal Communications Commission's Part 15 rules for unlicensed radio devices are tightening emission limits for mesh-networked controls. Manufacturers must redesign antenna architectures and retest existing SKUs. Smart city deployments in Chicago and Austin are delaying procurement until recertified hardware reaches distribution channels.
Municipal procurement teams are consolidating specification authority into centralized sustainability offices, displacing traditional public works-driven buying. Electrical distributors face margin compression as direct-to-municipality platform contracts bypass wholesale channels. This concentration is most visible in California and New York where climate mandates empower centralized procurement functions.
North America Outdoor Lighting Market Segmentation
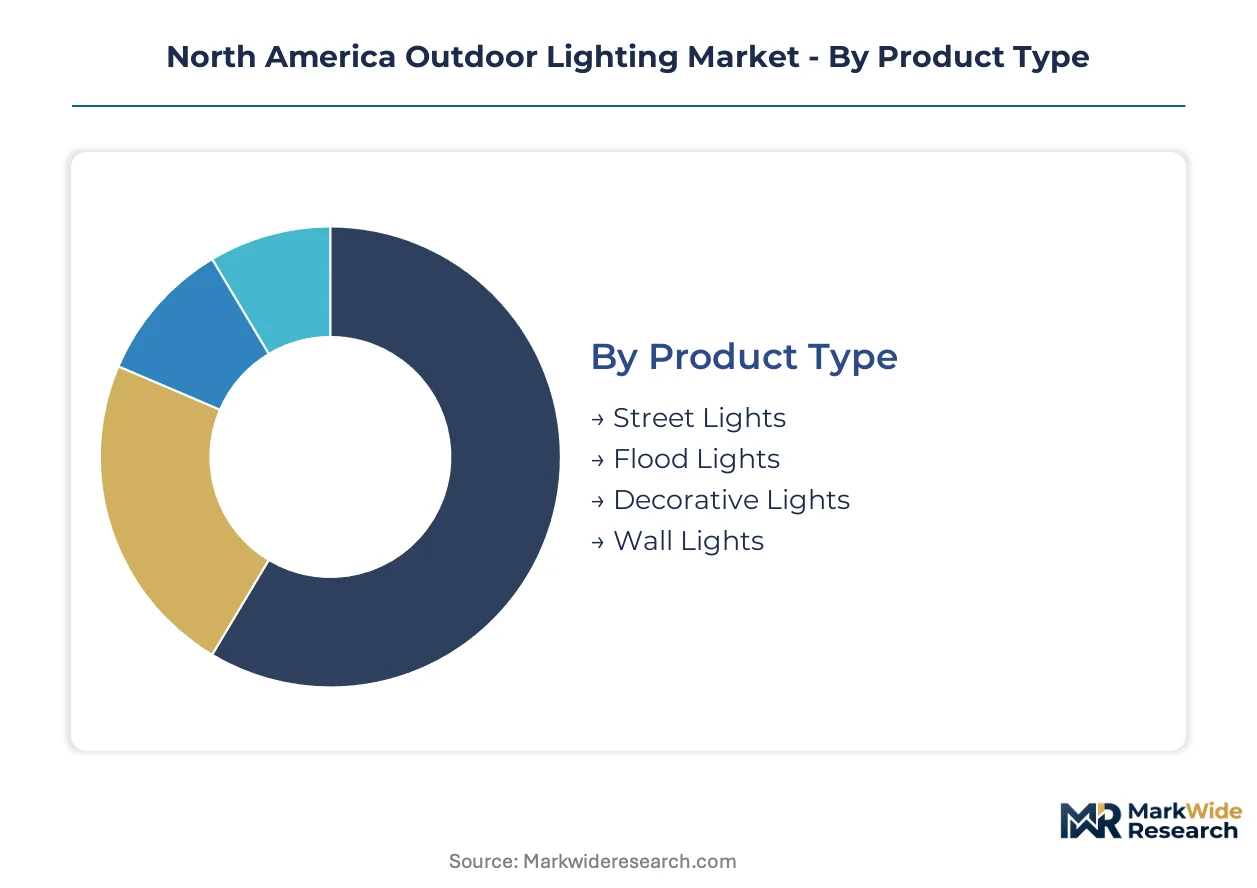
Segmentation in the North America outdoor lighting market reveals how procurement authority, technology transitions, and installation context reshape competitive positioning across hardware and service revenue streams. Understanding these divides illuminates where specification-grade margins concentrate versus commodity volume plays.
Product Type:
Mature pole-mounted categories dominate municipal procurement volumes while emerging form factors capture architectural specification premiums.
- Street Lights:Cobra-head and shoebox configurations engineered for IESNA roadway distribution patterns with IP66 ratings and 100,000-hour L70 lifespans. Demand concentrates in California and Texas DOT retrofits where utility rebate programs compress payback periods below four years.
- Flood Lights:Asymmetric and symmetric optic packages delivering 10,000 to 100,000 lumens for area illumination with NEMA beam spread classifications. Sports complexes and logistics facilities across Ontario and Illinois drive specification pull for glare-controlled designs.
- Decorative Lights:Post-top and pendant configurations blending aesthetic housing designs with functional photometric output.
- Wall Lights:Compact forward-throw and full-cutoff distributions for facade grazing and security perimeter applications.
Street lights retain volume leadership; wall lights hold the steepest expansion curve in commercial retrofit programs.
Technology:
Cost tier stratification separates legacy installed base from next-generation procurement specifications.
- LED:Solid-state packages with 130+ lumens per watt efficacy, dimmable drivers, and 50,000-hour minimum rated life. Municipal procurement across Arizona and Colorado now mandates LED for all new installations under dark sky compliance frameworks.
- Solar:Integrated photovoltaic panels with lithium iron phosphate battery storage and adaptive control electronics. Remote Canadian Prairie roadways and Arizona tribal lands drive off-grid deployment where trenching costs exceed hardware premiums.
- HID:High-pressure sodium and metal halide legacy installations requiring ballast-compatible retrofit engineering.
- Fluorescent:Compact and linear sources retained in cost-constrained residential and small commercial applications.
LED captures the dominant procurement share; solar is climbing the fastest as battery economics improve.
Application:
Customer type concentration determines whether specifications flow through centralized sustainability offices or traditional public works channels.
- Street & Roadway:DOT and municipal public works procurement with AASHTO pole standards and IES roadway lighting criteria. Texas and California infrastructure budgets channel the largest volume through centralized procurement platforms.
- Commercial:Property developer and facility manager specifications prioritizing brand image and operating cost reduction. Chicago and Toronto corporate campuses drive demand for tunable white and circadian-optimized facade systems.
- Parks:Recreation department procurement blending safety illumination with ecological sensitivity requirements.
- Residential:Homeowner and builder-grade installations through electrical distributor and big-box retail channels.
Street and roadway retains volume leadership; commercial holds the steepest expansion curve in connected lighting upgrades.
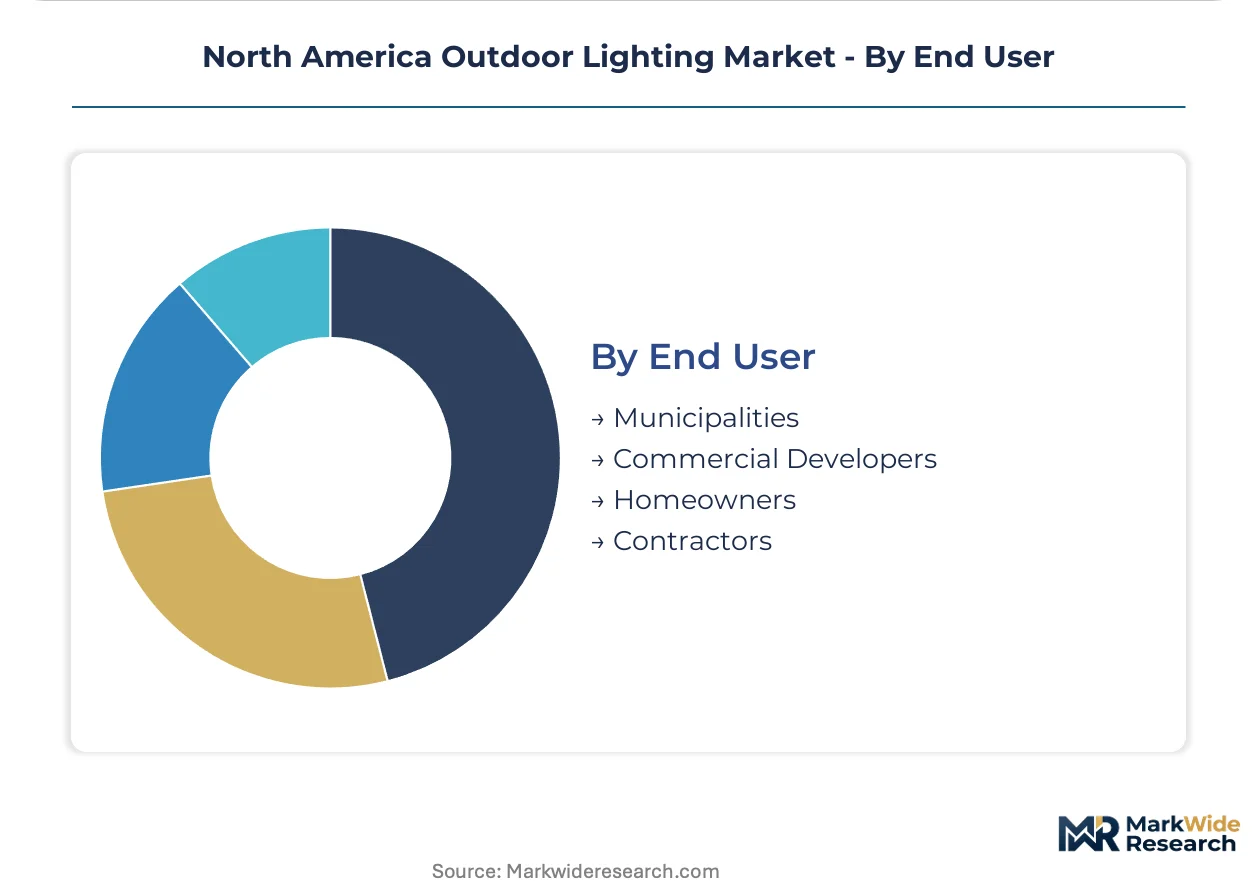
End User:
Procurement authority migration reshapes channel economics and margin capture mechanisms.
- Municipalities:Centralized sustainability offices consolidating specification authority away from public works departments. California and New York climate mandates accelerate this shift toward outcome-based contracting.
- Commercial Developers:Institutional and corporate real estate teams prioritizing LEED certification and tenant experience metrics.
- Homeowners:Retail and e-commerce procurement of replacement and new construction lighting.
- Contractors:Electrical and landscape installation firms sourcing through distributor relationships or direct manufacturer programs.
Municipalities retain volume leadership; commercial developers hold the steepest expansion curve in smart city integration projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian municipal buyers demonstrate the highest price elasticity, deferring procurement during commodity spikes, while Texas DOT and California sustainability offices absorb premiums for smart city integration and dark sky compliance.
United States
California and Texas DOT retrofits channel the largest infrastructure volumes through centralized procurement platforms where utility rebate programs compress LED payback periods below four years. The US Department of Energy's SSL Quality Advocates program and ENERGY STAR certification requirements shape product eligibility for state-level incentive pools. Chicago and Austin smart city deployments are delaying procurement until FCC-recertified mesh-networked hardware reaches distribution channels following Part 15 emission limit tightening.
Canada
Remote Prairie roadways and Ontario municipal parks drive off-grid solar-integrated deployments where trenching costs exceed hardware premiums and lithium iron phosphate battery economics improve total cost of ownership. Natural Resources Canada regulates minimum efficacy standards through the Energy Efficiency Regulations, creating compliance thresholds for cross-border suppliers. Toronto's connected lighting pilots concentrate networked controls integration with traffic management and public safety data streams.
Mexico
Border state municipalities and industrial corridor developers are accelerating LED retrofits as CFE utility programs expand rebate pools for high-efficacy street lighting in Baja California and Nuevo León. The national energy regulator SENER coordinates federal efficiency mandates with state infrastructure budgets. Mexico City Metro's smart city initiatives are piloting traffic-responsive illumination along high-volume corridors where pedestrian detection virtualizes traditional fixed-schedule photocell models.
North America Outdoor Lighting Market Competitive Landscape
Capability concentration sits with specification-grade engineering specialists; scale advantage sits with diversified electrical conglomerates that leverage channel partnerships with national distributors. The vendor base organizes around three strategic archetypes: connected platform providers securing recurring software revenue, vertically integrated component manufacturers controlling LED driver supply, and specification-grade engineering houses anchoring utility-scale roadway projects. Dominant competitive moves include backward integration into captive LED driver production and outcome-based service contracting that extends asset life cycles through predictive maintenance platforms.
Among Netherlands-based lighting conglomerates, Signify Holding exemplifies the connected platform archetype through its Interact software ecosystem. US-domiciled electrical manufacturers Acuity Brands Lighting and Eaton Intelligent Lighting occupy positions on opposite vectors of the competitive map—Acuity sustaining positioning through upstream control over component manufacturing, Eaton anchoring presence in specification-grade infrastructure through distributor channel density. These three entities represent the tier-one competitive set against which mid-scale specialists and regional assemblers define differentiation strategies.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands Lighting |
| Eaton Intelligent Lighting |
| Cree Lighting |
| ams-OSRAM AG |
| Hubbell |
| GE Current |
| Dialight |
| Ideal Industries |
| Others |
Pricing and Supply Chain Analysis
Asian-sourced LED driver concentration feeds directly into margin compression for North American fixture assemblers, shifting value capture toward aftermarket service tiers and software-enabled recurring revenue models.
Pricing Analysis
Aftermarket service contracts and predictive maintenance subscriptions now drive lifetime value capture for platform providers. Pricing stratifies across specification-grade architectural systems, utility-scale roadway packages, and commodity retrofit replacements. Cost compression in the LED driver tier intensifies because of import dependency and aluminum housing volatility. Municipal procurement teams demonstrate the highest price elasticity, while commercial developers absorb premiums for connected lighting and dark sky compliance.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for North American outdoor lighting manufacturers. Component sourcing draws from China for LED drivers, Mexico for pole fabrication, and domestic facilities for final fixture assembly. Raw material dependencies span aluminum extrusions for housings, copper for electrical conductors, and lithium iron phosphate cells for solar-integrated systems. Single-source vulnerability in driver electronics creates procurement fragility. Distribution runs through national electrical distributors and direct-to-municipality platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart city integration and dark sky ordinance proliferation are disrupting traditional procurement channels, creating asymmetric opportunity for platform-native competitors against legacy hardware specialists.
For Market Incumbents: Pre-empt platform commoditization by securing FCC-recertified mesh network architectures ahead of delayed municipal deployments in Chicago and Austin. Backward integration into captive LED driver production mitigates Asian supply vulnerability. Channel control through distributor partnerships anchors specification-grade positioning against direct-to-municipality procurement consolidation. For New Entrants and Emerging Players: Rural solar-integrated roadway deployments across the Canadian Prairies and Arizona tribal lands represent the most penetrable entry point where trenching economics override incumbent scale advantages. Predictive maintenance software for existing LED retrofits offers a services-first wedge with lower capital barriers. Target outcome-based contracting models that displace traditional public works procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward connected platform providers with demonstrated recurring revenue traction and utility-scale specification authority. The five-to-ten-year viability window favors vendors combining software subscription models with Buy America-compliant hardware sourcing. Monitor FCC Part 15 recertification completion rates as the signal for procurement restart timing in delayed smart city deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Driver Manufacturing | Captive supply of critical components insulates margins from Asian sourcing volatility and tariff exposure. |
| Connected Platform Subscription Launch | Recurring software revenue streams transform transactional hardware economics into sustained customer lifetime value. |
| Buy America Compliance Engineering Investment | Domestic content scoring unlocks federally funded infrastructure procurement eligibility and competitive differentiation. |
| Predictive Maintenance Service Rollout | Outcome-based contracting extends asset life cycles while capturing aftermarket revenue from installed LED bases. |
| Dark Sky Certification Portfolio Expansion | Shielded luminaire specifications align with Arizona, Colorado, and Texas municipal mandate proliferation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with municipal procurement directors, electrical distributor category managers, utility rebate program administrators, and smart city integration engineers; and secondary validation through ENERGY STAR certification databases, FCC equipment authorization filings, US DOT infrastructure budget disclosures, and Natural Resources Canada regulatory bulletins. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Forecast inputs span LED efficacy improvement curves, battery chemistry cost reduction trajectories, utility rebate program expansion schedules, and dark sky ordinance adoption patterns across the analysis window. Segmentation dimensions include product type, technology tier, application context, and end-user procurement authority. CAGRs derive from installed base replacement cycles, new infrastructure build rates, and technology transition velocity.
Macroeconomic conditions sit as an overlay; deviation in municipal infrastructure appropriations, aluminum and copper commodity price bands, or FCC regulatory enforcement intensity would shift the trajectory. Forecasts embed assumptions about smart city pilot conversion rates and solar-integrated system total cost of ownership parity timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
Residential Lighting Fixtures Market
Lighting
Ultraviolet Lamps Market
Lighting
Tritium Light Source Market
Lighting
Lighting Product Market
Lighting
Ambient Lighting Market
Lighting
Bulb Market
Lighting
EV Lighting Market
Lighting
Connected Lighting Platform Market
Lighting
Wireless Lighting Market
Lighting
Plasma Lighting Market
Lighting
Solar Lights Market
Lighting
Europe Decorative Lighting Market
Lighting
Lighting As a Service (Laas) Market
Lighting
Lighting Control Components Market
Lighting
UV Lamps Market