
 Bacteriological Light Market | 2026-2036
Bacteriological Light Market Size, Share, and Industry Trends Forecast 2026-2036
Bacteriological Light Market Outlook
The gap between validated medical-grade systems and unregulated consumer devices is recalibrating competitive boundaries across the bacteriological light landscape. Signify Holding leverages its luminaire scale to dominate institutional procurement channels in Europe. Atlantic Ultraviolet Corporation anchors North American supply through captive mercury-vapor tube production. Xenex Disinfection Services differentiates via pulsed xenon protocols targeting hospital-acquired infection protocols.
Bacteriological light denotes electromagnetic radiation engineered to inactivate microorganisms through photochemical damage to nucleic acids, typically operating at 200–280 nanometer wavelengths for germicidal efficacy. UV-C LEDs eliminate mercury dependency while sacrificing output intensity versus traditional low-pressure lamps, constraining their deployment to flow rates below 500 liters per minute in water treatment. Among applications, surface disinfection leads in installed base owing to pandemic-era hospital infrastructure builds, yet advanced oxidation processes for pharmaceutical wastewater represent the fastest-expanding margin pool. Photocatalytic technology segments command premium positioning where titanium dioxide coatings enable continuous self-sterilizing surfaces in healthcare settings.
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act constrain market entry for claims exceeding general sanitation, while EU REACH compliance on mercury content accelerates LED substitution timelines. FDA enforcement discretion letters for COVID-19-era UV devices are narrowing, forcing manufacturers toward 510(k) pathways for medical device classification. Stakeholders must weigh capital commitment to mercury-free platforms against the residual cost advantage of mature amalgam lamp supply chains as regulatory windows tighten.
Market Dynamics
Mercury-free UV-C LED platforms are compressing installed costs and recalibrating competitive positioning against legacy amalgam lamp supply chains, forcing capital reallocation across manufacturing footprints.
Growth Catalysts
- ECHA Biocidal Product Regulation:Tightened efficacy validation standards in Germany are accelerating institutional procurement of validated UV-C systems in healthcare facilities.
- Semiconductor manufacturing clusters:East Asian fabs are deploying advanced oxidation modules for ultrapure water loops, creating concentrated demand for high-intensity bacteriological light systems.
- Photocatalytic titanium dioxide coatings:Continuous self-sterilizing surfaces in healthcare settings are expanding addressable market beyond episodic disinfection protocols.
Market Restraints
- Mercury vapor supply concentration:Captive production of low-pressure lamps in North America creates dependency on limited qualified tube manufacturers.
- LED output intensity ceiling:UV-C diode arrays sacrifice radiant flux versus traditional lamps, constraining deployment to flow rates below 500 liters per minute in water treatment.
- FDA 510(k) pathway complexity:Narrowing enforcement discretion for COVID-19-era devices is extending regulatory timelines for medical-grade claims.
Strategic Opportunities
- Pharmaceutical wastewater oxidation:Advanced oxidation processes for API degradation represent the fastest-expanding margin pool in industrial applications.
- EU REACH mercury restrictions:Accelerated substitution timelines are creating first-mover advantage for LED platform manufacturers.
- Consumer device channel unbundling:Direct-to-hospital procurement platforms are bypassing traditional luminaire distributors in institutional segments.
Industry Challenges
- Optical engineering talent scarcity:Deep UV semiconductor physics and photocatalytic reactor design expertise concentrates in limited academic and industrial centers.
- Legacy system integration friction:Retrofitting UV-C modules into existing HVAC and water infrastructure requires custom mechanical and control interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacteriological Light Market |
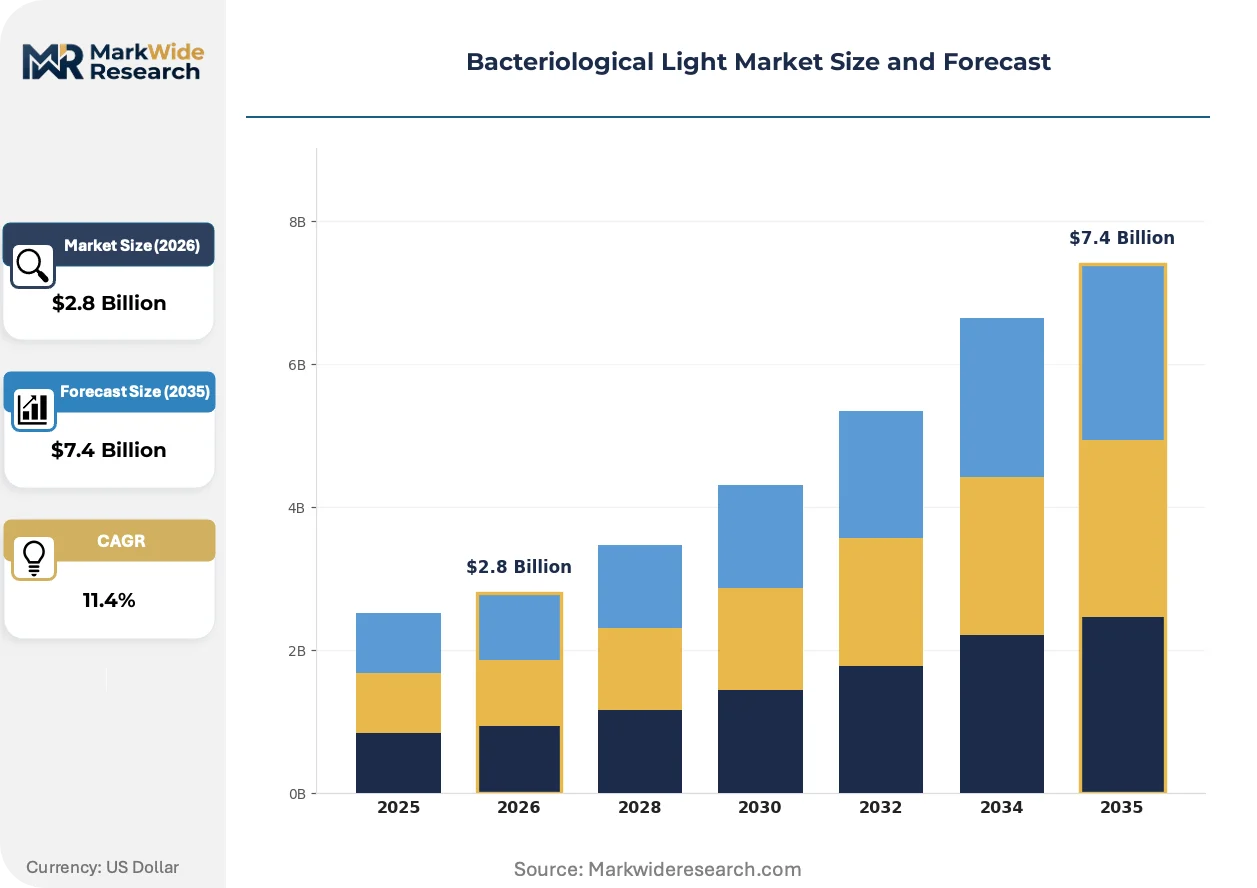
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, UV-C, Fluorescent, Halogen Application: Water Treatment, Air Purification, Surface Disinfection, Laboratory Research End User: Healthcare Facilities, Educational Institutions, Industrial Plants, Research Labs Technology: Photocatalytic, Conventional, Advanced Oxidation, Ozone Generation |
| Companies Covered | Signify Holding, Acuity Brands, Osram Licht, Atlantic Ultraviolet Corporation, Xenex Disinfection Services, American Ultraviolet, Trojan Technologies, UV Light Technology Limited, AquiSense Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacteriological Light Market Strategic Shifts
Wavelength-selective emitter architectures and service-model reinvention are compressing technology refresh cycles and redrawing value capture boundaries across the bacteriological light value chain.
UV-C LED array technology is modularizing. Solid-state emitters at 265-280 nanometers enable scalable panel configurations for surface and air disinfection. Hospital infrastructure teams in the United States are piloting swappable emitter cartridges that reduce maintenance downtime. This architecture is modularizing system design, allowing manufacturers to compress SKUs while expanding application coverage across room size and airflow specifications.
REACH Annex XVII mercury restrictions are tightening industrial supply constraints. The EU prohibition on mercury in certain products is forcing accelerated R&D spending on high-power LED alternatives. Water treatment OEMs serving municipal and pharmaceutical clients are requalifying reactor designs around diode-based sources, with Germany and Netherlands leading validation protocols.
Equipment-as-service contracting is displacing capital purchase models. Hospital procurement departments are shifting toward subscription-based disinfection assurance with performance guarantees. This restructuring concentrates vendor risk while transferring operational burden to equipment suppliers, with Nordic healthcare systems and US integrated delivery networks piloting outcome-based arrangements.
Bacteriological Light Market Segmentation
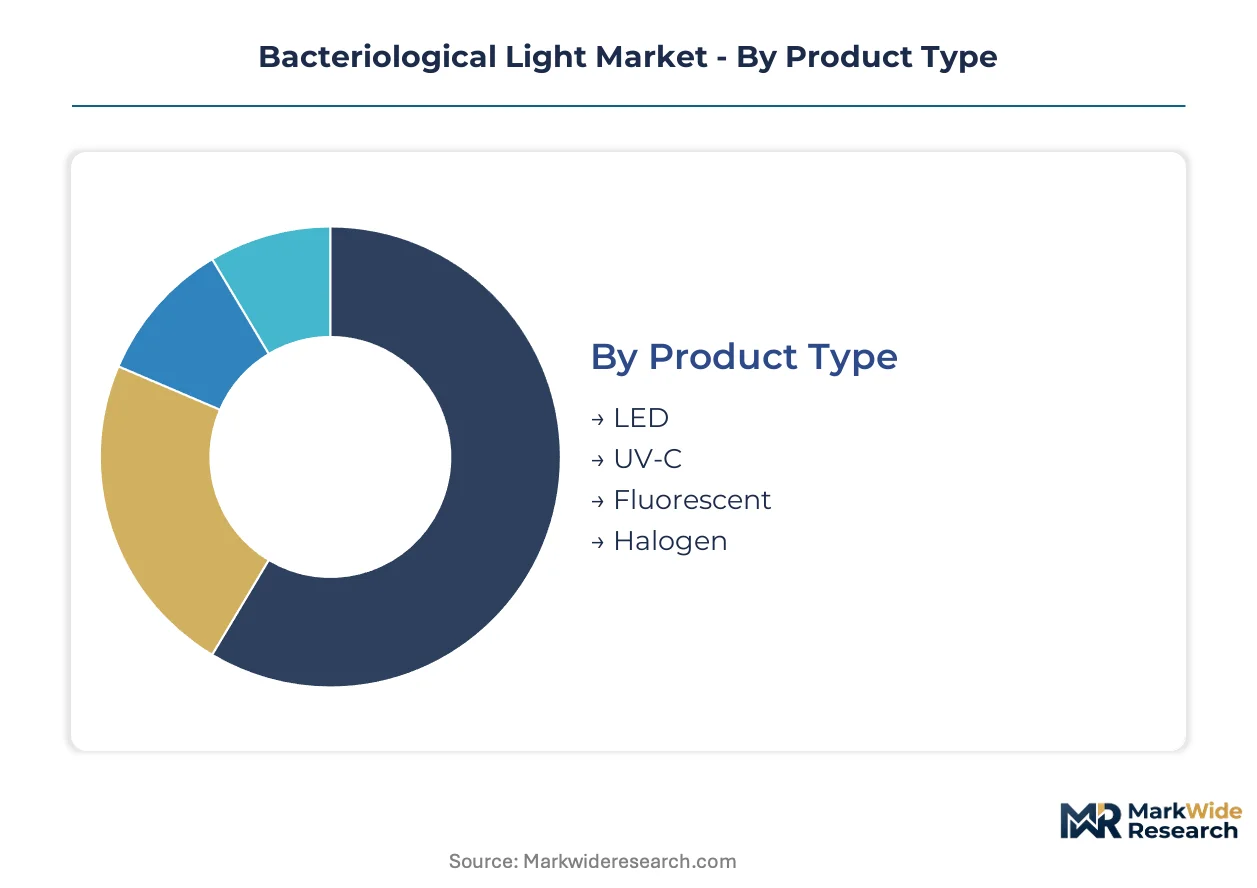
Bacteriological light systems vary dramatically in capital requirements, from semiconductor fab installations requiring multi-million dollar advanced oxidation trains to modular surface disinfection units for clinics. Understanding these investment tiers clarifies where vendor margins concentrate and which segments attract infrastructure financing.
Product Type:
Capital intensity peaks in mercury-free LED platforms where epitaxial wafer fabrication and deep UV packaging drive upfront manufacturing investment.
- LED:Solid-state emitters at 265-280 nanometers eliminate mercury dependency while demanding precision semiconductor fabrication. Healthcare procurement teams in Germany prioritize validated LED systems under tightened ECHA biocidal standards, though output intensity constraints limit water treatment flows.
- UV-C:Low-pressure mercury and amalgam lamps deliver superior radiant flux for high-volume water loops. East Asian semiconductor fabs deploy these systems for ultrapure water treatment where flow rates exceed 500 liters per minute.
- Fluorescent:Phosphor-converted sources for general antimicrobial applications in educational settings.
- Halogen:Thermal-emission systems with limited germicidal efficacy, primarily legacy installations.
Most installed capacity flows through UV-C. Expansion is steepest in LED.
Application:
Application segments diverge by operational complexity, with continuous-flow water systems requiring more sophisticated control architecture than episodic surface protocols.
- Water Treatment:Continuous disinfection for municipal, pharmaceutical, and semiconductor process water. Advanced oxidation modules for API degradation command premium positioning in industrial margins.
- Surface Disinfection:Room-scale and device-level protocols dominate hospital infrastructure builds from pandemic-era capital programs.
- Air Purification:HVAC-integrated and standalone units for occupied space treatment.
- Laboratory Research:Controlled-environment sterilization for cell culture and analytical workflows.
Surface disinfection retains the largest installed base. Pharmaceutical wastewater oxidation climbs fastest.
End User:
Customer archetypes range from procurement-centralized hospital networks to fragmented research institutions with disparate technical specifications.
- Healthcare Facilities:Hospitals and clinics with centralized infection control protocols. Nordic integrated delivery networks pilot subscription-based disinfection assurance with outcome guarantees.
- Industrial Plants:Semiconductor, pharmaceutical, and food processing operations with validated process requirements.
- Educational Institutions:Schools and universities with episodic disinfection needs and constrained capital budgets.
- Research Labs:Academic and commercial laboratories requiring precise wavelength control for experimental reproducibility.
Healthcare facilities absorb the majority of current shipments. Industrial plants show the steepest order book expansion.
Technology:
Technology platforms separate by mechanism of microbial inactivation, from direct nucleic acid damage to radical-mediated oxidation cascades.
- Photocatalytic:Titanium dioxide coatings activated by UV-A or visible light enable continuous self-sterilizing surfaces. Healthcare settings in Germany validate these for high-touch infrastructure.
- Advanced Oxidation:Hydroxyl radical generation through UV/hydrogen peroxide or ozone combinations. Pharmaceutical manufacturers deploy these for recalcitrant API destruction in wastewater streams.
- Conventional:Direct UV-C irradiation without chemical augmentation for standard disinfection protocols.
- Ozone Generation:Corona discharge or UV-based ozone production for oxidative water treatment.
Conventional systems anchor current deployment. Photocatalytic platforms gain share fastest in premium healthcare specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep UV semiconductor physicists cluster in Eindhoven, Nagoya, and Boston, anchoring innovation pipelines for solid-state emitter architectures. Their concentration shapes where capital flows and where regulatory validation protocols achieve first-mover status.
Germany
Hospital procurement teams in Munich and Berlin are scaling UV-C installations under ECHA biocidal product standards tightened in 2024. The Federal Environment Agency is accelerating mercury-free substitution timelines through REACH Annex XVII enforcement. The Rhine-Ruhr industrial corridor hosts validation laboratories where LED-based water treatment systems undergo reactor requalification for pharmaceutical clients.
United States
Integrated delivery networks in Texas and California are piloting subscription-based disinfection assurance with outcome guarantees. FDA enforcement discretion letters for COVID-19-era devices are narrowing, forcing manufacturers toward 510(k) pathways for medical-grade claims. The Research Triangle in North Carolina anchors pulsed xenon protocol development targeting hospital-acquired infection reduction.
China
Semiconductor fabs in the Yangtze River Delta are deploying advanced oxidation modules for ultrapure water loops at flow rates exceeding 500 liters per minute. The Ministry of Ecology and Environment is tightening discharge standards for pharmaceutical wastewater, driving API degradation system procurement. Suzhou and Wuxi host concentrated manufacturing clusters for mercury-vapor tube components serving domestic and export markets.
Japan
Metropolitan hospital systems in Tokyo and Osaka are validating photocatalytic titanium dioxide coatings for continuous self-sterilizing surfaces. METI efficiency standards are compressing payback periods for LED retrofits in healthcare infrastructure. The Kansai region maintains specialized optical engineering programs supplying deep UV packaging expertise to domestic emitter manufacturers.
Netherlands
Signify Holding's Eindhoven headquarters anchors European luminaire scale for institutional procurement channels. The National Institute for Public Health and the Environment is harmonizing efficacy validation protocols with ECHA frameworks, streamlining cross-border healthcare facility approvals. The Brainport region concentrates epitaxial wafer fabrication capacity for mercury-free LED platforms.
Bacteriological Light Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent manufacturing footprints in the bacteriological light landscape. The vendor base separates between integrated luminaire manufacturers controlling distribution channels and specialized emitter technology developers licensing core components. Three archetypes dominate: multinational lighting conglomerates with institutional procurement relationships, captive mercury-vapor tube producers defending legacy installed bases, and venture-backed LED platform innovators capturing substitution premiums. Competitive moves concentrate on strategic partnerships for reactor validation and geographic expansion through distributor acquisition in healthcare procurement channels.
Within the multinational tier, Signify Holding and Osram Licht occupy positions defined by luminaire scale and European institutional access. Atlantic Ultraviolet Corporation anchors North American supply through captive production indicated by its corporate designation. Xenex Disinfection Services exemplifies the venture-backed archetype, with its name signaling specialization in pulsed protocols for hospital-acquired infection applications. These three represent distinct strategic postures: procurement channel dominance, upstream manufacturing control, and clinical outcome differentiation.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| Osram Licht |
| Atlantic Ultraviolet Corporation |
| Xenex Disinfection Services |
| American Ultraviolet |
| Trojan Technologies |
| UV Light Technology Limited |
| AquiSense Technologies |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII mercury restrictions gate qualified supply and premium-tier pricing access for validated UV-C systems in European healthcare procurement. Buyers without certified LED platforms face exclusion from German hospital tenders under tightened ECHA biocidal standards, compressing margin capture to compliant manufacturers.
Pricing Analysis
The bundled-vs-unbundled service split separates capital purchase models from subscription-based disinfection assurance with performance guarantees. Three-tier pricing structure across premium, standard, and economy levels differentiates validated medical-grade systems from unregulated consumer devices, with certification grade and after-sales service as primary drivers. Cost compression in standard tiers intensifies because LED platform manufacturers compete for substitution premiums. Educational institutions exhibit highest price sensitivity, while Nordic integrated delivery networks prioritize outcome guarantees over unit economics.
Supply Chain Analysis
Freight cost volatility from Asia-Europe corridors elevates landed costs for mercury-vapor tube components and deep UV semiconductor packages. Supply concentrates in China, Japan, and the Netherlands, with epitaxial wafer fabrication drawing from specialized chemical precursors and precision optical substrates. Single-source vulnerability in qualified tube manufacturing creates procurement risk for North American healthcare distributors. Distribution runs through institutional luminaire channels and direct-to-hospital procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in bacteriological light hinges on LED platform cost-down curves and premium-tier shift toward outcome-based contracting in healthcare procurement.
For Market Incumbents: To counter venture-backed LED innovators capturing substitution premiums, legacy mercury-vapor manufacturers should accelerate reactor requalification for pharmaceutical wastewater oxidation and deepen captive supply of deep UV packaging through backward integration into epitaxial wafer capacity. For New Entrants and Emerging Players: Pulsed xenon protocol differentiation offers a technology-first wedge into hospital-acquired infection reduction segments underserved by continuous irradiation systems. White-space targets include US integrated delivery networks piloting subscription models and East Asian semiconductor fabs requiring advanced oxidation modules for ultrapure water loops above 500 liters per minute. For Investors and Strategic Acquirers: Roll-up economics work for specialized LED platform developers because regulatory validation protocols create durable moats against commoditization. Acquisition targets should demonstrate EPA or ECHA biocidal product registrations with hospital procurement relationships. The signal to watch is FDA 510(k) clearance velocity for medical-grade claims as enforcement discretion narrows.| Strategic Initiative | Industry Significance |
|---|---|
| Mercury-Free Platform Migration | REACH Annex XVII compliance secures European healthcare procurement access against substitution risk. |
| Advanced Oxidation Module Deployment | Pharmaceutical wastewater oxidation commands premium margins in industrial applications. |
| Subscription Service Model Launch | Outcome-based contracting transfers operational burden to vendors while concentrating risk. |
| Reactor Requalification Investment | LED-based system validation opens pharmaceutical and semiconductor process water segments. |
| Photocatalytic Coating Integration | Titanium dioxide surfaces expand addressable market beyond episodic disinfection protocols. |
Study Parameters
Coverage spans North America, Europe, and East Asia, with primary inputs from each region combined with secondary validation. Interviews with hospital procurement managers, biomedical engineers, semiconductor fab operations directors, and water treatment OEM technical leads anchored demand-side intelligence. Secondary sources included EPA registration databases, ECHA biocidal product filings, FDA 510(k) clearance records, and customs trade data for mercury-vapor tube components. Bottom-up unit economics triangulated against top-down sector spending estimates.
Granularity-level framing modeled product type, application, end user, and technology dimensions at country level for Germany, the United States, China, Japan, and the Netherlands. CAGRs derived from weighted average of historical substitution rates and regulatory-driven replacement timelines. Industry-specific inputs incorporated REACH Annex XVII enforcement schedules and FDA enforcement discretion narrowing patterns.
The model holds under stable regulatory enforcement timelines; deviation in ECHA efficacy validation acceleration or FDA 510(k) backlog clearance would shift LED substitution curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
EV Lighting Market
Lighting
Solar Column Headlight Market
Lighting
Directional Luminaire Market
Lighting
Lighting Product Market
Lighting
Xenon Lights Market
Lighting
Intelligent Lighting Controls Market
Lighting
Solid-State Lighting Source Market
Lighting
Tritium Light Source Market
Lighting
Dimmer and Color Tunable Market
Lighting
Global Lighting Control System Market
Lighting
Solar Spotlights Market
Lighting
Global Stadium Lighting Market
Lighting
UAE Smart Lighting Market
Lighting
Europe Decorative Lighting Market
Lighting
Ambient Lighting Market
Lighting
Graphene Lighting Market