
 Ultra Violet (UV) Lamps Market | 2026-2036
Ultra Violet (UV) Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra Violet (UV) Lamps Market Analytics
Subscription-based UV lamp replacement programs is pivoting how vendors monetize installed bases. Heraeus Noblelight leverages its mercury vapor expertise to anchor long-term service contracts with European semiconductor fabs. Seoul Viosys Co., Ltd. dominates UV-C LED chip supply through captive epitaxy capacity. Nichia Corporation differentiates via phosphor-converted UV-A modules for precision curing lines.
Ultra Violet lamps are gas-discharge or solid-state devices emitting electromagnetic radiation in the 100–400 nm wavelength range, with mercury vapor variants utilizing low-pressure arc tubes doped with argon and mercury to produce germicidal UV-C at 253.7 nm for pathogen inactivation. LED-based alternatives employ aluminum gallium nitride heterostructures to achieve comparable germicidal action without mercury content, serving water, air, and surface treatment applications across industrial and commercial settings. Mercury vapor systems still occupy the largest installed base in municipal water treatment, though UV-C LED modules represent the fastest-expanding technology segment as mercury phase-out regulations tighten. Material curing applications in automotive coatings and electronics assembly concentrate margin pools in UV-A and hybrid systems requiring precise wavelength tuning.
EPA drinking water disinfection rules and FDA food contact surface standards in the United States, alongside EU RoHS mercury restrictions and REACH substance registration in Europe, are reshaping product compliance requirements and accelerating LED substitution timelines. China's GB standards and MEE environmental discharge rules mandate UV treatment for specific industrial effluent categories, expanding domestic procurement volumes. Stakeholders must monitor regulatory divergence between mercury-ban jurisdictions and grandfathered infrastructure regions to align R&D portfolios with compliance trajectories.
Market Dynamics
Mercury phase-out mandates across multiple jurisdictions are compressing technology transition timelines, forcing simultaneous R&D acceleration and installed-base service reconfiguration across lamp manufacturers.
Growth Catalysts
- EPA Disinfection Rules:Municipal water utilities in the United States face upgraded pathogen inactivation standards, expanding procurement of validated UV-C systems for cryptosporidium and giardia compliance.
- China Industrial Effluent Mandates:MEE environmental discharge regulations for pharmaceutical and chemical manufacturing are mandating UV treatment integration into wastewater infrastructure.
- Aluminum Gallium Nitride Epitaxy:Advances in UV-C LED chip fabrication are reducing cost-per-milliwatt, enabling point-of-use disinfection in commercial foodservice and healthcare settings.
Market Restraints
- Mercury Supply Concentration:Primary mercury mining concentrates in Kyrgyzstan and China, creating geopolitical exposure for legacy lamp manufacturers dependent on liquid mercury feedstock.
- UV-C LED Thermal Management:Wall-plug efficiency limitations below 280 nm wavelengths restrict high-flow water treatment applications, preserving mercury vapor dominance in municipal scale.
- EU RoHS Exemption Uncertainty:Pending renewal decisions for mercury-containing lamps in professional equipment create compliance planning paralysis among European industrial buyers.
Strategic Opportunities
- India Water Infrastructure:Smart Cities Mission and AMRUT 2.0 allocations prioritize UV disinfection for secondary treatment in tier-2 municipal utilities with limited chlorination infrastructure.
- UV-C LED-AI Convergence:Integration of real-time dosage monitoring with connected lamp systems enables predictive maintenance contracts and usage-based billing models.
- Surface Disinfection Certification:FDA emergency use authorization pathways for UV-C devices in healthcare settings create first-mover advantage for validated system suppliers.
Industry Challenges
- Optical Engineering Talent Scarcity:Specialized expertise in radiometric calibration and quartz sleeve fouling dynamics remains concentrated among aging technician cohorts in Germany and Japan.
- Legacy Infrastructure Retrofit Complexity:Ballast incompatibility and chamber geometry constraints complicate LED module swaps in existing horizontal pressure vessel installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra Violet (UV) Lamps Market |
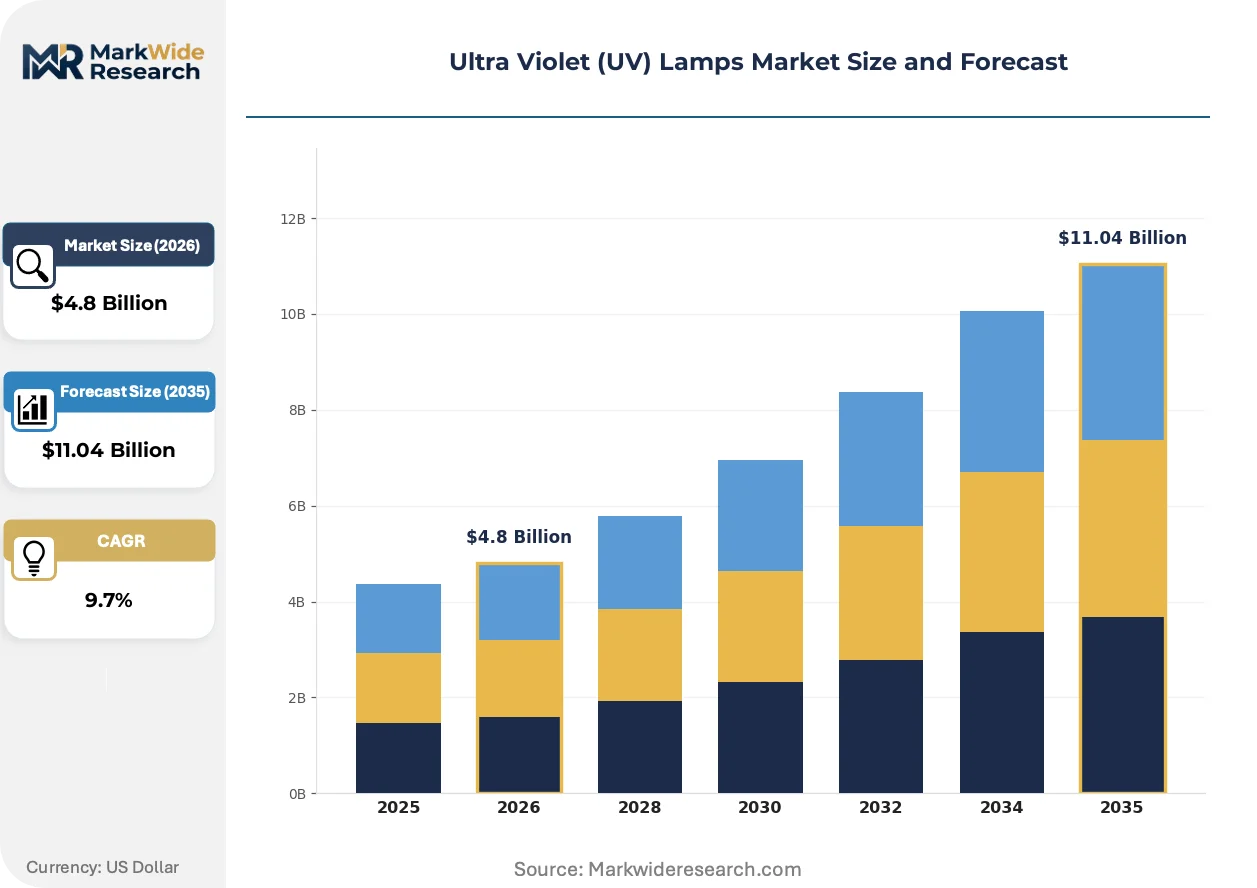
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mercury Vapor, Compact Fluorescent, LED, Plasma Application: Water Purification, Surface Disinfection, Air Treatment, Material Curing End User: Healthcare, Food & Beverage, Industrial, Residential Technology: UV-C, UV-B, UV-A, Hybrid |
| Companies Covered | Heraeus Noblelight, Nichia Corporation, Seoul Viosys Co., Ltd., Philips Lighting, Ushio Inc., Atlantic Ultraviolet Corporation, ams-OSRAM AG, American Ultraviolet, STANLEY ELECTRIC CO., LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra Violet (UV) Lamps Market Evolving Landscape
Technology substitution and regulatory fragmentation are simultaneously compressing product lifecycles and expanding application boundaries across the UV lamp value chain.
Hybrid UV-LED systems are unifying mercury vapor output reliability with solid-state dimming precision in precision manufacturing environments. Automotive coating lines at BMW and Volkswagen facilities in Germany are piloting these configurations for energy-responsive curing intensity. The convergence is unifying process control architectures that previously required separate PLC systems for arc and LED sources.
REACH substance authorization timelines for mercury compounds are tightening supply chain disclosure requirements for European lamp assemblers. ECHA's 2024 sunset date review for mercury in measuring devices signals broader category restrictions ahead. German and Dutch water utilities are accelerating LED tender specifications to preempt grandfathering uncertainty.
Subscription replacement programs are displacing transactional component sales in semiconductor fab maintenance channels. Heraeus and Ushio now bundle lamp supply with quarterly radiometer calibration and quartz sleeve inspection. This model concentrates most visibly in Taiwan and South Korea where fab uptime penalties exceed component costs by orders of magnitude.
Ultra Violet (UV) Lamps Market Segmentation
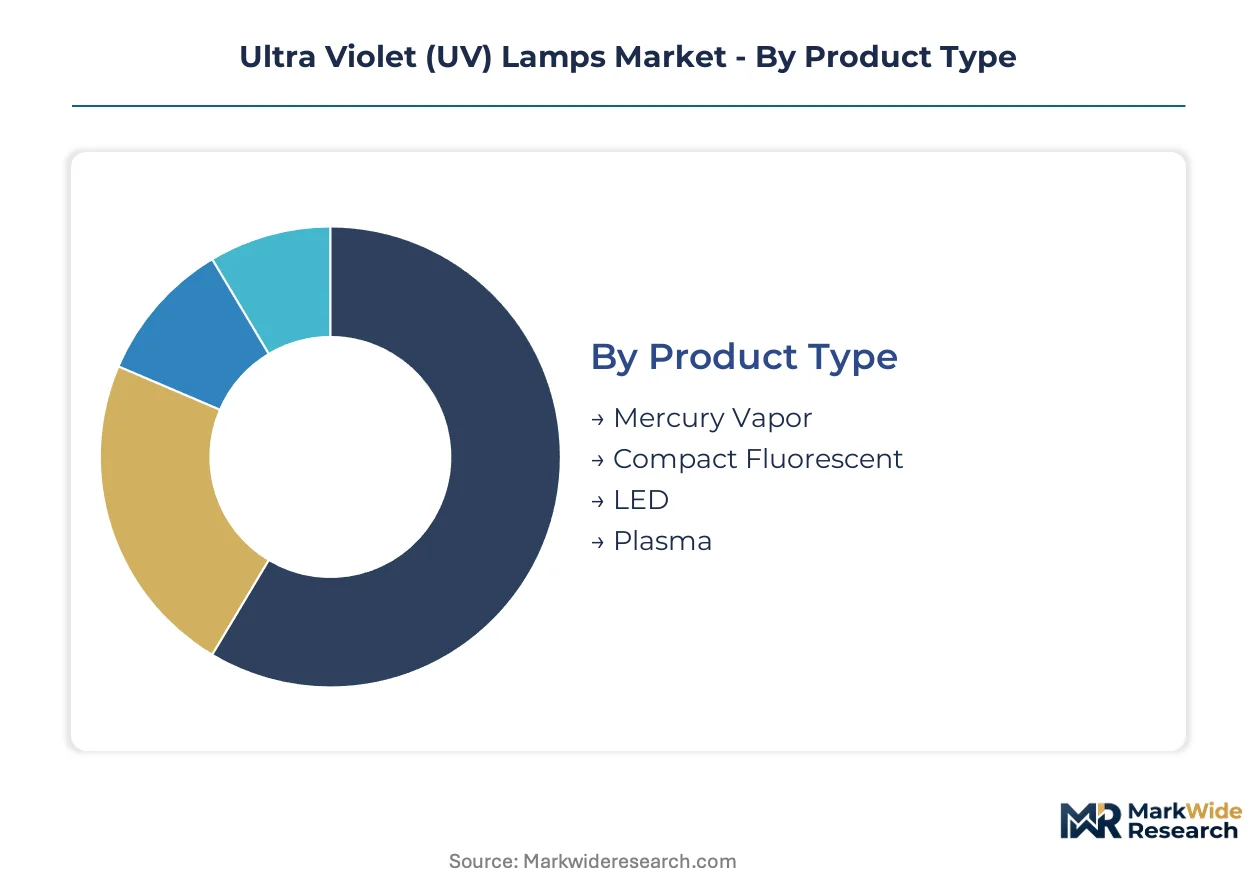
UV lamp procurement patterns diverge sharply across integration contexts. Standalone systems in municipal water plants demand different specifications than embedded modules in semiconductor manufacturing lines. Understanding these segmentation boundaries clarifies where technology substitution accelerates versus where legacy formats retain dominance.
Product Type:
Mercury vapor lamps anchor installed-base infrastructure while LED formats penetrate point-of-use applications where mercury compliance risks concentrate procurement decisions.
- Mercury Vapor:Low-pressure arc tubes doped with argon and mercury generate 253.7 nm UV-C output through gas discharge. Municipal utilities in Germany and the United States specify these for high-flow cryptosporidium inactivation where wall-plug efficiency requirements favor established designs.
- LED:Aluminum gallium nitride heterostructures emit germicidal wavelengths without mercury content. Commercial foodservice operators in Japan and South Korea adopt these for under-counter disinfection units where RoHS compliance eliminates vapor lamp options.
- Compact Fluorescent:Phosphor-coated tubes producing UV-A output serve consumer nail curing and counterfeit detection applications with limited commercial scale.
- Plasma:Dielectric barrier discharge configurations generate ozone-coupled UV for industrial effluent treatment in chemical manufacturing clusters.
Mercury vapor leads volumes today; LED is gaining share fastest as RoHS exemption timelines compress.
Application:
Water infrastructure commands capital expenditure cycles while surface and air treatment segments respond to regulatory emergency authorizations.
- Water Purification:Closed-vessel reactor designs with quartz sleeve protection dominate municipal secondary treatment. EPA Long Term 2 Enhanced Surface Water Treatment Rule mandates drive procurement across utilities serving populations above ten thousand.
- Material Curing:UV-A and UV-B systems polymerize automotive coatings and electronics conformal coatings. BMW and Volkswagen assembly lines in Germany specify hybrid arc-LED configurations for energy-responsive intensity modulation.
- Surface Disinfection:Mobile and fixed-mount UV-C systems target healthcare-associated infection reduction. FDA emergency use authorization pathways accelerated hospital procurement during respiratory pandemic periods.
- Air Treatment:In-duct and upper-room irradiation systems serve commercial HVAC integration. Building codes in Singapore and the United Arab Emirates now mandate UV-C in healthcare facility air handling.
Water purification generates the largest contract values; material curing commands the highest margin per installed watt.
End User:
Healthcare and food processing segments prioritize validation documentation while industrial buyers emphasize total cost of ownership across replacement cycles.
- Healthcare:Hospitals and long-term care facilities require third-party efficacy validation for UV-C surface systems. Joint Commission accreditation standards in the United States specify dosage verification protocols.
- Industrial:Semiconductor fabs and pharmaceutical manufacturers accept premium pricing for guaranteed uptime contracts. Taiwan and South Korean fabrication clusters concentrate subscription-based lamp replacement programs.
- Food & Beverage:Breweries and dairy processors deploy UV-C for pasteurization alternatives. FDA juice HACCP rules recognize UV treatment for five-log pathogen reduction.
- Residential:Point-of-use water pitchers and air purifiers represent emerging LED penetration. Consumer education gaps limit adoption velocity relative to commercial segments.
Industrial end users concentrate supplier margins; healthcare segments expand fastest on regulatory tailwinds.
Technology:
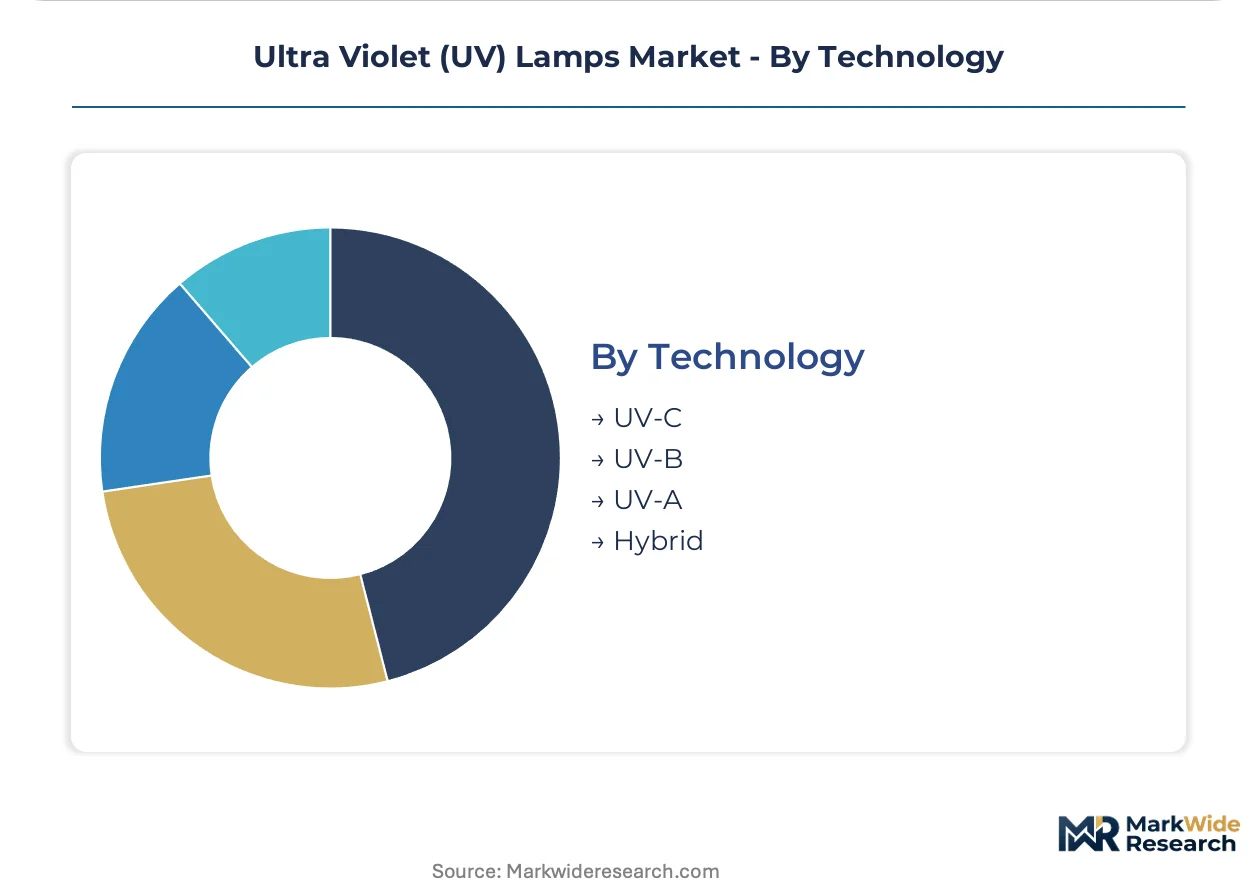
Wavelength specificity determines germicidal efficacy versus material interaction tradeoffs across application boundaries.
- UV-C:200-280 nm emission inactivates nucleic acids through thymine dimer formation. Germicidal action peaks at 265 nm, with mercury vapor at 253.7 nm and LED sources approaching this optimum through epitaxy refinement.
- Hybrid:Combined UV-C LED and mercury vapor architectures unify dimming precision with output reliability. Automotive coating lines pilot these configurations for process control integration.
- UV-A:315-400 nm wavelengths drive photopolymerization in printing and coating applications. Phosphor-converted modules enable precise wavelength tuning for specific resin chemistries.
- UV-B:280-315 nm emission serves phototherapy and limited industrial curing where deeper penetration matters.
UV-C dominates installed base; hybrid configurations climb fastest on manufacturing automation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China represent contrasting procurement trajectories, with German utilities accelerating LED tenders ahead of RoHS deadlines while Chinese industrial clusters expand mercury vapor capacity for wastewater infrastructure.
United States
EPA Long Term 2 Enhanced Surface Water Treatment Rule mandates drive municipal procurement of validated UV-C systems for cryptosporidium inactivation. FDA emergency use authorization pathways for healthcare surface disinfection create regulatory tailwinds for device suppliers. Texas and California water utilities concentrate high-flow reactor installations serving populations above ten thousand.
Germany
REACH substance authorization timelines and ECHA sunset date reviews for mercury compounds tighten supply chain disclosure requirements. BMW and Volkswagen automotive coating lines pilot hybrid arc-LED configurations for energy-responsive curing intensity. Bavarian and Baden-Württemberg manufacturing clusters anchor precision curing demand.
China
MEE environmental discharge regulations mandate UV treatment integration into pharmaceutical and chemical manufacturing wastewater infrastructure. GB standards and dual carbon goals accelerate domestic LED module procurement. Yangtze River Delta industrial parks concentrate effluent treatment capacity expansion.
Japan
METI efficiency standards and JIS certification requirements shape commercial foodservice adoption of mercury-free under-counter disinfection units. Semiconductor fabs in Kyushu and Kansai regions concentrate subscription-based lamp replacement programs. Tokyo metropolitan utilities specify validated UV-C systems for secondary treatment.
India
Smart Cities Mission and AMRUT 2.0 allocations prioritize UV disinfection for secondary treatment in tier-2 municipal utilities with limited chlorination infrastructure. BIS standards and CEA guidelines shape product certification requirements. Maharashtra and Gujarat industrial corridors concentrate pharmaceutical manufacturing effluent treatment demand.
Ultra Violet (UV) Lamps Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with municipal water infrastructure favoring established lamp suppliers while point-of-use applications attract electronics assemblers. The vendor base organizes around three strategic archetypes: mercury vapor legacy specialists with installed-base service capabilities, UV-C LED chip fabricators with captive epitaxy capacity, and hybrid system integrators bridging arc and solid-state architectures. Competitive moves concentrate on technology licensing partnerships and backward integration into quartz sleeve and aluminum nitride substrate supply.
Within the legacy specialist tier, Heraeus Noblelight and Ushio Inc. occupy positions anchored by long-term service contract expertise in European and East Asian semiconductor fab channels. Among LED chip fabricators, Seoul Viosys Co., Ltd. and Nichia Corporation exemplify divergent strategic postures on wavelength optimization and phosphor conversion architectures.
| Leading Market Players |
|---|
| Heraeus Noblelight |
| Nichia Corporation |
| Seoul Viosys Co., Ltd. |
| Philips Lighting |
| Ushio Inc. |
| Atlantic Ultraviolet Corporation |
| ams-OSRAM AG |
| American Ultraviolet |
| STANLEY ELECTRIC CO., LTD. |
| Others |
Value Network & Pricing Analysis
Optical engineering talent scarcity in Germany and Japan concentrates radiometric calibration expertise among aging technician cohorts, widening labor-cost differentials between precision-curing premium tiers and commodity mercury-vapor economy segments. Subscription-based service bundling in Taiwan and South Korean semiconductor fabs compresses transactional price spreads while elevating total contract values.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for UV-C LED modules as domestic epitaxy scale reduces cost-per-milliwatt trajectories. Three-tier pricing structure across premium, standard, and economy levels separates validated healthcare systems with FDA emergency use authorization from unvalidated commercial units and basic mercury-vapor replacements. Pricing pressure stems from aluminum gallium nitride thermal management limitations below 280 nm that preserve mercury-vapor dominance in municipal high-flow applications. Healthcare facilities demonstrate lowest price sensitivity due to Joint Commission accreditation requirements, while residential point-of-use segments exhibit highest elasticity amid consumer education gaps.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from BMW and Volkswagen coating lines, while distributor networks serve tier-2 municipal utilities with limited procurement staff. Manufacturing concentrates in China, Germany, and Japan, with quartz sleeve fabrication anchored in Heraeus's German operations and aluminum nitride substrate supply resting on Japanese ceramic specialists. Raw material dependencies include liquid mercury feedstock from Kyrgyzstan and China, high-purity synthetic quartz, and aluminum gallium nitride wafers. Single-source vulnerability in mercury mining creates geopolitical exposure for legacy lamp manufacturers. Distribution runs through authorized service contractors for semiconductor fab maintenance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mercury phase-out timelines in the European Union and China's dual carbon goals create a geographic-arbitrage window where LED module production in China serves RoHS-compliant demand in Germany at 40% lower labor-adjusted unit costs.
For Market Incumbents: Acquire captive epitaxy capacity to secure aluminum gallium nitride wafer supply against Seoul Viosys's dominant chip fabrication position. Consolidate quartz sleeve production through backward integration into synthetic quartz supply, defending service-contract margins as mercury-vapor installed bases require replacement. RoHS exemption uncertainty demands accelerated LED R&D to preempt grandfathering risk in European municipal tenders. For New Entrants and Emerging Players: Launch via direct-to-utility digital procurement platforms targeting India's tier-2 Smart Cities Mission allocations with validated UV-C systems for cryptosporidium compliance. India's underpenetrated secondary treatment infrastructure offers lowest competitive density among major economies. White-space concentration in pharmaceutical effluent treatment under China's MEE regulations provides secondary entry vector through local EPC partnerships. For Investors and Strategic Acquirers: Industrial water treatment OEMs are the most active acquirer in this space, seeking lamp technology to complete vertical integration in wastewater infrastructure packages. Long-term viability hinges on mercury-phase-out trajectory alignment across multiple regulatory jurisdictions. Acquisition target archetype: UV-C LED module specialists with validated efficacy data and existing semiconductor fab service relationships. Signal to monitor: ECHA sunset date review outcomes for mercury-containing professional equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Nitride Substrates | Captive wafer supply reduces dependency on Japanese ceramic specialists for UV-C LED fabrication. |
| Subscription-Based Service Contract Expansion | Quarterly radiometer calibration bundles with lamp replacement concentrate recurring revenue in Taiwan fab clusters. |
| Hybrid Arc-LED System Development | BMW and Volkswagen pilot configurations unify process control architectures for energy-responsive curing intensity. |
| India Water Infrastructure Partnership | AMRUT 2.0 allocations in Maharashtra and Gujarat create validated system procurement pathways for tier-2 utilities. |
| Healthcare Surface Disinfection Certification | FDA emergency use authorization pathways accelerate hospital procurement during respiratory pandemic periods. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal water utility procurement officers, semiconductor fab maintenance directors, automotive coating line engineers, and healthcare infection control specialists with secondary validation through EPA Long Term 2 rule filings, ECHA substance authorization databases, China's MEE discharge regulation updates, and SEC 10-K disclosures from listed lamp manufacturers. Bottom-up segment sizing and top-down macro constraint checks ensured cross-verification across the analysis window.
Segment-weighting approaches distributed value estimates across mercury-vapor versus LED product types, water purification versus material curing versus surface disinfection applications, and healthcare versus industrial versus municipal end-user categories. CAGRs were derived from installed-base replacement cycles, regulatory compliance deadlines, and technology substitution elasticity parameters. Forecast inputs incorporated aluminum gallium nitride epitaxy cost curves, mercury supply concentration risk premiums, and REACH authorization timeline probabilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated RoHS exemption withdrawal or breakthrough thermal management advances in sub-280 nm LED architectures. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
India Lighting Market
Lighting
Studio Lighting Equipment Market
Lighting
Solid State Lighting System Market
Lighting
EV Lighting Market
Lighting
Specialty Lighting Market
Lighting
Street and Roadway Lighting Market
Lighting
Fluorescent Lighting Market
Lighting
Directional Luminaire Market
Lighting
Global Headlight Control Module Market
Lighting
Bulb Market
Lighting
Wireless Lighting Market
Lighting
Malaysia LED Lighting Controllers Market
Lighting
Dimmer and Color Tunable Market
Lighting
Recessed Lighting Market
Lighting
Explosion Proof Lighting Market
Lighting
Portable Lamps Market