
 UV-C LED Market | 2026-2036
UV-C LED Market Size, Share, and Industry Trends Forecast 2026-2036
UV-C LED Market Analysis
Japanese LED epitaxy houses are repositioning their wafer capacity toward deep-ultraviolet wavelengths as mercury lamp phase-outs accelerate under the Minamata Convention. Seoul Viosys leverages its vertical LED foundry model to control substrate sourcing and epitaxial growth for 275 nm devices. Crystal IS anchors North American supply through its native aluminum nitride substrate technology, while Nichia Corporation dominates high-efficiency single-chip outputs for point-of-use water systems.
UV-C LED denotes semiconductor devices emitting ultraviolet-C radiation at wavelengths between 200 and 280 nanometers, typically fabricated from aluminum gallium nitride (AlGaN) heterostructures on sapphire or aluminum nitride substrates to achieve germicidal action through photochemical damage to pathogen DNA and RNA. Water treatment applications lead installed value due to retrofit demand across municipal infrastructure, while surface disinfection in healthcare facilities posts the fastest uptake as hospitals replace mercury-vapor systems with solid-state alternatives. AlGaN technology captures the dominant share of structural margin as substrate quality and p-type doping efficiency separate commercial viability from laboratory performance.
The U.S. EPA and FDA jointly shape product validation requirements for UV-C LED systems deployed in drinking water and medical device sterilization, with NSF/ANSI 55 certification serving as the primary gateway for consumer-facing claims. Europe's ECHA enforcement of RoHS mercury restrictions and the EU Green Deal's circular economy mandates are compressing timelines for mercury-free transitions across industrial sterilization equipment. Stakeholders must monitor wavelength-specific efficacy data against emerging pathogen variants and evolving photobiological safety standards from IEC before committing to platform designs.
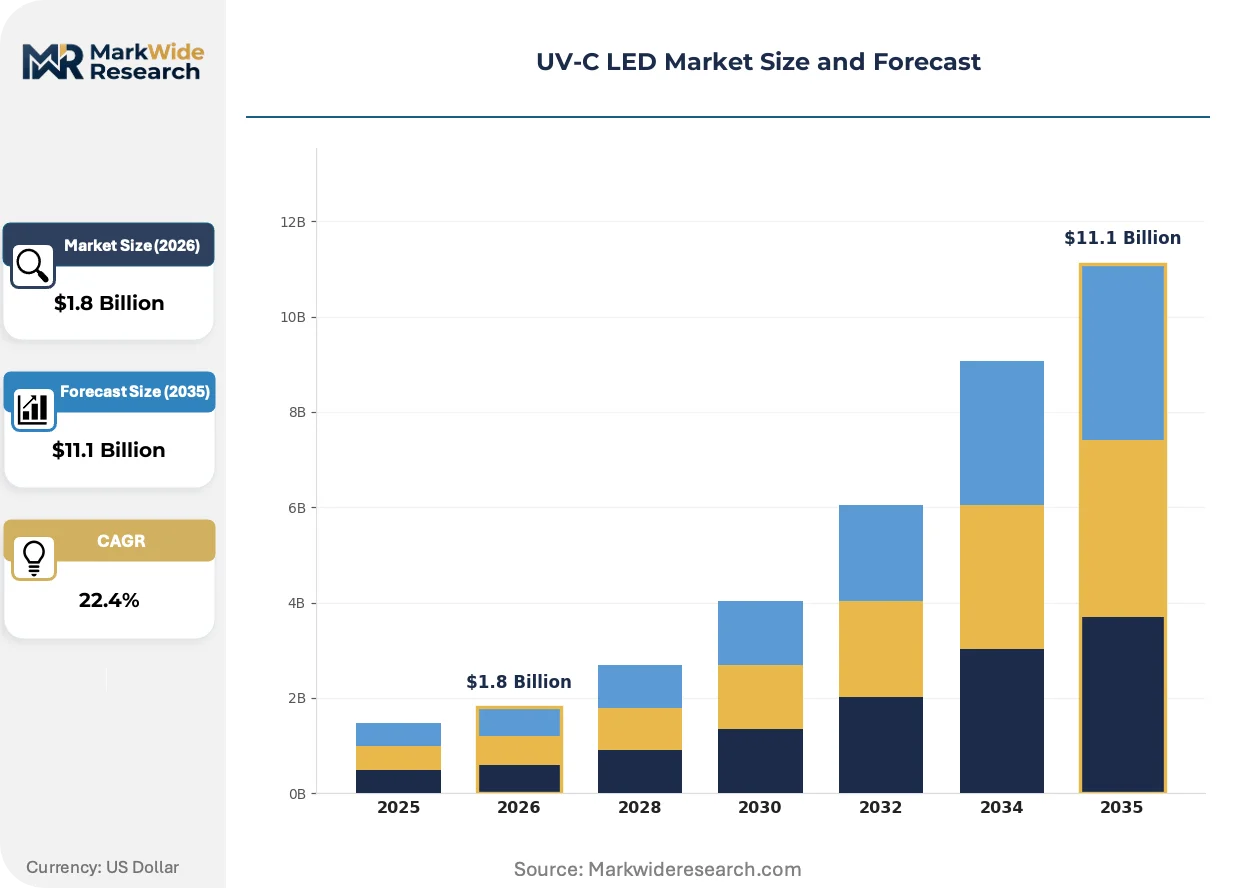
Market Dynamics
The Minamata Convention's mercury phase-out deadlines are compressing replacement cycles for legacy disinfection infrastructure, forcing capital allocation toward solid-state alternatives before 2027 enforcement windows.
Growth Catalysts
- Minamata Convention compliance:Binding international mercury restrictions are mandating lamp replacements across municipal water treatment plants and medical sterilization equipment.
- AlGaN epitaxy maturation:Advances in p-type doping efficiency and native aluminum nitride substrate quality are pushing wall-plug efficiency above 10% for 275 nm devices.
- Point-of-use water systems:Residential and commercial under-sink installations are expanding as NSF/ANSI 55 certification validates germicidal claims for consumer markets.
Market Restraints
- Substrate cost concentration:High-purity aluminum nitride wafers remain captive to limited Japanese and North American suppliers, inflating input costs for 265-285 nm device fabrication.
- Wall-plug efficiency gap:UV-C LEDs deliver 3-10% electrical-to-optical conversion versus 30-40% for medium-pressure mercury lamps, extending payback periods for high-volume industrial users.
- Thermal management complexity:Junction temperatures above 85°C degrade AlGaN quantum well output, requiring sophisticated heat sink integration that elevates system-level BOM costs.
Strategic Opportunities
- Healthcare HVAC retrofits:Upper-room air disinfection installations in hospitals and long-term care facilities present uncaptured volume as ASHRAE guidance prioritizes pathogen mitigation.
- EU Green Deal circularity mandates:RoHS enforcement and extended producer responsibility frameworks are accelerating mercury-free procurement timelines for industrial sterilization OEMs.
- Photocatalytic surface integration:Pairing UV-C emitters with titanium dioxide coatings enables continuous self-cleaning functionality for high-touch transit and retail environments.
Industry Challenges
- AlGaN epitaxy talent scarcity:Deep-UV device physics expertise concentrates among a narrow cohort of researchers trained at specific Japanese and American semiconductor programs.
- IEC 62471 photobiological certification:Wavelength-specific risk group classifications for skin and eye exposure are extending product validation timelines by 8-14 months for new form factors.
- Legacy ballast infrastructure:Mercury lamp replacement cycles must coordinate with existing electrical infrastructure that lacks compatibility with LED driver electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV-C LED Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Disinfection, Air Purification, Water Treatment, Medical Equipment Technology: InGaN, AlGaN, Gallium Nitride, Lithium Niobate Application: HVAC Systems, Food Processing, Laboratory Sterilization, Healthcare Facilities End User: Residential, Commercial, Industrial, Healthcare Providers |
| Companies Covered | ams-OSRAM AG, STANLEY ELECTRIC, Nichia Corporation, Silanna UV, AquiSense Technologies, Seoul Viosys, LG Innotek, Phoseon Technology, Crystal IS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV-C LED Market Emerging Trajectories
AlGaN-on-AlN substrate architectures are overtaking sapphire-based platforms as the dominant technical pathway, while regulatory enforcement tightens and procurement models favor certified system integrators over component vendors.
Single-chip UV-C emitters fabricated on native aluminum nitride substrates are overtaking sapphire-based alternatives in high-dose applications. Municipal water utilities in Germany and Japan are specifying AlN-substrate modules for their superior thermal conductivity and extended operational lifetime. This substrate transition is overtaking cost-sensitive designs in premium segments where 10,000-hour L70 maintenance is non-negotiable.
REACH Annex XVII mercury restrictions and RoHS recast directives are eliminating mercury lamp exemptions for industrial sterilization equipment across EU member states. German and Italian sterilization OEMs are redesigning product platforms to accommodate UV-C LED optical engines ahead of 2027 enforcement. Medical device manufacturers are prioritizing CE-MDR conformity routes that incorporate solid-state disinfection to preempt regulatory obsolescence.
System-level procurement is displacing component sourcing as NSF/ANSI 55 and EPA UV guidance validation become mandatory for municipal and healthcare tenders. Water treatment engineering firms are bundling LED modules with sensor feedback and IoT monitoring rather than specifying bare emitters. This integration preference is most pronounced in California and Texas municipal procurement, where total-cost-of-ownership metrics dominate capex minimization.
UV-C LED Market Segmentation
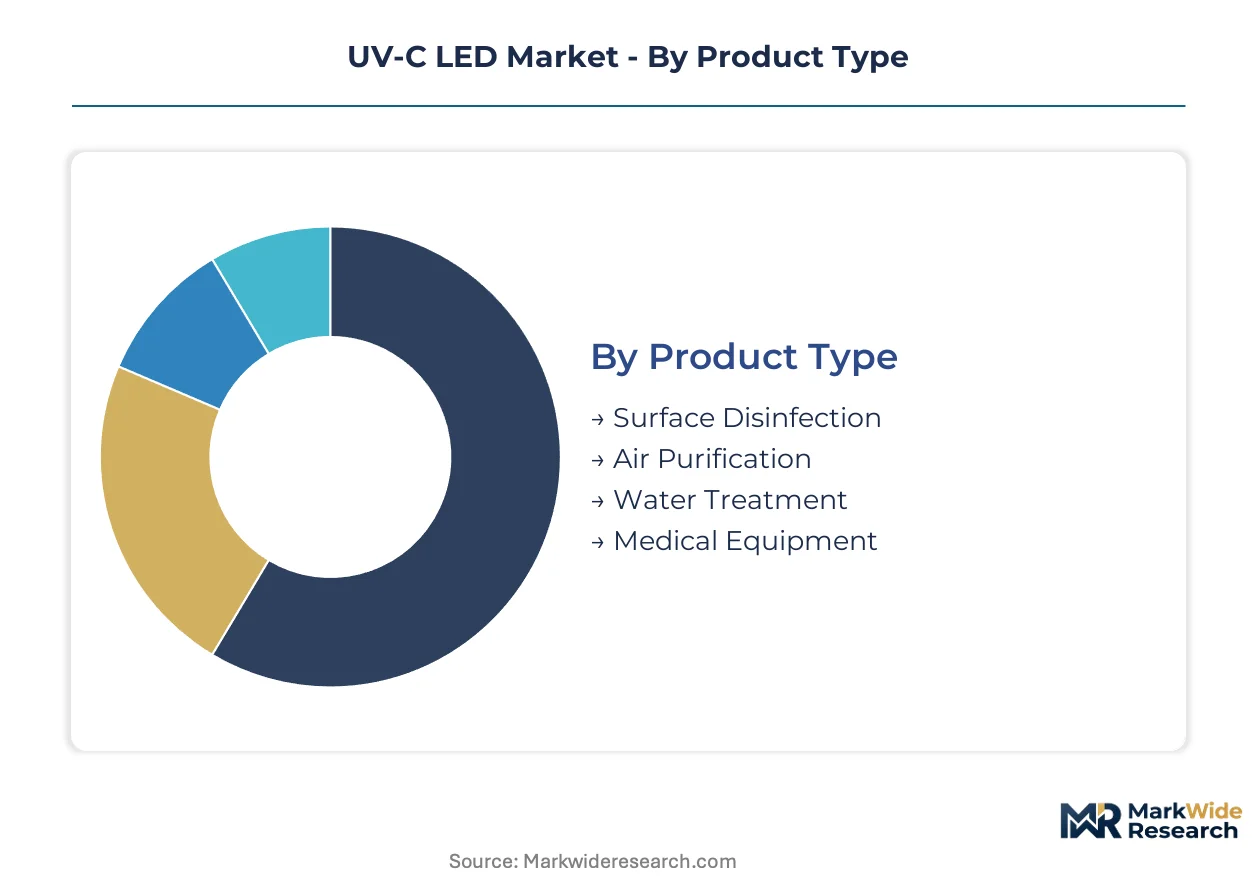
UV-C LED procurement patterns diverge sharply across application contexts, with municipal water utilities prioritizing certified system longevity while healthcare facilities emphasize rapid deployment cycles. Technology selection and end-user economics create distinct margin architectures that reshape competitive positioning across each segment boundary.
Product Type:
Supply concentration in AlGaN epitaxy capacity tilts procurement leverage toward module integrators who can guarantee wavelength-specific efficacy documentation.
- Water Treatment:Municipal utilities in Germany and Japan specify AlN-substrate modules for 10,000-hour L70 maintenance in high-dose disinfection infrastructure. REACH Annex XVII and Minamata Convention deadlines compress replacement timelines for mercury lamp retrofits across European and North American treatment plants.
- Surface Disinfection:Healthcare facilities in Texas and California replace mercury-vapor systems with solid-state alternatives for point-of-use sterilization. ASHRAE guidance on pathogen mitigation and FDA validation requirements for medical device sterilization accelerate procurement cycles.
- Air Purification:Upper-room installations in long-term care facilities gain traction under revised ventilation standards.
- Medical Equipment:CE-MDR conformity routes favor integrated optical engines over component sourcing for sterilization OEMs.
Water treatment absorbs the bulk of installed capacity; surface disinfection is expanding most quickly.
Technology:
Cost tier differentiation separates laboratory-grade performance from commercial viability, with substrate quality and p-type doping efficiency determining which platforms achieve production scale.
- AlGaN:Native aluminum nitride substrates deliver superior thermal conductivity for 275 nm emitters, though high-purity wafer supply concentrates among limited Japanese and North American foundries. Wall-plug efficiency above 10% now separates premium municipal specifications from cost-sensitive designs.
- Gallium Nitride:Broader wavelength tunability supports multi-emitter arrays for industrial sterilization equipment requiring variable dose protocols.
- InGaN:Near-UV variants face efficacy limitations below 280 nm for germicidal applications.
- Lithium Niobate:Nonlinear optical conversion pathways remain experimental for deep-UV generation.
AlGaN captures the dominant technology margin; Gallium Nitride is climbing the fastest as industrial OEMs redesign for wavelength flexibility.
Application:
Volume concentration in HVAC retrofits reflects ASHRAE guidance prioritization, while laboratory and food processing segments demand specialized certification pathways.
- HVAC Systems:Upper-room air disinfection in hospitals and transit infrastructure posts steep uptake as California and Texas municipalities bundle LED modules with IoT monitoring. Thermal management complexity at junction temperatures above 85°C elevates system-level BOM costs for continuous-operation designs.
- Healthcare Facilities:Surface and air sterilization in acute care settings requires IEC 62471 photobiological certification extending validation timelines.
- Food Processing:NSF/ANSI 55 certification gates consumer-facing germicidal claims for packaging and surface treatment.
- Laboratory Sterilization:Research-grade specifications prioritize wavelength precision over cost optimization.
HVAC systems absorb the bulk of installed capacity; healthcare facilities are gaining share fastest on regulatory tailwinds.
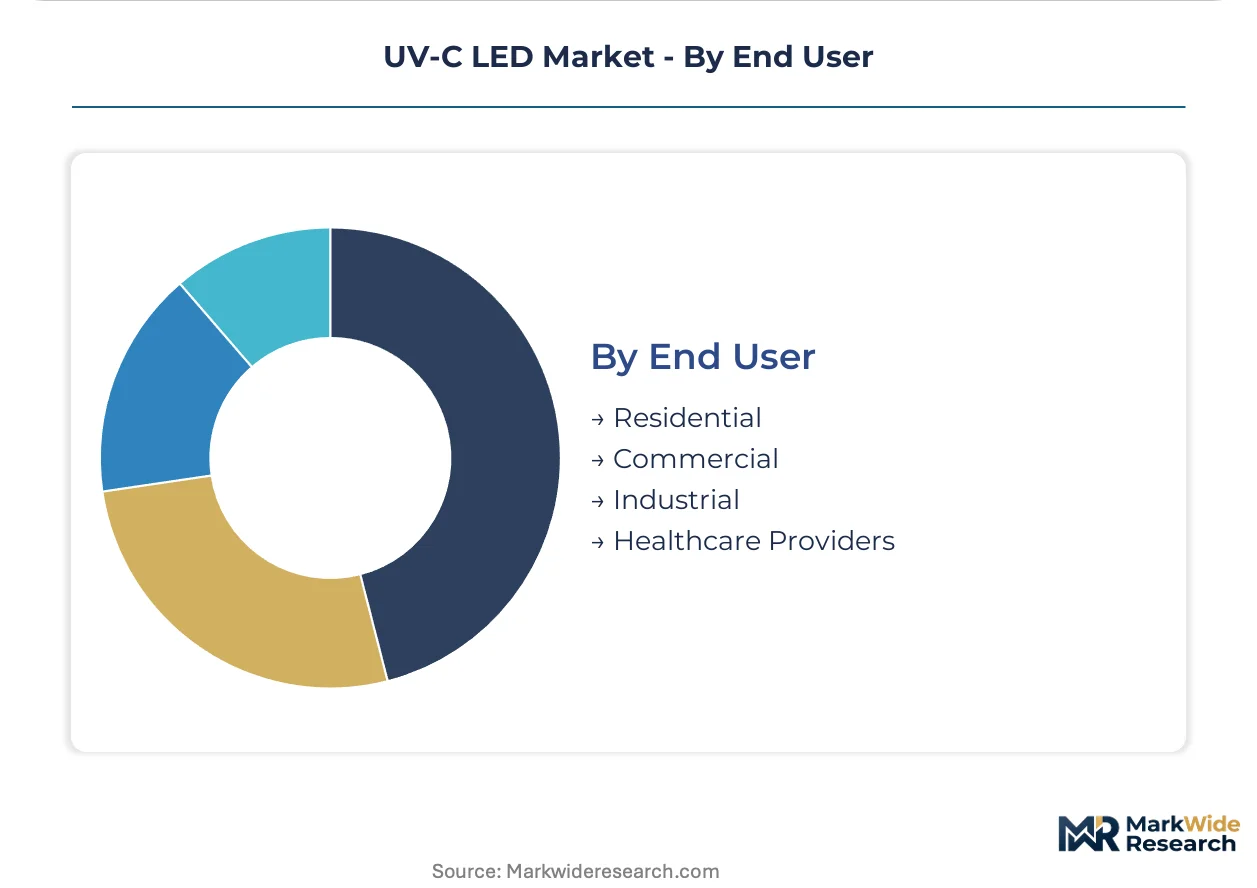
End User:
Customer type determines procurement modality, with industrial buyers negotiating total-cost-of-ownership metrics while residential segments remain certification-constrained.
- Industrial:Municipal water utilities and sterilization OEMs in Germany and Italy specify AlN-substrate modules ahead of RoHS enforcement windows. Extended producer responsibility frameworks under the EU Green Deal accelerate mercury-free platform transitions.
- Healthcare Providers:Hospital systems in California prioritize CE-MDR and FDA-validated systems for liability protection.
- Commercial:Under-sink point-of-use systems expand where NSF/ANSI 55 validation supports consumer marketing claims.
- Residential:Price sensitivity limits penetration to premium segments pending wall-plug efficiency improvements.
Industrial end users absorb the bulk of installed capacity; healthcare providers are expanding most quickly on infection control mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum nitride substrate supply concentrates in Japanese and North American foundries, anchoring regional competitive positioning. China scales AlGaN epitaxy capacity for export markets. European REACH enforcement accelerates mercury-free transitions.
United States
Municipal water utilities in California and Texas specify AlN-substrate modules for 10,000-hour L70 maintenance. EPA UV guidance and NSF/ANSI 55 certification gate consumer-facing germicidal claims. Crystal IS anchors North American supply through native aluminum nitride substrate technology.
Japan
Japanese LED epitaxy houses reposition wafer capacity toward deep-ultraviolet wavelengths. METI enforces Minamata Convention mercury phase-out deadlines ahead of 2027 windows. Nichia Corporation dominates high-efficiency single-chip outputs for point-of-use water systems from Kansai manufacturing clusters.
Germany
German sterilization OEMs redesign product platforms for UV-C LED optical engines. ECHA REACH Annex XVII and RoHS recast directives eliminate mercury lamp exemptions for industrial equipment. Municipal water utilities specify AlN-substrate modules for high-dose disinfection infrastructure across Bavaria and North Rhine-Westphalia.
China
Domestic LED foundries scale AlGaN epitaxy capacity for export markets. SAMR and MEE align national standards with Minamata Convention compliance timelines. Yangtze River Delta clusters concentrate module assembly for water treatment and surface disinfection applications.
South Korea
Seoul Viosys leverages vertical LED foundry models to control substrate sourcing and epitaxial growth. MFDS medical device regulations prioritize solid-state disinfection for CE-MDR conformity routes. Busan-Ulsan industrial corridors host packaging and module integration facilities.
UV-C LED Market Vendor Landscape
Global majors compete with regional champions across substrate technology and wavelength precision. The vendor base separates into three tiers: integrated foundries controlling epitaxy-to-module pipelines, specialized substrate developers, and system integrators bundling emitters with IoT monitoring. Dominant competitive moves include backward integration into aluminum nitride wafer supply and strategic partnerships with municipal engineering firms.
Among Japanese and South Korean fabricators, Nichia Corporation, Seoul Viosys, and LG Innotek exemplify the integrated foundry archetype. North American specialists Crystal IS and ams-OSRAM AG occupy positions anchored by native substrate technology. AquiSense Technologies and Phoseon Technology represent the system integration tier, bundling UV-C modules with sensor feedback for water treatment utilities.
| Leading Market Players |
|---|
| ams-OSRAM AG |
| STANLEY ELECTRIC |
| Nichia Corporation |
| Silanna UV |
| AquiSense Technologies |
| Seoul Viosys |
| LG Innotek |
| Phoseon Technology |
| Crystal IS |
| Others |
Supply Flow & Price Mechanics
High-purity aluminum nitride wafer pricing cascades through UV-C LED supply chains into three distinct procurement tiers, with substrate costs compressing margins for mid-range module integrators while premium AlN-on-AlN architectures command sustained premiums from municipal utilities.
Pricing Analysis
Warranty bundling separates premium municipal specifications from unbundled component sales to OEMs, with 10,000-hour L70 guarantees standard in German and Japanese utility contracts but absent in spot-market transactions. Three-tier pricing structure across certified-system, module-only, and bare-emitter levels reflects NSF/ANSI 55 validation tiers and thermal management complexity. Cost compression in mid-range modules is intensifying because Chinese foundries are scaling AlGaN epitaxy capacity for export markets. Residential point-of-use buyers exhibit highest price sensitivity, while industrial sterilization OEMs in Italy and Germany prioritize total-cost-of-ownership metrics over upfront capex.
Supply Chain Analysis
Domestic-content mandates under China's 14th Five-Year Plan and South Korea's K-Chips Act are reshaping sourcing patterns for critical substrate materials. Manufacturing concentrates in Japan, the United States, and China, with high-purity AlN wafers drawing from limited Japanese and North American foundry capacity. Raw material dependencies center on ammonia feedstock for nitride synthesis, sapphire substrates for cost-sensitive designs, and precious-metal catalysts for epitaxial growth. Single-source vulnerability in AlN wafer supply elevates procurement risk for 275 nm device fabricators. Distribution runs through system integrators bundling emitters with IoT monitoring rather than direct component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
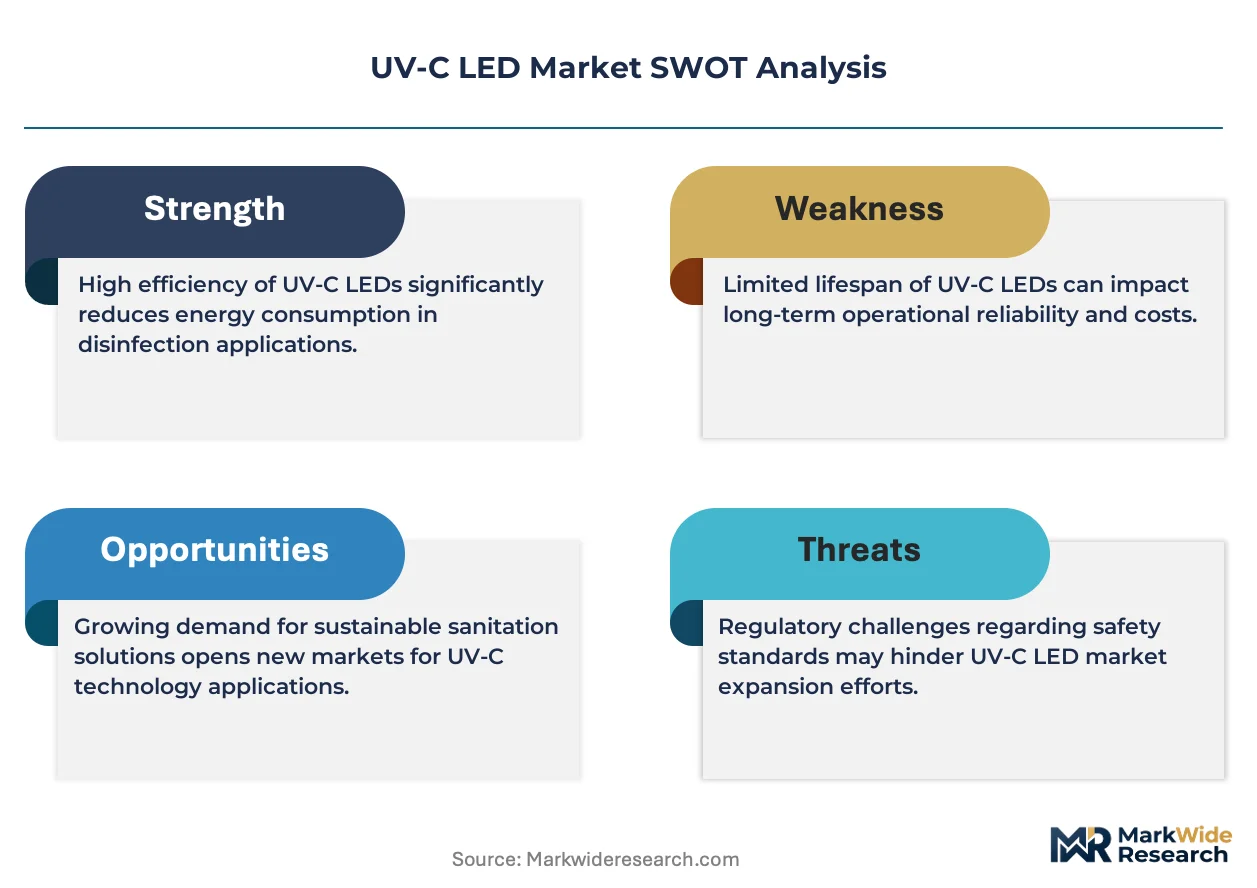
The UV-C LED market functions as a vertical-integration race where captive control over aluminum nitride substrate supply determines margin capture, with backward integration into wafer production emerging as the decisive competitive lever.
For Market Incumbents: Cement dominance by locking exclusive supply agreements with Japanese AlN wafer foundries before 2027 Minamata Convention enforcement windows close. Acquire specialized AlGaN epitaxy talent pools concentrated at specific American and Japanese semiconductor programs to preempt competitor hiring. Prioritize CE-MDR and FDA validation pathways for integrated optical engines to forestall modular component commoditization.
For New Entrants and Emerging Players: Begin with healthcare HVAC retrofit opportunities in Texas and California municipalities where ASHRAE guidance and bundled procurement models favor new system integrators over established component vendors. Target upper-room air disinfection in long-term care facilities as the most penetrable application segment, exploiting validation timeline gaps for emerging form factors. Pursue partnership-based go-to-market strategies with water treatment engineering firms rather than direct emitter sales.
For Investors and Strategic Acquirers: The window for entry favors mid-cap substrate developers with native AlN technology and existing epitaxy partnerships. Long-term viability hinges on mercury lamp replacement cycle timing across European and North American industrial sterilization infrastructure. Acquisition target archetype: specialized AlGaN foundries with p-type doping IP and municipal certification track records. Watch IEC 62471 photobiological certification timeline compression as the signal for competitive inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into AlN Substrate Supply | Captive wafer production secures margin capture against Japanese foundry concentration. |
| NSF/ANSI 55 Certification Investment | Validation gates consumer-facing germicidal claims in California and Texas municipal tenders. |
| Healthcare HVAC System Partnership | ASHRAE guidance prioritization creates procurement volume in hospital infrastructure retrofits. |
| AlGaN Epitaxy Talent Acquisition | Deep-UV device physics expertise concentrates among narrow cohorts of Japanese and American researchers. |
| IoT Monitoring Platform Integration | Bundled sensor feedback displaces bare emitter sourcing in system-level procurement. |
Methodological Framework
Multi-period observation of AlGaN epitaxy capacity announcements, Minamata Convention enforcement timelines, and municipal procurement award patterns anchored the trend analysis, supplemented by interviews with LED foundry operations directors, water treatment utility procurement managers, sterilization OEM platform engineers, and ECHA regulatory affairs specialists. Secondary validation drew from EPA UV guidance documents, REACH Annex XVII restriction updates, NSF/ANSI certification databases, and SEC filings of listed LED manufacturers. Bottom-up module shipment estimates triangulated against top-down municipal capital expenditure projections.
Input-output matrices mapped AlN substrate supply through epitaxial growth, device packaging, and system integration stages across the modeling period. Segmentation dimensions modeled include application context, substrate technology tier, end-user procurement modality, and regional regulatory cluster. CAGRs derived from curve-fitting against historical mercury lamp replacement cycles and enforcement deadline impacts. Industry-specific forecast inputs incorporated p-type doping efficiency trajectories and thermal management cost curves.
Underlying measurement precision varies by segment; water treatment and healthcare HVAC applications carry tighter precision than emerging photocatalytic surface integration categories. Forecasts reflect documented assumptions regarding Minamata Convention compliance timelines, AlGaN wall-plug efficiency improvement rates, and REACH enforcement uniformity across EU member states. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Linear LED Strip Fixture Market
LED
LED Display Market
LED
LED Power Supplies Market
LED
Mini LED Market
LED
LED Encapsulation Market
LED
Germany LED Lighting Market
LED
High-Brightness LED Market
LED
Led Video Walls Market
LED
Japan Outdoor LED Lighting Market
LED
Global Waterproof LED Module Market
LED
LED Panel Market
LED
Infrared (IR) LED Market
LED
Organic Light Emitting Diode (OLED) Market
LED
China LED Market
LED
LED Lamp Market
LED
Japan LED Lighting Market