
 Global Plasma Lamp Market | 2026-2036
Global Plasma Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plasma Lamp Market Outlook
Aftermarket service revenue for plasma lamp retrofits and spectral recalibration is rewriting margin distribution across the value chain. Ushio Inc. leverages its deep ultraviolet expertise to anchor premium industrial applications. Ceravision Limited competes through specialized microwave-driven plasma architectures. Hive Lighting Inc. differentiates by dominating film and broadcast entertainment segments with tunable full-spectrum output.
Plasma lamps generate illumination by ionizing noble gases within an electrodeless quartz envelope using radio-frequency or microwave energy, producing intense broad-spectrum light with color temperatures ranging from daylight to customized horticultural spectra. The technology serves industrial curing, greenhouse horticulture, and specialized entertainment lighting where spectral precision outweighs conventional LED economics. Xenon and argon product types lead current volume owing to their established supply chains and proven reliability in high-output fixtures. The research institutions end-user category represents the fastest-expanding structural segment as universities and national laboratories deploy plasma sources for photochemistry and materials science. Medium-size lamps occupy the dominant margin pool by balancing unit economics against installation flexibility across commercial and industrial sites.
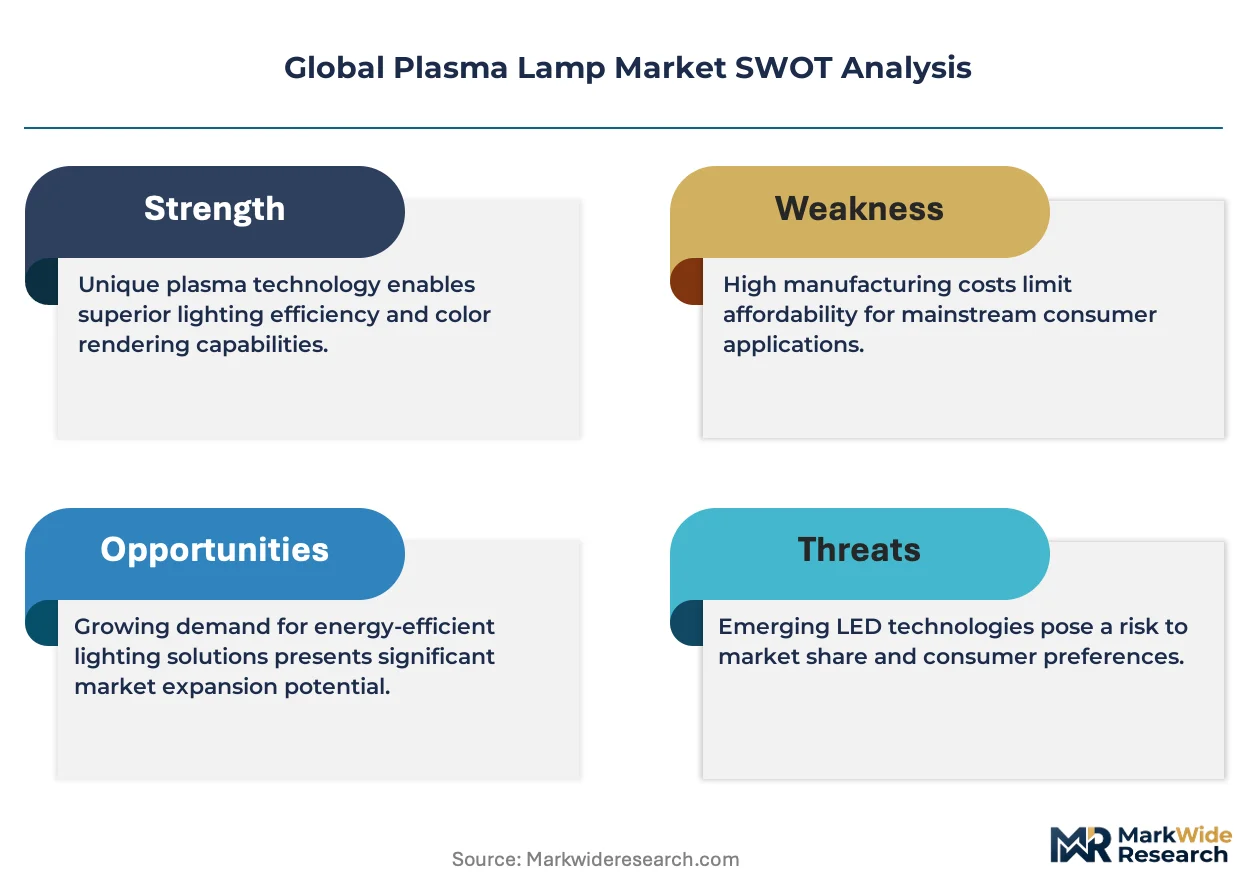
The U.S. EPA Energy Star program and California Title 20 appliance efficiency standards shape product development trajectories for plasma lamp manufacturers seeking North American market access. Ecodesign requirements under the EU Green Deal and RoHS substance restrictions compel reformulation of lamp envelopes and driver electronics for European commercialization. China's GB standards for electromagnetic compatibility and the MIIT's radio-frequency equipment certifications govern import pathways into that market. Stakeholders must monitor evolving spectral efficacy benchmarks and regional RF licensing frameworks as plasma technology encroaches on LED-dominated application spaces.
Market Dynamics
Controlled-environment agriculture operators are forcing plasma lamp manufacturers to reconfigure spectral output specifications as horticultural installations scale beyond research pilots into commercial greenhouse operations.
Growth Catalysts
- EU Green Deal Ecodesign mandates:Energy-efficiency requirements for lighting products are accelerating technology transitions away from legacy high-pressure sodium systems in European commercial horticulture.
- Photochemistry research expansion:Universities and national laboratories are deploying plasma sources for materials science applications, creating sustained demand for precision spectral instruments.
- Film and broadcast production:Entertainment lighting directors are specifying tunable full-spectrum plasma fixtures to replace tungsten and HMI sources on high-budget productions.
Market Restraints
- Quartz envelope supply concentration:High-purity fused silica sourcing depends on a limited supplier base concentrated in Germany and Japan, creating input vulnerability.
- LED substitution economics:Solid-state lighting continues compressing addressable market space in general illumination where spectral precision is not required.
- RF licensing complexity:Microwave and radio-frequency plasma drivers require equipment certifications under MIIT protocols in China and FCC Part 18 compliance in the United States, extending commercialization timelines.
Strategic Opportunities
- India controlled-environment agriculture:Protected cultivation expansion under national horticulture missions creates untapped demand for supplemental lighting in polyhouse installations.
- Dual carbon policy alignment:China's national emissions targets are incentivizing industrial facility retrofits with high-efficiency plasma curing systems for coatings and adhesives processing.
- Aftermarket spectral recalibration services:Service revenue streams for lamp retrofits and output tuning are emerging as margin contributors distinct from hardware sales.
Industry Challenges
- Electromagnetic compatibility certification:Plasma RF generators must demonstrate compliance with evolving GB standards and regional interference protocols, lengthening product launch cycles.
- Integration with legacy greenhouse control systems:New plasma installations require protocol bridges to connect with existing environmental management platforms in commercial agriculture facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plasma Lamp Market |
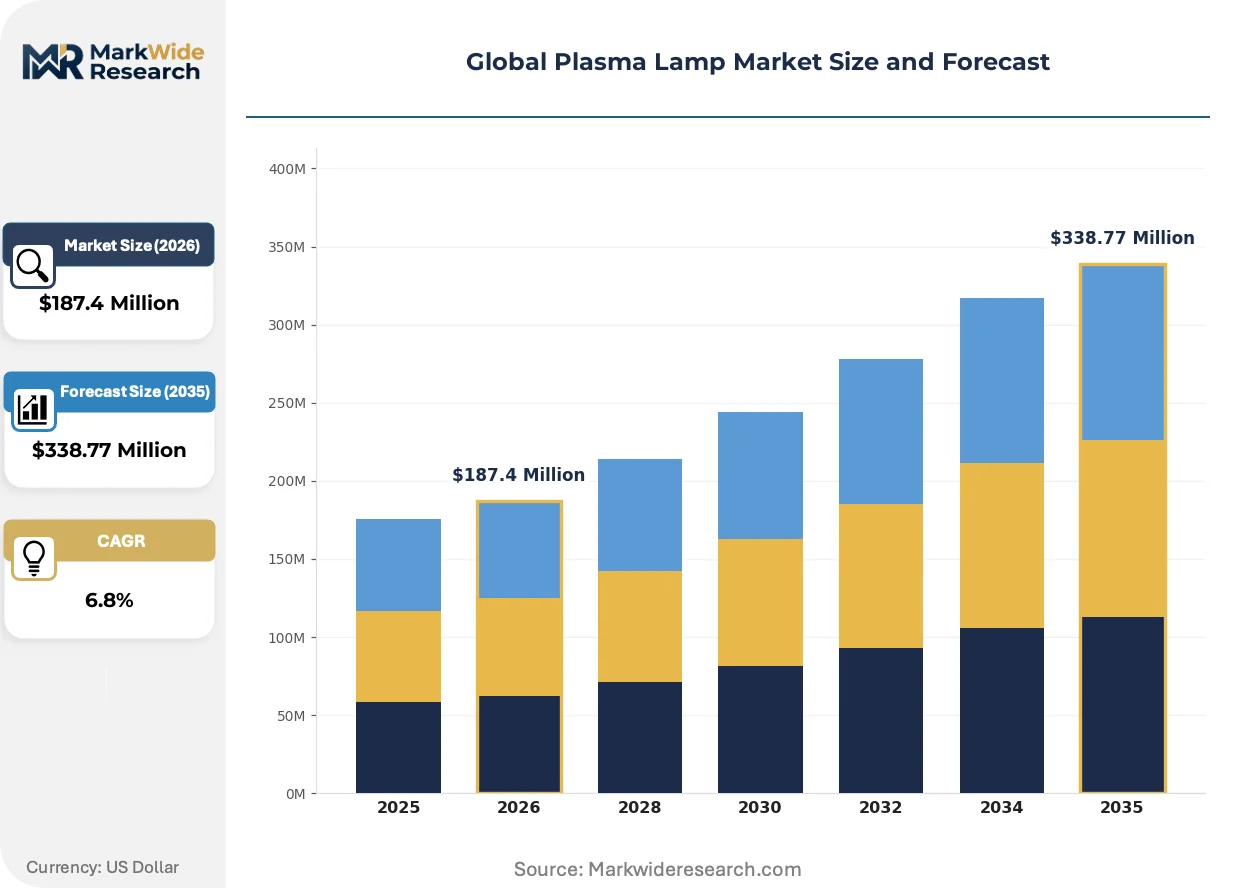
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neon, Xenon, Argon, Krypton End User: Residential, Commercial, Industrial, Research Institutions Application: Lighting, Decorative, Educational, Entertainment Size: Small, Medium, Large, Extra Large |
| Companies Covered | Ushio Inc., ams-OSRAM AG, Gavita International B.V., Hive Lighting Inc., Ka Shui International Holdings Ltd., Ceravision Limited, Pure Plasma Lighting Inc., BIRNS Inc., Ampleon Netherlands BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plasma Lamp Market Strategic Shifts
Spectral engineering and driver miniaturization are compressing the traditional trade-offs between plasma output intensity and installation flexibility that have constrained adoption in space-constrained applications.
Electrodeless microwave-driven plasma architectures are collapsing the gap between laboratory-grade spectral precision and field-deployable fixture economics. Greenhouse operators in the Netherlands and Belgium are piloting these systems for year-round tomato and pepper cultivation. The technology is collapsing capital cost barriers that previously restricted plasma deployment to research and premium entertainment applications.
REACH substance restrictions and RoHS envelope reformulation requirements are forcing manufacturers to eliminate legacy dopants and sealing materials from European-bound products. Industrial lighting OEMs are redesigning driver electronics to accommodate substance compliance without degrading thermal management performance. German and French importers are demanding pre-certified component documentation to accelerate customs clearance.
Buyer procurement patterns are fragmenting as large greenhouse consolidators bypass traditional electrical distributors to negotiate direct fixture and service contracts with plasma specialists. Dutch agribusiness cooperatives are unbundling hardware purchase from spectral calibration and maintenance agreements. This restructuring is most visible in the Rhine-Ruhr corridor where vertically integrated food producers are internalizing lighting system expertise.
Global Plasma Lamp Market Segmentation
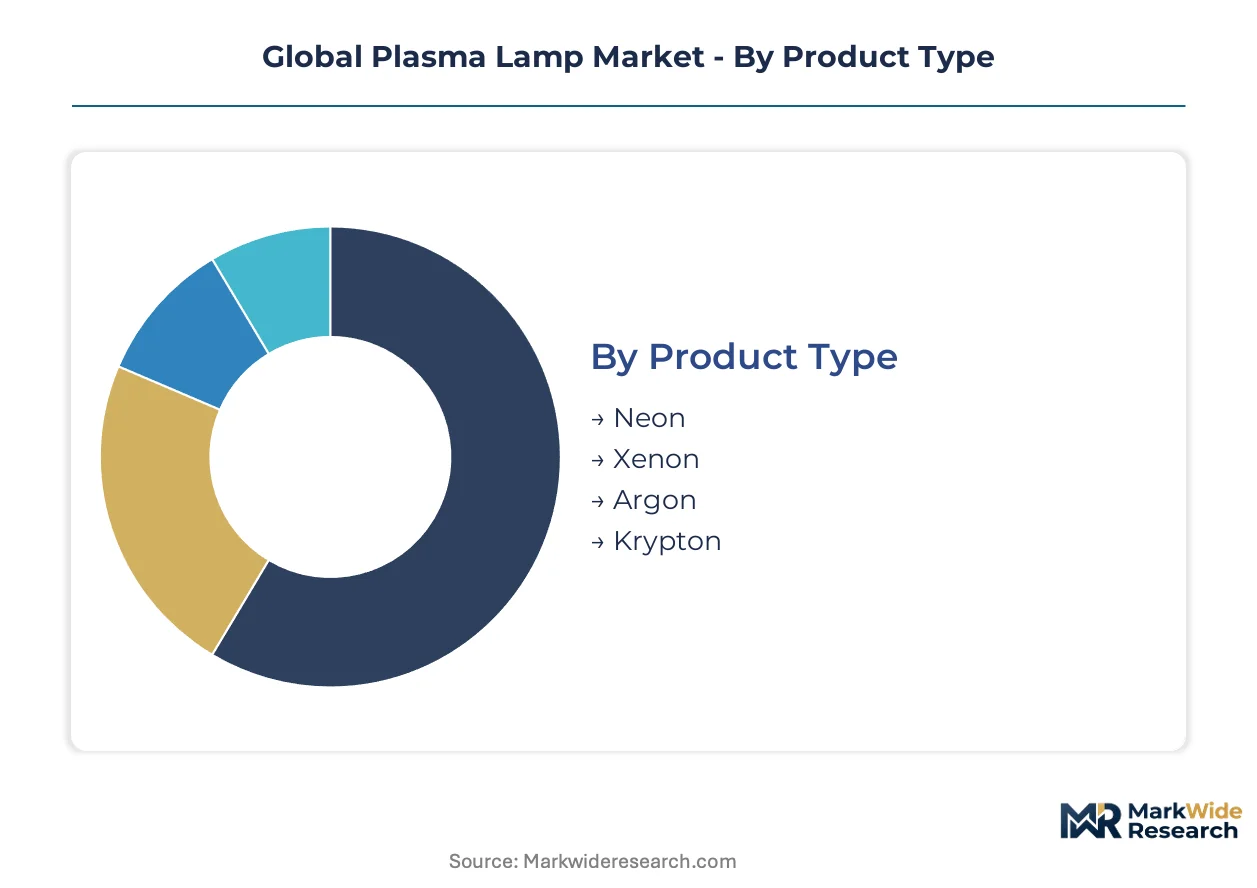
Plasma lamp segmentation reveals how ionization physics, installation scale, and end-use precision requirements fragment addressable demand across radically different value pools. Technical specifications around noble gas selection and envelope dimensions determine whether a fixture serves a research spectrometer or a greenhouse installation.
Product Type:
Mature gas chemistries dominate commercial volume while emerging formulations target specialized spectral applications.
- Xenon:Delivers the highest luminous efficacy among noble gas options with broad continuous spectrum output spanning ultraviolet through infrared. Greenhouse operators in the Netherlands and Belgium specify xenon fixtures for year-round tomato and pepper cultivation where solar supplementation requires precise photosynthetic photon flux density.
- Argon:Offers lower ionization voltage requirements and superior thermal stability in compact electrodeless envelopes. Industrial curing lines in Germany and Japan deploy argon-driven systems for coatings and adhesives processing where electromagnetic interference must stay within FCC Part 18 and MIIT certification limits.
- Neon:Produces distinctive orange-red monochromatic output valued for signage and artistic installations.
- Krypton:Generates high-intensity white light with excellent color rendering for specialized microscopy and inspection applications.
Xenon retains volume leadership; krypton holds the steepest expansion curve.
End User:
Customer archetypes range from price-sensitive residential buyers to institutions demanding spectral calibration certificates.
- Research Institutions:Universities and national laboratories require plasma sources with documented spectral stability for photochemistry and materials science. The EU Green Deal's research funding instruments are accelerating deployment of precision plasma instruments across German, French, and Dutch technical universities.
- Industrial:Manufacturing facilities integrate plasma curing systems into coatings, printing, and semiconductor fabrication lines. China's dual carbon policy targets are incentivizing retrofits with high-efficiency plasma systems for adhesives processing in industrial zones around Shanghai and Shenzhen.
- Commercial:Horticulture operators and entertainment venues balance capital expenditure against operational spectral flexibility.
- Residential:Collectors and enthusiasts purchase plasma fixtures for decorative and ambient lighting applications.
Industrial end users command the dominant margin pool; research institutions are climbing the fastest.
Application:
Use cases separate into functional illumination versus aesthetic or scientific deployment where spectral precision justifies premium economics.
- Lighting:Functional illumination for horticulture and industrial workspaces where photon delivery efficiency outweighs fixture cost. Controlled-environment agriculture operators in the Rhine-Ruhr corridor are unbundling hardware purchase from spectral calibration agreements.
- Entertainment:Film and broadcast production crews specify tunable full-spectrum plasma fixtures to replace tungsten and HMI sources on high-budget productions. Hive Lighting dominates this segment with specialized fixtures for Hollywood and European studio complexes.
- Decorative:Architectural and artistic installations leverage plasma's visual distinctiveness.
- Educational:Secondary and university physics departments deploy plasma lamps for demonstration and laboratory instruction.
Lighting applications retain volume leadership; entertainment holds the steepest expansion trajectory.
Size:
Envelope dimensions determine thermal management complexity and installation flexibility across constrained and open environments.
- Medium:Balances unit economics against installation versatility across commercial greenhouse and industrial sites. Medium-size fixtures occupy the dominant margin pool by serving the broadest addressable application base without requiring specialized structural support.
- Large:Delivers maximum photon flux for stadium-scale horticulture and industrial curing tunnels. Large installations concentrate in Belgian and Dutch agribusiness cooperatives operating multi-hectare greenhouse complexes.
- Small:Fits confined spaces in research instrumentation and portable entertainment rigs.
- Extra Large:Serves specialized industrial curing and scientific applications requiring extreme output density.
Medium size retains volume leadership; large fixtures are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit the lowest price elasticity, prioritizing spectral precision and regulatory compliance over unit economics. Chinese and Indian operators display higher sensitivity, driving procurement toward standardized medium-size fixtures with localized service support.
Germany
Industrial curing applications and greenhouse horticulture dominate German demand, with the Rhine-Ruhr corridor hosting dense clusters of vertically integrated food producers. EU Green Deal Ecodesign mandates under the EU Green Deal framework compel facility retrofits away from legacy sodium systems. Stuttgart and Munich anchor precision manufacturing of RF driver electronics for plasma lamp systems.
United States
Film production studios and research institutions drive premium-tier procurement, with Hive Lighting fixtures specified for Hollywood and European co-productions. EPA Energy Star certification and California Title 20 efficiency standards shape product development trajectories for manufacturers seeking market access. Greater Los Angeles and Boston-Worcester corridors concentrate entertainment lighting deployment and photochemistry research installations respectively.
Japan
Industrial semiconductor fabrication and materials science research sustain demand for high-stability plasma sources with documented spectral calibration. METI energy-efficiency guidelines and JIS standards govern product commercialization pathways. Osaka-Kobe industrial zone hosts major manufacturing clusters for electrodeless quartz envelope production.
China
Dual carbon policy targets incentivize industrial facility retrofits with high-efficiency plasma curing systems for coatings processing in Shanghai and Shenzhen industrial zones. MIIT radio-frequency equipment certifications and GB electromagnetic compatibility standards extend commercialization timelines for imported driver electronics. Yangtze River Delta greenhouse operators are piloting microwave-driven architectures for year-round vegetable cultivation.
Netherlands
Commercial greenhouse operators in the Randstad and Brabant regions unbundle hardware procurement from spectral calibration and maintenance agreements. Dutch agribusiness cooperatives negotiate direct fixture contracts, bypassing traditional electrical distribution channels. Wageningen University research partnerships accelerate pilot deployments for tomato and pepper cultivation under supplemental lighting.
Global Plasma Lamp Market Competitive Environment
Capability concentration sits with specialized microwave-driven and ultraviolet-expertise tiers; scale advantage sits with diversified lighting conglomerates and industrial electronics manufacturers. The vendor base stratifies across three functional archetypes: noble gas chemistry specialists, RF driver electronics fabricators, and horticultural lighting system integrators. Dominant competitive moves include backward integration into high-purity fused silica sourcing and technology licensing partnerships for electromagnetic compatibility certification acceleration.
Within the specialized technology tier, Ushio Inc. and Ceravision Limited exemplify contrasting architectural approaches to electrodeless plasma generation, while Hive Lighting Inc. occupies a distinct position in entertainment-focused fixture design. These three companies represent the spectrum from industrial ultraviolet applications through microwave-driven systems to tunable full-spectrum broadcast lighting. Ampleon Netherlands BV and ams-OSRAM AG sit within the semiconductor and optoelectronics fabricator tier, supplying critical RF power components and light engine subsystems. Gavita International B.V. anchors the horticultural system integrator archetype, bridging plasma hardware with greenhouse environmental control platforms.
| Leading Market Players |
|---|
| Ushio Inc. |
| ams-OSRAM AG |
| Gavita International B.V. |
| Hive Lighting Inc. |
| Ka Shui International Holdings Ltd. |
| Ceravision Limited |
| Pure Plasma Lighting Inc. |
| BIRNS Inc. |
| Ampleon Netherlands BV |
| Others |
Value Chain & Pricing Dynamics
Osaka-Kobe industrial zone capacity dynamics directly shape downstream pricing power for electrodeless quartz envelopes, as high-purity fused silica output constraints ripple through RF driver electronics and complete fixture assemblies. German and Japanese buyers absorb premium pricing for documented spectral calibration certificates, while Chinese and Indian operators negotiate standardized medium-size fixtures with localized service support.
Pricing Analysis
Aftermarket spectral recalibration and extended maintenance contracts drive lifetime value across the plasma lamp installed base. Three-tier pricing structure across premium, standard, and economy levels separates research-grade instruments with calibration documentation from commercial greenhouse fixtures and basic industrial curing systems. Cost compression in the standard tier intensifies because LED substitution economics constrain addressable market space for general illumination applications. Research institutions exhibit the lowest price sensitivity, prioritizing spectral precision and regulatory compliance over unit economics, while residential collectors and Indian polyhouse operators display the highest sensitivity.
Supply Chain Analysis
Export-control regimes governing radio-frequency power components limit technology flows from Dutch and German fabricators to Chinese system integrators, lengthening procurement cycles for microwave-driven plasma architectures. High-purity fused silica sourcing draws from Germany, Japan, and limited US suppliers, creating input concentration around noble gas ionization envelopes and thermal management substrates. Single-source vulnerability runs through the quartz envelope tier, where three suppliers control semiconductor-grade material certification. Distribution runs through direct fixture contracts with greenhouse consolidators and specialized industrial electronics distributors, bypassing traditional electrical wholesale channels in the Rhine-Ruhr corridor and Randstad regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plasma lamp market tracks a cyclical recovery pattern driven by controlled-environment agriculture capital expenditure cycles, as greenhouse operators refresh supplemental lighting installations following EU Green Deal mandate compliance waves.
For Market Incumbents: Pre-empt LED encroachment into horticultural applications by accelerating backward integration into high-purity fused silica sourcing and securing captive supply of electrodeless quartz envelopes. Lock in long-term spectral calibration service contracts with Dutch agribusiness cooperatives before emerging RF driver specialists capture aftermarket revenue. Defensive patent positioning around microwave-driven architectures limits Ceravision-class entrants from scaling beyond research pilots.
For New Entrants and Emerging Players: Pursue India's protected cultivation expansion under national horticulture missions, where polyhouse installations lack established plasma lighting suppliers and price sensitivity favors localized service models. Target film and broadcast production white-space in European studio complexes outside Hive Lighting's Hollywood-centric footprint. Lead with tunable full-spectrum fixtures bundled with protocol bridges for legacy greenhouse control system integration.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty industrial components play because plasma lamp technology will not displace LED economics in general illumination but will defend premium niches requiring spectral precision. Acquisition candidates include microwave-driven plasma specialists with MIIT certification progress and horticultural system integrators with unbundled service revenue streams. Watch for inflection when Indian polyhouse operators scale beyond pilot deployments into commercial volume procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Envelope Supply | Captive sourcing from Osaka-Kobe suppliers eliminates single-source vulnerability for RF driver manufacturers. |
| MIIT Certification Acceleration | Early compliance with China's radio-frequency equipment protocols unlocks Yangtze River Delta industrial zone demand. |
| Spectral Calibration Service Unbundling | Dutch greenhouse operators now separate hardware purchase from maintenance agreements, creating recurring revenue pools. |
| Protocol Bridge Development | Integration layers for legacy environmental management platforms reduce installation friction in commercial agriculture facilities. |
| REACH-Compliant Envelope Reformulation | RoHS substance compliance without thermal degradation protects European market access under EU Green Deal mandates. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with greenhouse operations directors, RF electronics procurement leads, film lighting gaffers, and university research facility managers; and secondary validation against EU Ecodesign directive filings, MIIT equipment certification databases, EPA Energy Star qualified product lists, and customs trade records for high-purity fused silica. Bottom-up fixture shipment estimates triangulated against top-down greenhouse acreage expansion and industrial curing line retrofit activity.
Forecast inputs incorporated noble gas chemistry segmentation, envelope size tiering, end-use precision requirements, and regional regulatory cluster differentiation across the projection horizon. CAGRs derived from modeled adoption curves for microwave-driven architectures in controlled-environment agriculture and photochemistry research expansion. Industry-specific inputs included spectral efficacy benchmark evolution and RF licensing framework maturity by geography.
Sensitivities concentrate around LED substitution economics in general illumination, quartz envelope supply disruption, and electromagnetic compatibility certification timeline extension. Forecasts reflect documented assumptions regarding EU Green Deal implementation pace and Chinese dual carbon policy enforcement intensity. Material shifts in noble gas supply chain concentration or REACH substance restriction scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Flexible Lighting Foils Market
Lighting
Photography Light Box Market
Lighting
UV Lamps Market
Lighting
Graphene Lighting Market
Lighting
Wireless Lighting Market
Lighting
Photocell Market
Lighting
Ring Lights Market
Lighting
EV Lighting Market
Lighting
Illuminating Signs Market
Lighting
Smart Lighting Market
Lighting
UAE Smart Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
US Indoor LED Lighting Market
Lighting
Industrial OLED Lighting Market
Lighting
Connected Lighting Platform Market
Lighting
Gesture Control Light Market