
 North America Product Design and Development Services Market | 2026-2036
North America Product Design and Development Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Product Design and Development Services Market Intelligence
The gap between premium consultancies and commoditized engineering shops is hardening across North America. IDEO leverages its human-centered research infrastructure to command retainers for early-stage product strategy. Frog Design anchors its positioning through deep integration with Silicon Valley hardware ecosystems. Capgemini Engineering competes on scale, embedding thousands of engineers inside automotive and aerospace supply chains.
Product design and development services encompass the end-to-end transformation of concepts into production-ready artifacts, spanning industrial design, mechanical engineering, electronics integration, and user experience validation through functional prototyping. These services reduce time-to-market by compressing iterative cycles between digital modeling and physical testing. Prototype development and user experience design now capture disproportionate margin pools as clients prioritize speed and usability over cosmetic refinement. The automotive vertical drives outsized demand for hybrid delivery models that blend onshore program management with offshore CAD execution.
FDA quality system regulation and Health Canada ISO 13485 enforcement shape healthcare vertical demand by mandating design history files and risk management documentation. The EPA and NHTSA impose material and safety standards that filter which development partners qualify for automotive and sustainability-focused engagements. Stakeholders must weigh regulatory compliance depth against speed-to-market when selecting between boutique specialists and integrated engineering conglomerates.
Market Dynamics
Cloud-native CAD platforms and FDA quality system tightening are compressing development cycles while forcing medical device manufacturers toward specialized external partners with validated documentation infrastructure.
Growth Catalysts
- ISO 13485 enforcement:FDA and Health Canada mandates for design history files push medical device makers toward partners with pre-built quality management systems.
- Automotive electrification:EV battery pack integration and thermal management systems require cross-functional design capabilities that internal teams lack.
- Bay Area startup density:California's hardware incubator ecosystem generates concentrated demand for rapid prototyping and industrial design services.
Market Restraints
- Specialized engineering labor scarcity:Mechatronics and embedded systems talent pools concentrate in Southern Ontario and Austin, creating wage pressure.
- Semiconductor component volatility:FPGA and sensor module lead times disrupt prototype scheduling and inflate BOM validation costs.
- ITAR and EAR compliance friction:Defense-adjacent projects require controlled facility certification that filters out mid-tier design shops.
Strategic Opportunities
- Sustainability mandates:EPA material restrictions and California SB 54 packaging rules create design-for-recyclability consulting demand.
- Digital twin convergence:Real-time simulation coupled with generative design tools opens subscription-based continuous engineering models.
- Canadian medtech expansion:Health Canada's streamlined MDEL pathways for software-as-medical-device attract US developers seeking parallel market entry.
Industry Challenges
- Cross-functional integration:Industrial designers and electrical engineers operate in disconnected software environments, forcing manual handoff protocols.
- Regulatory documentation burden:FDA 21 CFR Part 820 design controls require dedicated quality personnel that strain boutique firm economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Product Design and Development Services Market |
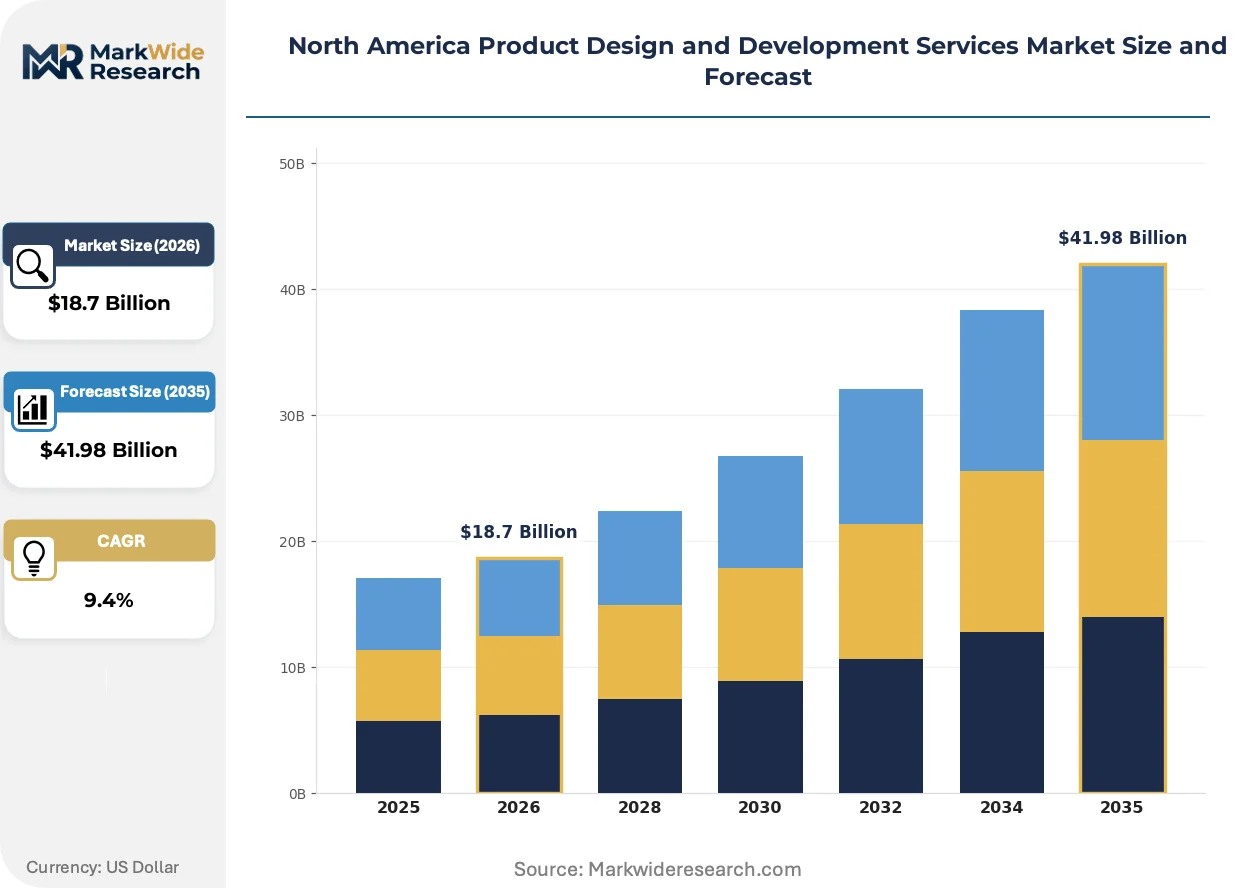
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Prototype Development, User Experience Design, Industrial Design, Product Strategy Industry Vertical: Consumer Electronics, Automotive, Healthcare, Aerospace Delivery Model: Onshore, Offshore, Hybrid, Outsourced Target Market: Startups, SMEs, Corporations, Nonprofits |
| Companies Covered | IDEO, Frog Design, R/GA, Capgemini Engineering, Accenture, Ziba Design, Lunar, Smart Design, Design 1st, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Product Design and Development Services Market Strategic Shifts & Innovations
Generative design algorithms and real-time collaboration platforms are dissolving boundaries between concept modeling, simulation, and manufacturing preparation.
Cloud-native simulation environments are unifying finite element analysis, computational fluid dynamics, and thermal modeling into single-pane workflows. Automotive OEMs in Michigan and aerospace suppliers in Quebec adopt these platforms within six-month procurement cycles. This convergence is unifying previously siloed engineering disciplines and collapsing prototype iteration timelines from weeks to days.
NHTSA updated FMVSS crashworthiness standards and EPA lightweighting mandates are forcing material substitution roadmaps into early design phases. Engineering service providers must now validate aluminum-intensive and carbon-fiber structures against federal safety thresholds before client gate reviews. Medical device developers face parallel pressure from FDA biocompatibility testing timelines that extend polymer selection windows.
Hardware startups now engage design partners through milestone-based statements of work rather than retained engineering relationships. This purchasing pattern compresses vendor evaluation cycles and privileges firms with modular service menus over full-stack consultancies. The shift is most pronounced in Southern California's consumer electronics and robotics clusters, where venture funding volatility demands capital-efficient development pacing.
North America Product Design and Development Services Market Segmentation
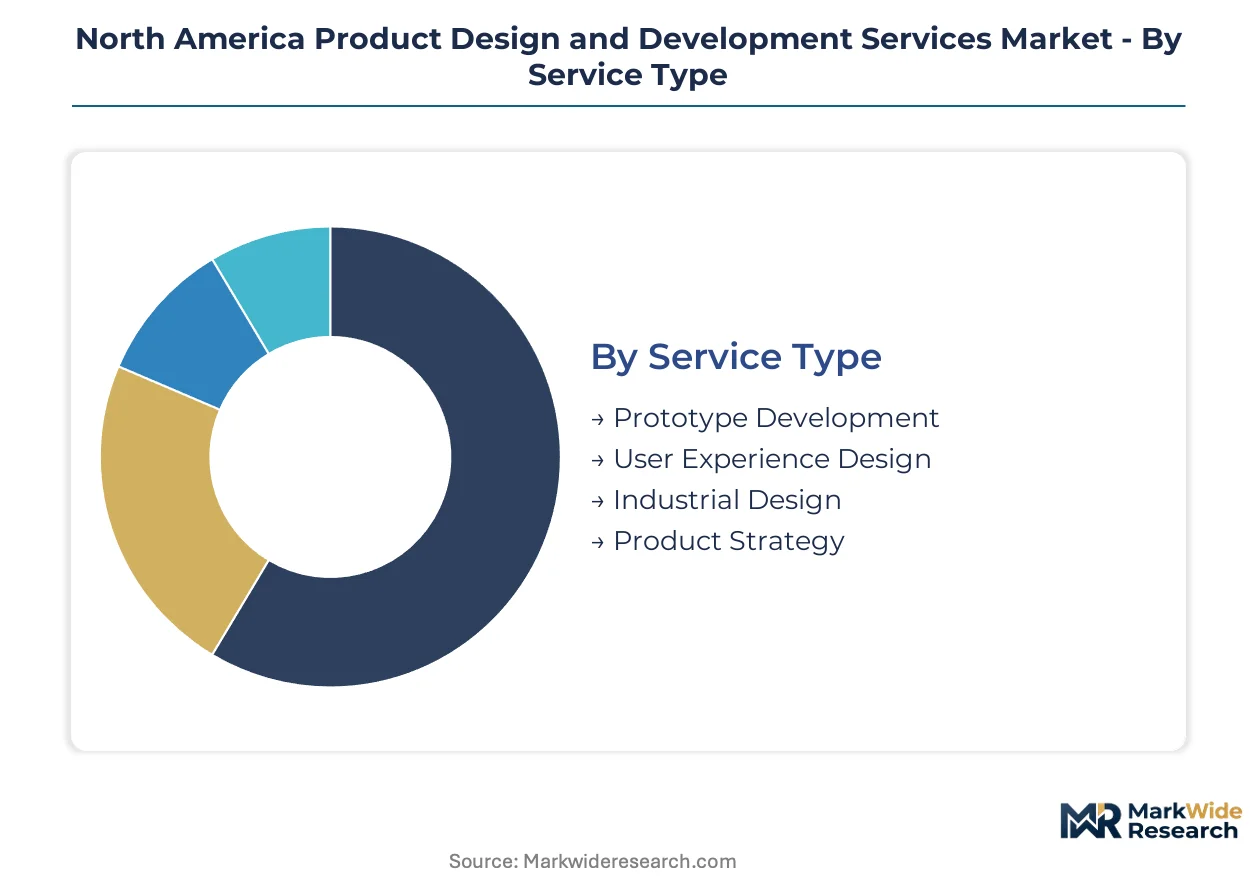
Service specialization and regulatory complexity fragment the North American product design market into distinct capability tiers. Each segmentation axis reveals divergent margin structures and competitive intensity that shape vendor selection criteria.
Service Type:
Technical sophistication and documentation burden differentiate service tiers across the development lifecycle.
- Prototype Development:Functional prototyping combines rapid additive manufacturing with embedded systems integration for pre-production validation. Demand concentrates in California's Bay Area robotics clusters where venture-backed startups compress iteration cycles to meet funding milestones.
- User Experience Design:Human-centered research methodologies translate ethnographic insights into interaction specifications and usability testing protocols. Healthcare developers in Southern Ontario prioritize UX partners with FDA 21 CFR Part 820 familiarity for software-as-medical-device submissions.
- Industrial Design:Aesthetic and ergonomic refinement services bridge concept sketches with manufacturing-ready surface definitions.
- Product Strategy:Early-stage market positioning and feature prioritization engagements command premium retainers from well-capitalized entrants.
Prototype Development leads on scale; User Experience Design leads on momentum.
Industry Vertical:
Regulatory exposure and capital intensity create divergent procurement patterns across end-use sectors.
- Consumer Electronics:Short lifecycle products demand compressed development timelines and offshore CAD execution for cost containment. Southern California hardware incubators drive concentrated demand for rapid industrial design and DFM feedback loops.
- Automotive:EV platform architectures require cross-functional thermal management and battery pack integration capabilities that strain internal engineering bandwidth. Michigan OEMs favor hybrid delivery models blending onshore program management with offshore simulation execution.
- Healthcare:FDA quality system mandates and Health Canada ISO 13485 enforcement require validated design history file infrastructure. Medical device developers in Minnesota and Massachusetts pay premiums for partners with pre-built QMS documentation systems.
- Aerospace:ITAR-controlled facility certification and AS9100 traceability requirements filter out mid-tier engineering shops. Quebec suppliers leverage Canadian dual-use exemptions for defense-adjacent commercial satellite projects.
Automotive commands the largest project values; Healthcare exhibits the steepest expansion trajectory.
Delivery Model:
Geographic distribution of engineering labor shapes cost-quality tradeoffs and regulatory compliance depth.
- Onshore:US-based and Canadian execution centers provide direct client collaboration and intellectual property security for sensitive defense and medical device programs. Premium pricing reflects specialized labor scarcity in mechatronics and embedded systems.
- Offshore:Remote CAD and simulation execution reduces hourly engineering costs for non-regulated consumer product development.
- Hybrid:Blended models anchor program management and quality oversight domestically while routing computational modeling and documentation drafting to lower-cost centers. This configuration dominates automotive electrification projects requiring 24-hour development cycles.
- Outsourced:Full-stack externalization transfers entire product development functions to specialized engineering conglomerates with validated quality infrastructure.
Hybrid delivery captures the broadest adoption; Onshore commands the highest premiums.
Target Market:
Capital availability and procurement sophistication segment client relationships across organizational maturity stages.
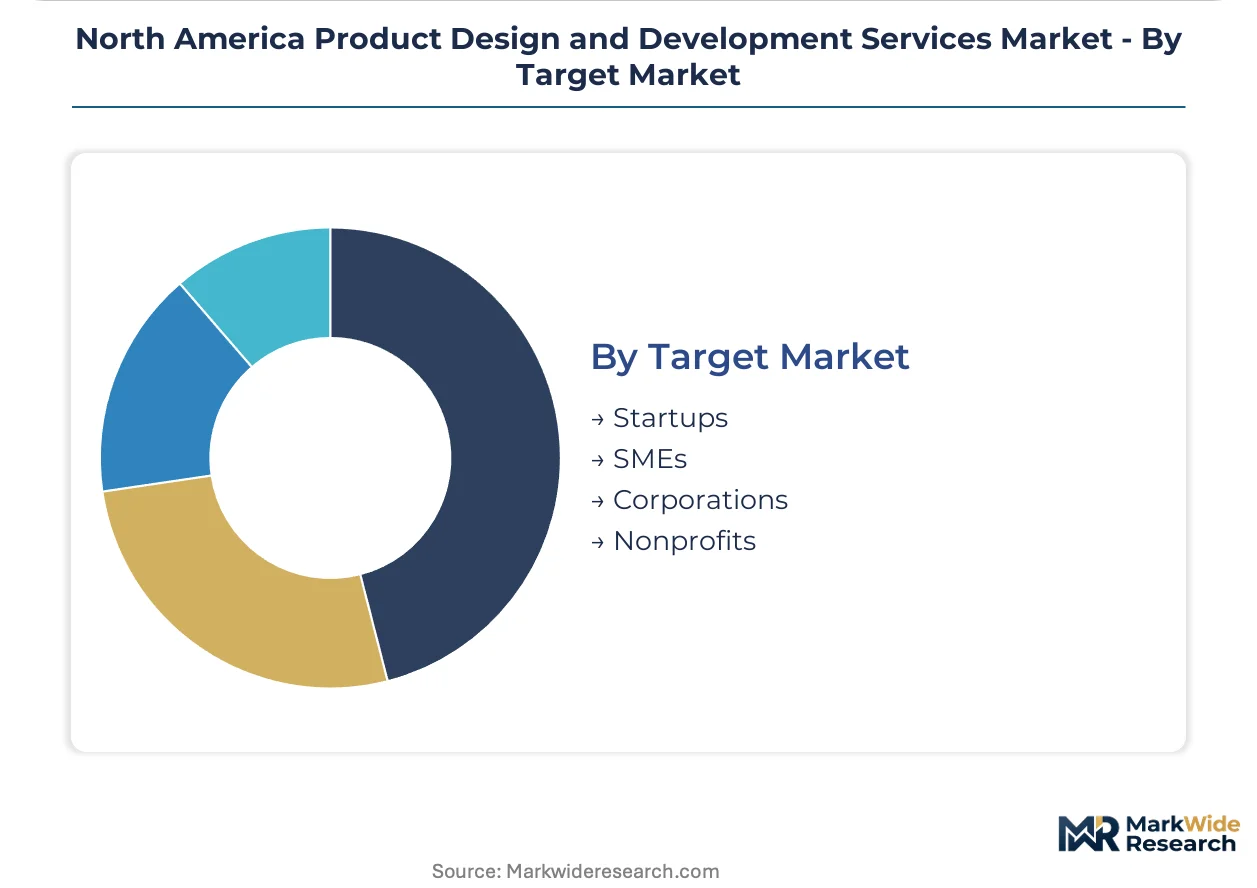
- Startups:Milestone-based statements of work replace retained relationships as venture funding volatility demands capital-efficient pacing. Bay Area hardware accelerators generate concentrated demand for modular service menus over full-stack consultancies.
- SMEs:Mid-market manufacturers lack internal industrial design capabilities but possess sufficient procurement discipline to evaluate vendor quality systems.
- Corporations:Fortune 500 product divisions embed external partners within multi-year engineering service agreements with volume commitments and dedicated team allocation.
- Nonprofits:Mission-driven organizations prioritize cost containment and open-source hardware compatibility over proprietary design protection.
Corporations anchor revenue stability; Startups drive innovation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's medical technology corridor generates concentrated design outsourcing demand, while Mexico's manufacturing integration creates distinct procurement patterns for cross-border engineering services.
United States
FDA quality system mandates and automotive electrification programs drive partner selection toward validated documentation infrastructure. NHTSA updated FMVSS crashworthiness standards force material substitution validation into early design phases. California's Bay Area robotics clusters compress iteration cycles to meet venture funding milestones.
Canada
Health Canada ISO 13485 enforcement and streamlined MDEL pathways attract US developers seeking parallel market entry. The country's national medical device regulator prioritizes software-as-medical-device submissions with pre-built quality management systems. Southern Ontario technology corridors concentrate mechatronics talent pools and automotive OEM engineering centers.
Mexico
Nearshoring manufacturing integration and USMCA trade compliance create demand for bilingual engineering program management. The country's federal economic secretariat supports aerospace supplier development through dual-use exemption frameworks. Baja California and Chihuahua industrial corridors host defense-adjacent commercial satellite projects requiring ITAR-controlled facility coordination.
North America Product Design and Development Services Market Key Industry Players
Top-tier vendors anchor premium strategy retainers, while mid-tier engineering shops compete on modular service menus and capital-efficient pacing. The vendor base stratifies across three capability tiers: human-centered research consultancies, scale-driven engineering conglomerates, and boutique specialists with validated quality infrastructure. Dominant competitive moves include hybrid delivery model expansion and pre-built regulatory documentation system acquisition.
Within the human-centered research tier, IDEO and Frog Design exemplify positioning through deep Silicon Valley hardware ecosystem integration. Capgemini Engineering occupies a position among scale-driven engineering conglomerates embedding thousands of engineers inside automotive and aerospace supply chains. These three entities represent the archetype spectrum from premium consultancies to integrated engineering service providers.
| Leading Market Players |
|---|
| IDEO |
| Frog Design |
| R/GA |
| Capgemini Engineering |
| Accenture |
| Ziba Design |
| Lunar |
| Smart Design |
| Design 1st |
| Others |
Cost & Logistics Intelligence
Engineering labor cost indices in Southern Ontario and Austin feed directly into tiered service pricing across the North American product design market. Cloud-native CAD platform subscriptions compress fixed cost structures for mid-tier providers while specialized FDA documentation capabilities sustain premium retainers in medical device segments.
Pricing Analysis
Capacity additions in Mexico's Baja California engineering corridors are reshaping price floors for hybrid delivery models. Project-based milestone pricing dominates startup engagements, while ISO 13485 certification tier and mechatronics specialization drive price differentiation between boutique consultancies and scale engineering conglomerates. Cost compression in consumer electronics prototyping intensifies as offshore CAD execution expands, with venture-backed startups exhibiting highest price sensitivity and Fortune 500 medical device divisions showing lowest.
Supply Chain Analysis
Regional distribution centers in Michigan, Southern California, and Quebec maintain hub-and-spoke patterns for prototype component fulfillment. Supply chains draw from Taiwan for FPGA modules, China for sensor arrays, and domestic US sources for ITAR-controlled aerospace components. Single-source vulnerability concentrates in advanced semiconductor components for embedded systems integration. Distribution runs through specialized logistics providers with cleanroom handling capabilities for pre-production medical device assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 820 design control tightening compounds demand for validated quality infrastructure, creating sustained procurement premiums for compliant service providers across the North American medical device vertical.
For Market Incumbents: Anchor defensive positioning through pre-built design history file templates and Health Canada MDEL pathway expertise. Consolidate mechatronics talent pools in Austin and Southern Ontario through targeted capability acquisition. Certification investment in AS9100 and ITAR facility status filters competitive pressure from mid-tier engineering shops in defense-adjacent commercial satellite segments. For New Entrants and Emerging Players: EPA material restrictions under California SB 54 packaging rules open a window for design-for-recyclability consulting specialization. Target sustainability-mandated automotive OEMs in Michigan seeking aluminum-intensive structure validation against NHTSA FMVSS crashworthiness standards. Lead generation through hardware incubator partnerships in Bay Area robotics clusters accelerates credential building for subsequent enterprise procurement cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique specialists possessing validated FDA quality management systems and embedded Silicon Valley hardware ecosystem relationships. Long-term viability hinges on recurring revenue attachment to software-as-medical-device development pipelines. Watch Health Canada streamlined MDEL approval velocity as inflection indicator for Canadian medtech expansion demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation System Acquisition | Pre-built FDA 21 CFR Part 820 templates compress client onboarding timelines for medical device engagements. |
| Hybrid Delivery Model Expansion | Blended onshore program management with offshore CAD execution captures automotive electrification project demand. |
| Cloud-Native Platform Integration | Unified simulation environments collapse prototype iteration cycles from weeks to days for Bay Area robotics startups. |
| Sustainability Consulting Capability Buildout | EPA material restriction expertise unlocks design-for-recyclability mandates in automotive and consumer electronics verticals. |
| Mechatronics Talent Hub Establishment | Southern Ontario and Austin engineering concentration addresses specialized labor scarcity driving wage pressure. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with medical device regulatory affairs leads, automotive OEM platform engineers, hardware startup CTOs, and design consultancy principals with secondary validation. FDA 510(k) submission databases, Health Canada MDEL registration records, NHTSA FMVSS compliance filings, and venture capital hardware investment tracking supplied foundational market sizing inputs. Bottom-up service provider revenue aggregation and top-down end-user procurement spend analysis triangulated segment-level demand estimates.
Comparable historical period analysis anchored the projection framework across the modeling period. Segmentation dimensions included service type, industry vertical, delivery model, and target market maturity stage. CAGRs derived from regression analysis against engineering labor cost indices, regulatory filing velocity, and cloud platform adoption curves. Industry-specific forecast inputs incorporated automotive electrification program timelines and medical device software classification trends.
Revisions become necessary when FDA quality system guidance updates, semiconductor component lead time disruptions, or ITAR facility certification backlog conditions materialize beyond baseline assumptions. Forecasts reflect documented parameter sets around regulatory enforcement intensity and venture funding volatility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Key Management As a Service (Kmaas) Market
Digital Solutions
Dating Services Market
Digital Solutions
Container Orchestration Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
Web Real Time Communication Solution Market
Digital Solutions
Digital Rights Management (DRM) Market
Digital Solutions
Global Data Historian Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
Social Networking App Market
Digital Solutions
Kubernetes Solutions Market
Digital Solutions
Core Graphics Market
Digital Solutions
Docketing Solution Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Barcode Software Market
Digital Solutions
Transit Station Display Board Market