
 Global App Store Optimization Tools Software Market | 2026-2036
Global App Store Optimization Tools Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global App Store Optimization Tools Software Market Foresight
Silicon Valley's developer-tool infrastructure is realigning as cloud-native ASO platforms absorb functionality from fragmented point solutions. AppTweak leverages its Brussels-based R&D hub to sustain keyword-optimization leadership across European languages. Sensor Tower anchors its competitive position through proprietary download-estimate models trained on panel data from mobile operators. Gummicube differentiates by specializing in creative-testing workflows for mobile game publishers, a segment where user-acquisition economics demand precise store-page optimization.
App Store Optimization Tools Software comprises algorithmic platforms that analyze ranking signals, metadata fields, and conversion funnels within mobile application storefronts to improve discoverability and install rates; core technical parameters include keyword difficulty scoring, conversion-rate modeling from impression-to-install pipelines, and API integration with Apple App Store Connect and Google Play Console. Cloud-Based deployment leads solution adoption among mid-market app developers seeking elastic compute for large-scale A/B testing, while Keyword Optimization remains the most mature solution offering with compressed margins; Review Management and A/B Testing represent faster-growing margin pools as enterprises prioritize retention metrics over pure acquisition volume. Mobile Games and E-Commerce Apps command the largest application share, though Finance applications show accelerating compliance-driven demand for structured metadata governance.
The Federal Trade Commission's scrutiny of dark-pattern design in mobile interfaces shapes how ASO tools frame preview video and screenshot recommendations, while the EU AI Act imposes transparency requirements on automated keyword-suggestion engines deployed in European storefronts. Apple's App Store Review Guidelines and Google's Developer Program Policies function as de facto product standards that ASO platforms must reverse-engineer and monitor for algorithmic updates. Stakeholders should track regulatory divergence between Washington and Brussels on automated decision-making disclosures, as this will determine whether unified or region-specific tool architectures prove more durable.
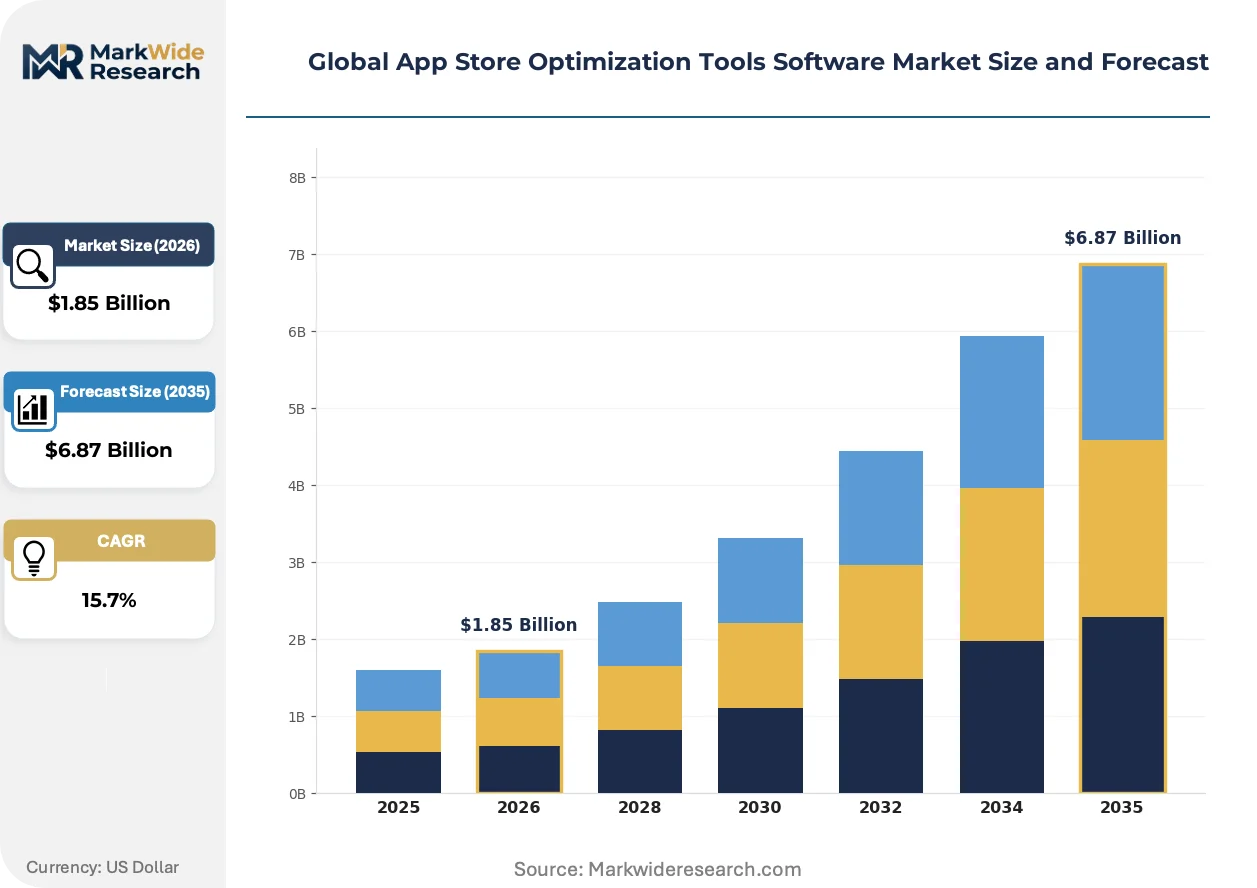
Market Dynamics
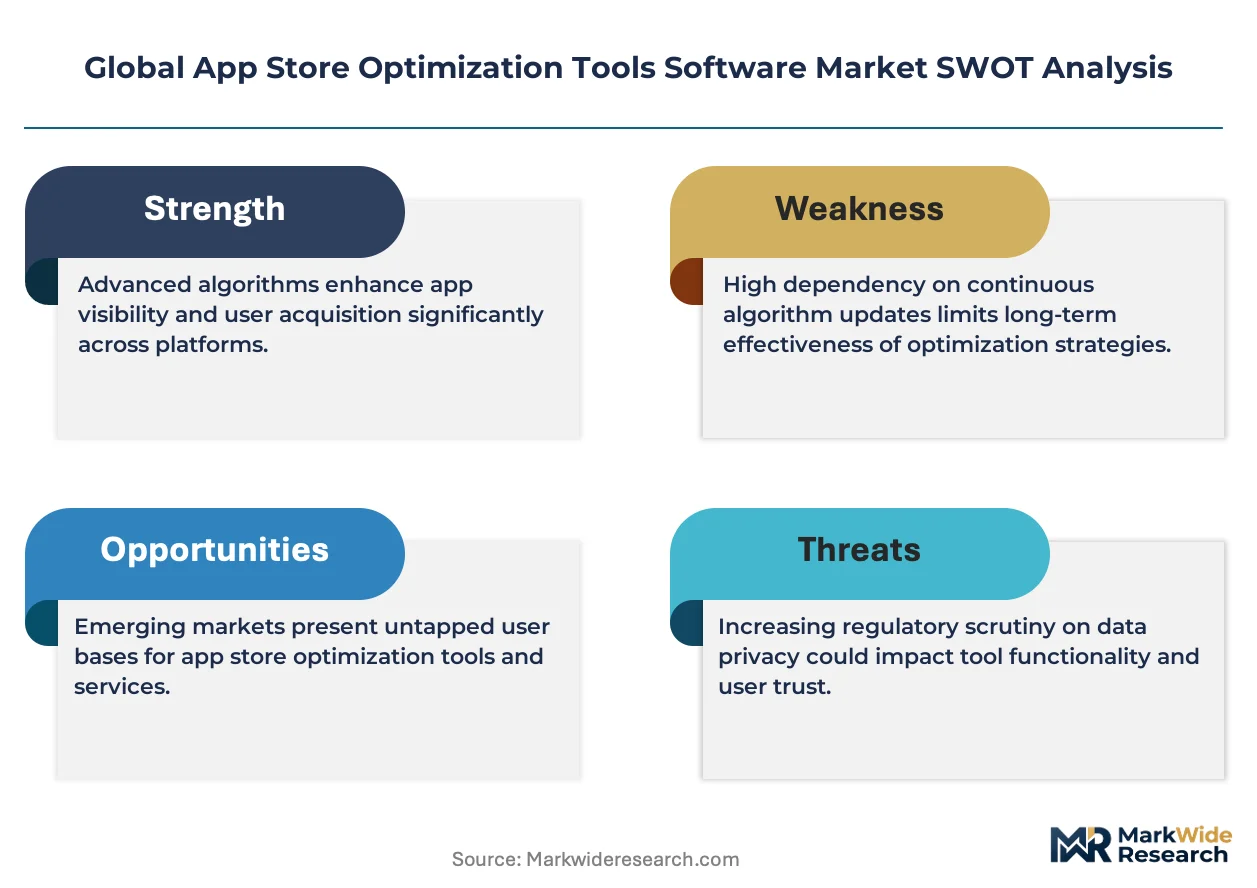
Apple's App Tracking Transparency framework and Google's Privacy Sandbox are compressing attribution fidelity for mobile marketers, forcing ASO platforms to rebuild conversion models around first-party signals and on-device measurement rather than cross-app behavioral graphs.
Growth Catalysts
- EU AI Act transparency mandates:Automated keyword-suggestion engines in European storefronts face new disclosure requirements, creating compliance-tool demand from ASO vendors serving multilingual markets.
- Mobile game studios:User acquisition economics on Apple App Store and Google Play Store now demand precise store-page optimization, driving premium tool subscriptions from mid-tier publishers.
- Cloud-native architectures:Elastic compute for large-scale A/B testing allows mid-market developers to rival enterprise testing velocity without fixed infrastructure commitments.
Market Restraints
- Platform algorithm opacity:Apple and Google provide no official ranking-factor documentation, forcing ASO vendors to maintain expensive reverse-engineering operations with uncertain validation cycles.
- API dependency concentration:App Store Connect and Google Play Console rate limits and unannounced endpoint changes create operational fragility for tools built on official data pipelines.
- Privacy-first attribution erosion:Apple's ATT framework and Google's upcoming Android privacy changes degrade the signal quality that underpins conversion-rate modeling accuracy.
Strategic Opportunities
- Finance app compliance tooling:Structured metadata governance requirements from banking regulators in Germany and Singapore create vertical-specific ASO module demand.
- Creative-testing automation:Convergence of computer vision and generative design tools enables automated screenshot and preview video variant generation at scale.
- India's developer ecosystem:Google Play's dominance in India's price-sensitive market favors freemium ASO tool penetration before monetization maturity.
Industry Challenges
- ML engineering talent scarcity:Download-estimate modeling requires proprietary panel data integration skills that compete with ad-tech salaries in San Francisco and Tel Aviv.
- Cross-platform metadata synchronization:Diverging field requirements between Apple App Store and Google Play Console force redundant workflow engineering for unified campaign management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global App Store Optimization Tools Software Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Hosted Solution Offering: Keyword Optimization, Competitor Analysis, Performance Tracking, A/B Testing, Review Management Application: Mobile Games, E-Commerce Apps, Social Networking, Utilities, Education, Finance End User: App Developers, Digital Marketing Agencies, Independent Publishers, Enterprises, Software Distributors |
| Companies Covered | AppTweak, data.ai, AppFollow, Appfigures, Sensor Tower, Gummicube, SplitMetrics, StoreMaven, Mobile Action, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global App Store Optimization Tools Software Market Shifts & Advancements
ASO tool architectures are fragmenting as point solutions specializing in creative optimization, review sentiment analysis, and competitive intelligence resist consolidation into unified suites.
On-device attribution SDKs are decentralizing conversion measurement away from server-side aggregation, enabling privacy-compliant impression-to-install tracking without third-party data sharing. Mobile game publishers in South Korea and Japan are adopting these SDKs fastest due to stricter local consent requirements. This shift is compressing the competitive advantage held by panel-based download estimators.
The EU AI Act's transparency requirements for automated decision systems are forcing keyword-suggestion engines to expose their ranking logic to European users. ASO platforms serving Brussels, Berlin, and Paris must now architect explainable recommendation layers that satisfy CNIL and BfDI scrutiny. Finance and health app publishers face the steepest compliance burdens given their sensitivity classification.
Subscription-based pricing for ASO tools is displacing seat-based licensing as mid-market developers prioritize elastic testing volume over fixed user counts. Agencies in New York and London are negotiating outcome-tied contracts where fees scale with measured conversion improvements. This model is most visible among mobile game publishers running continuous store-page experiments across seasonal content drops.
Global App Store Optimization Tools Software Market Segmentation
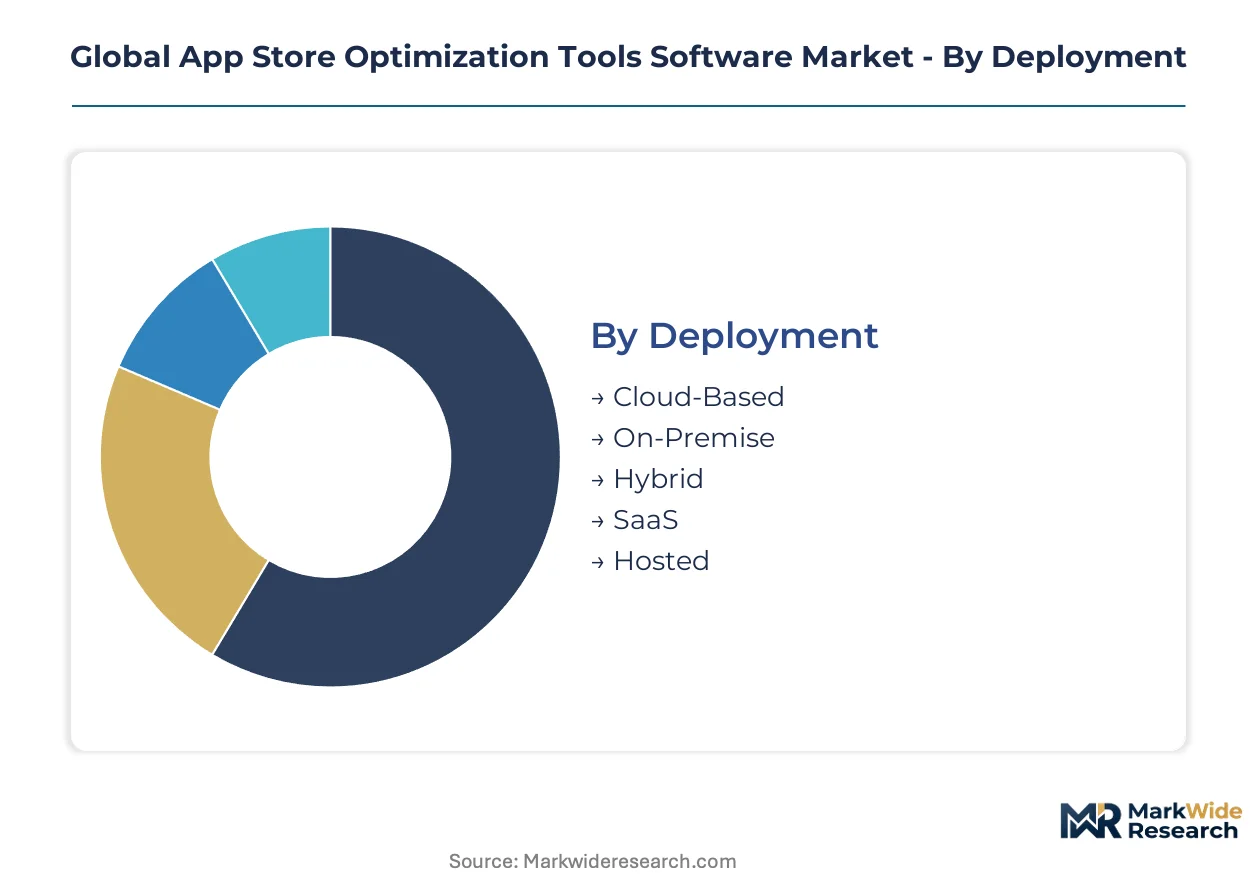
ASO tool buyers fragment sharply across technical maturity and compliance burden. Deployment choices determine infrastructure control, while solution specialization reflects whether publishers prioritize acquisition volume or retention economics.
Deployment:
Cost tier separates buyers in this category, with infrastructure commitment level driving contract structure and margin capture.
- Cloud-Based:Elastic compute architectures enable large-scale A/B testing without fixed infrastructure commitments. Mid-market developers in San Francisco and New York favor this model as seasonal content drops demand variable testing velocity.
- SaaS:Subscription pricing with API-native integration into Apple App Store Connect and Google Play Console reduces engineering overhead. Digital marketing agencies in London negotiate outcome-tied contracts where fees scale with measured conversion improvements.
- On-Premise:Finance and health app publishers in Germany deploy on-premise stacks to satisfy BfDI data sovereignty requirements for sensitive metadata.
- Hybrid:Split architectures process non-sensitive keyword data in cloud while retaining proprietary conversion models on local infrastructure.
- Hosted:Managed single-tenant deployments appeal to Japanese publishers navigating METI guidelines on cross-border data flows.
Cloud-Based leads volumes today; SaaS is gaining share fastest.
Solution Offering:
Application focus distinguishes buyers, with gaming publishers demanding creative velocity against finance apps requiring audit trails.
- Keyword Optimization:Algorithmic difficulty scoring across multilingual storefronts remains the most mature offering with compressed margins. Brussels-based R&D hubs sustain European language coverage for AppTweak and competitors.
- A/B Testing:Conversion-rate modeling from impression-to-install pipelines commands premium pricing as privacy-first attribution erodes. Mobile game studios in South Korea adopt on-device SDKs fastest due to stricter local consent requirements.
- Review Management:Sentiment analysis and response automation expands fastest among subscription apps prioritizing retention metrics over pure acquisition.
- Competitor Analysis:Proprietary download-estimate models trained on panel data from mobile operators anchor Sensor Tower's positioning in competitive intelligence.
- Performance Tracking:Unified dashboards consolidating Apple and Google metrics face engineering redundancy from diverging field requirements between platforms.
Keyword Optimization leads volumes today; A/B Testing is expanding most quickly.
Application:
Margin structure varies by vertical, with compliance burden and creative refresh frequency determining willingness to pay.
- Mobile Games:Continuous store-page experiments across seasonal content drops demand precise creative-testing workflows. User acquisition economics on Apple App Store and Google Play Store now command premium tool subscriptions from mid-tier publishers.
- Finance:Structured metadata governance requirements from banking regulators in Germany and Singapore create vertical-specific module demand. EU AI Act transparency mandates impose additional explainability layers on automated suggestions.
- E-Commerce Apps:Conversion optimization focuses on product imagery and seasonal campaign alignment rather than continuous testing velocity.
- Social Networking:Network effects reduce dependency on organic discovery, compressing ASO tool penetration relative to paid acquisition.
- Utilities:Functional utility over aesthetic differentiation limits screenshot variant testing compared to gaming or retail.
- Education:Institutional procurement cycles and accessibility compliance slow adoption of automated creative generation tools.
Mobile Games leads volumes today; Finance is climbing the fastest.
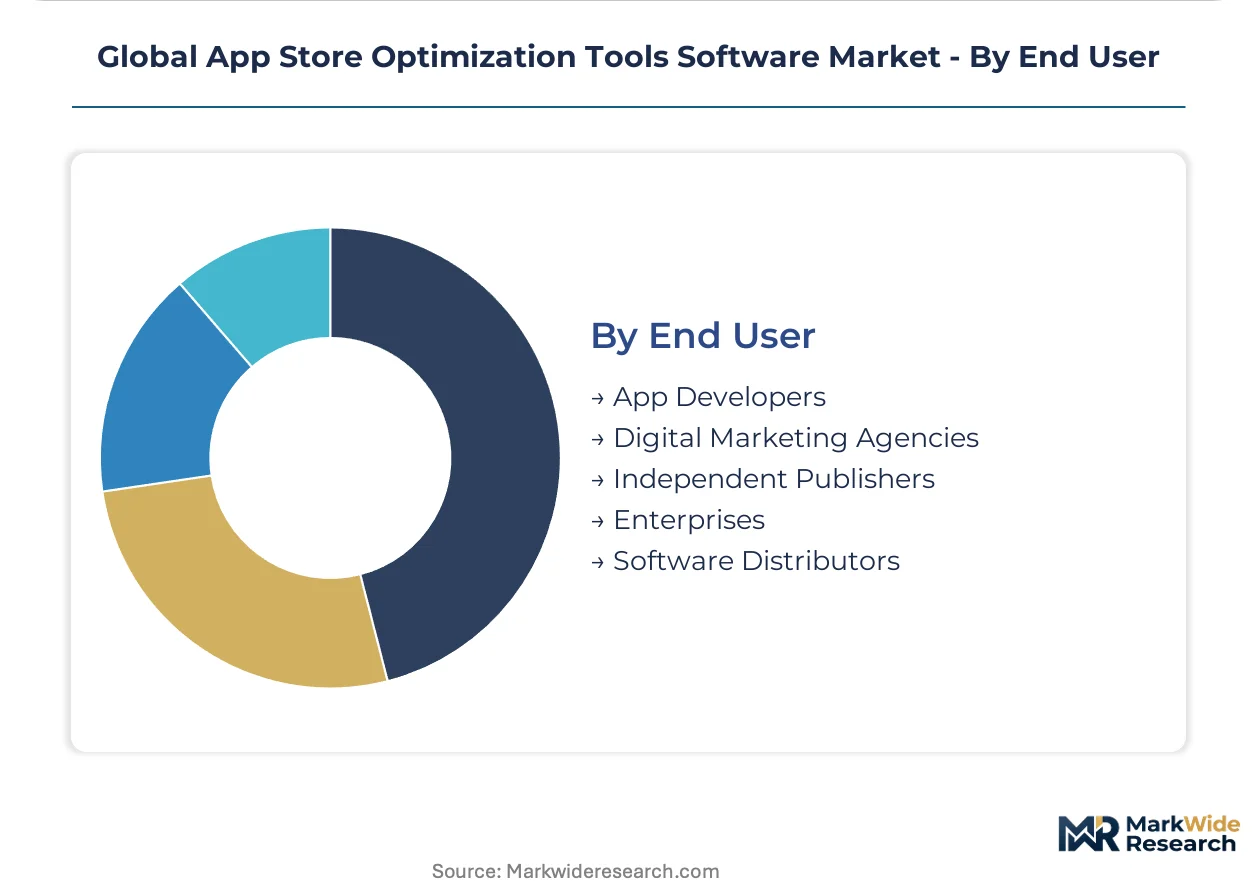
End User:
Customer type determines feature depth, with enterprises demanding governance layers against indie developers prioritizing speed-to-insight.
- Digital Marketing Agencies:Multi-tenant campaign management across publisher portfolios requires unified workflows despite diverging Apple and Google field requirements. New York and London agencies drive outcome-tied contract innovation.
- Enterprises:Compliance tooling for structured metadata governance and audit trails justifies premium pricing from banking and health app publishers facing BfDI and CNIL scrutiny.
- App Developers:Direct publisher adoption concentrates among mid-tier mobile game studios seeking to rival enterprise testing velocity through cloud-native elasticity.
- Independent Publishers:Price-sensitive developers in India's Google Play-dominant market favor freemium penetration before monetization maturity.
- Software Distributors:Channel partners bundling ASO tools with broader mobile marketing stacks face margin pressure from point-solution specialization.
Digital Marketing Agencies lead volumes today; Enterprises is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains premium tool adoption through San Francisco's developer density and New York's agency ecosystem, while India's price-sensitive market favors freemium penetration before monetization maturity.
United States
San Francisco's cloud-native infrastructure and New York's digital marketing agencies drive outcome-tied contract innovation for ASO platforms. The FTC scrutinizes dark-pattern design in mobile interfaces, shaping how tools frame preview video recommendations. Silicon Valley's developer-tool realignment absorbs functionality from fragmented point solutions as mid-market studios seek elastic testing velocity.
Germany
BfDI data sovereignty requirements push finance and health app publishers toward on-premise ASO deployments for sensitive metadata governance. The EU AI Act imposes transparency mandates on automated keyword-suggestion engines deployed in European storefronts. Berlin's R&D hubs sustain multilingual keyword-optimization leadership across European languages.
India
Google Play's dominance in India's price-sensitive market favors freemium ASO tool penetration among independent publishers. The country's national data protection framework shapes cross-border data flow considerations for cloud-based deployments. Bangalore's developer ecosystem concentrates mid-tier app studios seeking cost-efficient creative-testing workflows.
South Korea
Mobile game publishers adopt on-device attribution SDKs fastest due to stricter local consent requirements under national privacy regulations. MFDS-aligned health app compliance creates vertical-specific module demand for structured metadata governance. Seoul's gaming studios drive continuous store-page experiments across seasonal content drops.
Japan
METI guidelines on cross-border data flows push publishers toward hosted single-tenant ASO deployments. Tokyo's mobile game publishers prioritize creative velocity with precise store-page optimization for user acquisition economics. The national regulator's emphasis on consent management accelerates privacy-compliant impression-to-install tracking adoption.
Global App Store Optimization Tools Software Market Competitive Landscape
United States producers anchor the premium tier; European specialists hold compliance-advantaged positions in regulated verticals. The vendor base splits between consolidated platforms with proprietary download-estimate models and fragmented point solutions resisting suite absorption. Three archetypes dominate: panel-data aggregators, creative-testing specialists, and cloud-native elasticity providers. Competitive moves concentrate on geographic R&D hub expansion and outcome-based pricing contract innovation.
Among Brussels-based R&D operations, AppTweak exemplifies the multilingual keyword-optimization archetype. Sensor Tower occupies a position anchored in proprietary download-estimate models trained on mobile operator panel data. Gummicube represents the creative-testing specialization vector for mobile game publishers. These three companies illustrate how geographic concentration and technical differentiation stratify competitive positioning without requiring unified platform dominance.
| Leading Market Players |
|---|
| AppTweak |
| data.ai |
| AppFollow |
| Appfigures |
| Sensor Tower |
| Gummicube |
| SplitMetrics |
| StoreMaven |
| Mobile Action |
| Others |
Supply & Pricing Matrix
Mobile game studios' demand for elastic A/B testing velocity without fixed infrastructure commitments forces cloud-native ASO vendors to absorb compute cost volatility while subscription pricing models compress margin buffers across mid-market tiers.
Pricing Analysis
Distributor margin compression in agency-led procurement channels intensifies as New York and London marketing agencies negotiate outcome-tied contracts where fees scale with measured conversion improvements. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by API call volume entitlements and dedicated customer success tiering. Pricing pressure stems from freemium penetration in India's Google Play-dominant market. Independent publishers in Bangalore and Delhi exhibit highest price sensitivity; enterprise banking app publishers in Germany show lowest sensitivity due to BfDI-mandated compliance tooling requirements.
Supply Chain Analysis
ML engineering talent scarcity in San Francisco and Tel Aviv constrains proprietary download-estimate model development, forcing ASO vendors to compete with ad-tech salary benchmarks or relocate R&D to Brussels and Berlin. Cloud compute provisioning concentrates in United States, Ireland, and Singapore; panel data partnerships draw from mobile operators in South Korea and Japan. API dependency on Apple App Store Connect and Google Play Console creates single-source vulnerability from unannounced endpoint changes. Distribution runs through direct SaaS self-service portals and agency-managed enterprise contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU AI Act transparency mandates impose costly explainability-layer engineering on European deployments, while India's price-sensitive market permits freemium scale-before-monetization strategies unavailable under Brussels regulatory burden.
For Market Incumbents: Anticipate privacy-first attribution erosion degrading conversion-model accuracy by accelerating first-party signal infrastructure and on-device SDK partnerships. Defensive consolidation of creative-testing specialists in Seoul and Tokyo counters emerging computer-vision automation entrants. Vertical integration into panel data partnerships with mobile operators in South Korea and Japan anchors proprietary download-estimate moats against decentralized attribution SDKs. For New Entrants and Emerging Players: Generative design automation for screenshot and preview video variants offers a technology-first wedge against incumbent creative-testing workflows. India's independent publisher segment presents the most penetrable geography given freemium tolerance and Google Play dominance. Go-to-market through Bangalore developer ecosystem partnerships bypasses saturated San Francisco agency channels. For Investors and Strategic Acquirers: Asymmetric upside sits with creative-testing specialists possessing computer-vision IP and mobile game publisher relationships in South Korea and Japan. Five-to-ten year viability favors vendors bridging privacy-compliant attribution with explainable AI layers for EU finance and health verticals. Watch on-device SDK adoption velocity in Seoul and Tokyo as inflection indicator for panel-data aggregator defensibility.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Layer Development | EU AI Act compliance in Brussels, Berlin, and Paris storefronts mandates transparent keyword-suggestion logic for finance and health apps. |
| On-Device Attribution SDK Integration | Privacy-compliant impression-to-install tracking in South Korea and Japan counters Apple's ATT framework signal degradation. |
| Creative-Testing Automation Platform | Computer-vision and generative design convergence enables screenshot variant generation at scale for mobile game seasonal content drops. |
| Regional R&D Hub Expansion | Brussels-based operations sustain European multilingual keyword-optimization leadership against Silicon Valley salary inflation. |
| Outcome-Tied Contract Structuring | New York and London agency negotiations align vendor fees with measured conversion improvements, reducing churn risk. |
Research Methodology
Bottom-up mobile game publisher and finance app modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core. Primary interviews with ASO platform CTOs, digital marketing agency heads, mobile operator data partnership leads, and app store policy compliance officers combined with secondary validation from SEC filings, App Store Connect documentation, Google Play Console policy archives, and EU AI Act regulatory texts. Triangulation across deployment model adoption curves and solution offering margin structures verified segment-level estimates.
Historical trendline analysis of keyword optimization maturity curves and A/B testing velocity benchmarks established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution specialization, application vertical, and end-user category, with additional weighting for regulatory compliance burden tiers. CAGRs derived from elasticity-adjusted adoption curves incorporating privacy-framework impact coefficients and cloud-native infrastructure penetration rates. Forecast inputs included mobile game seasonal content release calendars and banking regulator metadata governance mandate timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Apple and Google algorithm opacity, API endpoint discontinuation risk, and divergent Washington-Brussels regulatory trajectory on automated decision-making disclosures. Forecasts reflect documented assumptions on privacy-first attribution degradation velocity and EU AI Act enforcement consistency. Material deviation in platform algorithm update frequency or cross-border data flow restriction scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Intelligent Apps Market
Software & Services
Stone Analysis Software Market
Software & Services
Global CMMS Software Market
Software & Services
Global Forestry Software Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Global Content Management Systems (CMS) Market
Software & Services
Global Demand Planning Software Market
Software & Services
SMS Marketing Software Market
Software & Services
Canada HR Payroll Software Market
Software & Services
Geomechanics Software and Service Market
Software & Services
Global Municipal Software Market
Software & Services
Preschool Education Software Market
Software & Services
PAC Programming Software Market
Software & Services
Global Online OCR Software Market
Software & Services
Interior Design Software Market
Software & Services
APAC Workforce Management Software Market