
 Image Recognition in Retail Market | 2026-2036
Image Recognition in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Image Recognition in Retail Market Outlook
GDPR enforcement in Europe is shifting the cost-of-entry calculus for retail image recognition vendors, forcing privacy-by-design architectures that smaller players struggle to fund. NVIDIA Corporation dominates GPU-accelerated inference for in-store analytics, while Amazon Web Services Inc. extends cloud-native vision services to mid-market retailers. Qualcomm Incorporated specializes in edge-AI chipsets that reduce latency for real-time shelf monitoring.
Image recognition in retail encompasses systems that identify, classify, and interpret visual data from store environments using convolutional neural networks operating at 30-60 frames per second, primarily to automate inventory tracking, loss prevention, and shopper behavior analysis. Deep learning architectures lead the technology segment due to superior accuracy in cluttered shelf conditions, while visual search applications grow fastest as e-commerce platforms integrate camera-based product discovery. Software solutions capture the largest revenue share, though integrated systems that combine cameras, edge processors, and analytics dashboards command the highest margins.
The EU AI Act and GDPR constrain biometric data collection in European retail environments, while the FDA oversees image-based diagnostic tools in pharmacy retail settings and China's SAMR enforces algorithmic recommendation transparency for consumer-facing applications. Retailers must navigate fragmented compliance obligations that vary by jurisdiction, data type, and deployment context. Stakeholders should monitor evolving algorithmic accountability rules that will determine which vision technologies remain permissible in physical retail spaces.
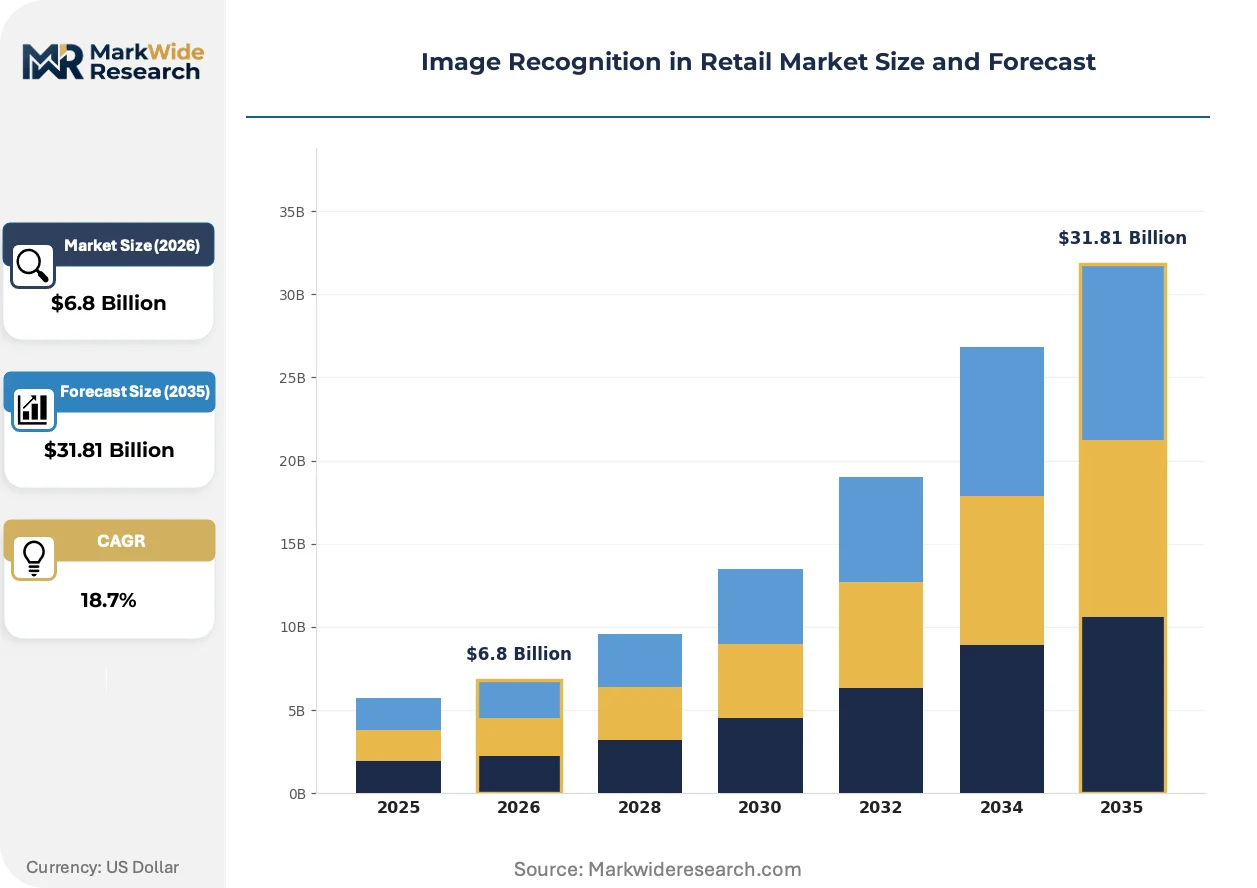
Market Dynamics
Self-checkout systems and smart shelf monitoring are pulling convolutional neural networks into physical retail at 30-60 frames per second, while the EU AI Act rewrites compliance architecture for biometric deployments.
Growth Catalysts
- EU AI Act compliance mandates:Retailers across France, Germany, and Italy must deploy privacy-by-design vision systems, creating procurement urgency for certified vendors.
- Edge-AI chipset maturation:Qualcomm's neural processing units enable real-time shelf analytics without cloud latency, unlocking mid-market supermarket adoption.
- Loss prevention automation:Shrinkage reduction targets at Walmart and Target are channeling capital into computer vision infrastructure for checkout monitoring.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in accelerated inference creates single-source dependency risk for retail analytics deployments.
- GDPR biometric friction:Facial recognition deployments in European stores face explicit consent requirements that throttle rollout velocity.
- Legacy POS integration complexity:Decades-old supermarket checkout hardware requires expensive middleware to interface with modern vision systems.
Strategic Opportunities
- India's PLI scheme for electronics:Manufacturing incentives are attracting edge-device assembly for cost-competitive smart shelf hardware.
- Visual search e-commerce convergence:Camera-based product discovery is absorbing smartphone-native shoppers in South Korean and Japanese retail apps.
- Pharmacy retail diagnostics:FDA oversight of image-based health tools is creating a regulated channel for computer vision in drugstore settings.
Industry Challenges
- Computer vision engineer scarcity:Retailers compete with automotive and healthcare sectors for talent capable of optimizing CNNs for cluttered shelf conditions.
- Multi-jurisdiction compliance stacking:Chains operating across the United States, EU, and China must maintain parallel algorithmic accountability documentation under FDA, GDPR, and SAMR frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Image Recognition in Retail Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.81 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Deep Learning, Computer Vision, Machine Learning, Image Processing Application: Inventory Management, Customer Analytics, Fraud Detection, Visual Search Product Type: Software Solutions, Cloud Services, Hardware Devices, Integrated Systems End User: Supermarkets, E-commerce Platforms, Retail Chains, Specialty Stores |
| Companies Covered | Trax Retail Solutions Pte. Ltd., NEC Corporation, Google LLC, Intel Corporation, Qualcomm Incorporated, Amazon Web Services Inc., Clarifai Inc., NVIDIA Corporation, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Image Recognition in Retail Market Strategic Shifts
Vision systems are migrating from cloud inference to edge-native processing, compressing response times for real-time retail decisions. This architectural shift is redrawing competitive boundaries between semiconductor suppliers and software platforms.
Transformer-based vision models are absorbing attention mechanisms previously reserved for natural language processing, enabling shelf-level product recognition in occluded or poorly lit conditions. Grocery chains in the United States are piloting these architectures for automated inventory audits. The technology is absorbing market share from older YOLO-based detection pipelines by reducing false positives on irregular packaging.
The EU AI Act's risk-classification framework is forcing retailers to document training data provenance and algorithmic impact assessments for biometric applications. European deployment timelines have lengthened as chains await certified conformity assessment bodies. France's CNIL has issued specific guidance on facial recognition in public retail spaces that exceeds baseline EU requirements.
Buyer concentration among top-ten grocery chains is compressing vendor negotiation cycles and demanding outcome-based pricing tied to shrinkage reduction metrics. Mid-tier retailers are responding by pooling procurement through cooperative buying groups. This pattern is most visible in German and Dutch markets where centralized retail federations dominate shelf space.
Image Recognition in Retail Market Segmentation
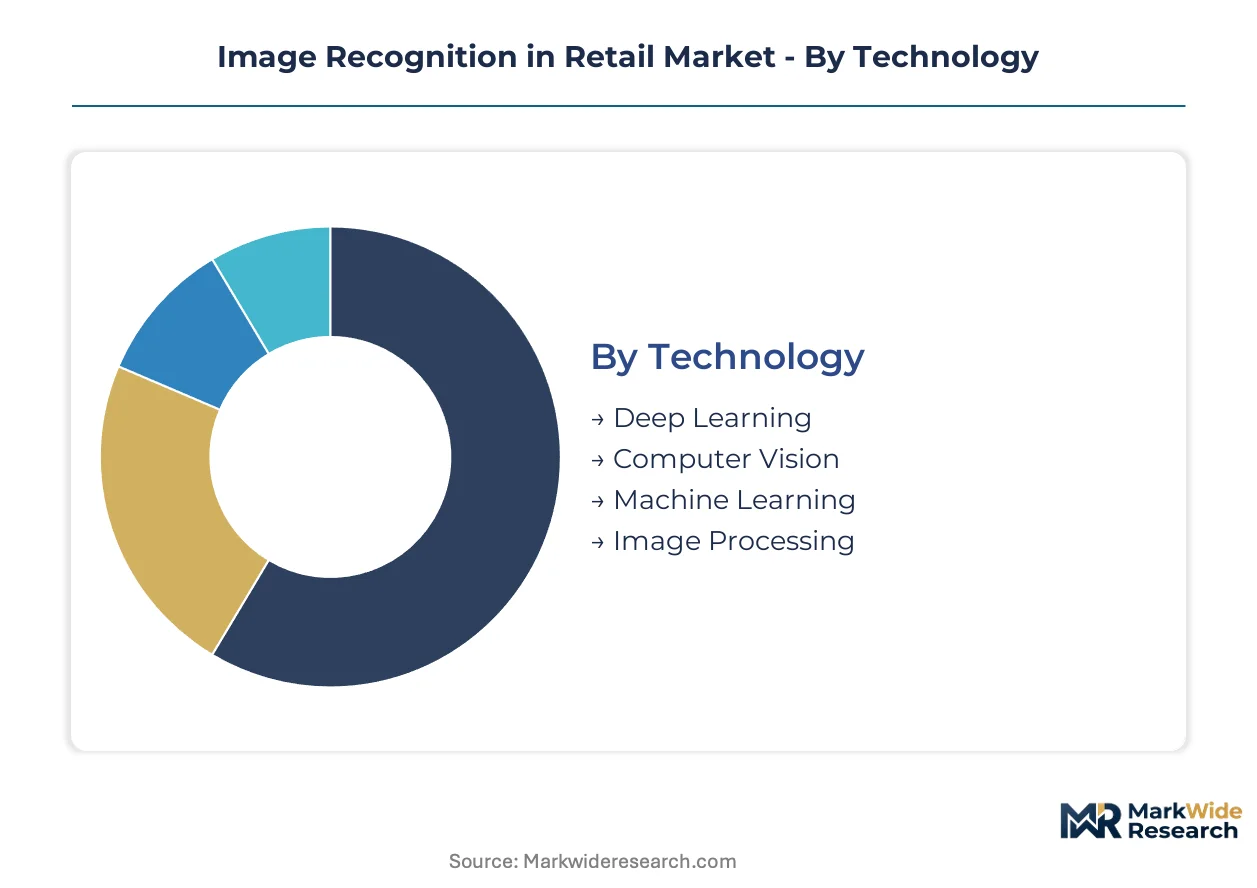
Retail image recognition segments diverge sharply by deployment complexity and integration depth. Technology choices determine inference latency, while product architecture decisions lock in margin structures and vendor switching costs for multi-year contracts.
Technology:
Customization intensity spans from off-the-shelf APIs to proprietary model training pipelines requiring dedicated ML engineering teams.
- Deep Learning:Convolutional neural networks operating at 30-60 frames per second process cluttered shelf imagery with superior accuracy in variable lighting. Supermarket operators in the United States prioritize these architectures for automated inventory audits where packaging irregularities demand contextual interpretation.
- Computer Vision:Traditional feature-extraction methods using edge detection and pattern matching execute on lower-cost hardware with deterministic latency. Specialty stores deploy these systems for fixed-angle product verification where environmental conditions remain controlled.
- Machine Learning:Gradient-boosted classifiers and support vector machines handle structured metadata tagging and product attribute extraction at reduced computational overhead.
- Image Processing:Preprocessing pipelines for noise reduction, perspective correction, and illumination normalization prepare raw camera feeds for downstream neural network consumption.
Most installed capacity flows through Deep Learning architectures. Expansion is steepest in Computer Vision as edge-AI chipsets mature and latency requirements tighten for real-time checkout monitoring.
Application:
Cost tier stratification separates capital-intensive infrastructure deployments from software-only analytics subscriptions with faster payback periods.
- Inventory Management:Shelf-mounted cameras and overhead vision systems track stock levels, planogram compliance, and out-of-stock conditions through automated visual audits. Walmart and Target channel capital into these deployments to reduce manual audit labor and improve replenishment velocity.
- Customer Analytics:Heat mapping, dwell-time measurement, and demographic estimation using anonymized silhouette analysis. GDPR constraints in France, Germany, and Italy throttle biometric data collection, forcing privacy-preserving alternatives that aggregate patterns without individual identification.
- Fraud Detection:Checkout cameras flag unscanned items, sweethearting behaviors, and return fraud through real-time video analysis integrated with POS transaction logs.
- Visual Search:Camera-based product discovery enables shoppers to photograph items and retrieve matching or similar products from digital catalogs. E-commerce platforms in South Korea and Japan absorb smartphone-native users through this interface paradigm.
Revenue concentration sits with Inventory Management due to supermarket chain procurement scale. Visual Search gains share fastest as mobile commerce penetration deepens in East Asian markets.
Product Type:
Margin structure correlates inversely with hardware content, with pure software commanding recurring revenue multiples and integrated systems capturing highest absolute margins through vendor lock-in.
- Software Solutions:Cloud-hosted inference APIs and on-premise analytics platforms processing video streams from customer-owned cameras. These capture the largest revenue share through subscription pricing models that scale with store count and camera density.
- Integrated Systems:Bundled deployments combining edge processors, purpose-built cameras, and analytics dashboards with unified support contracts. German and Dutch retail federations favor these procurements to minimize multi-vendor integration complexity.
- Cloud Services:Pay-per-inference models for retailers with variable demand patterns or seasonal traffic spikes requiring elastic compute scaling.
- Hardware Devices:Specialized cameras, edge-AI boxes, and shelf-mounted sensors sold as capital equipment with multi-year depreciation schedules.
Deployment volume flows predominantly through Software Solutions. Integrated Systems expand most quickly as mid-market retailers seek turnkey deployments reducing internal engineering burden.
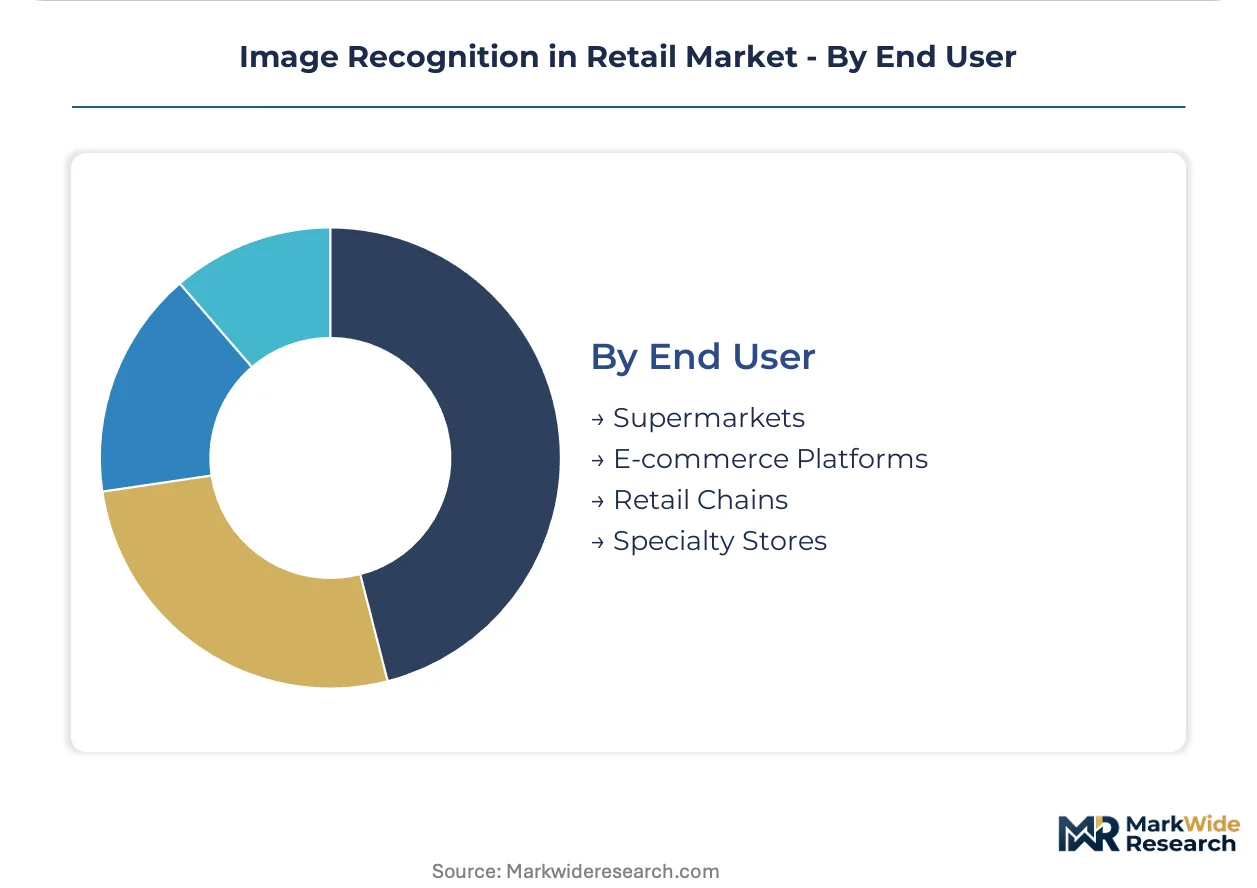
End User:
Customer type determines procurement sophistication, with enterprise grocery chains demanding outcome-based pricing tied to shrinkage metrics versus smaller retailers accepting standardized SaaS tiers.
- Supermarkets:Large-format grocery operators deploying self-checkout vision systems and smart shelf monitoring across thousands of locations. The EU AI Act mandates privacy-by-design architectures for biometric applications in French, German, and Italian stores.
- E-commerce Platforms:Pure-play digital retailers integrating visual search, augmented reality try-on, and automated product photography pipelines. These operators drive fastest growth in transformer-based vision models for camera-based discovery.
- Retail Chains:Multi-format operators with heterogeneous store sizes requiring scalable vision architectures adaptable from hypermarkets to convenience footprints.
- Specialty Stores:Focused retailers in apparel, electronics, or cosmetics deploying targeted applications like virtual fitting rooms or skin-tone-matched product recommendations.
Procurement volume concentrates in Supermarkets due to camera density requirements and loss prevention budgets. E-commerce Platforms show steepest adoption curves as visual search absorbs mobile-native shopper behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computer vision engineers cluster in the United States, China, and Germany, anchoring retail AI development in these markets while regulatory divergence fragments deployment timelines elsewhere.
United States
Walmart and Target channel capital into self-checkout vision systems and smart shelf monitoring across thousands of locations. The FDA oversees image-based diagnostic tools in pharmacy retail settings, creating a regulated channel for computer vision deployment. Seattle and San Francisco host dense concentrations of cloud-native vision service providers serving mid-market retailers.
China
E-commerce platforms absorb smartphone-native shoppers through camera-based product discovery interfaces. SAMR enforces algorithmic recommendation transparency for consumer-facing applications, constraining how vision systems present search results. Shenzhen manufacturers produce cost-competitive edge-AI chipsets for real-time shelf analytics.
Germany
Retail federations concentrate procurement through cooperative buying groups, demanding integrated systems that minimize multi-vendor complexity. GDPR and the EU AI Act mandate privacy-by-design architectures for biometric applications, lengthening deployment timelines. Berlin and Munich anchor development of transformer-based vision models for automated inventory audits.
France
Supermarket operators face explicit consent requirements for facial recognition deployments under CNIL guidance that exceeds baseline EU standards. The EU AI Act's risk-classification framework forces retailers to document training data provenance and algorithmic impact assessments. Paris clusters computer vision startups focused on anonymized shopper behavior analytics.
Japan
Visual search applications gain traction as e-commerce platforms integrate camera-based product discovery for mobile-native consumers. METI standards shape edge-AI deployment protocols for retail environments. Tokyo and Osaka concentrate development of low-latency vision systems for convenience store automation.
Image Recognition in Retail Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the retail image recognition value chain. Semiconductor suppliers battle cloud service providers for control over inference architecture, while software platforms jostle with integrated system vendors for procurement contracts. Three archetypes dominate: GPU-accelerated inference providers, edge-AI chipset specialists, and cloud-native vision service platforms. Competitive moves center on strategic partnerships between hardware and software layers and geographic expansion into mid-market retail segments.
Within the semiconductor tier, NVIDIA Corporation and Qualcomm Incorporated anchor opposing architectural philosophies—cloud versus edge—while Amazon Web Services Inc. exemplifies the cloud-native platform approach. Google LLC and Intel Corporation occupy positions spanning hardware-software boundaries. These five entities collectively represent the competitive tension between latency-optimized edge deployment and elastic cloud scaling that shapes vendor selection criteria across supermarket chains and e-commerce operators.
| Leading Market Players |
|---|
| Trax Retail Solutions Pte. Ltd. |
| NEC Corporation |
| Google LLC |
| Intel Corporation |
| Qualcomm Incorporated |
| Amazon Web Services Inc. |
| Clarifai Inc. |
| NVIDIA Corporation |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EU AI Act-compliant vision systems and standard deployments splits both pricing architectures and supplier qualification pathways. Premium-tier vendors absorb compliance documentation costs into multi-year service contracts, while commodity hardware producers compete on unit economics for non-biometric shelf monitoring applications.
Pricing Analysis
Bundled integrated systems command three-to-five-year service contracts with hardware refresh clauses, while unbundled software subscriptions scale per-camera or per-store monthly fees. Price differentiation hinges on GDPR certification tier and edge-AI processing latency guarantees, with French and German supermarket federations paying premiums for documented algorithmic impact assessments. Cost compression in mid-market SaaS tiers intensifies as cooperative buying groups consolidate procurement volumes. Small-format specialty retailers exhibit highest price sensitivity, deferring upgrades until edge-device costs fall below capital expenditure thresholds.
Supply Chain Analysis
Reverse-logistics flows for edge-AI hardware remain underdeveloped, with failed shelf-mounted cameras and obsolete neural processing units accumulating in retailer warehouses rather than returning to refurbishment centers. Manufacturing concentrates in Taiwan for GPU accelerators, South Korea for advanced memory modules, and China for camera assembly and edge-device packaging. Component supply draws from NVIDIA's inference chip allocation system, Sony's image sensor foundries, and Qualcomm's neural processing unit fabrication network. Single-source dependency on NVIDIA's GPU supply creates vulnerability for real-time analytics deployments. Distribution runs through German and Dutch retail federations for integrated systems, and AWS marketplace channels for cloud-native software subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement committees prioritize documented compliance over raw performance specifications. Demand is shifting toward premium-tier vision systems with pre-certified EU AI Act conformity assessments that accelerate deployment timelines.
For Market Incumbents: Lock in long-term GPU allocation agreements with NVIDIA to secure inference capacity for enterprise supermarket contracts. Defend margin position by embedding compliance documentation services into recurring revenue streams, neutralizing emerging pure-play software vendors that lack certification expertise. Deepen backward integration into edge-device firmware to reduce dependency on Qualcomm's neural processing unit roadmaps.
For New Entrants and Emerging Players: Capture white-space in India's mid-market supermarket segment where PLI scheme incentives lower hardware assembly costs and EU regulatory complexity has delayed incumbent entry. Target South Korean and Japanese e-commerce platforms with visual search APIs that bypass the compliance documentation burden constraining European deployments. Lead with pay-per-inference pricing to minimize customer capital commitment and accelerate proof-of-concept cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where computer vision engineering talent scarcity intersects with fragmented mid-market software vendors lacking compliance infrastructure. Long-term viability favors platforms with documented algorithmic accountability frameworks spanning FDA, GDPR, and SAMR jurisdictions. Monitor CNIL enforcement actions and FDA pharmacy retail guidance as early signals of regulatory stringency that will determine which vendor architectures achieve scalable deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-by-Design Architecture Certification | EU AI Act compliance documentation accelerates procurement cycles with French and German retail federations. |
| Edge-AI Chipset Partnership | Qualcomm neural processing unit integration reduces cloud latency for real-time shelf monitoring applications. |
| Visual Search Platform Launch | Camera-based product discovery captures smartphone-native shoppers in South Korean and Japanese e-commerce apps. |
| Cooperative Buying Group Alignment | German and Dutch retail federation contracts minimize customer acquisition costs through pooled procurement. |
| Pharmacy Retail Diagnostics Expansion | FDA-regulated channel creates defensible positioning for computer vision in drugstore health tool deployments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with computer vision engineering leads, supermarket loss prevention directors, e-commerce platform product managers, and edge-AI semiconductor procurement specialists with secondary validation against SEC hyperscaler capex disclosures, EU AI Act implementation guidance, and FDA pharmacy retail device filings. Bottom-up store-level camera deployment estimates triangulated against top-down retail IT spending benchmarks.
Comparable-period anchoring tied projection models to historical adoption curves for self-checkout systems and smart shelf monitoring rollouts across the analysis window. Segmentation dimensions spanned technology architecture, application use case, product bundling configuration, and end-user format type. CAGRs derived from S-curve penetration modeling calibrated to supermarket chain capital expenditure cycles and e-commerce platform feature release timelines. Forecast inputs incorporated edge-device cost decline trajectories and regulatory compliance timeline assumptions.
Underlying measurement precision varies by segment; integrated systems and enterprise supermarket deployments carry tighter precision than fragmented specialty store applications. Forecasts reflect assumptions about EU AI Act enforcement consistency, GPU supply allocation stability, and edge-AI chipset performance evolution. Practitioners should monitor CNIL facial recognition rulings, FDA pharmacy guidance expansion, and SAMR algorithmic transparency enforcement for early signals of regulatory trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mobile Dating Apps Market
Digital Solutions
Digital Library Software Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
Life Science Multichannel Campaign Management Market
Digital Solutions
Weather Information Technologies Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Digital Signage Market
Digital Solutions
Electronic Data Interchange (EDI) Market
Digital Solutions
Lecture Capture Solutions Market
Digital Solutions
Demand Signal Repository Solutions Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Global Freelance Platforms Market