
 Communication Repeater Market | 2026-2036
Communication Repeater Market Size, Share, and Industry Trends Forecast 2026-2036
Communication Repeater Market Analytics
Multi-source component procurement is decoupling from legacy single-vendor radio frequency chains as price volatility in gallium nitride semiconductors forces diversification. Nextivity, Inc. leverages its North American channel partnerships to sustain enterprise indoor deployments. Huaptec anchors Asia-Pacific manufacturing scale for cost-optimized cellular repeaters. Ritron, Inc. specializes in hardened outdoor units for public safety frequencies.
A communication repeater is an electronic device that receives, amplifies, and retransmits radio frequency signals across designated spectrum bands, typically operating at power levels from milliwatts to several watts depending on deployment class. Its primary commercial purpose is extending coverage footprint or filling dead zones without requiring additional base station infrastructure. Cellular repeaters command the largest installed base among product categories, though IoT repeaters are gaining traction in agricultural telemetry and industrial sensor backhaul where low-power wide-area protocols require gap-filling infrastructure. Fiber optic technology segments carry premium pricing due to minimal signal degradation over long-haul links, while analog technology persists in legacy public safety networks with slow replacement cycles.
FCC Part 20 certification governs signal booster operation in the United States, mandating automatic gain control and network protection safeguards that add engineering cost but block uncertified imports. CE marking under the EU Radio Equipment Directive and GB standards administered by MIIT in China create parallel compliance tracks that fragment vendor testing budgets. India's WPC frequency authorization process, managed through the Department of Telecommunications, imposes additional field trials for imported repeaters. Stakeholders must monitor spectrum reallocation timelines in major economies, as mid-band 5G refarming directly threatens existing repeater compatibility and forces hardware refresh decisions.
Market Dynamics
Mid-band 5G refarming is forcing hardware refresh cycles across installed repeater bases as spectrum reallocation renders legacy equipment incompatible with new carrier configurations.
Growth Catalysts
- FCC Part 20 certification mandates:Automatic gain control requirements in the United States block uncertified imports, creating protected demand corridors for compliant domestic vendors.
- India's tier-2 city corridors:Mobile subscriber density in urban peripheries outpaces base station deployment, accelerating digital repeater procurement by telecom operators.
- Gallium nitride semiconductor advances:Power amplifier efficiency gains enable smaller form factors and reduced thermal management costs in outdoor cellular repeaters.
Market Restraints
- Gallium nitride price volatility:Supply concentration among limited foundry operators creates input cost instability for radio frequency chain manufacturers.
- Multi-jurisdiction certification burden:Parallel CE marking, FCC Part 20, and MIIT GB standards fragment vendor testing budgets and extend product launch timelines.
- Fiber optic substitution threat:Long-haul backhaul projects increasingly favor optical transport over amplified radio links in greenfield infrastructure.
Strategic Opportunities
- Agricultural telemetry backhaul:Low-power wide-area IoT repeaters for sensor networks remain underdeployed in precision farming regions.
- Public safety frequency mandates:Hardened outdoor units for first responder networks face mandated replacement cycles in multiple jurisdictions.
- Enterprise indoor densification:Channel partnerships with systems integrators unlock recurring deployment revenue in commercial real estate verticals.
Industry Challenges
- Radio frequency engineering talent scarcity:Specialized expertise in interference mitigation and spectrum coexistence commands premium compensation.
- Legacy analog integration friction:Public safety networks with slow replacement cycles require backward-compatible digital migration paths.
- Field trial duration in India:WPC authorization through the Department of Telecommunications imposes extended validation periods for imported equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Communication Repeater Market |
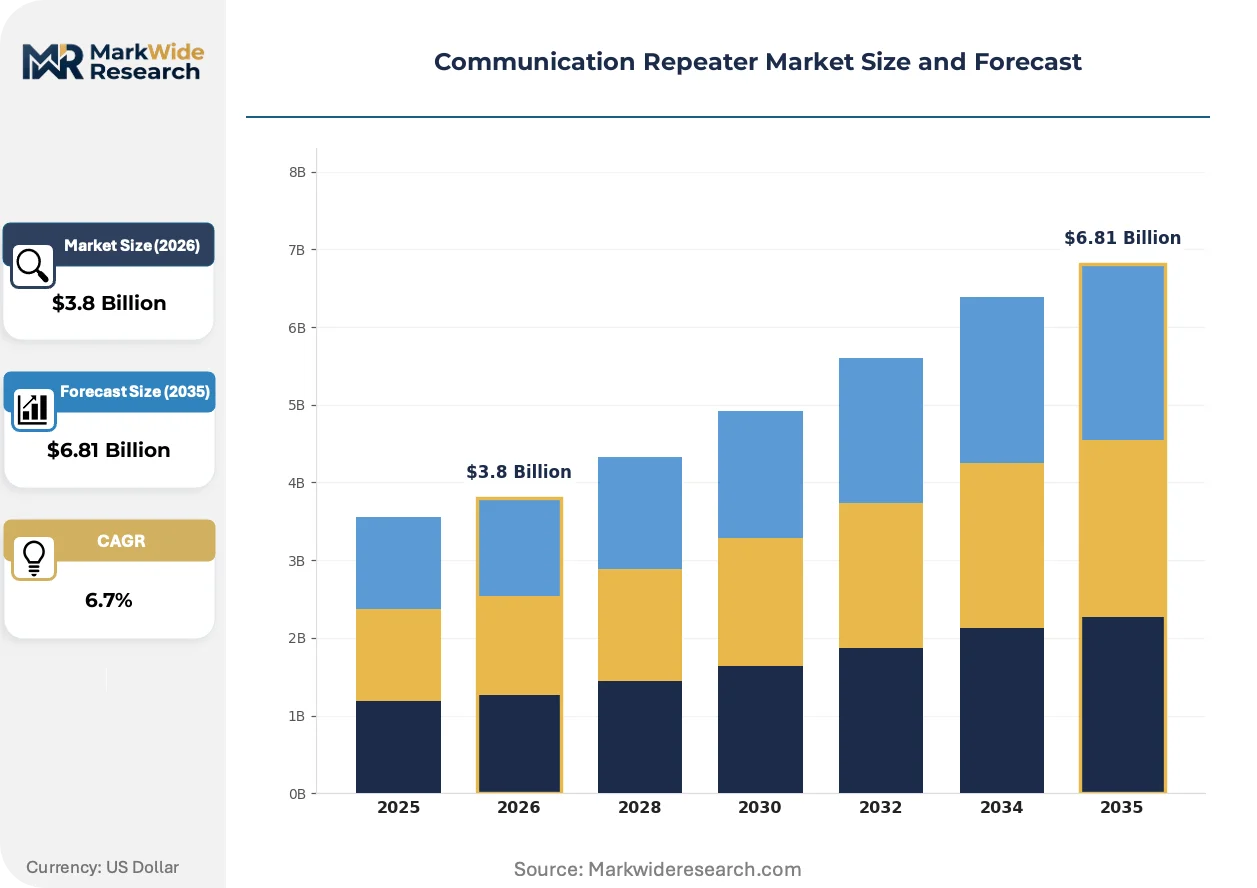
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Repeaters, Outdoor Repeaters, Cellular Repeaters, IoT Repeaters Technology: Analog Technology, Digital Technology, Voice over Internet Protocol, Fiber Optic Technology End User: Telecom Operators, Enterprises, Government Agencies, Residential Users Deployment Model: On-Premises, Cloud-Based, Hybrid, Dedicated Solutions |
| Companies Covered | JDTECK, Smoothtalker, Nextivity, Inc., MaxComm, Huaptec, Ritron, Inc., Stelladoradus, Cel-Fi, Codan Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Communication Repeater Market Evolving Landscape
Digital signal processing architectures are displacing analog chains across all power classes, compressing equipment footprints while enabling software-defined reconfiguration for shifting spectrum allocations.
Software-defined radio platforms is modularizing repeater architectures by separating baseband processing from radio frequency front-ends. Rural carriers in India's tier-2 corridors adopt these configurations to reduce sparing inventory. The approach is modularizing supply chains, allowing independent upgrades to processing modules without full hardware replacement.
EU Radio Equipment Directive enforcement is tightening electromagnetic compatibility documentation for signal boosters. Manufacturers face expanded technical file requirements and notified body involvement. Cellular repeater vendors targeting European markets are restructuring quality management systems to accommodate sequential CE marking audits.
Enterprise buyers now specify outcome-based coverage guarantees rather than equipment-centric procurement. Systems integrators displace direct vendor relationships by assuming performance risk for indoor deployments. This pattern concentrates in North American commercial real estate where landlord-tenant service agreements demand measurable signal quality metrics.
Communication Repeater Market Segmentation
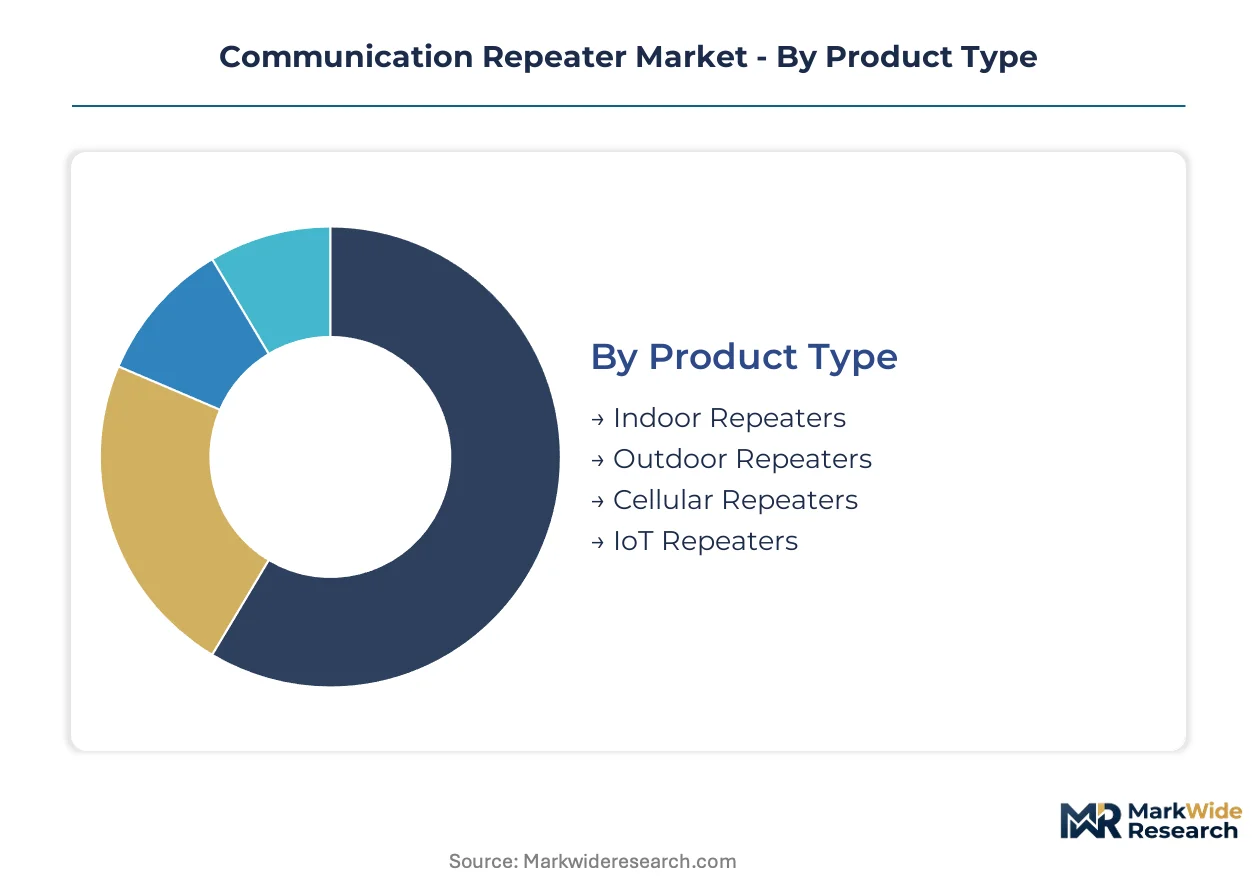
Communication repeater procurement patterns diverge sharply across deployment contexts, with certification requirements and power constraints fragmenting vendor addressable markets. Equipment specifications must align precisely with spectrum licensing conditions in each operating jurisdiction.
Product Type:
Supply concentration among gallium nitride foundries favors manufacturers with scale to secure power amplifier allocations for high-output outdoor units.
- Cellular Repeaters:These devices amplify licensed mobile spectrum across sub-6 GHz bands with automatic gain control mandated by FCC Part 20. India's tier-2 city corridors drive procurement volume as Bharti Airtel and Reliance Jio densify coverage without base station builds.
- Outdoor Repeaters:Hardened enclosures withstand temperature extremes and moisture ingress for tower-mounted or rooftop installations. Public safety frequency mandates in the United States and Germany force replacement cycles for legacy analog units.
- Indoor Repeaters:Lower power output and compact form factors serve enterprise densification in commercial real estate.
- IoT Repeaters:Low-power wide-area protocol support enables agricultural telemetry backhaul in precision farming regions.
Cellular repeaters absorb the bulk of installed capacity; IoT repeaters are expanding most quickly.
Technology:
Cost tier stratification separates premium fiber optic transport from economy analog equipment with minimal signal processing.
- Fiber Optic Technology:Minimal signal degradation over long-haul links commands premium pricing for carrier backhaul applications. Greenfield infrastructure projects in Germany and Japan increasingly specify optical transport over amplified radio links.
- Digital Technology:Software-defined reconfiguration enables rapid adaptation to mid-band 5G refarming without hardware replacement. Rural carriers in India adopt modular architectures to reduce sparing inventory costs.
- Analog Technology:Legacy public safety networks in the United States maintain slow replacement cycles.
- Voice over Internet Protocol:Packet-switched voice transport integrates with enterprise unified communications platforms.
Digital technology captures the majority of new equipment procurement; fiber optic technology delivers the steepest expansion trajectory in long-haul applications.
End User:
Volume concentration among telecom operators creates procurement leverage that squeezes margin for mid-tier equipment vendors.
- Telecom Operators:Licensed spectrum holders deploy carrier-grade repeaters under regulatory mandates for rural coverage expansion. FCC broadband infrastructure requirements and analogous German spectrum efficiency rules tighten certification burdens.
- Enterprises:Commercial real estate landlords specify outcome-based coverage guarantees through systems integrator relationships. North American channel partnerships with firms like Nextivity sustain recurring deployment revenue.
- Government Agencies:First responder networks require hardened outdoor units with public safety frequency compatibility.
- Residential Users:Consumer-grade signal boosters face import restrictions under FCC Part 20 automatic gain control requirements.
Telecom operators dominate unit volume; enterprises are gaining share fastest as indoor densification accelerates.
Deployment Model:
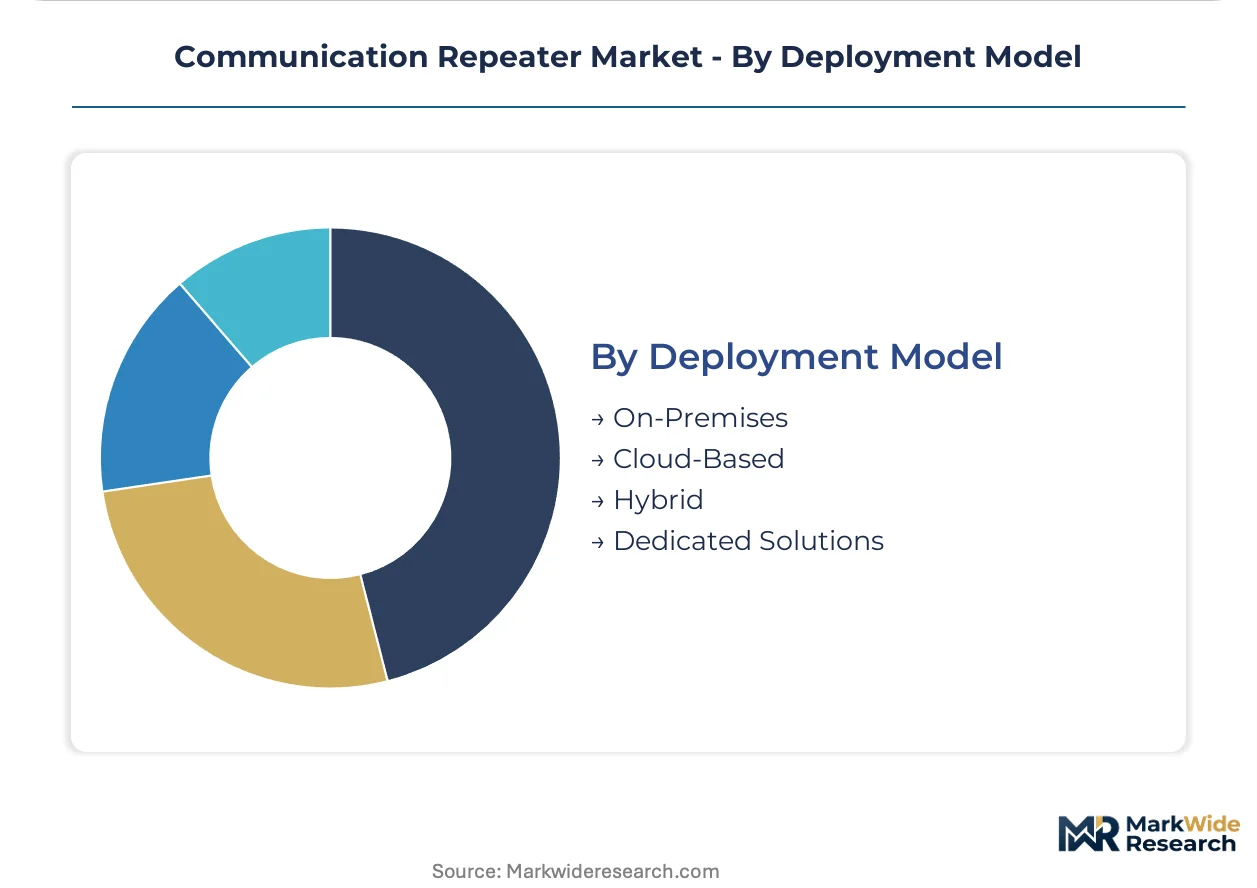
Customer type preferences fragment between capital-intensive on-premises ownership and operational expenditure models.
- On-Premises:Enterprise and government buyers favor perpetual licensing with direct hardware ownership for security-sensitive installations. India's WPC authorization process imposes extended field trials for imported equipment regardless of deployment model.
- Cloud-Based:Software-defined radio platforms enable remote configuration management and over-the-air updates. Managed service providers assume performance risk for coverage outcomes.
- Hybrid:Split architectures combine local radio frequency processing with cloud-hosted baseband functions.
- Dedicated Solutions:Custom-engineered systems serve unique spectrum environments or interference conditions.
On-premises deployment retains the majority of legacy installed base; cloud-based models are climbing the fastest among greenfield enterprise installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's tier-2 city corridors concentrate procurement volume as mobile density outpaces base station deployment. FCC mandates in the United States and spectrum efficiency rules in Germany tighten certification requirements across their respective markets. China's manufacturing scale anchors component supply for radio frequency chains worldwide.
United States
Telecom operators accelerate rural coverage expansion through digital repeater procurement. FCC Part 20 certification mandates automatic gain control and network protection safeguards that block uncertified imports. Enterprise indoor deployments concentrate through North American channel partnerships in commercial real estate verticals.
Germany
Spectrum efficiency rules under EU Radio Equipment Directive enforcement tighten electromagnetic compatibility documentation requirements. Greenfield infrastructure projects increasingly specify fiber optic transport over amplified radio links for long-haul backhaul. Industrial clusters in Bavaria and Baden-Württemberg host systems integrators serving enterprise densification contracts.
India
Bharti Airtel and Reliance Jio densify coverage in tier-2 urban peripheries without base station builds. WPC frequency authorization through the Department of Telecommunications imposes extended field trials for imported equipment. Procurement concentrates in Maharashtra and Karnataka corridors where mobile subscriber density exceeds infrastructure deployment.
China
MIIT GB standards administer parallel compliance tracks that fragment vendor testing budgets alongside CE marking and FCC regimes. Manufacturing scale in the Yangtze River Delta and Pearl River Delta anchors cost-optimized cellular repeater production for Asia-Pacific markets. Domestic foundry capacity for gallium nitride semiconductors influences power amplifier supply security.
Japan
METI industrial policy supports fiber optic technology adoption for minimal signal degradation in long-haul carrier backhaul. Greenfield infrastructure specifications in Tokyo-Osaka corridors favor optical transport architectures. Precision farming regions in Hokkaido and Tohoku deploy low-power wide-area IoT repeaters for agricultural telemetry networks.
Communication Repeater Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek certification expertise and channel access across fragmented regulatory jurisdictions. The vendor base organizes around three tiers: multinational equipment conglomerates with full certification portfolios, regional specialists leveraging geographic proximity to demand clusters, and component-focused fabricators supplying radio frequency chains. Two archetypes define competitive positioning: certification-heavy incumbents defending protected demand corridors, and modular architecture innovators enabling software-defined reconfiguration. Geographic expansion and technology licensing represent the dominant competitive moves as firms navigate multi-jurisdiction compliance burdens.
Within the North American channel-focused tier, Nextivity, Inc. and Ritron, Inc. exemplify divergent specialization strategies. Nextivity occupies a position anchored in enterprise indoor densification through systems integrator relationships. Ritron sits within the hardened outdoor unit segment serving public safety frequency mandates. Huaptec represents the Asia-Pacific manufacturing scale archetype, positioned to supply cost-optimized cellular repeaters for regional demand concentration. These three firms illustrate how competitive positioning fragments across certification geography, deployment environment, and supply chain configuration rather than converging on unified product strategies.
| Leading Market Players |
|---|
| JDTECK |
| Smoothtalker |
| Nextivity, Inc. |
| MaxComm |
| Huaptec |
| Ritron, Inc. |
| Stelladoradus |
| Cel-Fi |
| Codan Communications |
| Others |
Value Network & Pricing Analysis
Gallium nitride power amplifier costs cascade through three distinct equipment tiers, with foundry concentration in China's Yangtze River Delta and Taiwan straining mid-market vendors serving India's tier-2 procurement corridors. FCC Part 20 certification burdens in the United States and WPC field trial requirements in India fragment compliance spending, compressing margins for non-integrated assemblers while securing premium capture for certified domestic producers.
Pricing Analysis
Volume procurement by Bharti Airtel and Reliance Jio in India compresses unit economics for standard cellular repeaters, while fiber optic long-haul configurations command residual premium in German and Japanese greenfield projects. Price differentiation hinges on certification tier—FCC Part 20, CE marking under EU Radio Equipment Directive, and MIIT GB standards—and on volume scale commitments from telecom operators. Pricing pressure stems from gallium nitride semiconductor cost volatility among limited foundry operators. Residential consumer-grade signal boosters face acute price sensitivity under import restrictions, whereas enterprise indoor deployments through systems integrators absorb moderate premium for outcome-based coverage guarantees.
Supply Chain Analysis
India's phased manufacturing program and local-content preferences in Department of Telecommunications procurement are reshaping component sourcing for equipment destined for Maharashtra and Karnataka corridors. Manufacturing concentration centers on China, Taiwan, and South Korea for gallium nitride semiconductors and radio frequency chains, with Germany and the United States retaining specialized foundry capacity for public-safety-grade hardened enclosures. Raw material dependencies span gallium nitride substrates, aluminum enclosures for thermal management, and precision coaxial connectors. Single-source vulnerability in gallium nitride foundry capacity poses structural risk. Distribution runs through telecom operator direct procurement, systems integrator channels for enterprise verticals, and authorized distributor networks for government agency mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital signal processing architectures are displacing analog chains across all power classes, compressing equipment footprints while enabling software-defined reconfiguration for shifting spectrum allocations.
For Market Incumbents: Anchor certification portfolios across FCC Part 20, CE marking, and MIIT GB standards to defend protected demand corridors against modular architecture innovators. Deepen backward integration into gallium nitride power amplifier sourcing to offset foundry price volatility. Prioritize channel control through systems integrator relationships in North American commercial real estate verticals. For New Entrants and Emerging Players: Capture agricultural telemetry backhaul white space in precision farming regions of Japan's Hokkaido and Tohoku corridors, where low-power wide-area IoT repeaters remain underdeployed. Target India's tier-2 city corridors through modular software-defined radio platforms that reduce sparing inventory costs for rural carriers. Pursue go-to-market alignment with managed service providers assuming performance risk for coverage outcomes. For Investors and Strategic Acquirers: Mid-band 5G refarming announcements from major spectrum regulators are the leading indicator that hardware refresh cycles will accelerate replacement demand across installed repeater bases. Long-term viability favors vendors with software-defined reconfiguration capabilities over legacy analog-dependent assemblers. Monitor acquisition targets with modular architecture expertise and established certification pathways across multiple jurisdictions. Spectrum reallocation timelines in major economies signal inflection points for hardware refresh decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | Parallel FCC Part 20, CE marking, and MIIT GB compliance unlocks protected demand corridors across United States, Germany, and China. |
| Software-Defined Radio Platform Development | Modular architectures separating baseband processing from radio frequency front-ends enable rapid adaptation to mid-band 5G refarming. |
| Systems Integrator Channel Partnership | Outcome-based coverage guarantees through North American commercial real estate relationships displace direct vendor procurement. |
| Backward Integration into Gallium Nitride Sourcing | In-house power amplifier production mitigates foundry concentration risk among Yangtze River Delta and Taiwan operators. |
| Agricultural Telemetry Backhaul Deployment | Low-power wide-area IoT repeaters in Hokkaido and Tohoku precision farming regions address underpenetrated sensor network infrastructure. |
Research Methodology
Document review covered FCC Part 20 certification databases, EU Radio Equipment Directive technical files, MIIT GB standard registrations, and WPC frequency authorization records, complemented by interviews with radio frequency engineering directors at telecom operators, procurement leads at systems integrators, regulatory affairs managers at equipment vendors, and foundry operations specialists at gallium nitride semiconductor manufacturers. Secondary validation drew from customs trade data for repeater equipment, SEC filings of listed communications infrastructure firms, and spectrum reallocation notices from national regulators. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segment-level projections across product type, technology, end user, and deployment model dimensions informed aggregate market sizing across the analysis window. CAGRs derived from regression analysis of historical procurement patterns against spectrum licensing timelines and infrastructure deployment schedules. Industry-specific forecast inputs incorporated mid-band 5G refarming timelines, gallium nitride foundry capacity expansion announcements, and rural coverage obligation mandates in India and the United States.
The model holds under stable regulatory certification requirements and predictable spectrum allocation timelines; deviation in accelerated refarming schedules or trade restriction escalations would shift equipment refresh velocity and geographic sourcing patterns. Forecasts reflect documented assumptions regarding foundry capacity growth, operator capital expenditure commitments, and systems integrator channel penetration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
China Telecom Towers Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
Kenya Telecom Tower Market
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
Japan Telecom Market
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market
Telecommunications Infrastructure
Global Telecom System Integration Market
Telecommunications Infrastructure
Carrier Infrastructure in Telecom Applications Market
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market