
 Global Assistive Technologies for Visually Impaired Market | 2026-2036
Global Assistive Technologies for Visually Impaired Market Size, Share, and Industry Trends Forecast 2026-2036
Global Assistive Technologies for Visually Impaired Market Foresight
Aftermarket service revenue is reconfiguring competitive economics in assistive technology distribution. Apple leverages its VoiceOver ecosystem to dominate mobile accessibility. HumanWare Group specializes in dedicated Braille hardware for education and rehabilitation settings. OrCam Technologies Ltd. differentiates through portable text-to-speech devices for workplace and daily living applications.
Assistive technologies for visually impaired encompass hardware and software systems that convert visual information into auditory, tactile, or enhanced visual outputs using speech synthesis, refreshable Braille cells, and optical character recognition engines. These systems primarily enable independent navigation, digital content consumption, and professional participation for individuals with blindness or low vision. Screen Readers and Braille Displays anchor the technology segment, with Optical Character Recognition representing the fastest-expanding capability as smartphone integration accelerates. Education and Workplace Accessibility applications command the largest share of institutional procurement, while Wearable Instruments and Cloud-Based Services deployment methods attract the highest-margin subscription and upgrade revenue.
The FDA regulates medical device classifications for certain assistive hardware in the United States, while the EU Accessibility Act and EMA frameworks mandate conformity assessment and digital inclusion standards across European markets. WHO guidelines on vision rehabilitation further shape national procurement policies and reimbursement eligibility for assistive products. Stakeholders must monitor evolving interoperability mandates between mainstream consumer electronics and dedicated accessibility platforms to anticipate procurement standard shifts.
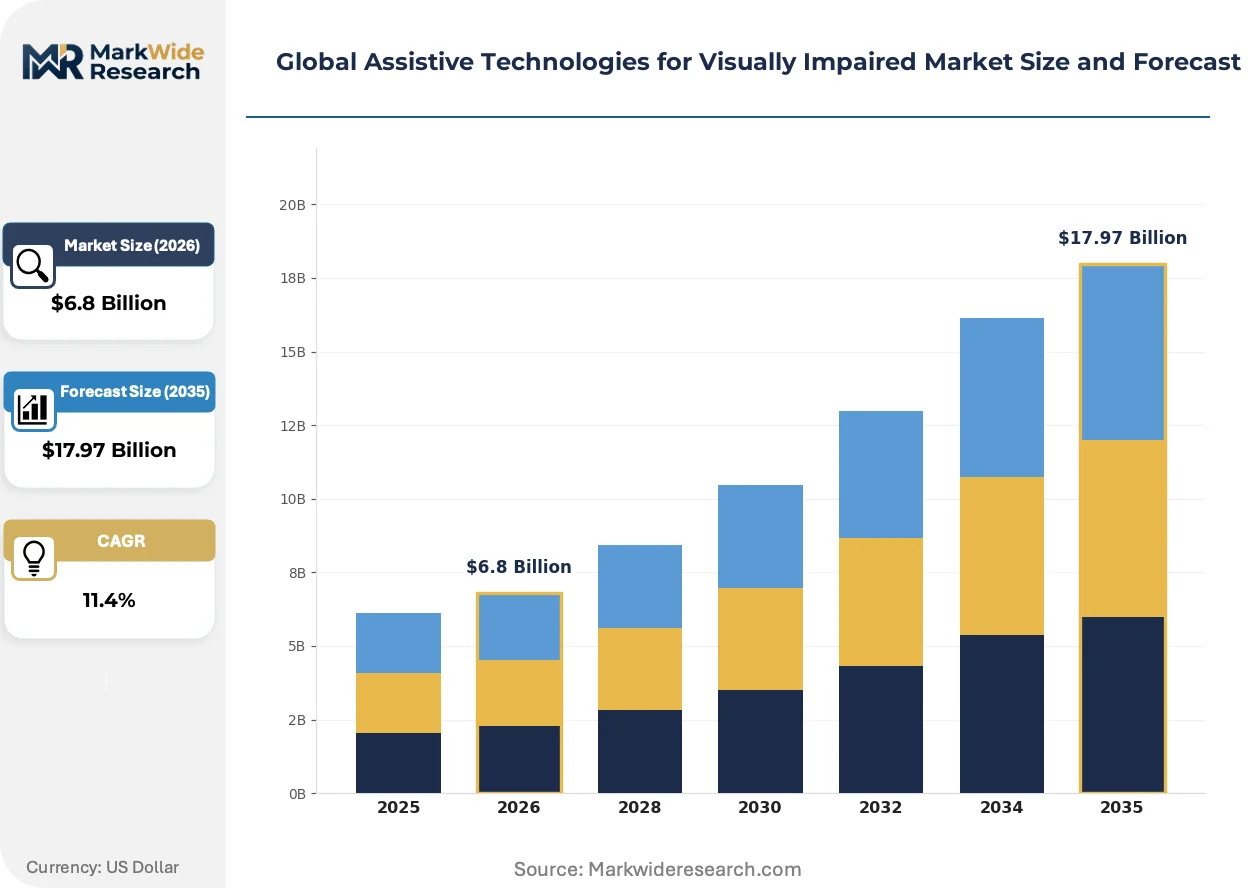
Market Dynamics
Integration between mainstream consumer electronics and dedicated accessibility platforms is compressing procurement cycles and forcing hardware specialists to differentiate through service bundling rather than device specifications alone.
Growth Catalysts
- Medicare and VA reimbursement policies:Sustained federal funding in the United States removes cost barriers for screen readers and Braille displays in rehabilitation settings.
- EU Accessibility Act mandates:Digital service compliance requirements across member states compel software vendors to embed native accessibility features.
- Refreshable Braille cell miniaturization:Advances in piezoelectric actuator manufacturing reduce hardware footprints for portable displays.
Market Restraints
- Specialized semiconductor supply concentration:Piezoelectric driver chips for refreshable Braille displays depend on limited Asian foundry capacity.
- FDA Class II device classification:Hardware with therapeutic claims faces extended premarket notification timelines and clinical data requirements.
- Smartphone native accessibility substitution:Built-in screen readers and magnification tools in iOS and Android reduce standalone device necessity for casual users.
Strategic Opportunities
- Workplace accessibility mandates in Germany:Federal employment quotas and inclusion subsidies drive enterprise procurement of assistive workstations.
- Cloud-based subscription services:Remote screen reader configuration and document accessibility auditing create recurring revenue streams independent of hardware sales.
- Optical character recognition and edge AI convergence:On-device text recognition without cloud dependency addresses privacy-sensitive institutional deployments.
Industry Challenges
- Rehabilitation specialist certification bottlenecks:Qualified orientation and mobility instructors remain scarce relative to device deployment targets.
- Interoperability testing complexity:Compatibility validation across proprietary Braille codes and third-party software platforms extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Assistive Technologies for Visually Impaired Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Screen Readers, Braille Displays, Optical Character Recognition, Text-to-Speech, Magnification Software, Audio Description Application: Education, Workplace Accessibility, Navigation Assistance, Communication Enhancement, Leisure Activities, Daily Living Support End User: Individuals with Low Vision, Schools for the Blind, Rehabilitation Centers, Private Therapy Providers, Nonprofit Organizations, Special Education Institutions Deployment Method: Mobile Devices, Desktop Platforms, Wearable Instruments, Cloud-Based Services, Embedded Systems, Dedicated Terminals |
| Companies Covered | Apple Inc., Google LLC, Microsoft Corporation, Vispero, HumanWare Group, OrCam Technologies Ltd., Aira Tech Corp., Freedom Scientific, Dolphin Computer Access Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Assistive Technologies for Visually Impaired Market Shifts & Advancements
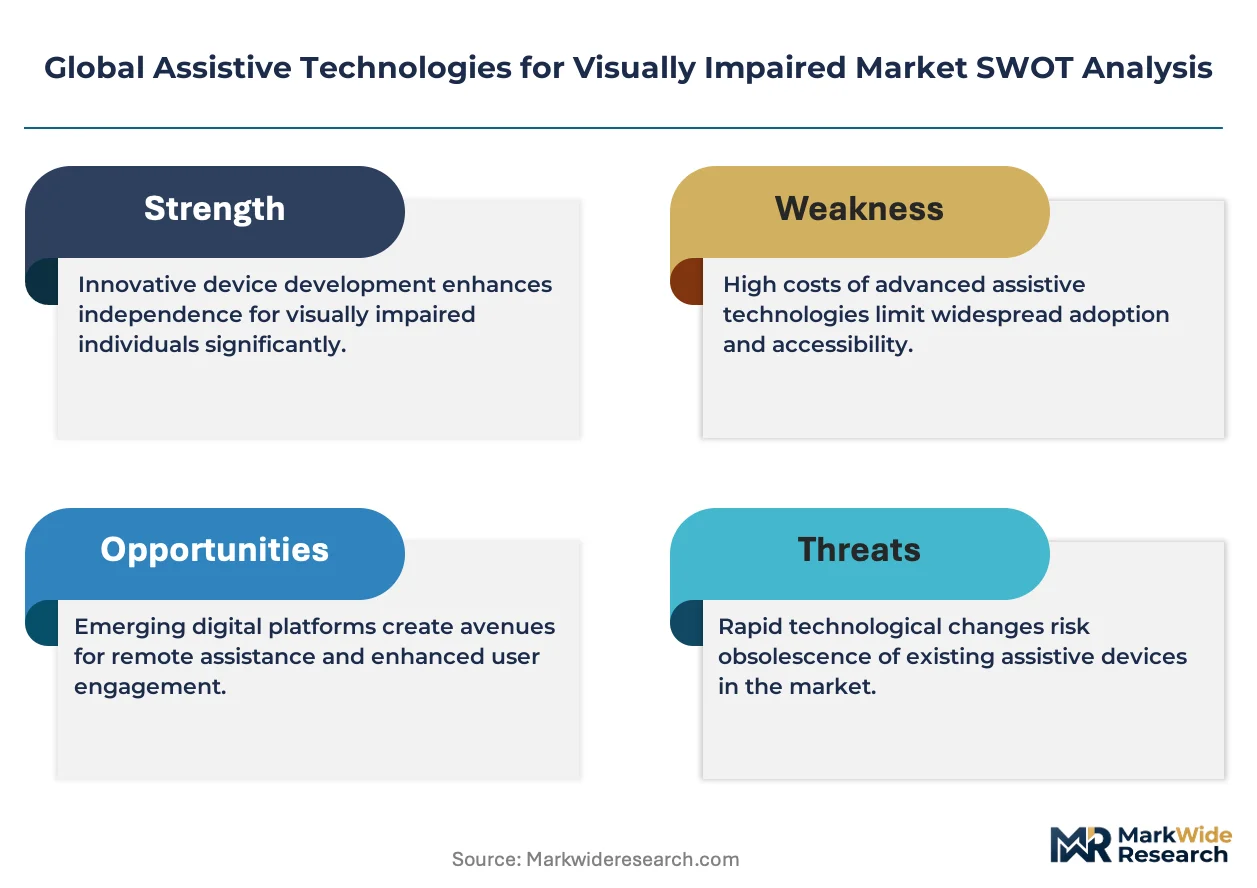
Assistive technology architectures are fragmenting between closed ecosystems and open standards, with procurement decisions increasingly driven by interoperability certifications rather than hardware specifications alone.
Multimodal sensory substitution systems are hybridizing tactile, auditory, and haptic feedback into unified navigation devices. Rehabilitation centers in the United States and Germany are piloting these integrated platforms for indoor wayfinding. The technology is hybridizing previously separate device categories into single-unit procurement decisions that compress vendor selection cycles.
REACH and RoHS substance restrictions in the European Union are forcing material substitutions in Braille display manufacturing. Piezoelectric actuator suppliers must reformulate ceramic compositions to eliminate restricted heavy metals. Medical device manufacturers serving European institutional buyers are accelerating supply chain audits to maintain CE marking eligibility.
Subscription-based accessibility software licensing is displacing perpetual license models in North American education procurement. State-level purchasing cooperatives now favor annual service agreements with remote technical support inclusion. K-12 districts and universities represent the vertical where this shift is most pronounced, with multi-year enterprise agreements replacing individual device sales.
Global Assistive Technologies for Visually Impaired Market Segmentation
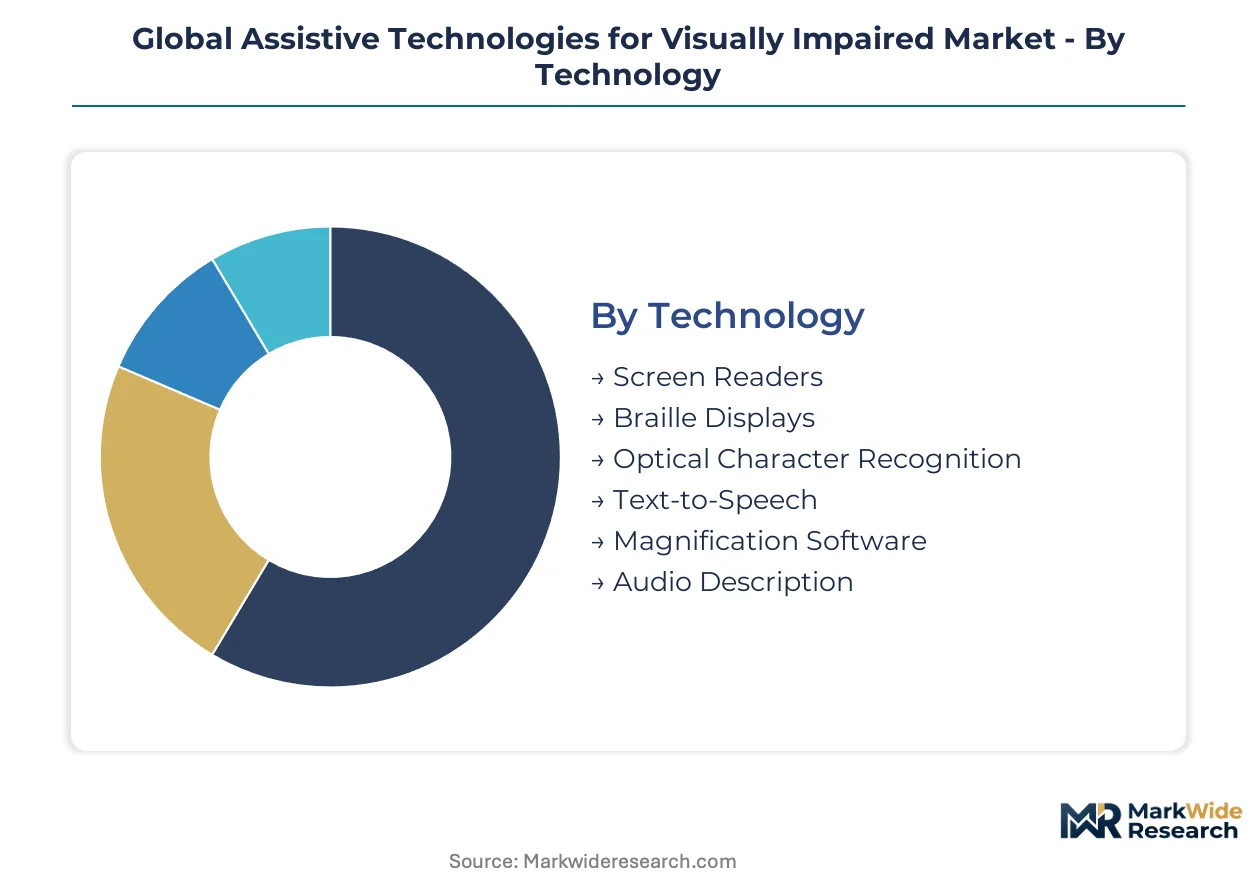
Assistive technology procurement decisions fragment across four intersecting dimensions. Technology type determines hardware versus software spend ratios. Application context shapes institutional reimbursement eligibility and feature prioritization.
Technology:
Use-case spectrum spans casual digital consumption to intensive professional workflows, with each technology tier serving distinct functional intensity requirements.
- Screen Readers:Software platforms convert visual interface elements into synthesized speech or Braille output through system-level APIs. Medicare and VA reimbursement policies in the United States sustain procurement for rehabilitation settings, though smartphone native accessibility tools compress standalone demand for casual users.
- Braille Displays:Refreshable tactile output devices employ piezoelectric actuators to raise and lower Braille cells dynamically. Schools for the Blind across Germany and the United States anchor institutional procurement volumes, with REACH and RoHS compliance mandates in the European Union forcing ceramic formulation changes in actuator manufacturing.
- Optical Character Recognition:On-device text recognition without cloud dependency addresses privacy-sensitive institutional deployments.
- Text-to-Speech:Document and web content narration engines integrate with mainstream productivity software.
- Magnification Software:Screen enlargement tools with contrast enhancement serve low-vision users retaining partial sight.
- Audio Description:Narrated visual content tracks for broadcast and streaming media accessibility compliance.
Established volume favors Braille Displays; emerging adoption favors Optical Character Recognition.
Application:
Cost tier stratification separates subsidized institutional procurement from out-of-pocket consumer purchases, with reimbursement eligibility determining addressable market scope.
- Education:K-12 districts and universities drive subscription-based software licensing displacement of perpetual models in North American procurement. State-level purchasing cooperatives favor annual service agreements with remote technical support inclusion.
- Workplace Accessibility:Federal employment quotas and inclusion subsidies in Germany drive enterprise procurement of assistive workstations. Rehabilitation centers in the United States pilot multimodal sensory substitution systems for indoor wayfinding.
- Navigation Assistance:GPS-enabled mobility tools with haptic feedback support independent travel.
- Communication Enhancement:Real-time transcription and alternative input methods facilitate interpersonal exchange.
- Leisure Activities:Gaming and media accessibility features expand addressable user base.
- Daily Living Support:Appliance labeling and medication identification tools assist household independence.
Reimbursement concentration favors Education; self-funded procurement favors Daily Living Support.
End User:
Customer type determines procurement authority structure, with institutional buyers operating through competitive bidding versus individual direct purchase.
- Individuals with Low Vision:Direct consumers navigate fragmented insurance coverage and out-of-pocket cost barriers.
- Schools for the Blind:Specialized institutions expanding procurement of screen readers and Braille displays represent concentrated volume anchors.
- Rehabilitation Centers:Clinical settings integrate device prescription with orientation and mobility training.
- Private Therapy Providers:Independent practitioners recommend solutions without direct procurement authority.
- Nonprofit Organizations:Advocacy groups facilitate device donation and loan programs.
- Special Education Institutions:Mainstream schools with disability inclusion mandates drive software licensing volume.
Procurement scale favors Schools for the Blind; service integration favors Rehabilitation Centers.
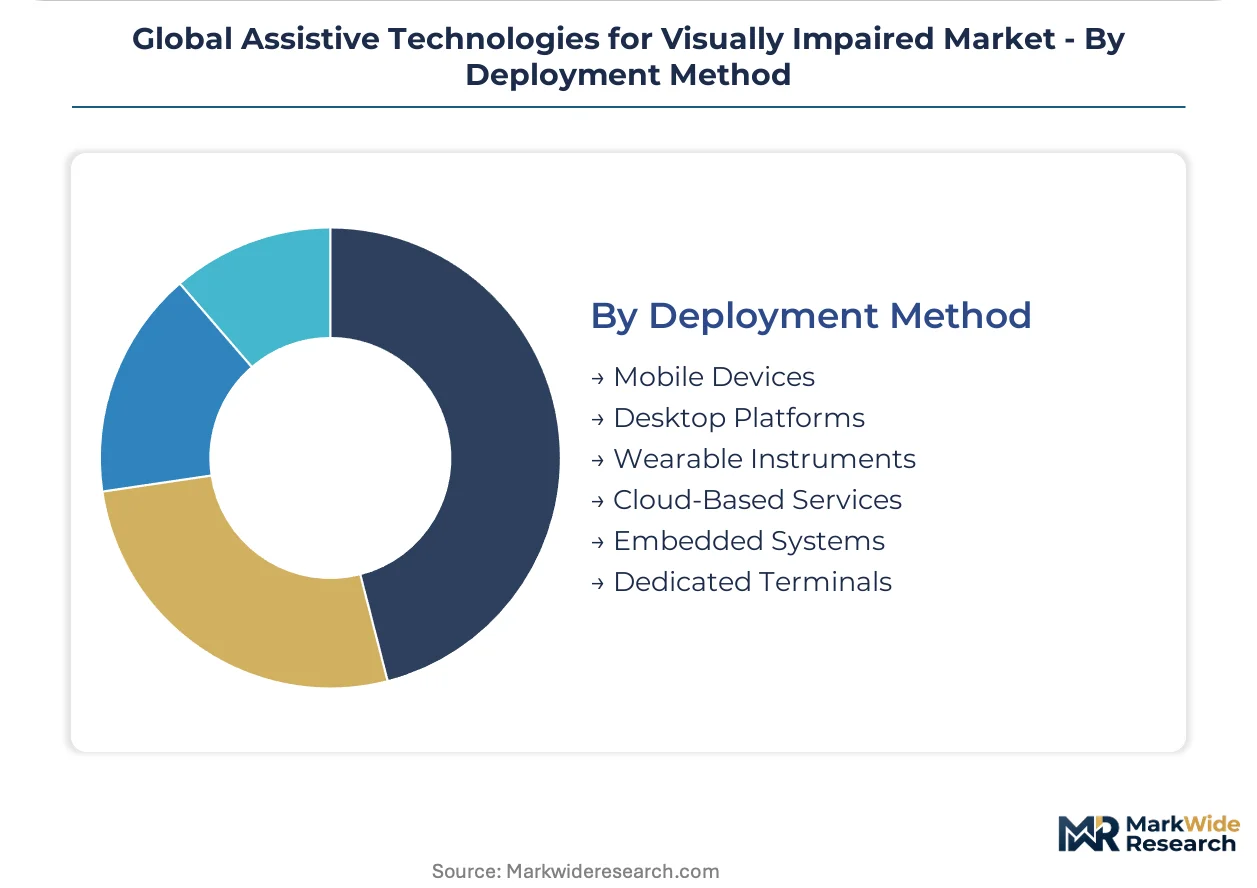
Deployment Method:
Supply concentration in semiconductor foundries and cloud infrastructure operators shapes hardware availability and subscription pricing power.
- Mobile Devices:iOS and Android native accessibility ecosystems dominate consumer reach.
- Desktop Platforms:Windows and macOS screen readers retain professional workflow dominance.
- Wearable Instruments:Attract highest-margin subscription and upgrade revenue in emerging product categories.
- Cloud-Based Services:Remote screen reader configuration and document accessibility auditing create recurring revenue streams independent of hardware sales.
- Embedded Systems:Fixed-function devices in public kiosks and transportation infrastructure.
- Dedicated Terminals:Single-purpose hardware for specialized institutional deployments.
Margin capture favors Cloud-Based Services; unit volume favors Mobile Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized semiconductor foundries in Taiwan and South Korea supply piezoelectric driver chips that constrain global refreshable Braille display output. Distribution networks for assistive hardware concentrate through rehabilitation procurement channels in the United States and Germany. Regulatory divergence between FDA medical device frameworks and EU accessibility mandates fragments certification pathways.
United States
Medicare and Veterans Affairs reimbursement policies sustain institutional procurement of screen readers and Braille displays for rehabilitation settings. FDA Class II device classification applies to hardware with therapeutic claims, extending premarket notification timelines. Boston and Minneapolis-St. Paul anchor specialized training centers where orientation and mobility instructors certify device deployment protocols.
Germany
Federal employment quotas and workplace inclusion subsidies drive enterprise procurement of assistive workstations for visually impaired employees. The EU Accessibility Act mandates digital service compliance across member states, compelling software vendors to embed native accessibility features. Munich and Stuttgart host rehabilitation technology clusters where multimodal sensory substitution systems undergo clinical piloting for indoor wayfinding.
United Kingdom
NHS vision rehabilitation services coordinate device prescription with community-based training programs. The Equality Act 2010 and Public Sector Bodies Accessibility Regulations enforce digital inclusion standards across government services. London and Manchester concentrate nonprofit advocacy organizations that facilitate device donation and loan programs for low-income users.
Japan
Ministry of Health, Labour and Welfare guidelines shape national procurement policies for assistive products in aging populations. METI standards on information accessibility mandate smartphone and public kiosk compatibility. Tokyo and Osaka metropolitan areas host specialized Schools for the Blind that anchor institutional demand for refreshable Braille hardware.
Australia
NDIS individual funding packages remove cost barriers for assistive technology acquisition among working-age adults with vision impairment. TGA medical device regulations classify certain low-vision aids, requiring conformity assessment for therapeutic claims. Melbourne and Sydney rehabilitation centers integrate device prescription with occupational therapy services.
Global Assistive Technologies for Visually Impaired Market Competitive Landscape
Consumer technology conglomerates and dedicated accessibility specialists split the market across contrasting value capture models. The vendor base concentrates around three strategic archetypes: ecosystem-integrated platforms, hardware-focused specialists, and service-layer intermediaries. Dominant competitive moves include cloud-based subscription migration and multimodal sensory integration partnerships.
Within the ecosystem-integrated tier, Apple Inc. and Google LLC exemplify platform-scale positioning through native accessibility feature deployment. Microsoft Corporation occupies a position bridging enterprise software licensing with assistive tool integration. Among dedicated hardware specialists, HumanWare Group and OrCam Technologies Ltd. represent the specialist-manufacturer archetype, while Vispero anchors the rehabilitation-focused service bundling segment.
| Leading Market Players |
|---|
| Apple Inc. |
| Google LLC |
| Microsoft Corporation |
| Vispero |
| HumanWare Group |
| OrCam Technologies Ltd. |
| Aira Tech Corp. |
| Freedom Scientific |
| Dolphin Computer Access Ltd. |
| Others |
Supply & Pricing Matrix
Freight corridors connecting Taiwanese semiconductor foundries to German rehabilitation centers transmit cost volatility directly into Braille display pricing tiers, with piezoelectric actuator freight surcharges compressing margins for mid-tier hardware vendors while premium ecosystem-integrated platforms capture service-bundling premiums.
Pricing Analysis
After-sales service revenue tiers encompassing remote configuration support and extended warranty contracts now drive lifetime value capture across assistive technology portfolios. Subscription-based SaaS-tiered pricing stratifies across premium, standard, and economy levels, with differentiation anchored in certification grade (FDA Class II versus consumer-grade) and geographic delivery cost to institutional buyers. Cost compression in hardware-only transactional sales is intensifying because smartphone native accessibility tools erode standalone device necessity. K-12 procurement cooperatives exhibit highest price sensitivity; enterprise workplace accessibility buyers in Germany demonstrate lowest sensitivity due to federal inclusion subsidies.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese and South Korean foundries supplying piezoelectric driver chips, alongside Chinese EMS providers assembling refreshable Braille cell modules. Raw material dependencies center on lead-free ceramic formulations for RoHS-compliant actuators, rare-earth elements for precision motors, and specialized polymers for tactile surface overlays. Single-source vulnerability in piezoelectric driver chip fabrication creates supply chain risk exposure. Distribution runs through rehabilitation procurement channels and state-level education purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in assistive technology is approaching an inflection as Apple's VoiceOver ecosystem interoperability mandates force dedicated hardware vendors toward service-layer differentiation.
For Market Incumbents: Insulate hardware margins by deepening backward integration into piezoelectric actuator supply and securing exclusive rehabilitation center service contracts. The threat of smartphone native accessibility substitution demands certification investment in FDA Class II therapeutic claims to maintain reimbursement eligibility. Channel control through orientation and mobility instructor training programs creates switching costs.
For New Entrants and Emerging Players: Build out cloud-based subscription offerings targeting North American K-12 districts where perpetual license displacement creates white-space opportunity. The most penetrable segment combines document accessibility auditing with remote technical support. A direct-to-institution go-to-market angle bypasses established rehabilitation procurement gatekeepers.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate medical device divisions where assistive technology represents non-core revenue. Long-term viability hinges on recurring revenue attachment rates rather than hardware shipment volumes. The signal to watch as inflection indicator is interoperability certification adoption velocity across European institutional buyers.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Service Migration | Recurring revenue streams from K-12 districts displace perpetual software licenses. |
| Piezoelectric Supply Integration | Backward integration into Taiwanese foundry partnerships secures Braille display component access. |
| Multimodal Platform Development | Sensory substitution hybridization captures rehabilitation center pilot procurement in Germany. |
| EU Accessibility Act Certification | CE marking for interoperability opens member state institutional procurement channels. |
| Workplace Mandate Alignment | Federal quota compliance in Germany drives enterprise assistive workstation deployments. |
Research Methodology
A spread of perspectives from rehabilitation technology procurement officers, orientation and mobility instructors, biomedical engineers at Schools for the Blind, and GPO contracts managers converged on the working assumptions. Primary interviews combined with secondary validation from FDA 510(k) filings, EU Accessibility Act implementation guidance, CMS Medicare reimbursement databases, and WHO vision rehabilitation guidelines. Bottom-up unit demand modeling and top-down market sizing triangulation anchored volume estimates.
Demand-supply balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled encompass technology type, application context, end-user procurement authority, and deployment method complexity. CAGRs derived from historical reimbursement policy trajectories and institutional procurement cycle analysis. Industry-specific forecast inputs included Medicare coverage determination timelines and REACH substance restriction phase-in schedules.
Stress conditions across semiconductor foundry capacity utilization, federal reimbursement policy continuity, and EU interoperability certification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding piezoelectric actuator supply expansion and smartphone accessibility feature evolution. Quarterly review of institutional procurement bid volumes and rehabilitation specialist certification rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
China Digital Twin Market
Digital Solutions
Mobile Campaign Management Market
Digital Solutions
Customer Experience As a Service (Cxaas) Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Digital Certificates Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Global Digital Art Software Market
Digital Solutions
AQI App Market
Digital Solutions
Global Product Design and Development Market
Digital Solutions
AI Infrastructure Market
Digital Solutions
Web Performance Optimization (WPO) Solution Market
Digital Solutions
Latin America IT Market
Digital Solutions
Global Dock and Yard Management System Market