
 Next Generation Search Engines Market | 2026-2036
Next Generation Search Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Search Engines Market Intelligence
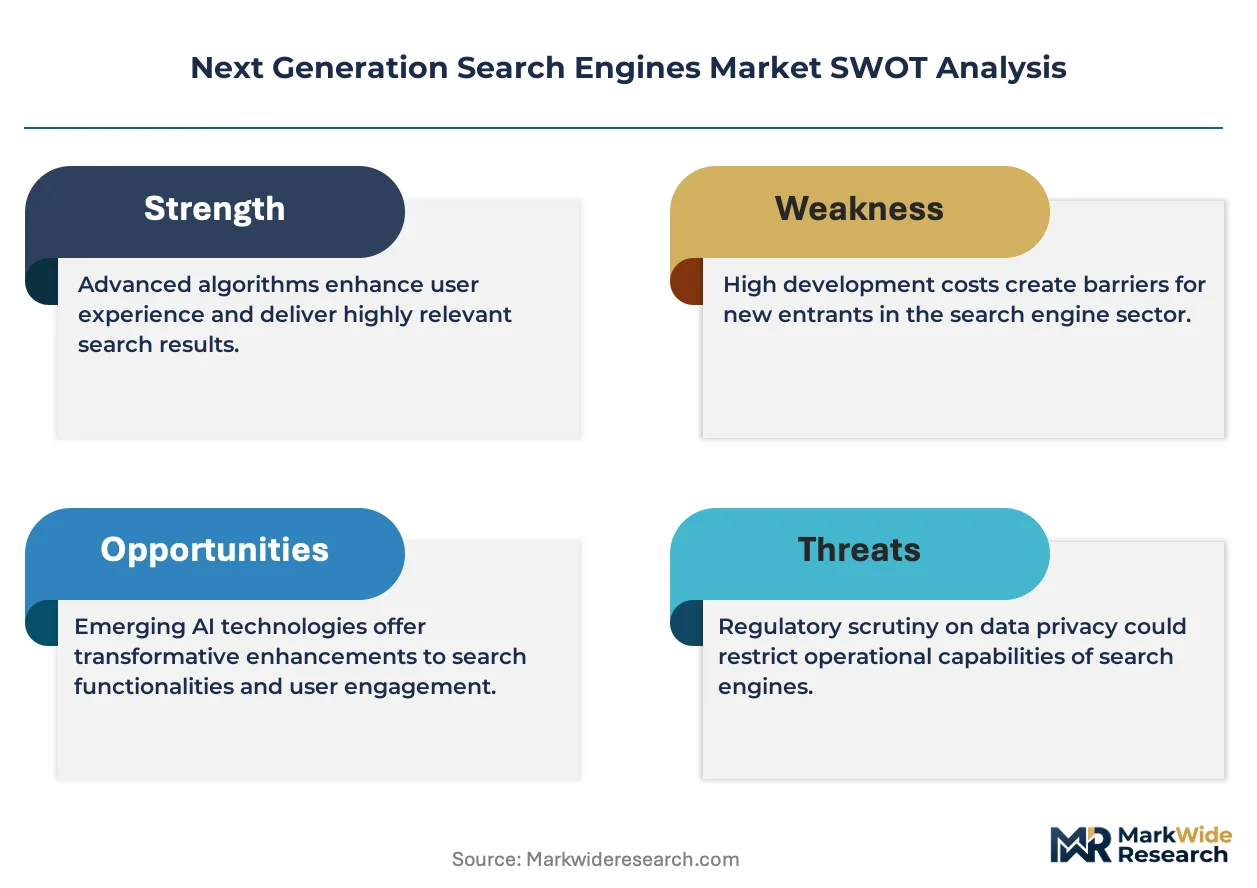
Multi-source data partnerships between foundation model providers and proprietary index operators is restructuring how search infrastructure gets built. Google LLC leverages its vertically integrated crawler-to-LLM pipeline to sustain inference cost advantages at scale. Microsoft anchors enterprise distribution through existing cloud productivity contracts, while Perplexity AI competes on citation transparency and real-time source freshness.
Next generation search engines are AI-native information retrieval systems that synthesize results from large language models, vector databases, and live web indexes rather than serving static ranked lists. Natural Language Processing capabilities now handle query intent disambiguation across multilingual corpora with sub-second latency requirements. Cloud-Based solutions lead deployment preference among businesses seeking elastic scaling without infrastructure ownership, while API Access offerings capture developer-driven integration demand across embedded applications. The E-commerce application segment concentrates margin pools where purchase-intent queries command premium placement economics.
The EU AI Act imposes transparency obligations on generative search outputs that force architectural changes to citation and provenance layers. The US Federal Trade Commission scrutinizes self-preferencing in AI-enhanced search result placement under existing antitrust frameworks. China's SAMR mandates algorithmic filing requirements for personalized information recommendation services, creating compliance friction for foreign index providers. Stakeholders must monitor how jurisdictional fragmentation in algorithmic accountability standards shapes product architecture decisions and market entry sequencing.
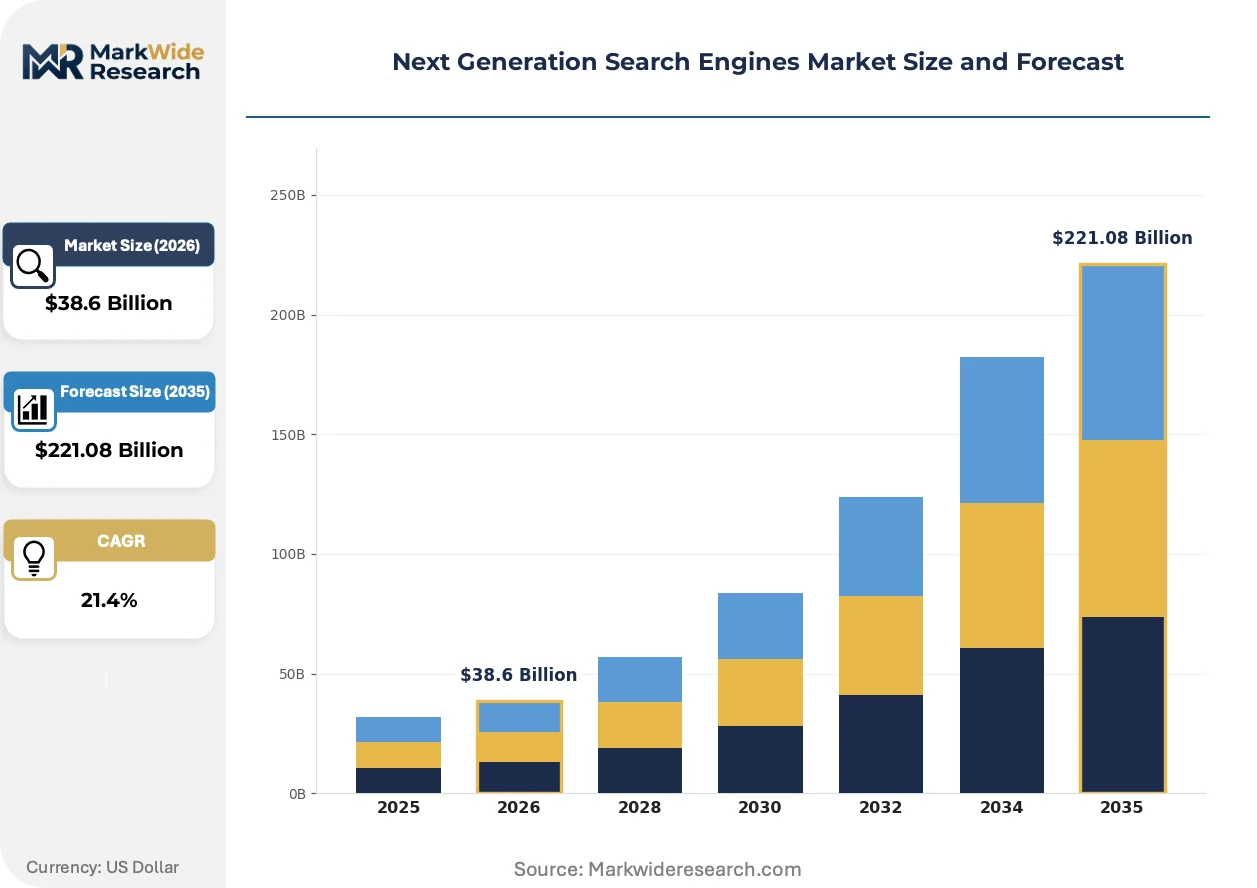
Market Dynamics
The transition from static ranked lists to AI-native synthesis engines is compressing traditional search monetization models while forcing infrastructure reinvestment in vector databases and inference clusters.
Growth Catalysts
- EU AI Act transparency mandates:Regulatory pressure on citation provenance is accelerating architectural upgrades that improve user trust metrics and retention.
- Enterprise knowledge management teams:These buyers are deploying AI-native retrieval systems to reduce internal document search friction and accelerate decision velocity.
- Hyperscaler infrastructure density:Concentrated cloud compute availability in the United States is lowering barrier-to-entry for generative search startups.
Market Restraints
- GPU supply concentration:Inference hardware dependency on Taiwan-based foundries creates vulnerability to geopolitical disruption and allocation constraints.
- Training data licensing friction:Proprietary content owners are restricting crawler access, fragmenting index completeness and raising acquisition costs.
- Latency-accuracy tradeoff:Sub-second response requirements force model compression that degrades synthesis quality for complex multilingual queries.
Strategic Opportunities
- Underpenetrated E-commerce verticals:Purchase-intent query monetization remains underdeveloped in fashion and home goods segments outside the United States.
- API Access channel expansion:Developer-driven embedded search integrations in SaaS applications represent a distribution path with lower customer acquisition cost than direct consumer competition.
- Cloud-Based deployment preference:Elastic scaling demand from mid-market enterprises without infrastructure ownership is creating a serviceable addressable segment distinct from hyperscaler-native buyers.
Industry Challenges
- Retrieval-augmented generation engineering talent:Scarce expertise in vector database optimization and prompt chaining is inflating compensation and slowing product iteration cycles.
- Legacy enterprise system integration:Knowledge graph migration from decades-old document management platforms requires custom pipeline development that extends implementation timelines.
- Cross-jurisdictional compliance architecture:Simultaneous satisfaction of EU AI Act transparency, SAMR algorithmic filing, and FTC self-preferencing scrutiny demands modular citation layers that increase engineering complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Search Engines Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $221.08 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Natural Language Processing, Machine Learning, Deep Learning, AI Algorithms Application: E-commerce, Online Advertising, Data Analytics, Content Discovery End User: Businesses, Developers, Marketers, Consumers Solution: Cloud-Based, On-Premises, Hybrid, API Access |
| Companies Covered | Google LLC (Alphabet Inc.), Microsoft, OpenAI, Perplexity AI, Apple Inc., Amazon.com Inc., Baidu Inc., Brave Software, Anthropic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Search Engines Market Strategic Shifts & Innovations
Foundation model providers and proprietary index operators are restructuring search infrastructure through multi-source data partnerships that bypass traditional crawler economics.
Retrieval-augmented generation is integrating live web indexes with parametric knowledge to reduce hallucination rates in real-time query responses. Enterprise procurement teams are adopting these systems for internal knowledge bases at pace, replacing legacy keyword search within eighteen-month refresh cycles. The technology is integrating citation provenance as a core architectural layer rather than an aftermarket compliance add-on.
The EU AI Act's risk classification framework for automated decision-making systems is forcing vendors to reconstruct output attribution mechanisms. Search providers must now expose source lineage and confidence scoring in ways that expose competitive indexing strategies. E-commerce application segments face the steepest compliance burden given their direct transaction influence and corresponding regulatory scrutiny.
Buyer procurement patterns are compressing vendor evaluation cycles as pilot-to-production timelines shrink from twelve months to ninety days. Enterprise IT departments are unbundling search procurement from existing cloud productivity contracts, creating direct purchasing relationships with specialized AI-native providers. This disintermediation is most visible in United States financial services verticals where compliance teams demand citation transparency that incumbent bundled solutions cannot provide.
Next Generation Search Engines Market Segmentation
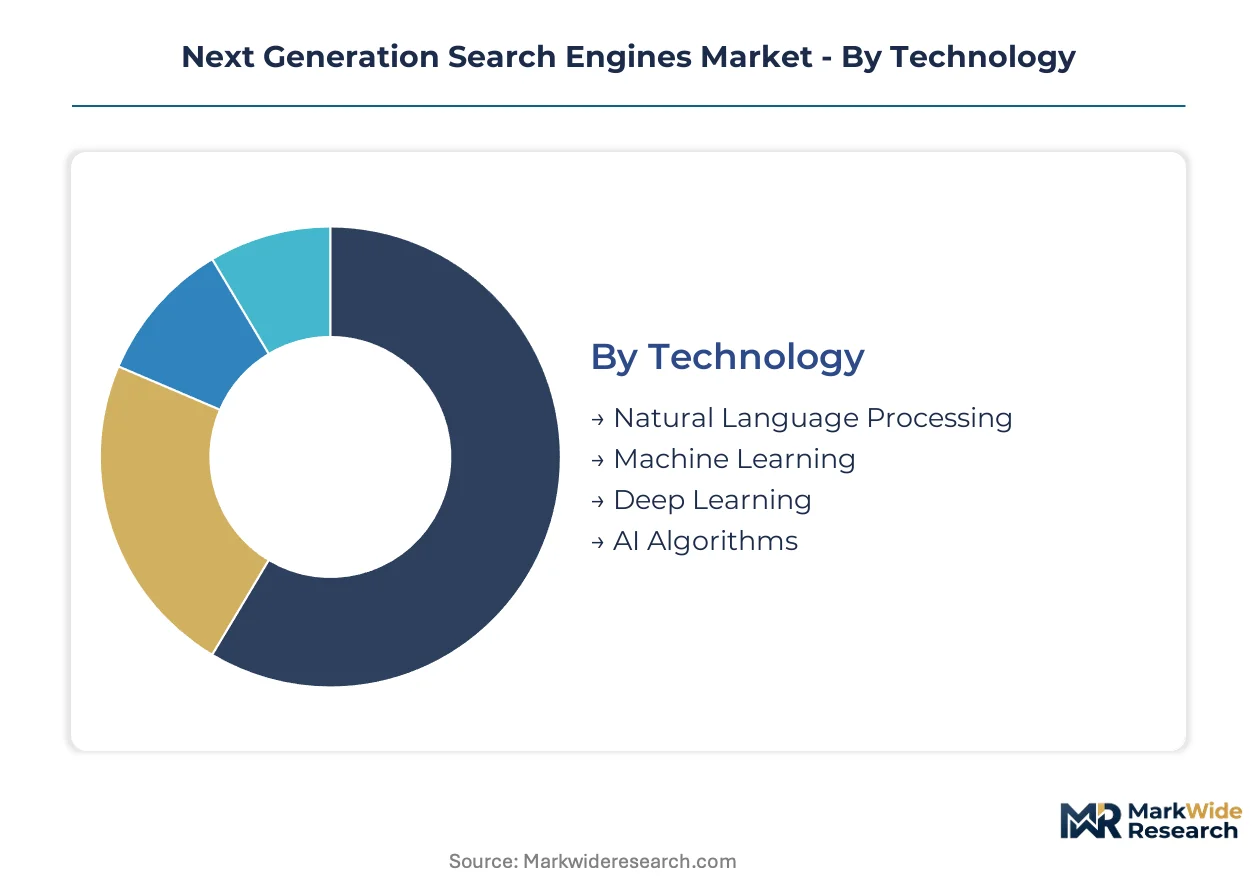
Next generation search engines fragment across four orthogonal dimensions that determine architectural requirements, deployment economics, and buyer procurement patterns. Technology selection dictates inference infrastructure investments. Application focus shapes monetization models and regulatory exposure. These segmentation axes reveal where vendor specialization creates defensible positioning versus where horizontal platforms dominate.
Technology:
Natural Language Processing capabilities anchor query understanding layers, with each technology stack demanding distinct hardware configurations and talent acquisition strategies.
- Natural Language Processing:Semantic parsing engines disambiguate intent across multilingual corpora with sub-second latency requirements. Enterprise knowledge management teams in the United States deploy these systems to reduce internal document search friction and accelerate decision velocity.
- Machine Learning:Ranking and personalization models optimize result relevance through continuous feedback loops. E-commerce platforms concentrate investment here where purchase-intent queries command premium placement economics and direct transaction influence.
- Deep Learning:Neural architectures enable embedding-based retrieval at scale. Vector database optimization expertise remains scarce, inflating compensation and slowing product iteration cycles for teams building on this stack.
- AI Algorithms:Broad category encompassing retrieval-augmented generation and prompt chaining techniques. Developer-driven demand concentrates in API Access channels seeking embedded search integrations.
Natural Language Processing leads on scale; Deep Learning leads on momentum.
Application:
End-use context determines compliance burden, with transaction-adjacent applications facing steeper regulatory scrutiny under the EU AI Act's risk classification framework.
- E-commerce:Purchase-intent query monetization remains underdeveloped in fashion and home goods segments outside the United States. The EU AI Act imposes transparency obligations on generative outputs that force architectural changes to citation and provenance layers for this vertical.
- Online Advertising:Auction mechanisms for sponsored placement require real-time bid processing and user profiling capabilities. The US Federal Trade Commission scrutinizes self-preferencing in AI-enhanced result placement under existing antitrust frameworks.
- Data Analytics:Enterprise procurement teams adopt these systems for internal knowledge bases, replacing legacy keyword search within compressed refresh cycles. Cloud-Based deployment preference dominates as buyers seek elastic scaling without infrastructure ownership.
- Content Discovery:Media and publishing platforms leverage synthesis engines to surface archival material. China's SAMR mandates algorithmic filing requirements for personalized information recommendation services, creating compliance friction for foreign index providers in this segment.
E-commerce leads on scale; Data Analytics leads on momentum.
End User:
Buyer sophistication and procurement authority shape sales cycle length, with enterprise IT departments unbundling search from existing cloud productivity contracts.
- Businesses:Mid-market enterprises without infrastructure ownership represent a serviceable addressable segment distinct from hyperscaler-native buyers. Procurement patterns compress vendor evaluation cycles as pilot-to-production timelines shrink.
- Developers:API Access offerings capture integration demand across embedded applications with lower customer acquisition cost than direct consumer competition. This segment expands fastest as SaaS applications embed search-native functionality.
- Marketers:Campaign optimization and audience intelligence tools drive adoption. Real-time source freshness requirements distinguish competitive offerings for this buyer type.
- Consumers:Direct-to-user distribution competes on citation transparency and interface simplicity. Perplexity AI targets this positioning against vertically integrated incumbents.
Businesses lead on scale; Developers lead on momentum.
Solution:
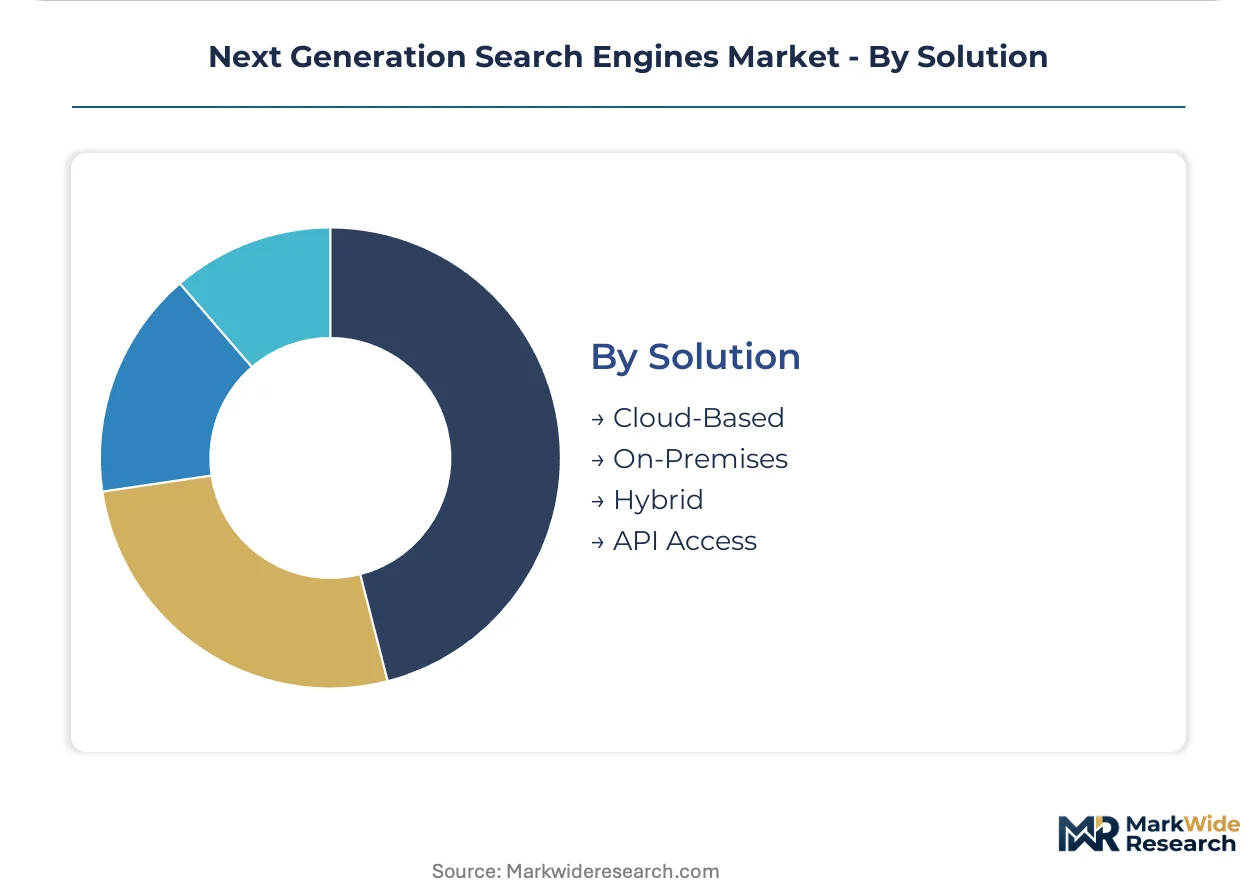
Deployment model selection reflects infrastructure ownership preferences and data residency requirements across regulated industries.
- Cloud-Based:Elastic scaling demand from financial services verticals creates direct purchasing relationships with specialized AI-native providers. United States hyperscaler infrastructure density lowers barrier-to-entry for generative search startups deploying on this model.
- On-Premises:Sovereign data requirements and latency-sensitive applications drive selection. Legacy enterprise system integration demands custom pipeline development that extends implementation timelines for this deployment mode.
- Hybrid:Split architectures process sensitive queries locally while leveraging cloud inference for general retrieval. Knowledge graph migration from decades-old document management platforms complicates hybrid deployments.
- API Access:Developer-driven embedded search integrations represent a distribution path with expanding addressable reach. Cross-jurisdictional compliance architecture demands modular citation layers that increase engineering complexity for API-first vendors.
Cloud-Based leads on scale; API Access leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are accelerating search infrastructure migration toward jurisdictions with clearer AI governance frameworks and concentrated cloud compute availability. Vendors are sequencing market entry based on compliance cost differentials and hyperscaler density.
United States
Enterprise knowledge management teams in financial services verticals are unbundling search procurement from cloud productivity contracts to secure citation transparency. The FTC scrutinizes self-preferencing in AI-enhanced result placement under existing antitrust frameworks. Silicon Valley and Seattle anchor venture deployment for generative search startups leveraging hyperscaler infrastructure density.
Germany
Industrial conglomerates in Baden-Württemberg and Bavaria are deploying AI-native retrieval systems for internal document search friction reduction. The EU AI Act's risk classification framework for automated decision-making systems is reshaping vendor compliance roadmaps. Berlin's startup ecosystem is concentrating engineering talent for retrieval-augmented generation pipeline development.
China
E-commerce platforms are driving demand for purchase-intent query monetization with premium placement economics. SAMR mandates algorithmic filing requirements for personalized information recommendation services, creating compliance friction for foreign index providers. Beijing and Shenzhen host domestic foundation model providers building vertically integrated crawler-to-LLM pipelines.
United Kingdom
Mid-market enterprises without infrastructure ownership are adopting Cloud-Based solutions for elastic scaling without capital expenditure. GDPR and emerging UK AI governance frameworks impose transparency obligations on generative outputs. London's fintech corridor is pioneering pilot-to-production cycles compressed to ninety days for internal knowledge base deployments.
India
Developer-driven demand is concentrating in API Access channels for embedded search integrations across SaaS applications. The country's data localization requirements and emerging AI governance discussions are shaping product architecture decisions. Bengaluru and Hyderabad are emerging as talent hubs for vector database optimization and prompt chaining expertise.
Next Generation Search Engines Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue citation transparency and real-time source freshness as differentiation vectors. The vendor base stratifies across three maturity tiers: hyperscalers with vertically integrated infrastructure, cloud-native specialists with modular architectures, and challenger platforms competing on interface simplicity. Strategic archetypes include inference-cost optimizers, enterprise distribution anchors, and transparency-first disruptors. Dominant competitive moves encompass multi-source data partnerships that bypass traditional crawler economics and architectural upgrades to citation provenance layers.
Among hyperscaler-based incumbents, Google LLC and Microsoft occupy positions defined by infrastructure control and enterprise distribution reach respectively. Perplexity AI exemplifies the transparency-first archetype competing on real-time source freshness against vertically integrated counterparts. These three anchors represent distinct strategic vectors: captive supply of training data and inference hardware, embedded distribution through productivity software contracts, and consumer-facing citation clarity as a trust-building mechanism.
| Leading Market Players |
|---|
| Google LLC (Alphabet Inc.) |
| Microsoft |
| OpenAI |
| Perplexity AI |
| Apple Inc. |
| Amazon.com Inc. |
| Baidu Inc. |
| Brave Software |
| Anthropic |
| Others |
Cost & Logistics Intelligence
NVIDIA H100 GPU spot pricing volatility cascades through inference-as-a-service tiers, compressing margins for API Access providers while hyperscalers absorb cost swings through captive silicon allocations. This input-cost architecture stratifies vendor economics between vertically integrated infrastructure owners and modular cloud-native competitors.
Pricing Analysis
Input-cost pass-through from Taiwan-based foundry capacity constraints forces three-tier pricing structure across premium inference, standard API, and economy batch-processing levels. Price differentiation hinges on latency guarantees and citation provenance depth, with financial services buyers least price-sensitive due to compliance mandates while mid-market SaaS developers face acute cost compression. Pricing pressure stems from hyperscaler bundling discounts that commoditize baseline retrieval services.
Supply Chain Analysis
Single-source vulnerability sits with TSMC's Arizona and Taiwan fabrication complexes for advanced AI accelerators. The supply chain draws from South Korean HBM memory suppliers, Japanese specialty chemical providers, and United States-based cloud infrastructure operators. Tariff exposure on Chinese-manufactured networking equipment threatens hardware cost structures. Distribution runs through hyperscaler marketplaces and direct enterprise procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification operates as a regulatory compounder, mandating citation transparency upgrades that accelerate procurement cycles for compliant vendors.
For Market Incumbents: Anchor enterprise retention through modular citation layers that satisfy simultaneous EU AI Act, SAMR, and FTC compliance demands. Deepen backward integration into vector database optimization to offset scarce RAG engineering talent. Defend against transparency-first challengers by exposing source lineage in consumer-facing interfaces.
For New Entrants and Emerging Players: Capture underpenetrated E-commerce verticals in European fashion and home goods segments where purchase-intent query monetization remains undeveloped. Prioritize API Access channel partnerships with vertical SaaS providers serving mid-market enterprises. Lead with real-time source freshness as the primary go-to-market wedge against incumbents.
For Investors and Strategic Acquirers: Asymmetric upside sits with retrieval-augmented generation infrastructure specialists possessing vector database optimization expertise. Long-term viability favors vendors with multi-jurisdictional compliance architectures already deployed. Monitor EU AI Act enforcement velocity as the critical inflection signal for enterprise procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Citation Provenance Architecture Upgrade | EU AI Act compliance mandates force reconstruction of output attribution mechanisms across all deployment tiers. |
| Multi-Source Data Partnership | Foundation model providers bypass traditional crawler economics through proprietary index operator alliances. |
| API Access Channel Expansion | Developer-driven embedded search integrations reduce customer acquisition cost versus direct consumer competition. |
| Enterprise Knowledge Base Migration | Financial services verticals unbundle search procurement from cloud productivity contracts for transparency. |
| Vector Database Optimization Investment | Scarce RAG engineering talent inflates compensation and slows iteration cycles for uncompetitive teams. |
Research Approach
Multiple input streams — primary interviews with enterprise knowledge management directors, CTOs at generative search startups, and cloud procurement officers, plus secondary validation against hyperscaler capex disclosures, SEC filings, and EU regulatory filings — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned vendor engineering leads, enterprise IT decision-makers, and compliance officers navigating cross-jurisdictional AI governance frameworks.
Data-stream reconciliation anchored the forecast framework across the projection horizon, modeling technology stack adoption, application vertical penetration, end-user procurement authority shifts, and solution deployment preferences. CAGRs were derived from segment-level growth trajectories weighted by infrastructure investment cycles and regulatory compliance timelines. Forecast inputs incorporated GPU supply allocation patterns, enterprise pilot-to-production acceleration rates, and citation transparency feature adoption curves.
Geopolitical disruption to Taiwan-based foundry output, abrupt EU AI Act enforcement escalation, and hyperscaler self-preferencing antitrust actions are the dominant revision risks that could compress or extend forecast trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Check Scanning Solutions Market
Digital Solutions
Telecom Site Management Software Market
Digital Solutions
Virtual Hiring Tools Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Smart Card in Government Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Global Software Defined Everything (SDE) Market
Digital Solutions
Europe ICT Market
Digital Solutions
Online Dating Market
Digital Solutions
Outsourced Digital Workplace Service Market
Digital Solutions
Global Connected Enterprise Market
Digital Solutions
Global Digital Accessibility Software Market
Digital Solutions
Self Service Technology Market
Digital Solutions
North America API Management Market