
 Trade Management Software Market | 2026-2036
Trade Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Trade Management Software Market Intelligence
Subscription-based compliance modules is decoupling trade management from perpetual licensing, letting buyers scale tariff-engine access by transaction volume rather than enterprise seat count. Oracle Trade Promotion Management leverages deep ERP integration to anchor multi-national deployment pipelines. Descartes Systems Group dominates customs brokerage networks through its logistics technology backbone. SAP Trade Promotion Management extends trade spend optimization into retail execution workflows.
Trade management software orchestrates cross-border commercial flows through automated harmonized system classification, duty drawback calculation, and preferential origin determination, typically deployed via API-connected cloud architectures that synchronize with carrier EDI feeds and customs single-window portals. Cloud-based deployments are capturing the fastest expansion as importers replace aging on-premise tariff engines, while hybrid architectures persist among exporters managing sensitive country-of-origin data behind firewalls. The retailer segment leads end-user demand as omnichannel fulfillment multiplies SKU-level customs complexity.
FDA import alert protocols, EU Customs Reform Programme mandates, and US CBP forced labor enforcement directives are tightening documentation requirements, compelling software vendors to embed real-time regulatory update feeds directly into workflow engines. ISO 27001 and SOC 2 Type II certifications have become baseline requirements for procurement shortlists. Stakeholders must evaluate whether their current platforms can ingest emerging carbon-border adjustment mechanisms without custom development cycles.
Market Dynamics
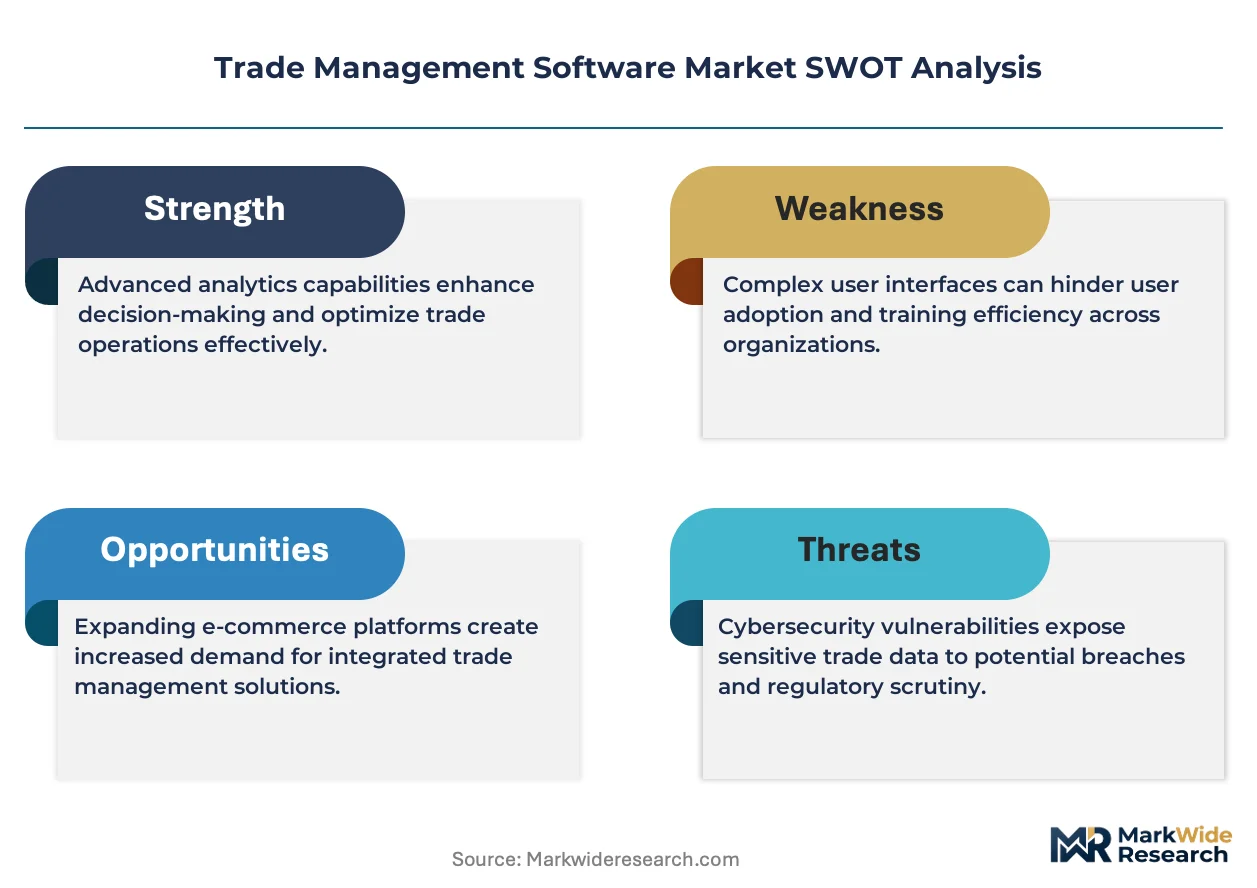
Cloud-native tariff engines are displacing on-premise customs infrastructure as importers prioritize API-driven compliance automation over legacy server deployments.
Growth Catalysts
- EU Customs Reform Programme:Mandates for real-time customs data exchange push freight forwarders toward automated single-window connectivity.
- Omnichannel retail fulfillment:SKU proliferation across digital and physical channels multiplies harmonized system classification complexity, forcing retailers to automate origin determination.
- Carbon-border adjustment mechanisms:Emerging emissions-tracking requirements in European customs frameworks create demand for embedded carbon-calculation modules.
Market Restraints
- Data sovereignty constraints:Exporters managing sensitive country-of-origin documentation behind national firewalls resist full cloud migration.
- Integration debt:Decades-old ERP systems in manufacturing verticals require expensive middleware to connect with modern trade platforms.
- Regulatory fragmentation:Divergent customs protocols across ASEAN member states force vendors to maintain parallel compliance rule engines.
Strategic Opportunities
- India's digitizing customs infrastructure:DGFT's phased rollout of paperless export-import procedures creates first-mover advantage for API-native vendors.
- Preferential origin automation:Rules-of-origin complexity under bilateral trade agreements drives demand for AI-powered qualification engines.
- Subscription modularization:Transaction-based pricing for tariff classification decouples revenue from enterprise seat licenses, opening mid-market access.
Industry Challenges
- Customs engineering talent scarcity:Shortage of professionals combining harmonized system expertise with API architecture skills constrains implementation velocity.
- Certification timeline compression:ISO 27001 and SOC 2 Type II requirements extend vendor onboarding cycles, delaying revenue recognition.
- Legacy EDI interoperability:Carrier systems using proprietary message formats resist standardization, forcing costly adapter development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trade Management Software Market |
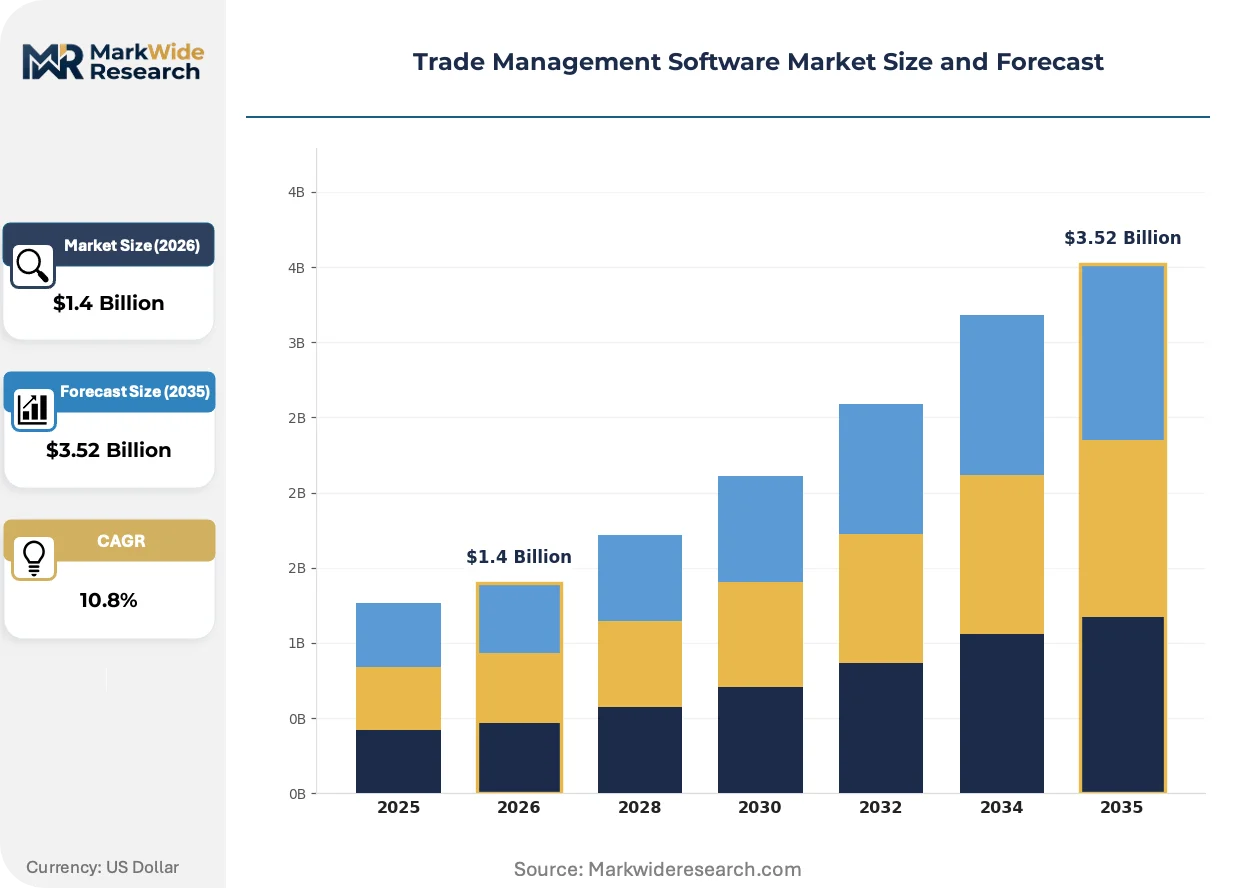
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.52 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Mobile End User: Retailers, Importers, Exporters, Brokers Deployment: Public Cloud, Private Cloud, Community Cloud, Dedicated Hosting Service Type: Implementation, Maintenance, Consulting, Support |
| Companies Covered | Zonos, Vividly, Oracle Trade Promotion Management, Salsify, Anaplan, SAP Trade Promotion Management, TradeInt, Celonis, Descartes Systems Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trade Management Software Market Strategic Shifts & Innovations
Embedded compliance intelligence is migrating from standalone modules to workflow-native automation, compressing the gap between regulatory change and system response.
API-first tariff classification engines are consolidating point-solution vendors into unified trade orchestration platforms. Retailers with complex omnichannel fulfillment operations are adopting these consolidated stacks fastest, replacing fragmented customs brokerage portals. The structural consequence is collapsing procurement cycles for trade technology from multi-year enterprise agreements to quarterly subscription adjustments.
REACH and the EU Green Deal are forcing chemical and manufacturing importers to embed carbon-border documentation into customs filings. Industrial consequence: software vendors must now ingest emissions data from supplier networks, not just calculate duties. German automotive suppliers and Dutch chemical distributors are rebuilding origin-determination workflows to capture Scope 3 emissions at the SKU level.
Outcome-based contracting for compliance accuracy is replacing traditional software licensing in freight forwarding. Large 3PLs now negotiate tariff-engine access contingent on classification error rates, shifting vendor risk onto performance guarantees. This model is penetrating fastest among US-based electronics distributors managing high-volume, low-margin import flows from Southeast Asian contract manufacturers.
Trade Management Software Market Segmentation
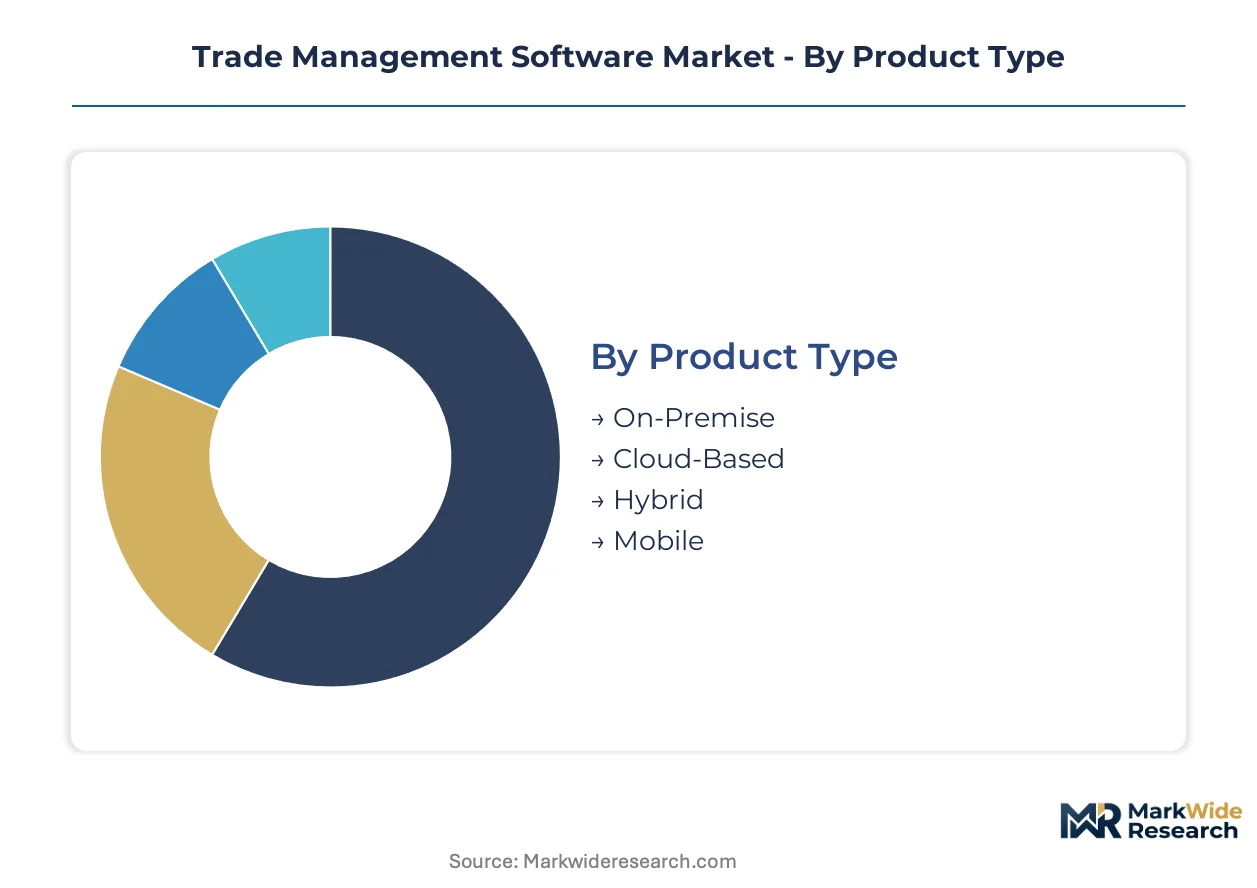
Trade management software vendors structure their offerings around four intersecting dimensions that determine compliance architecture, pricing models, and customer acquisition costs. Each segmentation axis carries distinct certification burdens and integration requirements that shape procurement decisions across retail, logistics, and manufacturing verticals.
Product Type:
ISO 27001 and SOC 2 Type II certifications apply universally across all product types, though audit scope varies with data residency architecture. Cloud-based deployments demand continuous compliance monitoring, while on-premise installations emphasize perimeter security validation.
- Cloud-Based:API-native architectures synchronize tariff engines with carrier EDI feeds and customs single-window portals in real time. Retailers with omnichannel fulfillment operations in the United States and Germany are replacing legacy installations fastest, driven by CBP forced labor enforcement directives and EU Customs Reform Programme mandates for real-time data exchange.
- Hybrid:Sensitive country-of-origin data remains behind corporate firewalls while compliance updates flow through encrypted cloud channels. German automotive suppliers and Dutch chemical distributors favor this architecture to satisfy REACH documentation requirements without exposing proprietary formulation data.
- On-Premise:Aging tariff engines in manufacturing verticals require expensive middleware for ERP connectivity. These installations persist where data sovereignty constraints block full cloud migration, particularly among exporters managing restricted technology classifications.
- Mobile:Field-accessible customs documentation tools support port inspectors and warehouse operators. Demand concentrates among freight forwarders managing containerized imports through congested US gateway ports.
Cloud-Based sits at the top of the volume ranking, with Hybrid climbing the fastest as carbon-border adjustment mechanisms force emissions data integration with legacy origin-determination systems.
End User:
Customer type determines feature depth, with retailers requiring SKU-level automation while brokers prioritize transaction throughput. Procurement authority and implementation timelines vary sharply across these segments.
- Retailers:Omnichannel fulfillment multiplies harmonized system classification complexity, forcing automation of preferential origin determination. US-based electronics distributors and German fashion retailers lead adoption, compelled by FDA import alert protocols and EU Green Deal supply chain disclosure rules.
- Importers:High-volume, low-margin operations demand outcome-based contracting contingent on classification accuracy. Electronics distributors sourcing from Southeast Asian contract manufacturers negotiate tariff-engine access tied to error-rate guarantees.
- Exporters:Rules-of-origin complexity under bilateral trade agreements drives demand for AI-powered qualification engines. India's DGFT paperless procedures create first-mover opportunities for API-native vendors serving this segment.
- Brokers:Customs brokerage networks consolidate around platforms with embedded regulatory update feeds. Descartes Systems Group dominates this channel through logistics technology backbone integration.
Retailers command the largest addressable spend, with Importers expanding most quickly as forced labor enforcement intensifies documentation requirements.
Deployment:
Infrastructure choice reflects data sensitivity, with public cloud capturing standard compliance workloads and private installations serving restricted trade scenarios. Community models emerge where industry consortia share compliance infrastructure.
- Public Cloud:Shared infrastructure delivers lowest per-transaction costs for standard tariff classification. Mid-market importers scale access by volume rather than enterprise seat count through subscription modularization.
- Private Cloud:Isolated environments satisfy data sovereignty constraints for exporters managing sensitive country-of-origin documentation. National firewalls in ASEAN member states reinforce demand for this architecture.
- Community Cloud:Industry-specific compliance rule engines serve vertical clusters with shared regulatory exposure. Chemical distributors in the Netherlands collaborate on REACH documentation workflows.
- Dedicated Hosting:Single-tenant deployments support largest freight forwarders with custom integration requirements. Extended vendor onboarding cycles for ISO 27001 certification delay revenue recognition in this segment.
Public Cloud holds the volume lead, with Community Cloud gaining share fastest as carbon-border mechanisms force sectoral emissions data pooling.
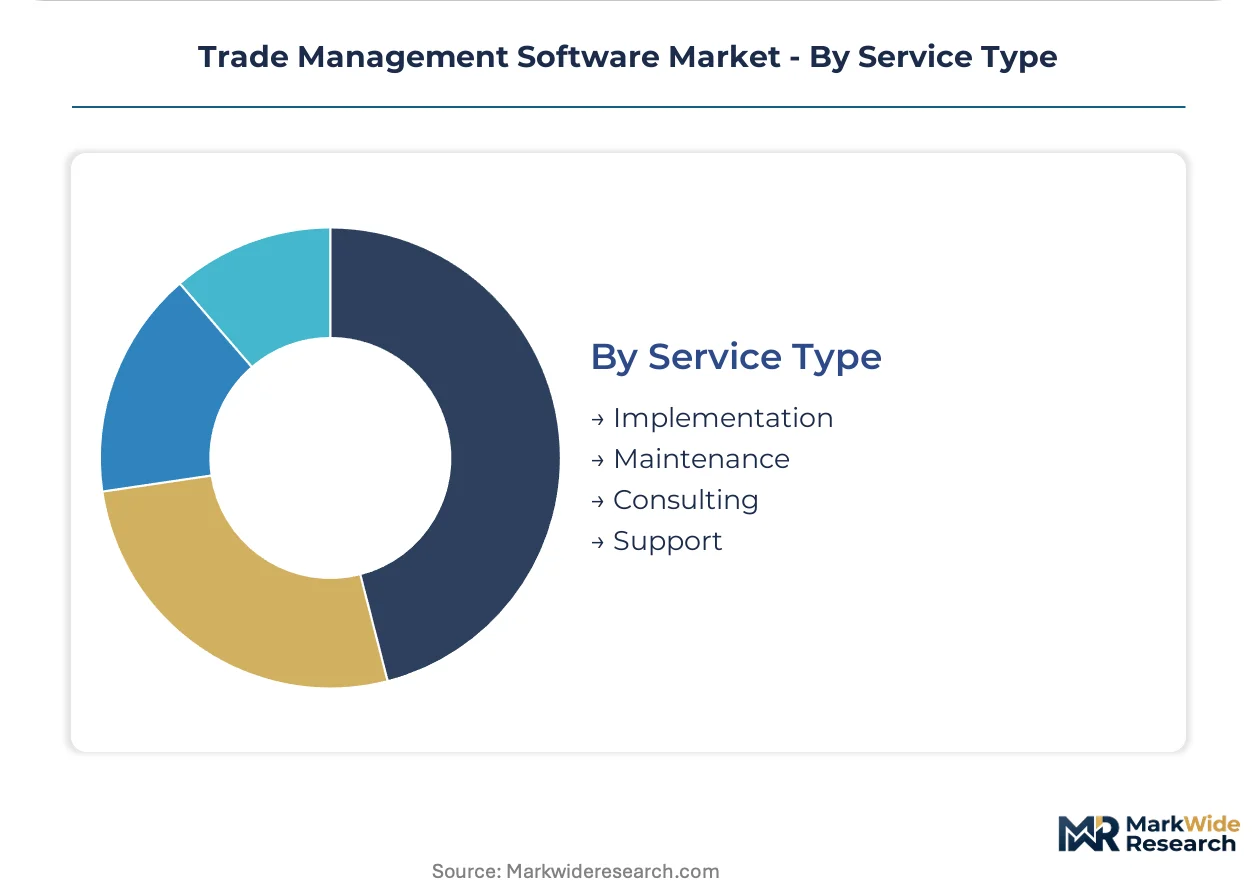
Service Type:
Revenue mix shifts from perpetual licensing toward recurring service streams, with implementation and maintenance capturing expanding share of customer lifetime value.
- Implementation:Customs engineering talent scarcity constrains deployment velocity. Vendors compete for professionals combining harmonized system expertise with API architecture skills.
- Maintenance:Continuous regulatory update feeds require dedicated subscription revenue. FDA, ECHA, and CBP directive changes propagate through automated workflow engines.
- Consulting:Preferential origin automation and bilateral trade agreement qualification drive advisory demand. AI-powered rules engines reduce but do not eliminate human expertise requirements.
- Support:Legacy EDI interoperability challenges force costly adapter development. Carrier systems using proprietary message formats resist standardization.
Implementation generates the highest absolute revenue, with Maintenance showing the steepest expansion trajectory as real-time compliance engines become operational necessities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the largest installed base of trade management platforms, while Germany accelerates faster as EU Customs Reform Programme deadlines tighten compliance automation timelines across member states.
United States
Port congestion at Los Angeles and Long Beach drives demand for real-time shipment visibility tools. CBP forced labor enforcement directives compel electronics distributors to automate supplier documentation. The Southeast manufacturing corridor from Georgia to Tennessee expands import processing capacity.
Germany
Automotive suppliers in Baden-Württemberg rebuild origin-determination workflows to capture Scope 3 emissions data. REACH documentation requirements under EU Green Deal mandates force chemical distributors toward embedded carbon-calculation modules. The Rhine-Ruhr logistics cluster consolidates customs brokerage networks around API-native platforms.
India
DGFT's phased rollout of paperless export-import procedures creates first-mover opportunities for API-native vendors. Electronics manufacturers in Karnataka and Tamil Nadu adopt automated harmonized system classification to manage bilateral trade agreement complexity. Mumbai's freight forwarding district scales transaction-based tariff engine access.
Netherlands
Chemical distributors in Rotterdam collaborate on REACH documentation workflows through community cloud architectures. Carbon-border adjustment mechanisms force emissions data integration with legacy origin-determination systems. The Port of Rotterdam accelerates single-window connectivity for real-time customs data exchange.
China
Dual carbon goals under MEE directives push manufacturing exporters toward embedded emissions tracking in customs filings. Electronics contract manufacturers in the Pearl River Delta automate preferential origin determination for bilateral trade agreements. Shanghai's customs district pilots API-connected compliance engines for high-volume import processing.
Trade Management Software Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with ERP-integrated suites capturing multinational deployment pipelines while point-solution vendors consolidate into unified orchestration platforms. The vendor base organizes around three archetypes: enterprise resource planning anchors, logistics technology backbones, and API-native classification engines. M&A activity concentrates on acquiring customs engineering talent and regulatory content libraries. Strategic partnerships between freight forwarders and compliance engine providers reshape procurement cycles from multi-year agreements to quarterly subscription adjustments.
Within the ERP-integrated tier, Oracle Trade Promotion Management and SAP Trade Promotion Management exemplify platforms extending trade spend optimization into retail execution workflows. Descartes Systems Group occupies a position among logistics technology providers, anchoring customs brokerage networks through backbone integration. These three entities represent distinct competitive vectors: deep enterprise system embedding, freight network dominance, and cloud-native modularization.
| Leading Market Players |
|---|
| Zonos |
| Vividly |
| Oracle Trade Promotion Management |
| Salsify |
| Anaplan |
| SAP Trade Promotion Management |
| TradeInt |
| Celonis |
| Descartes Systems Group |
| Others |
Cost & Logistics Intelligence
API architecture talent costs cascade through subscription pricing tiers, compressing margins for mid-market vendors while enterprise suites absorb these inputs through volume-scaled SaaS tiers that lock in multinational buyers.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for implementation services as customs engineering talent scarcity intensifies wage competition. Transaction-based pricing for tariff classification now stratifies across premium compliance modules, standard API access, and economy self-service portals, with ISO 27001 certification tiers driving price differentiation. Cost compression in the mid-market segment is intensifying because broker networks consolidate procurement around outcome-based contracts. Importers managing high-volume electronics flows from Southeast Asian contract manufacturers exhibit the highest price sensitivity, while German automotive suppliers prioritize accuracy guarantees over unit cost.
Supply Chain Analysis
Freight forwarding costs through congested US gateway ports propagate into software procurement cycles as retailers demand real-time shipment visibility bundled with compliance automation. Development resources concentrate in the United States, Germany, and India, with cloud infrastructure sourcing from hyperscaler regions in Ireland, Singapore, and Virginia. The vendor ecosystem draws from specialized customs content libraries, API middleware providers, and carrier EDI integration specialists. Single-source vulnerability persists where legacy EDI formats resist standardization, forcing costly adapter development. Distribution runs through direct enterprise sales for multinational deployments and channel partnerships for mid-market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trade management software market functions as a stable compounder, with regulatory complexity under the EU Customs Reform Programme and CBP enforcement directives ensuring sustained replacement demand for compliance engines.
For Market Incumbents: Cement multi-year relationships through embedded ERP integration that raises switching costs for Oracle and SAP anchor customers. Invest in customs engineering talent acquisition to defend implementation velocity against API-native challengers. Prioritize carbon-border calculation modules as German automotive suppliers and Dutch chemical distributors rebuild origin-determination workflows.
For New Entrants and Emerging Players: Cloud-native API marketplaces offer the most penetrable route for mid-market retailers seeking modular tariff-engine access without enterprise seat commitments. Target India's DGFT digitization rollout where paperless export-import procedures create first-mover whitespace. Pursue transaction-based pricing models that decouple revenue from perpetual licensing friction.
For Investors and Strategic Acquirers: Consolidation pressure builds where customs engineering talent scarcity constrains implementation velocity for point-solution vendors. The five-to-ten year viability window favors platforms with embedded regulatory content libraries and carrier network integration. Acquisition target archetypes include API-first classification engines with bilateral trade agreement rule sets. Watch for forced labor enforcement directive expansion as an inflection signal for documentation automation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP embedding with SAP and Oracle anchors multi-national deployment pipelines. |
| Acquisition of Specialist Firm | Customs content library purchases accelerate regulatory update feed capabilities. |
| Strategic Partnership | Freight forwarder alliances reshape procurement from multi-year agreements to quarterly subscriptions. |
| Geographic Expansion | DGFT digitization in India creates first-mover advantage for API-native vendors. |
| Product Launch | Carbon-calculation modules address EU Green Deal emissions documentation mandates. |
Research Approach
Direct dialogue with customs brokerage executives, ERP implementation specialists, freight forwarder operations heads, and retail supply chain directors grounded qualitative findings in operational reality. Secondary validation drew from CBP directive filings, EU Customs Reform Programme documentation, DGFT circulars, and SEC disclosures from logistics technology providers. Bottom-up and top-down triangulation cross-checked segment assumptions against aggregate market sizing.
Bottom-up modeling anchored volume projections to individual deployment patterns across cloud, hybrid, and on-premise architectures, while top-down analysis tracked aggregate spend shifts from perpetual licensing to subscription modularization. Segmentation dimensions included deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from trend extrapolation of replacement cycles for aging tariff engines and net new adoption curves for carbon-border modules. Forecast inputs incorporated customs single-window portal rollout timelines and forced labor enforcement directive expansion patterns.
Regulatory deadline delays, customs engineering talent availability shocks, and hyperscaler infrastructure cost volatility are the dominant revision risks across the projection horizon. Forecasts reflect documented assumptions about compliance automation penetration rates and carrier EDI standardization progress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Spain Digital Twin Market
Digital Solutions
Global E-Visa Market
Digital Solutions
Digital Dispenser Systems Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Consent Management Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Cannabis POS System Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
US Transcription Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
System Integrator Market