
 Data Cleansing Tools Market | 2026-2036
Data Cleansing Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Data Cleansing Tools Market Outlook
Platform licensing revenue is fragmenting between standalone cleansing modules and embedded features within broader data-management suites. Informatica leverages its enterprise integration heritage to anchor premium pricing for end-to-end data quality stacks. Alteryx competes through visual workflow design that lowers technical barriers for analyst-led cleansing projects. SAP sustains dominance in ERP-adjacent deployments where master data governance requirements create captive demand for native cleansing tools.
Data cleansing tools are software applications that detect, correct, or remove corrupt, inaccurate, or irrelevant records from datasets through rule-based validation, fuzzy matching algorithms, and statistical outlier detection, typically processing structured data at throughput rates exceeding millions of rows per hour to ensure downstream analytics and operational systems operate on reliable inputs. Cloud-based solutions now lead deployment preferences as elastic compute allows burst processing of periodic data loads without permanent infrastructure commitments, while on-premises tools retain structural importance in defense, intelligence, and critical infrastructure sectors where data residency requirements block external transmission. Data quality assessment applications command the deepest margin pools because enterprises treat pre-analytics validation as insurance against flawed decision-making, whereas customer data management applications grow fastest as B2C firms respond to consent-management and personalization imperatives.
FDA 21 CFR Part 11 shapes validation requirements for life-sciences data pipelines, while GDPR and the EU AI Act impose accountability standards that elevate cleansing to a documented compliance step rather than discretionary preprocessing. ISO 8000 data quality standards provide procurement leverage for buyers demanding certified tool performance. Stakeholders must monitor how emerging sector-specific AI regulations in healthcare and finance redefine acceptable error rates and audit trails for training data preparation.
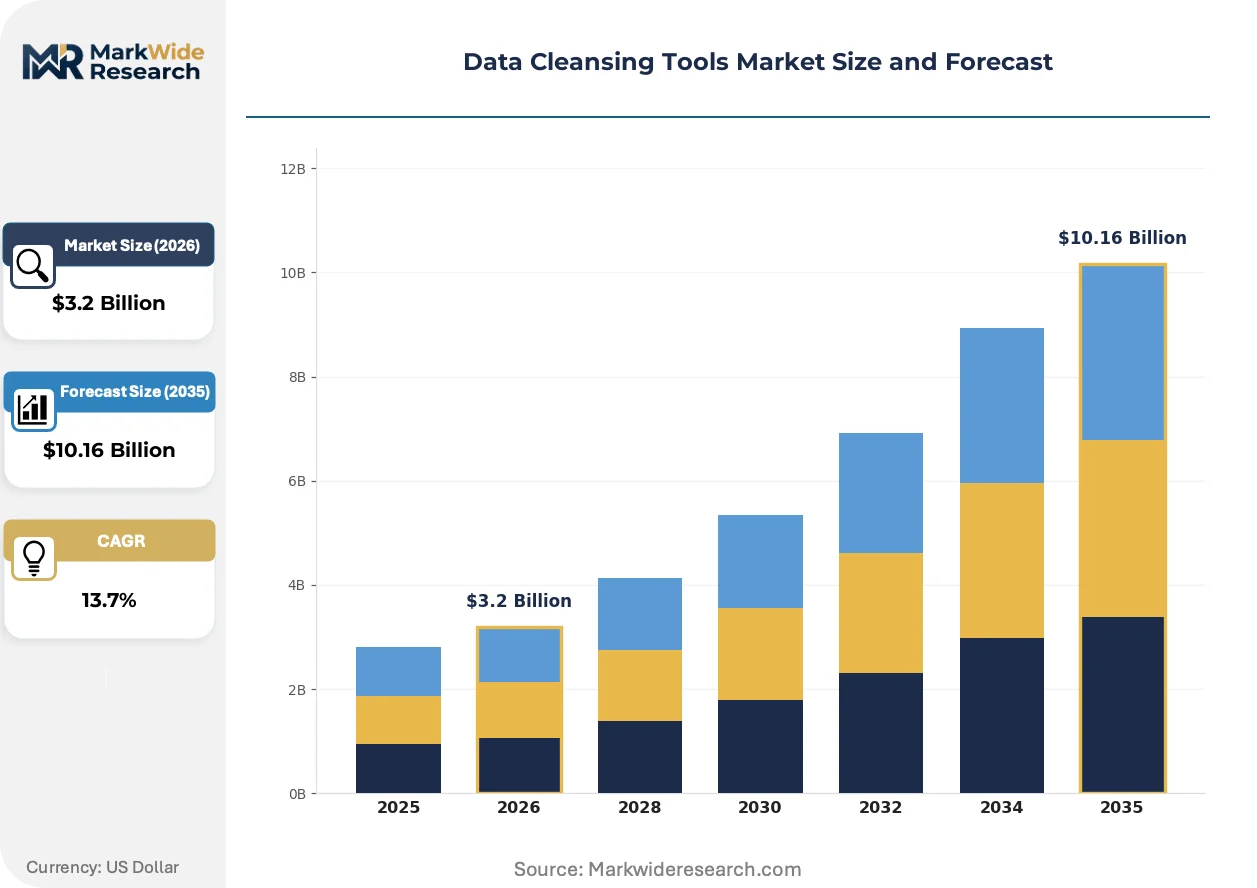
Market Dynamics
Automated provenance-tracking capabilities are compressing sales cycles as GDPR and EU AI Act compliance requirements force procurement teams to prioritize audit-ready validation pipelines over discretionary data-quality investments.
Growth Catalysts
- FDA 21 CFR Part 11:Life-sciences manufacturers must deploy validated cleansing workflows for electronic records, creating captive demand for tools with built-in audit trails and electronic signature support.
- Industrial data lake standardization:German manufacturing conglomerates require heavy preprocessing of sensor and ERP data before analytics deployment, concentrating procurement in Europe's largest industrial economy.
- Elastic cloud compute:Burst-processing architectures allow enterprises to handle periodic data loads without permanent infrastructure, expanding addressable market to mid-sized firms previously blocked by capex requirements.
Market Restraints
- Specialized engineering talent scarcity:Fuzzy-matching algorithm development and statistical outlier detection require rare combinations of data engineering and domain expertise, inflating implementation costs.
- Embedded feature substitution:Native data-quality modules within Snowflake, Databricks, and cloud data warehouses capture baseline cleansing workloads, compressing standalone tool pricing power.
- Cross-border data residency friction:Defense and intelligence sectors in the US, Germany, and Japan block external transmission, forcing redundant on-premises deployments that dilute vendor economies of scale.
Strategic Opportunities
- Bias-detection workflow integration:EU AI Act accountability standards elevate automated bias scanning from optional feature to documented compliance step, opening premium pricing for tools with certified fairness metrics.
- Consent-management convergence:Customer data management applications are absorbing cleansing, identity resolution, and preference-center functions into unified stacks, rewarding vendors with native consent orchestration.
- ISO 8000 procurement leverage:Certified data quality standards provide buyers with vendor-agnostic performance benchmarks, creating opening for challenger tools to displace incumbents in formal tender processes.
Industry Challenges
- Legacy ERP integration complexity:SAP and Oracle environments require custom connector development and schema mapping, extending implementation timelines and inflating professional services dependency.
- Multi-source lineage reconciliation:Enterprises struggle to maintain coherent audit trails when cleansing workflows span hybrid cloud, on-premises, and SaaS data sources with conflicting metadata standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Cleansing Tools Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $10.16 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Cloud-Based Solutions, On-Premises Tools, Data Profiling Tools Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Local Server End User: Small Enterprises, Medium Enterprises, Large Enterprises, Data Analysts Application: Data Quality Assessment, Data Integration, Customer Data Management, Data Migration |
| Companies Covered | Informatica, ZoomInfo, TIBCO Clarity, Alteryx, WinPure, LeadAngel, Melissa, SAP, Cognilix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Cleansing Tools Market Strategic Shifts
Rule-based validation engines are converging with machine-learning inference to handle semi-structured and unstructured data sources that traditional regex and fuzzy-matching algorithms cannot parse reliably.
Probabilistic data-matching engines are hybridizing deterministic rules with neural embeddings to resolve entity identities across fragmented customer databases. Retail banks and insurance underwriters are deploying these hybrid architectures for know-your-customer and fraud-detection pipelines. The technology is compressing time-to-value for master data management initiatives by reducing manual threshold-tuning requirements.
The EU AI Act's risk-based classification system mandates documented data quality for high-risk AI applications including credit scoring and medical diagnosis. Pharmaceutical manufacturers must now validate training data provenance through auditable cleansing steps. EMA-regulated firms are responding by embedding quality gates directly within MLOps pipelines rather than treating cleansing as upstream preprocessing.
Buyer preference is rotating toward consumption-based pricing that aligns vendor revenue with actual rows processed rather than perpetual seat licenses. Mid-market enterprises in the US and UK are unbundling professional services and demanding self-service configuration tools. This compression of the traditional implementation-heavy model is forcing vendors to invest in low-code workflow designers and automated schema detection.
Data Cleansing Tools Market Segmentation
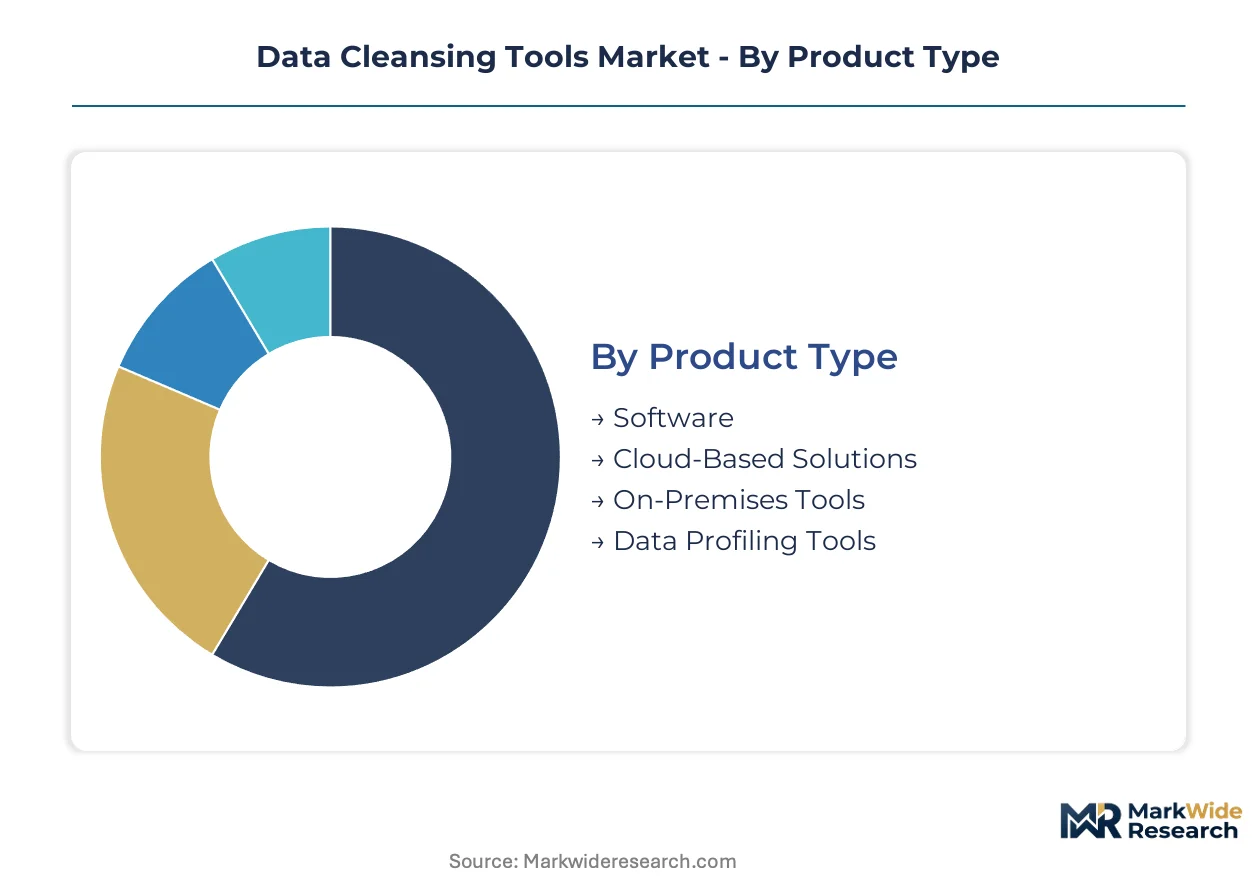
Segmentation in data cleansing tools reveals how procurement cycles, compliance mandates, and infrastructure constraints fragment demand across incompatible technology stacks. Vendors must architect separate go-to-market motions for cloud-native buyers versus captive on-premises deployments.
Product Type:
Software offerings turn over fastest as release cycles compress under competitive pressure, while on-premises tools exhibit the longest replacement cycles due to validation requirements in regulated sectors.
- Software:Perpetual and subscription-licensed applications deploy across heterogeneous data environments. Financial services firms in Germany and the US drive refresh cycles as Basel III and SEC audit requirements harden.
- Cloud-Based Solutions:Elastic compute architectures process burst workloads without infrastructure permanence. Mid-market enterprises in the UK and France adopt these for GDPR-mandated data residency compliance without capital expenditure.
- On-Premises Tools:Air-gapped deployments satisfy defense and intelligence sector data sovereignty requirements.
- Data Profiling Tools:Discovery-oriented modules map schema structures before transformation logic applies.
Software dominates installed base. Cloud-Based Solutions is where expansion concentrates.
Deployment:
Cost tiering separates hyperscaler consumption models from captive infrastructure, with hybrid architectures commanding premium professional services attach rates.
- Public Cloud:Multi-tenant SaaS platforms abstract infrastructure management entirely. Retail and media firms in Japan and Australia leverage these for seasonal data ingestion spikes.
- Private Cloud:Single-tenant virtualized environments isolate workloads while retaining operational flexibility. Healthcare networks in Germany and Switzerland deploy these for EMA patient-data protection compliance.
- Hybrid Cloud:Orchestrated workloads span on-premises and external compute pools.
- Local Server:Bare-metal installations serve edge manufacturing and critical infrastructure.
Public Cloud captures volume leadership. Private Cloud is climbing the fastest as sector-specific residency rules proliferate.
End User:
Organizational scale determines feature depth requirements, with large enterprises demanding governance modules that small firms cannot operationalize.
- Large Enterprises:Global data governance frameworks require federated quality controls across business units. Automotive and pharmaceutical conglomerates in Germany and the US mandate ISO 8000-certified tool performance.
- Data Analysts:Self-service interfaces bypass IT queue dependencies for exploratory cleansing. Marketing and operations teams in UK financial services drive adoption of visual workflow designers.
- Medium Enterprises:Departmental deployments balance capability against implementation complexity.
- Small Enterprises:Limited IT staffing restricts deployment to managed service overlays.
Large Enterprises dominate installed base. Data Analysts is gaining share fastest as low-code interfaces democratize access.
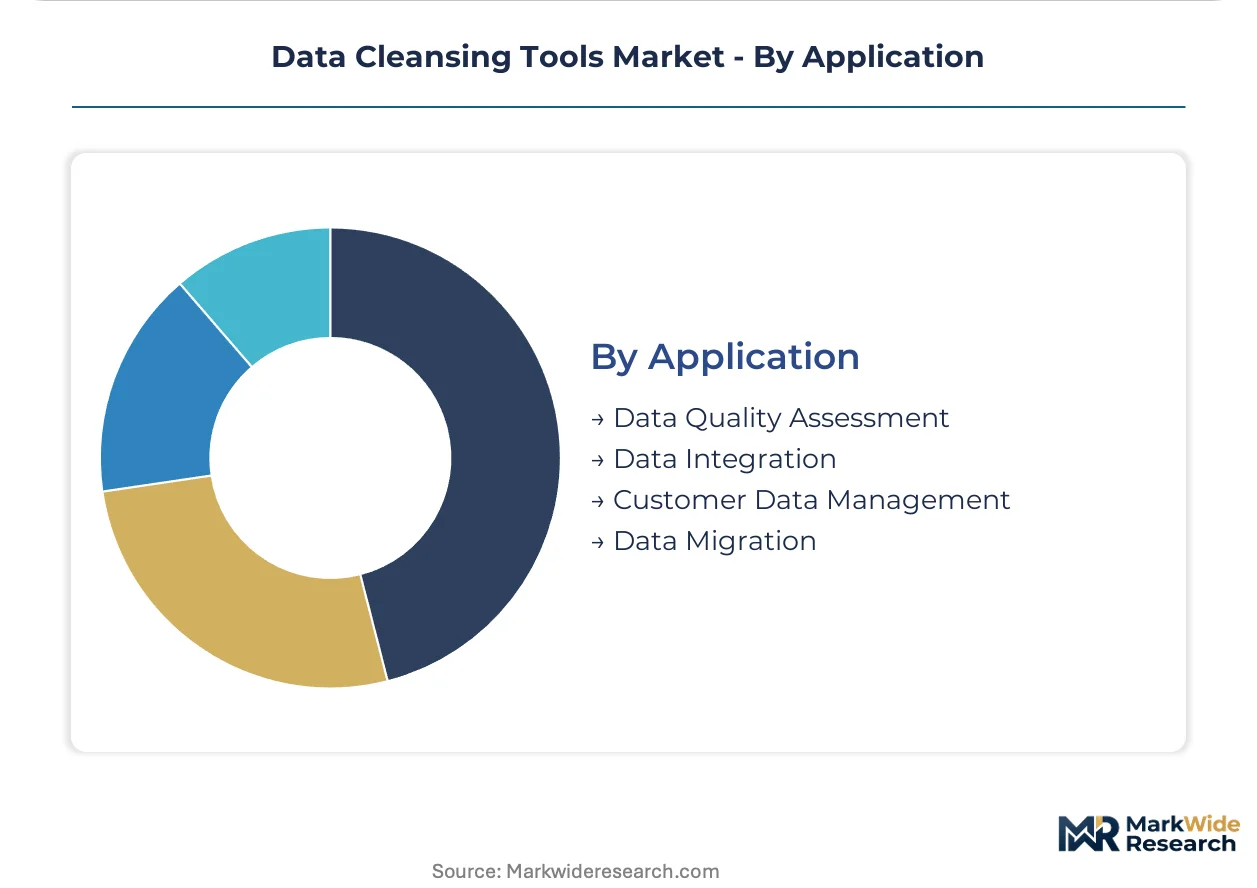
Application:
Use-case maturity varies sharply, with compliance-driven applications exhibiting inelastic demand compared to discretionary quality initiatives.
- Data Quality Assessment:Pre-analytics validation gates prevent flawed decision-making from propagating. Insurance underwriters in Germany and France treat these capabilities as regulatory capital under Solvency II.
- Customer Data Management:Identity resolution and consent orchestration converge within unified stacks. B2C retailers in the UK and US respond to GDPR and CCPA consent-management imperatives.
- Data Integration:ETL pipeline cleansing ensures semantic consistency across source systems.
- Data Migration:One-time transformation projects validate legacy system retirement.
Data Quality Assessment dominates installed base. Customer Data Management is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-market buyers in the United Kingdom exhibit acute price sensitivity toward consumption-based licensing, while German automotive and pharmaceutical conglomerates absorb premium pricing for ISO 8000-certified validation stacks without procurement friction.
United States
Financial services firms in New York and Chicago drive automated pipeline adoption to satisfy SEC audit requirements for electronic records. FDA 21 CFR Part 11 mandates validate cleansing workflows for life-sciences manufacturers in Boston's biotech corridor. Defense contractors in Northern Virginia maintain air-gapped on-premises deployments blocking external transmission.
Germany
Industrial data lakes at automotive conglomerates require heavy sensor and ERP standardization before analytics deployment. GDPR and the EU AI Act compel Munich and Stuttgart enterprises to invest in provenance-tracking capabilities. Manufacturing clusters in Baden-Württemberg concentrate procurement for bias-detection integration within MLOps pipelines.
United Kingdom
Retail banks and insurance underwriters in London deploy probabilistic matching for know-your-customer compliance. GDPR consent-management imperatives push B2C firms toward unified customer data stacks. Financial services teams in Canary Wharf adopt visual workflow designers to bypass IT queue dependencies.
Japan
Retail and media firms in Tokyo leverage public cloud SaaS for seasonal data ingestion spikes without infrastructure permanence. METI guidelines shape data quality expectations for manufacturing exporters in Osaka. Healthcare networks deploy private cloud single-tenant environments for patient-data protection compliance.
France
Insurance underwriters in Paris treat pre-analytics validation as regulatory capital under Solvency II requirements. EMA-regulated pharmaceutical firms embed quality gates directly within MLOps pipelines. Lyon-based manufacturing operations require federated quality controls across distributed business units.
Data Cleansing Tools Market Competitive Environment
Capability concentration sits with specialized cleansing vendors; scale advantage sits with enterprise integration incumbents. The market structures around three tiers: premium end-to-end stacks, mid-market visual workflow platforms, and embedded modules within cloud data warehouses. Dominant competitive moves include portfolio diversification into adjacent data governance and strategic partnerships with hyperscaler marketplaces.
Within the enterprise integration tier, Informatica leverages its heritage to anchor premium pricing for comprehensive data quality stacks. Alteryx competes through visual workflow design that lowers technical barriers for analyst-led projects. SAP sustains positioning in ERP-adjacent deployments where master data governance creates captive demand for native tooling.
| Leading Market Players |
|---|
| Informatica |
| ZoomInfo |
| TIBCO Clarity |
| Alteryx |
| WinPure |
| LeadAngel |
| Melissa |
| SAP |
| Cognilix |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure concentration in US hyperscaler regions directly shapes where margin pools accumulate in data cleansing tool delivery. Vendors anchoring compute contracts in Northern Virginia and Frankfurt capture operational leverage that compresses cost-to-serve for enterprise deployments.
Pricing Analysis
Professional services and extended implementation contracts drive lifetime value beyond initial SaaS subscriptions. Subscription-tiered pricing stratifies across enterprise, professional, and self-service levels based on row-processing volume and governance module depth. Pricing pressure stems from embedded data-quality features within Snowflake and Databricks capturing baseline workloads. Mid-market buyers in the United Kingdom exhibit acute price sensitivity toward consumption-based licensing, while German automotive conglomerates absorb premium pricing for ISO 8000-certified validation stacks without procurement friction.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware-dependent edge deployments. Software supply chains draw from development talent pools in India, Poland, and the United States. Cloud compute dependencies rest on server infrastructure from Taiwan and South Korea. Single-source vulnerability concentrates in GPU acceleration for ML-powered matching algorithms. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward procurement teams with consolidated vendor management authority, as mid-market enterprises unbundle professional services and demand self-service configuration tools.
For Market Incumbents: Build switching-cost moats through embedded workflow automation that deepens integration with SAP and Oracle ERP environments. Defensive moves require ISO 8000 certification investment to maintain procurement eligibility in German automotive and pharmaceutical tenders. Threat substitution from native cloud data warehouse features demands anchoring premium pricing in governance modules that embedded tools cannot replicate. Channel control through hyperscaler marketplace presence protects against direct sales erosion.
For New Entrants and Emerging Players: Pursue white-space opportunities in bias-detection workflow integration for EU AI Act compliance, where certified fairness metrics command premium positioning. The most penetrable segment sits with mid-market UK financial services firms seeking visual workflow designers to bypass IT queue dependencies. Go-to-market angles should emphasize consumption-based pricing that aligns vendor revenue with actual rows processed.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed data governance platforms seeking cleansing module tuck-ins to complete end-to-end stacks. Long-term viability hinges on M&A consolidation around compliance-driven demand inelasticity. Acquisition target archetypes include specialized fuzzy-matching algorithm shops with rare engineering talent. The signal to watch is EU AI Act enforcement intensity elevating documented data quality from discretionary preprocessing to mandatory compliance step.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding cleansing modules within broader data management suites captures ERP-adjacent demand from SAP environments. |
| Strategic Partnership | Hyperscaler marketplace listings expand addressable market to mid-sized firms blocked by traditional capex requirements. |
| Acquisition of Specialist Firm | Fuzzy-matching algorithm shops with neural embedding expertise compress time-to-value for master data management initiatives. |
| Product Launch | Bias-detection workflow tools with certified fairness metrics open premium pricing under EU AI Act accountability standards. |
| Geographic Expansion | Private cloud single-tenant deployments in Germany and Switzerland capture healthcare sector data residency compliance demand. |
Study Parameters
A standing panel of data engineering directors, IT procurement officers, compliance leads at financial services firms, and cloud platform engineers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against SEC filings, hyperscaler capex disclosures, regulatory submission databases, and enterprise software contract records. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Scenario-bracketing anchored the analytical framework, with projections tested against alternative regulatory enforcement intensities and cloud adoption trajectories. Segmentation dimensions modeled include deployment architecture, organization scale, application use case, integration complexity, and regional compliance pattern. CAGRs derived from fitted growth curves applied to validated base-year estimates. Industry-specific forecast inputs encompassed EU AI Act implementation timelines and FDA 21 CFR Part 11 validation requirement evolution.
Sensitivities concentrate around regulatory enforcement intensity, cloud infrastructure cost volatility, and embedded feature substitution rates. Forecasts reflect documented assumptions regarding compliance-driven demand inelasticity. Macroeconomic contraction, accelerated hyperscaler feature development, or sector-specific AI regulation delays would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Telecom Site Management Software Market
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Governed Enterprise Architecture Scenario Sandbox Market
Digital Solutions
Global Digital Art Software Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Supply Side Platform (SSP) Market
Digital Solutions
Digital Signage Market
Digital Solutions
Global Cloud POS Market
Digital Solutions
Global Smart Offices Market
Digital Solutions
Social Networking App Market
Digital Solutions
Global Intelligent Platform Management Interface (IPMI) Market
Digital Solutions
Latin America Digital Signage Market
Digital Solutions
Mobile Sharing Power Bank Rental Service Market
Digital Solutions
Location Targeted Mobile Advertising Market
Digital Solutions
Global Freight Software Market