
 ASEAN Cloud Computing Market | 2026-2036
ASEAN Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Cloud Computing Market Insights
Singapore's data center corridor is rewriting regional cloud infrastructure economics. Amazon Web Services anchors the city-state's hyperscale ecosystem through multi-zone availability architectures. Microsoft Azure leverages sovereign cloud partnerships to compete across Indonesia and Thailand. Alibaba Cloud dominates cross-border latency optimization for Chinese enterprise subsidiaries operating in Vietnam and the Philippines.
Cloud computing denotes networked delivery of on-demand compute, storage, and application resources via virtualized server pools operating at 99.99% uptime SLAs, enabling enterprises to replace capital-intensive on-premises hardware with metered operational expenditure. Public cloud deployments lead ASEAN adoption volumes as hyperscalers expand availability zones, while hybrid cloud architectures capture the fastest growth trajectory among regulated financial institutions requiring workload segregation. SaaS consumption within the service type category concentrates margin pools around vertical-specific applications for banking compliance and retail logistics.
Thailand's Personal Data Protection Commission, Singapore's Infocomm Media Development Authority, and Indonesia's Ministry of Communication and Informatics enforce data localization and cross-border transfer frameworks that shape provider certification requirements and customer procurement decisions. BIS-aligned standards in India exert indirect pressure on ASEAN operators serving multinational supply chains. Stakeholders must monitor evolving sovereignty mandates to align infrastructure placement with jurisdictional compliance boundaries.
Market Dynamics
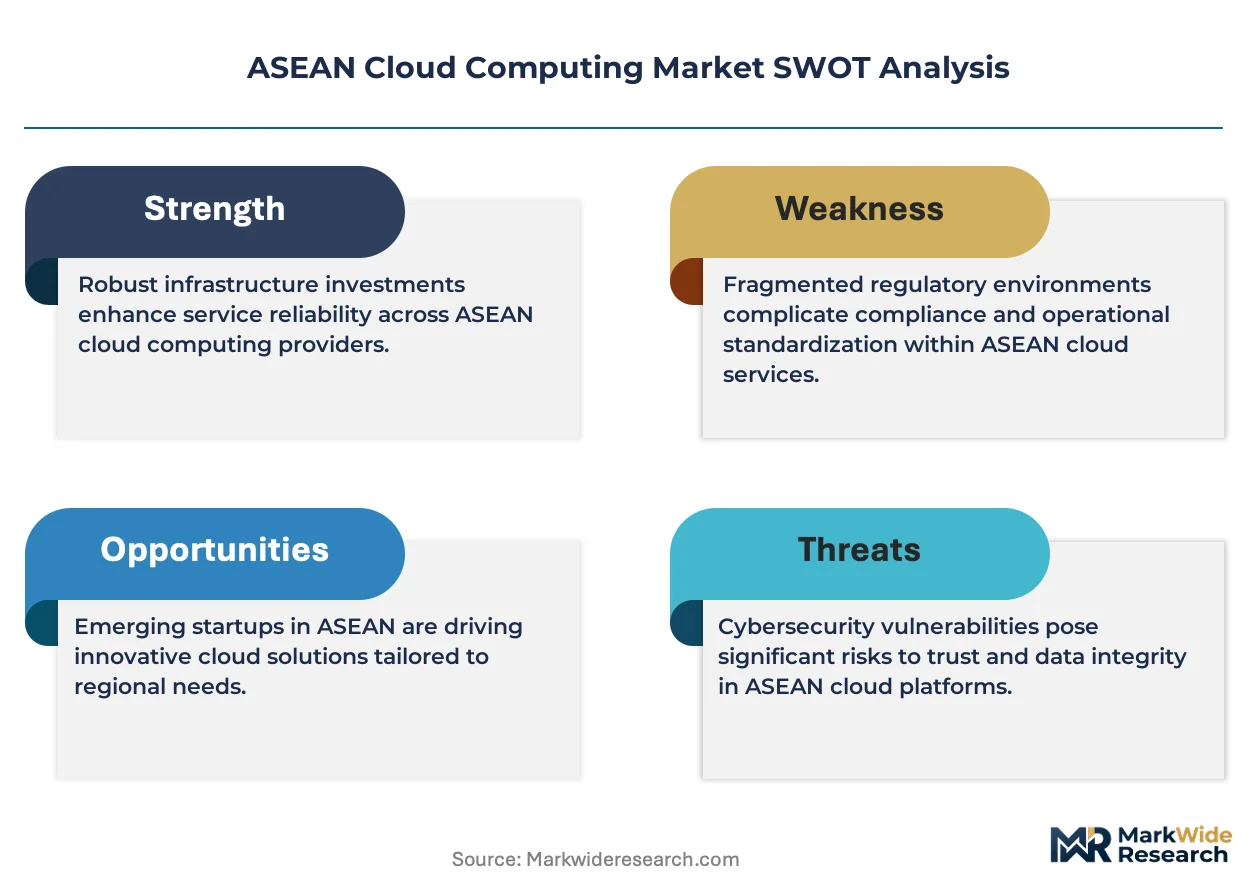
Data localization mandates across Southeast Asia are fragmenting cloud infrastructure deployment strategies, compelling providers to establish sovereign capacity in each jurisdiction rather than serving the region from centralized hubs.
Growth Catalysts
- Malaysia's Personal Data Protection Act:Financial institutions in Kuala Lumpur must maintain domestic data residency, accelerating sovereign cloud procurement from licensed providers.
- Edge computing integration:Manufacturing facilities in Vietnam's northern industrial zones deploy latency-sensitive IoT analytics on localized cloud nodes.
- Indonesian digital economy absorption:Jakarta's emergence as the primary data center cluster concentrates new hyperscale investments serving archipelago-wide demand.
Market Restraints
- Land and power scarcity:Singapore's moratorium on new data center construction limits physical expansion despite sustained demand from banking clients.
- Cross-border transfer friction:Thailand's Personal Data Protection Commission imposes certification delays on multi-tenant platforms serving regional enterprises.
- Talent pipeline constraints:Certified cloud architects and security specialists command premium compensation across Manila, Bangkok, and Ho Chi Minh City labor markets.
Strategic Opportunities
- Philippine archipelago connectivity:Submarine cable investments linking Visayas and Mindanao islands enable distributed cloud nodes for unbanked population digital services.
- Sovereign cloud partnerships:Government procurement frameworks in Indonesia and Vietnam favor domestic joint ventures with foreign hyperscalers.
- Regulatory sandbox participation:Singapore's Infocomm Media Development Authority permits experimental AI workload deployments under conditional compliance waivers.
Industry Challenges
- Multi-jurisdiction certification complexity:Providers must maintain parallel audit trails for Indonesia's Ministry of Communication and Informatics, Malaysia's data protection commissioner, and Singapore's IMDA simultaneously.
- Interoperability with legacy core banking systems:ASEAN financial institutions operate COBOL-based transaction engines requiring extensive middleware development for cloud-native integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Cloud Computing Market |
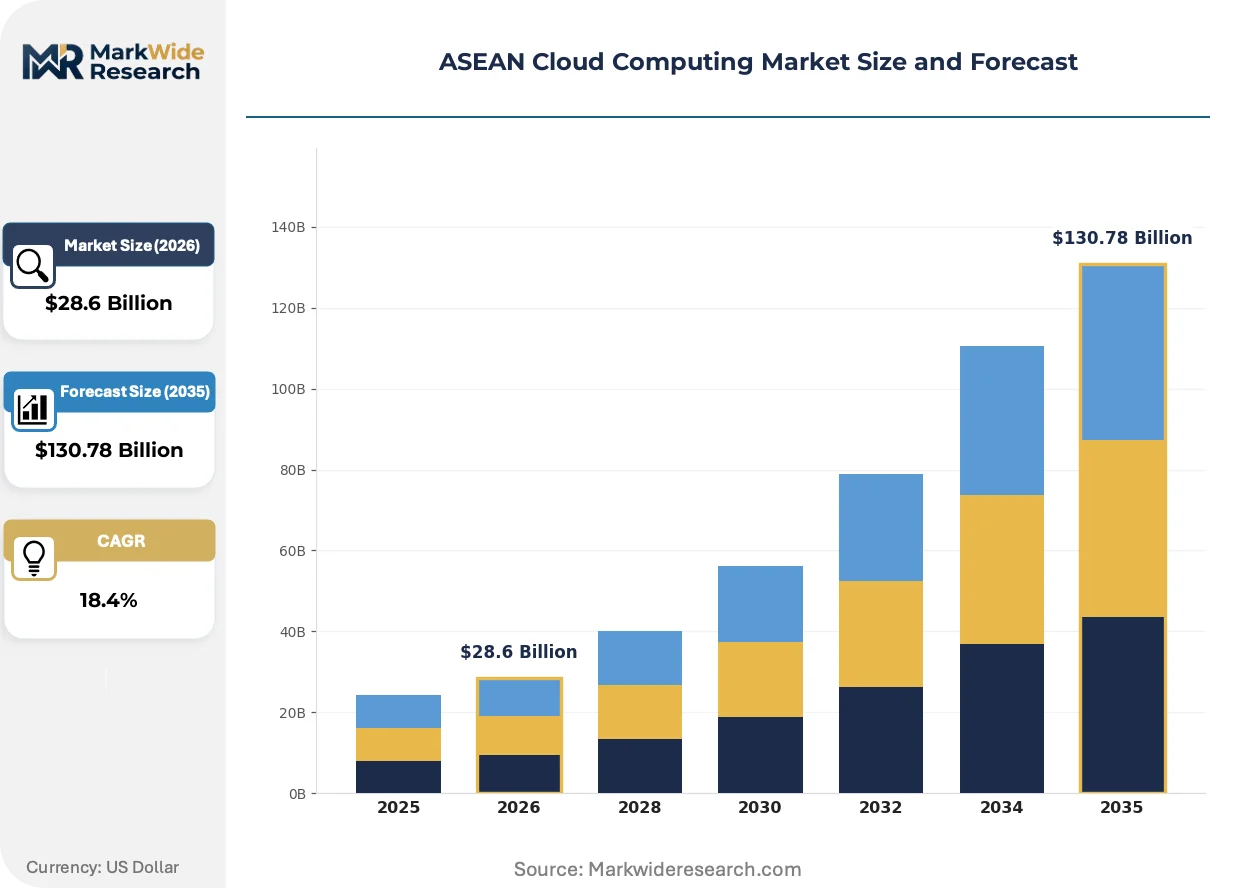
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Service Type: IaaS, PaaS, SaaS, DRaaS End User: SMEs, Large Enterprises, Government, Education Solution: Cloud Storage, Cloud Backup, Cloud Hosting, Cloud Security |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Alibaba Cloud, Huawei Cloud, Tencent Cloud, IBM Cloud, Oracle Cloud, Akamai Technologies, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Cloud Computing Market Trends and Innovations
Workload placement strategies across Southeast Asia are pivoting from cost-optimized centralized processing to compliance-driven distributed architectures that prioritize data sovereignty over unit economics.
Containerized microservices orchestration is migrating from experimental DevOps environments to production-grade financial services deployments. Regional banks in Singapore and Jakarta adopt Kubernetes-based platforms to decouple monolithic applications into independently scalable components. This migration from virtual machine-centric infrastructure to cloud-native architectures compresses deployment cycles from quarterly releases to daily updates.
Singapore's cloud-first government mandates now require all public sector agencies to procure exclusively through accredited domestic availability zones. This directive forces foreign hyperscalers to establish local legal entities and physical infrastructure before qualifying for government contracts. Civil aviation, healthcare, and customs authorities represent the most affected procurement segments, with tender documents explicitly excluding non-sovereign deployment options.
Enterprise buyers now demand consumption-based pricing with committed use discounts rather than traditional reserved instance contracts. Indonesian e-commerce platforms and Thai logistics operators negotiate dynamic scaling clauses that align cloud expenditure with transaction volume fluctuations. This behavioral shift is most visible in retail and transportation verticals where seasonal demand spikes previously forced overprovisioning of on-premises capacity.
ASEAN Cloud Computing Market Segmentation
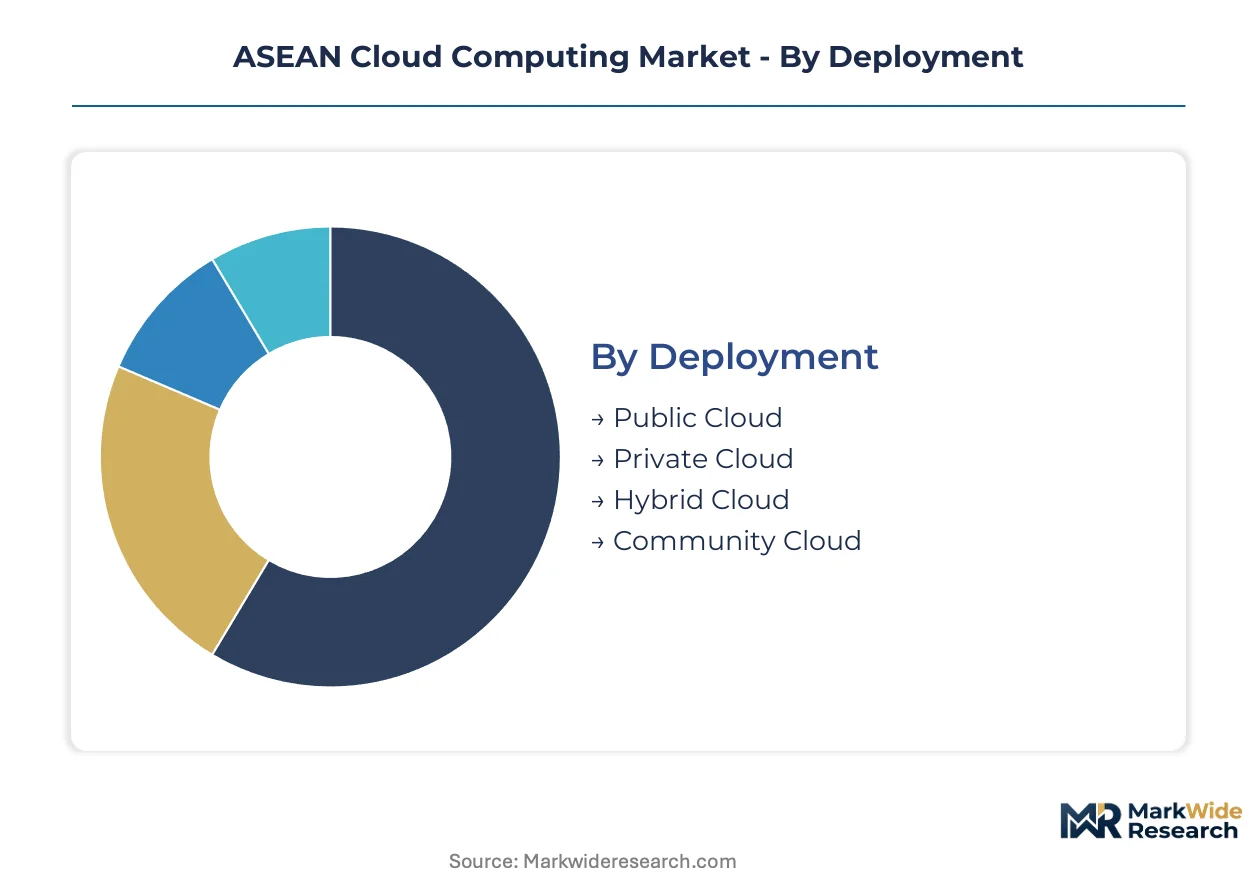
Cloud computing segmentation across Southeast Asia reflects divergent compliance requirements, workload sensitivity, and procurement sophistication. Deployment architecture choices directly determine data residency eligibility for regulated industries. Service model selection correlates with in-house technical capabilities and capital constraints.
Deployment:
Deployment architecture spans infrastructure ownership models from fully shared hyperscale pools to dedicated sovereign environments.
- Public Cloud:Multi-tenant hyperscale infrastructure delivers elastic compute and storage through metered consumption. Indonesian e-commerce platforms and Thai logistics operators dominate procurement volumes, driven by transaction volatility requiring rapid scaling without capital commitment.
- Private Cloud:Single-tenant dedicated infrastructure deployed on-premises or in exclusive colocation facilities. Singaporean banking consortiums and Malaysian financial institutions concentrate demand here, compelled by Monetary Authority of Singapore and Bank Negara Malaysia data residency mandates for core transaction processing.
- Hybrid Cloud:Interoperable architecture linking public burst capacity with private controlled environments. Vietnamese manufacturing groups deploy sensitive IoT analytics on localized nodes while pushing non-critical workloads to regional hyperscale zones.
- Community Cloud:Shared infrastructure serving specific industry verticals or regulatory frameworks. Philippine rural banking cooperatives and Indonesian Islamic finance networks adopt this model to achieve compliance economies unavailable through pure public deployments.
The dominant share belongs to Public Cloud, while Hybrid Cloud is closing the gap fastest.
Service Type:
Service abstraction layers determine customer responsibility for infrastructure management versus application development.
- IaaS:Virtualized compute, storage, and networking resources provisioned through APIs and management consoles. Singapore's civil aviation authority and Jakarta's port automation projects anchor regional demand, prioritizing infrastructure control without physical asset ownership.
- PaaS:Development frameworks, middleware, and runtime environments abstracting underlying infrastructure. Thai fintech startups and Vietnamese software exporters concentrate adoption here, accelerating application deployment without DevOps specialization.
- SaaS:Fully managed applications delivered through web interfaces and mobile clients. Malaysian retail chains and Philippine healthcare networks drive consumption, replacing on-premises ERP and patient management systems with subscription-based alternatives.
- DRaaS:Automated failover and recovery services protecting against site-level infrastructure failures. Singaporean financial institutions and Indonesian banking groups mandate this capability under operational resilience frameworks issued by respective monetary authorities.
SaaS commands the largest revenue pool, though DRaaS is expanding most quickly as regulatory resilience requirements harden.
End User:
Organizational scale and sector governance shape procurement authority and technical sophistication.
- SMEs:Businesses with limited IT staff and constrained capital budgets. Vietnamese manufacturing subcontractors and Philippine service exporters dominate this segment, prioritizing consumption-based pricing and minimal management overhead.
- Large Enterprises:Multinational corporations and major domestic conglomerates with dedicated technology functions. Singaporean commodity traders and Indonesian conglomerates anchor demand, negotiating enterprise licensing and custom compliance architectures.
- Government:National and subnational agencies with sovereign procurement frameworks. Malaysia's public sector digitization initiative and Singapore's cloud-first mandate concentrate volume, requiring domestic legal entity establishment and physical infrastructure presence.
- Education:Universities and technical institutes with research computing and administrative system requirements. Thai higher education institutions and Philippine state universities drive adoption, leveraging academic pricing tiers and grant-funded infrastructure.
Large Enterprises retain the dominant procurement volume, while Government is climbing the fastest as sovereign cloud frameworks mature.
Solution:
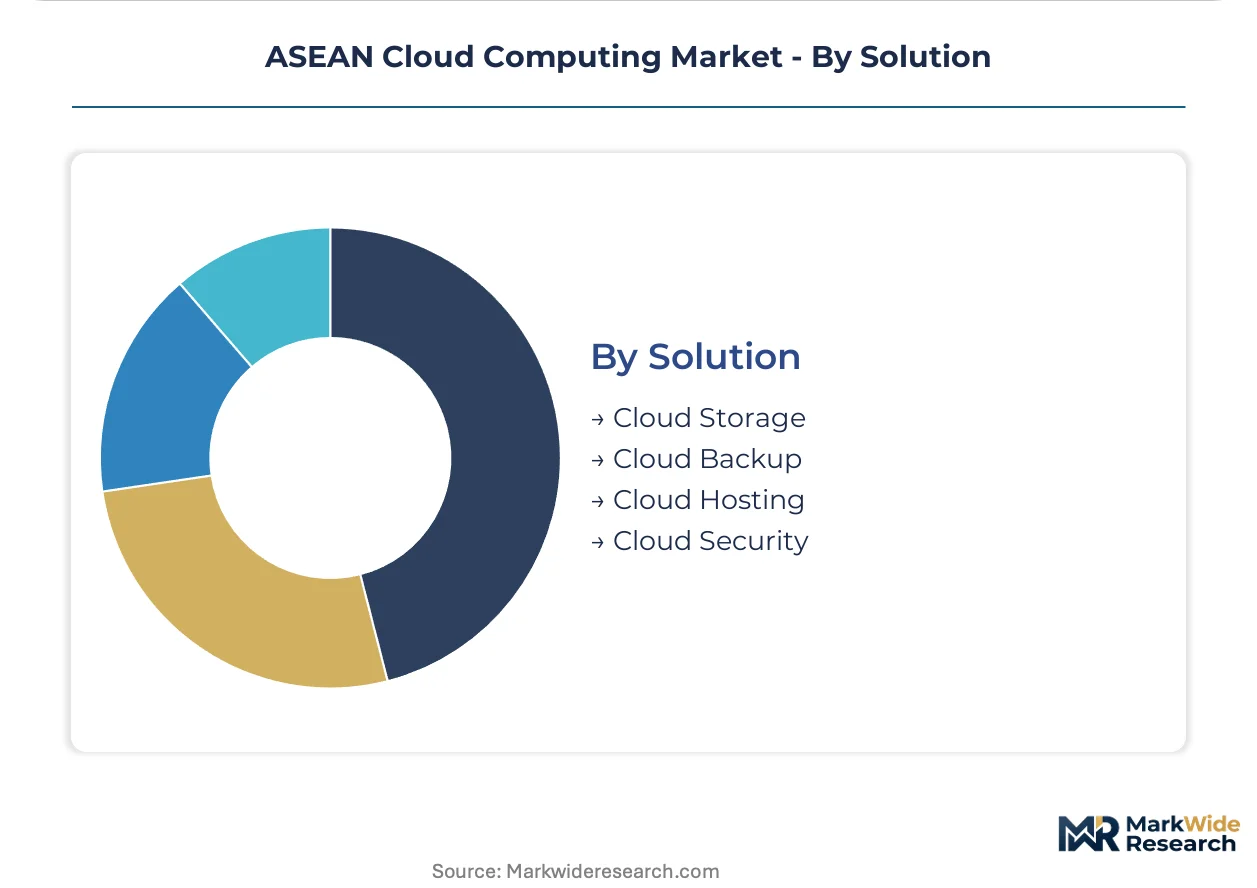
Functional capabilities address specific workload categories from persistent storage to threat protection.
- Cloud Storage:Durable object, block, and file services for unstructured and structured data persistence. Indonesian media streaming platforms and Singaporean genomic research institutes generate concentrated demand for petabyte-scale archival and active dataset hosting.
- Cloud Backup:Automated replication and point-in-time recovery protecting against data loss and corruption. Malaysian healthcare networks and Thai banking groups mandate this capability under sector-specific data protection regulations.
- Cloud Hosting:Application and website delivery infrastructure with global content distribution. Philippine business process outsourcing firms and Vietnamese e-commerce marketplaces depend on low-latency hosting for customer-facing service delivery.
- Cloud Security:Identity management, encryption, threat detection, and compliance monitoring services. Singaporean financial institutions and Indonesian payment processors drive premium consumption, responding to Monetary Authority of Singapore and Bank Indonesia cybersecurity directives.
Cloud Storage holds the dominant position, with Cloud Security gaining share fastest as regulatory enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Infocomm Media Development Authority anchors the region's cloud governance framework through sovereign procurement mandates and availability zone accreditation programs.
Singapore
Financial institutions and government agencies drive concentrated demand for sovereign cloud capacity. The Infocomm Media Development Authority mandates domestic availability zone procurement for all public sector contracts. Marina Bay and Changi North host the densest hyperscale clusters, where providers establish legal entities to qualify for civil aviation and healthcare tenders.
Indonesia
E-commerce platforms and payment processors absorb the majority of new public cloud capacity entering the archipelago. The Ministry of Communication and Informatics enforces data localization certification for financial services workloads. Jakarta's Cikarang and Bogor corridors concentrate hyperscale investments serving nation-wide digital economy expansion.
Malaysia
Banking consortiums in Kuala Lumpur accelerate sovereign cloud migration to modernize core transaction systems. The Personal Data Protection Act compels domestic data residency for financial institutions handling customer records. Iskandar Puteri and Cyberjaya emerge as secondary nodes for disaster recovery and hybrid workload placement.
Thailand
Fintech startups and logistics operators negotiate dynamic scaling contracts aligned with seasonal transaction volatility. The Personal Data Protection Commission imposes certification delays on multi-tenant platforms serving regional enterprises. Bangkok's Ratchada and Bang Na districts host the primary domestic availability zones for regulated workload hosting.
Vietnam
Manufacturing groups deploy latency-sensitive IoT analytics on localized infrastructure nodes. The Ministry of Information and Communications issues cloud service licenses contingent on domestic legal entity establishment. Ho Chi Minh City's Thu Duc and District 7 concentrate industrial zone edge computing deployments for northern factory automation.
ASEAN Cloud Computing Market Competitive Landscape
Hyperscale infrastructure operators and sovereign cloud specialists split the market into distinct capability tiers. Three structural archetypes dominate: US-based hyperscalers with multi-zone regional architectures, Chinese providers optimizing cross-border latency for enterprise subsidiaries, and domestic joint ventures leveraging government procurement preferences. Competitive moves concentrate on sovereign partnership formation and availability zone expansion rather than direct price competition.
Among US-based hyperscalers, Amazon Web Services and Microsoft Azure anchor the premium-tier infrastructure segment through accredited domestic entities. Alibaba Cloud occupies a distinct position serving Chinese enterprise demand across Vietnam and the Philippines. These three providers exemplify the strategic divergence between global scale operations and sovereignty-aligned market access.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Alibaba Cloud |
| Huawei Cloud |
| Tencent Cloud |
| IBM Cloud |
| Oracle Cloud |
| Akamai Technologies |
| Others |
Pricing and Supply Chain Analysis
Jakarta's Cikarang corridor concentrates hyperscale server deployments, concentrating procurement leverage among Indonesian e-commerce platforms and payment processors who negotiate dynamic scaling clauses aligned with transaction volume fluctuations. This geographic capacity clustering feeds downstream pricing power toward buyers in the archipelago's digital economy, while Singapore's land and power scarcity tightens margins for banking clients seeking sovereign cloud residency.
Pricing Analysis
Price spreads between Singapore and Jakarta availability zones reflect land scarcity premiums versus emerging market expansion subsidies. Consumption-based pricing with committed use discounts now dominates enterprise procurement, with Indonesian e-commerce platforms and Thai logistics operators driving the shift away from reserved instance contracts. Certification tier differentiation separates Monetary Authority of Singapore-accredited sovereign zones from standard multi-tenant deployments, with price compression intensifying in the mid-tier as Alibaba Cloud and Huawei Cloud expand Jakarta capacity. SMEs exhibit highest price sensitivity, while Singaporean financial institutions absorb premiums for domestic data residency compliance.
Supply Chain Analysis
Upstream server and networking hardware draws from Taiwan semiconductor foundries, Chinese optical component manufacturers, and Korean memory fabricators, creating multi-source dependencies for hyperscale infrastructure buildouts. Land acquisition in Jakarta's Bogor corridor and power purchase agreements with Indonesian state utilities anchor physical deployment timelines. Single-source vulnerability concentrates in advanced AI accelerators subject to US export licensing restrictions. Distribution runs through domestic legal entity establishment requirements, with providers like Amazon Web Services and Microsoft Azure incorporating local subsidiaries before qualifying for government and banking procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified cloud architects and security specialists command premium compensation across Manila, Bangkok, and Ho Chi Minh City labor markets, constraining delivery capacity for complex sovereign cloud deployments. This talent pipeline gap limits how quickly providers can expand accredited domestic availability zones.
For Market Incumbents: Entrench sovereign cloud partnerships with Indonesia's Ministry of Communication and Informatics and Malaysia's data protection commissioner to lock in certification pathways before competitors establish local legal entities. Prioritize hiring certified security specialists in Ho Chi Minh City and Manila to defend service delivery timelines against talent scarcity. Capacity expansion in Jakarta's secondary corridors—Bogor and Bekasi—preserves margin position as Singapore's moratorium on new data center construction redirects regional demand southward. For New Entrants and Emerging Players: Establish a beachhead in Philippine rural banking cooperatives and Indonesian Islamic finance networks where community cloud demand outstrips hyperscaler attention. Target Vietnamese manufacturing groups deploying latency-sensitive IoT analytics on localized edge nodes, a segment where sovereign compliance requirements favor smaller providers with flexible deployment models. Go-to-market positioning should emphasize rapid domestic legal entity establishment and direct Ministry of Information and Communications licensing engagement. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because data localization mandates across Thailand, Indonesia, and Malaysia are hardening faster than hyperscale providers can establish compliant entities. Acquisition targets should display existing domestic legal entity structures with active certification from national regulators, not just technical infrastructure. The signal to watch is Personal Data Protection Commission enforcement actions in Thailand and Bank Negara Malaysia audit frequency—these indicate when compliance premiums will widen further.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Domestic legal entity establishment qualifies providers for Singapore IMDA government tenders. |
| Edge Computing Node Deployment | Localized infrastructure in Vietnam's northern industrial zones captures manufacturing IoT analytics demand. |
| Certification Investment | Parallel audit trails for Indonesia's Ministry of Communication and Informatics and Malaysia's data protection commissioner unlock banking procurement. |
| Talent Pipeline Development | Certified cloud architect hiring in Manila and Bangkok defends service delivery timelines against premium compensation markets. |
| Dynamic Scaling Contract Structure | Consumption-based pricing with seasonal adjustment clauses aligns with Indonesian e-commerce transaction volatility. |
Research Methodology
A standing panel of cloud infrastructure procurement officers at ASEAN financial institutions, sovereign cloud program managers at national regulators, hyperscale provider country directors, and edge computing systems integrators provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against Infocomm Media Development Authority accreditation disclosures, Ministry of Communication and Informatics licensing databases, Bank Negara Malaysia circulars on data residency, and hyperscaler capital expenditure filings. Bottom-up deployment capacity tracking across Jakarta, Singapore, and Kuala Lumpur availability zones triangulated against top-down digital economy absorption estimates from national statistics offices.
Scenario bracketing anchored the analytical framework, with baseline, accelerated localization, and delayed certification pathways modeled across the projection horizon. Segmentation dimensions included deployment architecture, service abstraction layer, organizational scale, and national regulatory cluster. CAGRs derived from capacity installation timelines, procurement contract velocity, and compliance framework implementation schedules. AI workload deployment waivers under Singapore's regulatory sandbox and Indonesian digital economy transaction growth rates served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in regional currency stability, foreign direct investment flows into data center construction, or semiconductor export licensing regimes would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline continuity and power grid expansion schedules in primary deployment corridors. Cross-checking against Infocomm Media Development Authority and Ministry of Communication and Informatics published licensing volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Asia-Pacific Marketing Cloud Platform Market
Cloud Computing
Cloud Services Brokerage (CSB) Market
Cloud Computing
Cloud ELN Service Market
Cloud Computing
Global Cloud Office Services Market
Cloud Computing
Cloud Banking Solutions Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
Cloud Data Quality Monitoring Market
Cloud Computing
Cloud and Data Center Transformation Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
South Korea Cloud Computing Market
Cloud Computing
Global Cloud High-Performance Computing Market
Cloud Computing
Global Mobile Cloud Market
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
Cloud Enablement Market