
 In-App Purchase Market | 2026-2036
In-App Purchase Market Size, Share, and Industry Trends Forecast 2026-2036
In-App Purchase Market Intelligence
Mobile gaming is repositioning the revenue center of in-app commerce away from static utility apps toward live-service environments. Apple leverages its App Store commission structure to sustain premium transaction margins on iOS. Google competes through Android's broader geographic reach and alternative billing pilot programs. TikTok anchors social commerce innovation by blending entertainment with native checkout flows that bypass traditional retail apps.
In-app purchases represent digital transactions executed within software applications, typically involving micro-transactions processed through platform-native payment rails with 15-30% commission structures. The mechanism enables developers to monetize free distribution through segmented value tiers. Subscriptions and virtual goods dominate current revenue pools, while freemium conversion mechanics show the steepest growth trajectory in emerging markets. Platform segmentation reveals iOS commanding higher average transaction values, whereas Android scales through volume penetration across price-sensitive demographics.
The FTC scrutinizes dark pattern design in mobile interfaces that obscure true subscription costs. The EU Digital Markets Act mandates third-party payment system access, directly threatening platform fee architectures. The CMA in the United Kingdom pursues parallel investigations into Apple and Google billing monopolies. Stakeholders must monitor regulatory fragmentation as jurisdiction-specific compliance costs reshape developer platform preferences and consumer price exposure.
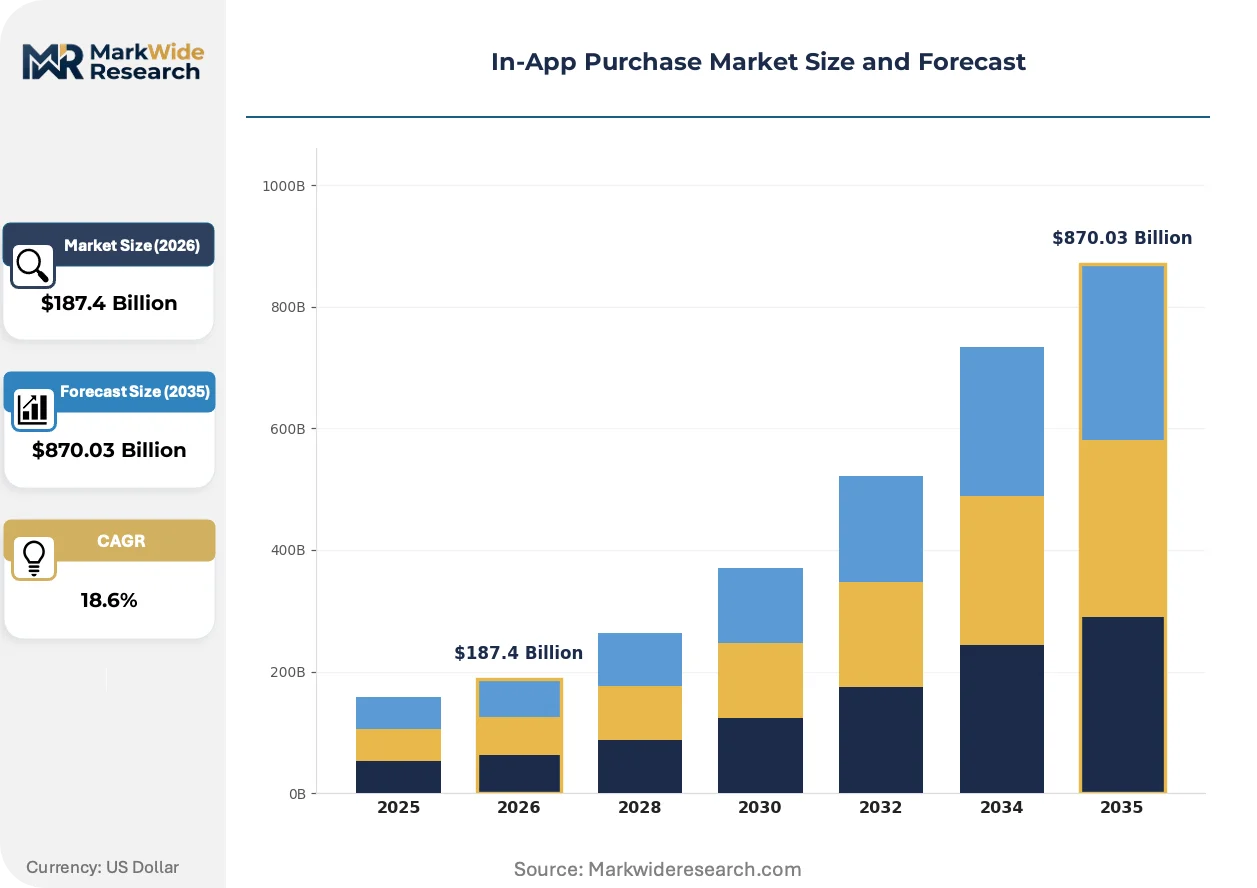
Market Dynamics
Platform gatekeeper regulations under the EU Digital Markets Act are dismantling the 15-30% commission monopoly that Apple and Google have maintained over in-app transactions, forcing structural changes to payment routing and developer economics.
Growth Catalysts
- Battle Pass Mechanics:Mobile gaming studios deploy seasonal progression systems that convert free users into recurring spenders through tiered reward structures. Live-service environments now anchor monetization strategy.
- Alternative Billing Pilots:Google's pilot programs in select jurisdictions demonstrate reduced friction for price-sensitive demographics, expanding addressable markets beyond premium iOS users.
- Social Commerce Integration:TikTok blends entertainment with native checkout flows, creating impulse purchase pathways that bypass traditional retail app intermediaries.
Market Restraints
- Platform Fee Compression Risk:Mandated third-party payment access under EU Digital Markets Act threatens the commission structures sustaining Apple's premium margins.
- Dark Pattern Scrutiny:FTC enforcement actions against subscription interfaces that obscure true costs impose redesign burdens and litigation exposure on developers.
- Geographic Revenue Concentration:Disproportionate iOS revenue generation in the United States creates vulnerability to regional regulatory shocks or consumer spending shifts.
Strategic Opportunities
- India Volume Expansion:Android's dominance among price-sensitive Indian consumers enables freemium conversion mechanics at scale through localized pricing tiers.
- Web-to-App Bypass:Developers exploit progressive web applications to route payments outside platform rails entirely, capturing margin otherwise lost to gatekeepers.
- Cross-Platform Progression:Cloud save synchronization across mobile, console, and PC ecosystems extends purchase persistence and lifetime value beyond single-device silos.
Industry Challenges
- Payment System Fragmentation:Jurisdiction-specific compliance requirements multiply engineering overhead as developers maintain parallel billing integrations for EU, UK, and South Korean markets.
- Conversion Rate Optimization Talent Scarcity:Specialized expertise in behavioral economics and A/B testing for micro-transaction flows commands premium compensation and constrains studio capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-App Purchase Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $870.03 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Goods, Subscriptions, Premium Features, Consumables Platform: iOS, Android, Web, Game Consoles End User: Gamers, Social Media Users, E-Commerce Shoppers, Streaming Subscribers Payment Model: One-Time Purchase, Recurring Payment, Freemium, Advertising-Based |
| Companies Covered | TikTok, Paramount+, Apple, Royal Match, HBO Max, Google, MONOPOLY GO!, Peacock, YouTube, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-App Purchase Market Strategic Shifts & Innovations
Live-service architecture is displacing static application models, embedding commerce into continuous content cycles rather than discrete purchase moments. This structural shift redefines how developers architect user engagement and monetization systems.
Blockchain-based digital ownership verification is electrifying virtual goods markets by enabling interoperable asset portability across gaming environments. Mid-sized studios adopt non-custodial wallet integrations to attract crypto-native user segments. This technology is electrifying secondary market dynamics and pressuring platform holders to accommodate external asset validation.
The EU Digital Markets Act mandates third-party in-app payment system access with interoperability requirements, directly threatening Apple's App Store commission architecture. Developers gain negotiating leverage through regulatory-mandated choice architecture. Mobile gaming publishers with EU user concentration accelerate alternative billing integration to capture margin recovery.
Subscription fatigue among younger demographics drives unbundling of premium tiers into modular micro-purchase options. Gen Z users in the United States demonstrate higher conversion on à la carte virtual goods than on recurring commitments. This behavioral pivot favors battle pass and gacha mechanics over traditional subscription models in content-heavy applications.
In-App Purchase Market Segmentation
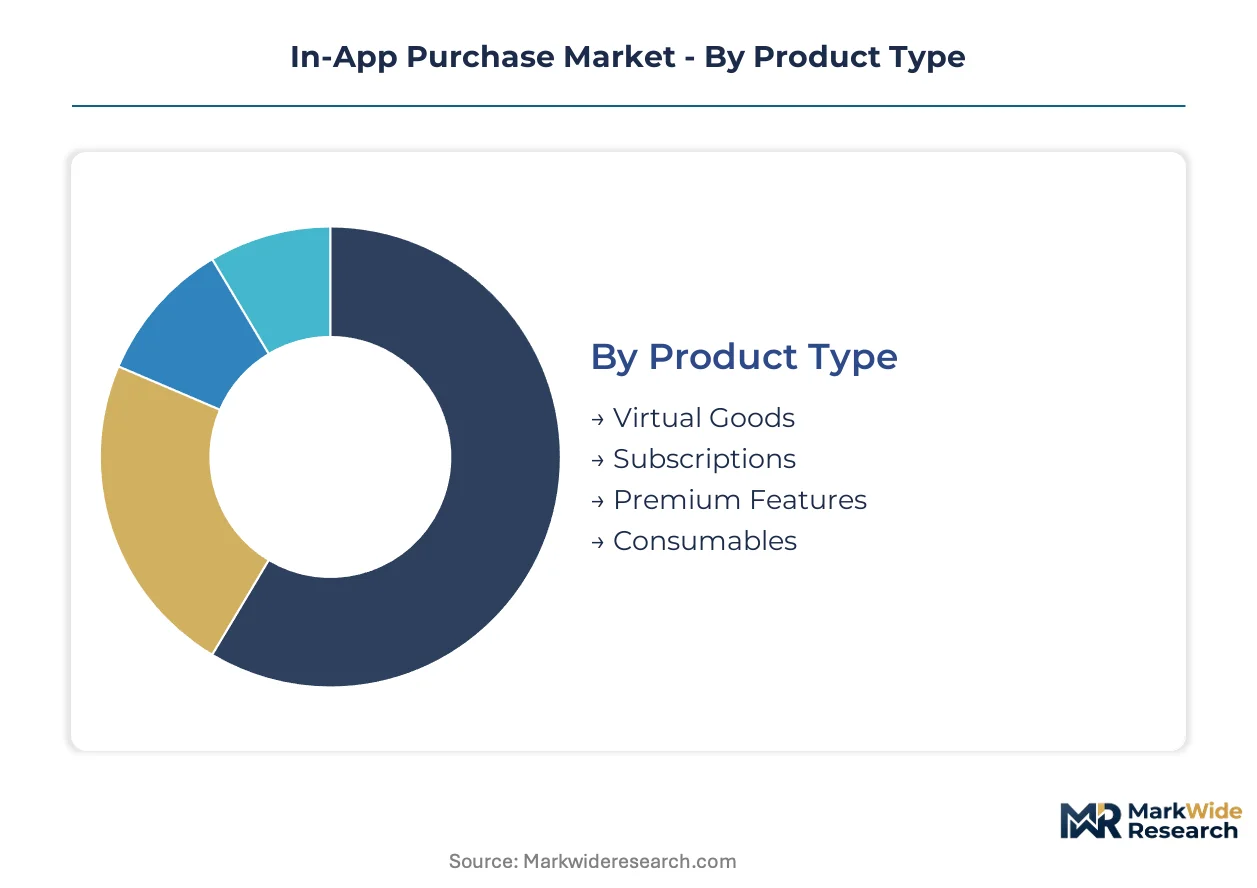
Segmentation in the In-App Purchase Market reveals divergent monetization physics across product types and platforms. Volume-heavy Android ecosystems sustain entirely different unit economics than premium iOS environments, forcing developers to architect parallel revenue strategies rather than unified approaches.
Product Type:
Virtual goods dominate transaction volume through micro-purchase velocity, while subscriptions capture superior lifetime value through recurring commitment structures.
- Virtual Goods:Non-tangible digital assets including character skins, power-ups, and cosmetic enhancements drive impulse purchase behavior through scarcity mechanics and social signaling value. Mobile gaming studios in the United States deploy gacha probability systems to extract maximum spend per engaged user, though regulatory scrutiny from the FTC on loot box mechanics constrains design freedom.
- Subscriptions:Recurring access fees for premium content tiers, cloud storage, or ad-free experiences generate predictable revenue streams with lower churn in productivity and entertainment verticals. European Union developers under Digital Markets Act mandates increasingly route these payments through third-party processors to bypass platform commissions.
- Premium Features:One-time unlocks of advanced functionality within freemium applications.
- Consumables:Depletable virtual resources requiring repeat purchase to sustain gameplay progression.
Today's leader: Virtual Goods. Tomorrow's challenger: Subscriptions.
Platform:
Platform selection determines addressable audience scale, transaction fee exposure, and regulatory jurisdiction complexity for payment routing.
- iOS:Apple's closed ecosystem commands higher average transaction values through affluent user demographics and seamless biometric payment authentication. United States-based developers face 15-30% commission structures that the EU Digital Markets Act now forces open to alternative billing in European markets.
- Android:Google's broader geographic penetration enables volume-based monetization through freemium conversion in price-sensitive demographics, particularly India where localized pricing tiers expand addressable markets.
- Web:Progressive web applications bypass platform gatekeepers entirely through external payment routing.
- Game Consoles:PlayStation and Xbox ecosystems extend purchase persistence through cross-platform progression systems.
iOS retains margin supremacy. Android scales through geographic penetration.
End User:
Behavioral segmentation separates impulse-driven entertainment spenders from utility-motivated productivity purchasers with fundamentally different conversion triggers.
- Gamers:Battle pass mechanics and seasonal progression systems convert free users into recurring spenders through tiered reward structures and fear-of-missing-out psychology.
- Social Media Users:TikTok-native checkout flows blend entertainment with commerce, creating impulse purchase pathways that bypass traditional retail application intermediaries.
- E-Commerce Shoppers:In-app checkout convenience reduces cart abandonment versus mobile web experiences.
- Streaming Subscribers:Ad-free tiers and offline download privileges drive conversion in saturated content markets.
Gamers generate highest per-user spend. Social media users expand fastest through platform-native commerce integration.
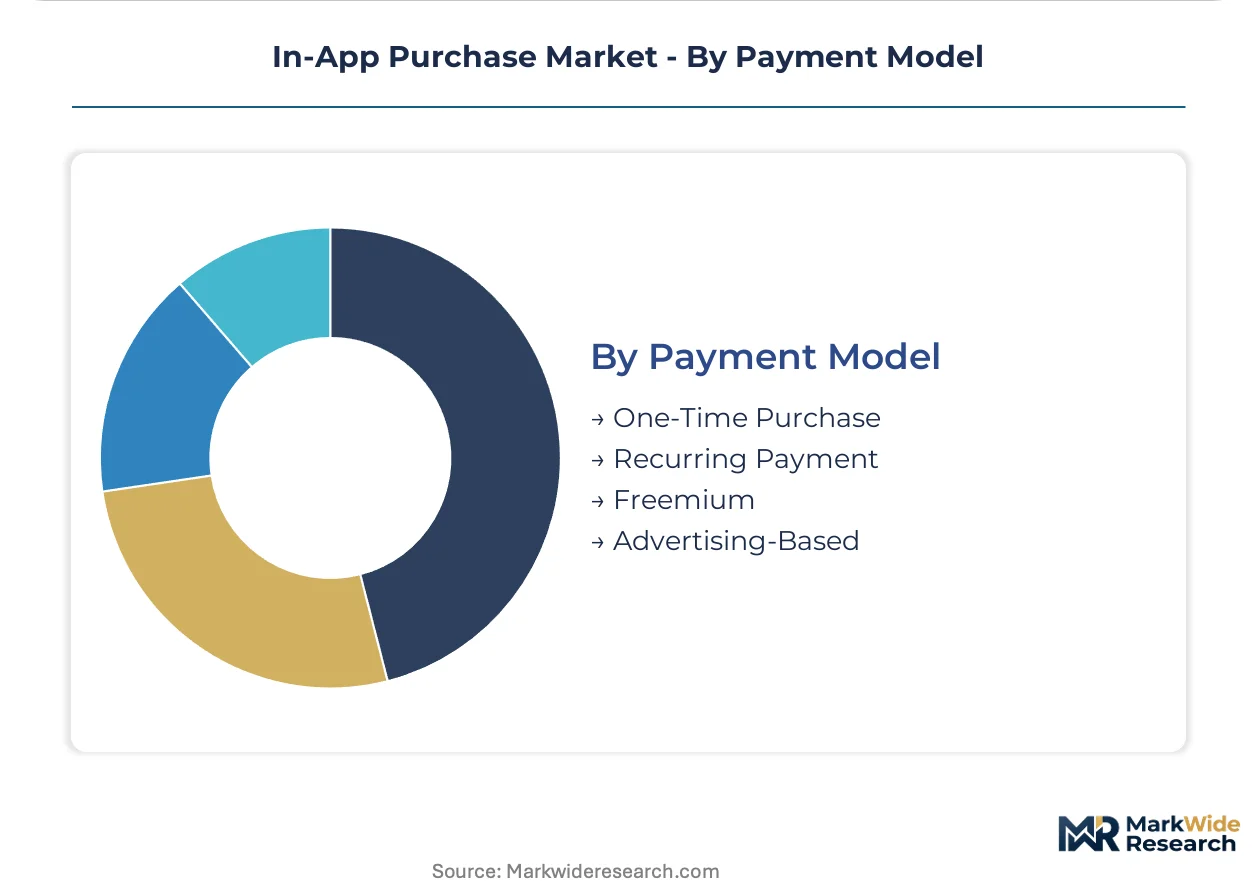
Payment Model:
Revenue architecture choices determine cash flow predictability, platform fee exposure, and vulnerability to subscription fatigue among younger demographics.
- One-Time Purchase:Discrete transaction model with immediate revenue recognition and zero ongoing customer relationship maintenance burden.
- Recurring Payment:Monthly or annual billing cycles generate predictable revenue streams but face elevated churn from Gen Z users demonstrating preference for à la carte virtual goods over commitment.
- Freemium:Tiered conversion funnels separate basic access from premium functionality, enabling zero-friction user acquisition with monetized depth.
- Advertising-Based:Rewarded video and interstitial formats subsidize access for non-paying users while generating indirect revenue.
Recurring payments anchor enterprise valuations. Freemium mechanics expand fastest in emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform fee arbitrage is redirecting developer investment toward jurisdictions with permissive payment routing rules. The EU Digital Markets Act created a compliance cost gap that accelerates alternative billing adoption in Europe while the United States retains premium commission structures.
United States
iOS users in the United States generate disproportionate revenue per download through seamless biometric authentication and affluent demographics. The FTC scrutinizes dark pattern design in subscription interfaces, imposing redesign burdens on developers targeting American consumers. San Francisco and Los Angeles anchor mobile gaming studio clusters where battle pass mechanics and gacha systems dominate monetization architecture.
European Union
The Digital Markets Act mandates third-party payment system access, dismantling Apple's commission monopoly in European markets. Germany's Federal Cartel Office and France's CNIL pursue parallel enforcement actions against platform billing practices. Berlin and Paris host emerging fintech clusters developing alternative payment infrastructure for mobile commerce.
India
Android's dominance among price-sensitive Indian consumers enables freemium conversion mechanics at scale through localized pricing tiers. The Reserve Bank of India regulates digital payment flows while the Telecom Regulatory Authority of India monitors platform fee structures. Bangalore and Hyderabad concentrate mobile gaming development studios targeting domestic volume expansion.
South Korea
The Korea Communications Commission enforced alternative billing mandates before EU regulatory alignment, creating early-mover advantages for domestic payment processors. Seoul anchors mobile gaming conglomerates deploying cross-platform progression systems across mobile, console, and PC ecosystems. Busan hosts emerging blockchain gaming studios integrating non-custodial wallet solutions.
Japan
Gacha probability systems originated in Japanese mobile gaming and remain culturally embedded despite regulatory scrutiny from the Consumer Affairs Agency. Tokyo concentrates social commerce innovation where entertainment-to-commerce conversion rates exceed Western benchmarks. Osaka hosts mid-sized studios adopting web-to-app bypass strategies through progressive web applications.
In-App Purchase Market Key Industry Players
Platform fee compression dominates the current landscape as developers migrate payment routing outside native rails. The market structure concentrates around three gatekeeper platforms controlling distribution infrastructure with divergent responses to regulatory pressure. Strategic archetypes separate commission-dependent incumbents, alternative billing enablers, and web-to-app bypass specialists. Competitive moves center on regulatory arbitrage through geographic licensing shifts and progressive web application deployment.
Among platform gatekeepers, Apple and Google occupy positions representing opposing responses to commission pressure, with Apple defending premium margin structures in permissive jurisdictions while Google pilots alternative billing in regulated markets. TikTok exemplifies the social commerce archetype, anchoring entertainment-integrated checkout flows that bypass traditional retail application intermediaries.
| Leading Market Players |
|---|
| TikTok |
| Paramount+ |
| Apple |
| Royal Match |
| HBO Max |
| MONOPOLY GO! |
| Peacock |
| YouTube |
| Others |
Cost & Logistics Intelligence
Premium iOS user monetization versus Android volume penetration creates a bifurcated pricing architecture that manifests in parallel supply chain configurations for payment processing infrastructure. Platform gatekeeper regulations in the European Union under the Digital Markets Act force alternative billing integration costs onto developers, while biometric authentication investments sustain Apple's transaction premium in permissive jurisdictions.
Pricing Analysis
Direct-to-developer platform fees anchor the dominant pricing structure, with Apple extracting 15-30% commissions on iOS transactions while Google pilots reduced-rate alternative billing in regulated markets. Price differentiation hinges on user affluence demographics and seamless payment authentication technology. Pricing pressure stems from EU-mandated third-party payment access threatening commission monopolies. Price sensitivity concentrates among Android users in emerging markets, while iOS users in the United States demonstrate lowest elasticity.
Supply Chain Analysis
Engineering talent scarcity in Bangalore, Berlin, and Seoul constrains payment system integration capacity as developers maintain parallel billing stacks for jurisdiction-specific compliance. Supply concentration centers on Ireland for European data residency requirements, Singapore for Asia-Pacific transaction routing, and the United States for fraud detection infrastructure. Raw material dependencies include cloud compute capacity, biometric authentication hardware, and cross-border payment rails. Single-source vulnerability runs through Apple's App Store review bottleneck. Distribution runs through platform-native rails with emerging web-to-app bypass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the In-App Purchase Market rests on regulatory arbitrage through alternative billing adoption and premium-tier conversion mechanics in live-service gaming environments.
For Market Incumbents: To counter EU Digital Markets Act commission compression, Apple should deepen in-house payment authentication investments to sustain biometric convenience premiums in unregulated markets. Google must accelerate alternative billing pilot scale-up to capture developer loyalty before jurisdictional fragmentation hardens. Both platforms should tighten cloud infrastructure integration to raise switching costs for multi-homing developers. For New Entrants and Emerging Players: Enter via progressive web application deployment to bypass platform gatekeepers entirely, capturing 15-30% margin recovery through external payment routing. Target India's price-sensitive Android user base with localized freemium conversion mechanics and UPI-native checkout flows. Pursue TikTok-style social commerce integration blending entertainment with impulse purchase pathways. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized conversion rate optimization talent scarcity constrains studio capacity to execute live-service monetization. Long-term viability favors platforms with regulatory agility across multiple jurisdictions and proprietary user engagement data. Acquisition target archetype: mid-sized mobile gaming studios with proven battle pass mechanics and EU alternative billing integration. Signal to watch: cross-platform progression technology enabling purchase persistence beyond single-device silos.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Billing Integration | EU Digital Markets Act compliance enables margin recovery through third-party payment routing. |
| Live-Service Architecture Deployment | Seasonal content cycles convert free users into recurring spenders through tiered reward structures. |
| Cross-Platform Progression Systems | Cloud save synchronization extends purchase persistence across mobile, console, and PC ecosystems. |
| Biometric Authentication Investment | Seamless payment convenience sustains premium transaction values in iOS user segments. |
| Social Commerce Integration | TikTok-native checkout flows create impulse purchase pathways bypassing traditional retail intermediaries. |
Research Approach
Direct dialogue with mobile gaming studio executives, platform payment product managers, EU regulatory affairs specialists, and behavioral economics consultants grounded qualitative insights for this analysis. Secondary validation drew from SEC filings, App Annie transaction data, Digital Markets Act implementation guidance, and Korea Communications Commission enforcement records. Bottom-up and top-down triangulation reconciled developer-reported monetization metrics with platform-disclosed commission revenue across the analysis window.
Bottom-up modeling aggregated transaction volume by platform, product type, and geography while top-down validation cross-checked against platform-reported services revenue. Segmentation dimensions included iOS versus Android ecosystem, virtual goods versus subscriptions versus consumables, and gamer versus social media user versus streaming subscriber behavioral archetypes. CAGRs were derived from regression analysis of historical transaction velocity and regulatory impact scenarios. Forecast inputs incorporated battle pass adoption curves and alternative billing penetration rates by jurisdiction.
The model holds under stable platform gatekeeper regulations and consistent live-service content investment cycles; deviation in EU enforcement intensity or subscription fatigue acceleration among Gen Z demographics would shift trajectory. Forecasts reflect assumptions about biometric authentication convenience premiums and cross-platform progression technology adoption. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Application Performance Management Market
Digital Solutions
Global DDI Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Europe API Management Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Digital Clothing Market
Digital Solutions
Global Data Historian Market
Digital Solutions
Beacons Management Software Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Global Drilling Data Management Systems Market
Digital Solutions
Smart Connected Assets and Operations Market