
 Contact Tracing Application Market | 2026-2036
Contact Tracing Application Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Tracing Application Market Analysis
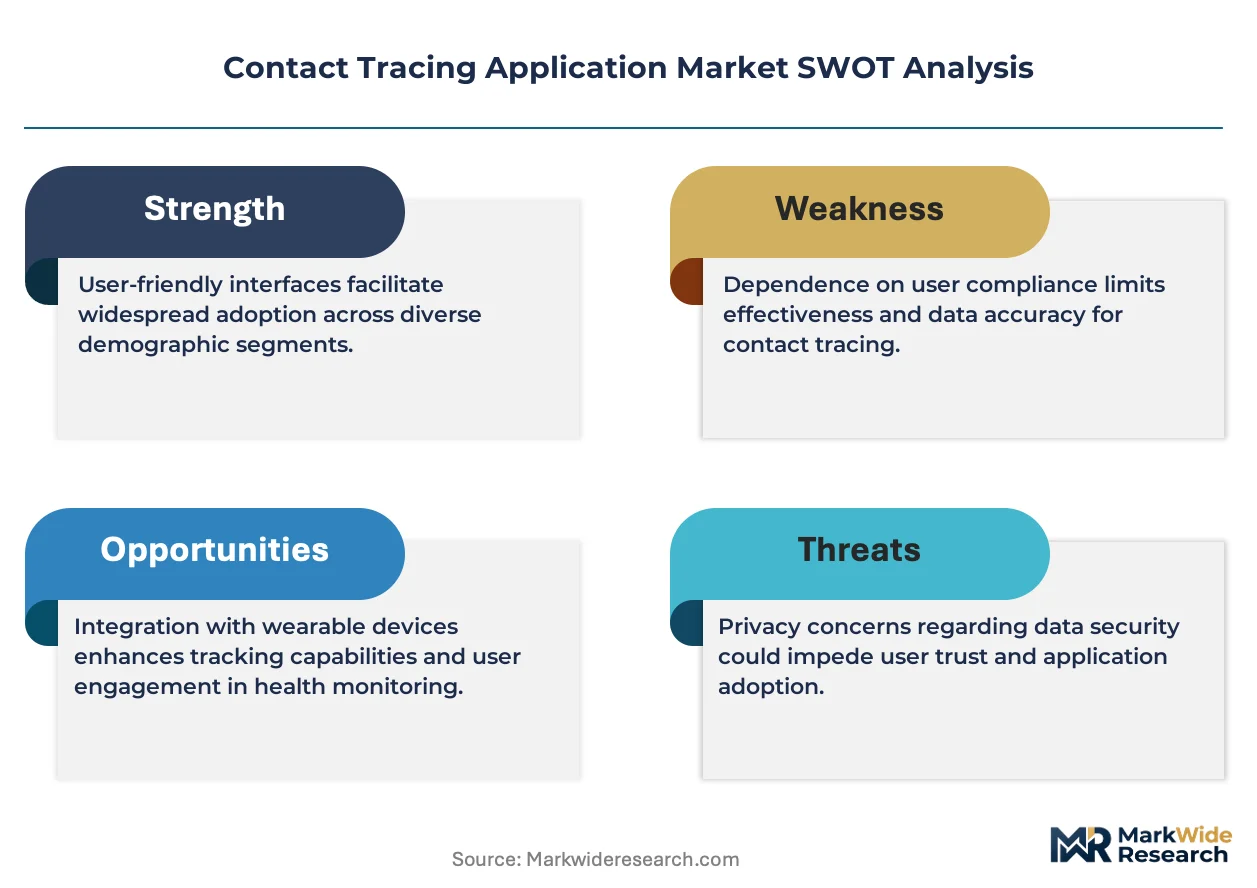
North American software developers is decoupling from legacy centralized architectures toward decentralized Bluetooth frameworks. Apple Inc. leverages its Exposure Notification API to sustain ecosystem control across iOS devices. Google LLC anchors the Android counterpart through open-source protocol standardization. IBM Corporation competes in enterprise-grade outbreak analytics for corporate campuses and hospital networks.
Contact tracing applications are proximity-sensing software platforms that use Bluetooth Low Energy signals, GPS coordinates, or QR code timestamps to log interpersonal encounters and flag potential pathogen exposure chains, primarily serving public health authorities and organizational risk managers. Mobile apps lead deployment volume due to smartphone ubiquity, while API integrations represent the fastest-expanding segment as health systems embed tracing logic into existing electronic medical records and workforce management platforms. Cloud-based deployment captures the dominant margin pool through recurring SaaS subscriptions, whereas on-premise installations retain niche demand among defense contractors and intelligence agencies with data sovereignty requirements.
The FDA oversees clinical decision-support algorithms embedded in healthcare-facing tracing tools, while the FCC governs Bluetooth spectrum allocation for proximity-sensing accuracy. GDPR in Europe and state-level biometric privacy laws in Illinois and California constrain location data retention policies, forcing vendors to architect jurisdiction-specific data governance modules. Stakeholders must monitor evolving interoperability standards between national health databases and private sector platforms to anticipate compliance-driven procurement cycles.
Market Dynamics
Bluetooth Low Energy proximity detection is converging with federated learning architectures to enable privacy-preserving epidemiological surveillance without centralized data repositories. This technical shift is compressing procurement timelines for healthcare systems seeking pandemic preparedness infrastructure.
Growth Catalysts
- Post-pandemic preparedness mandates:North American healthcare providers face institutional requirements to maintain digital contact tracing capabilities, driving recurring SaaS subscriptions for cloud-based deployment models.
- Germany's institutionalization of digital epidemiological infrastructure:The country's federal health ministry mandates interoperability standards that force vendors to architect jurisdiction-specific data governance modules.
- API integration into electronic medical records:Health systems embed tracing logic directly into existing workforce management platforms, expanding addressable market beyond standalone mobile applications.
Market Restraints
- GDPR location data retention constraints:European regulators enforce strict temporal limits on Bluetooth encounter logs, forcing costly re-architecture of backend storage systems for multi-jurisdiction deployments.
- Input cost volatility in semiconductor components:Bluetooth Low Energy chipsets face supply concentration risk from East Asian foundries, creating margin pressure on hardware-dependent proximity sensing systems.
- Technical limitation in indoor positioning accuracy:GPS signal degradation inside hospital complexes and corporate campuses reduces contact attribution precision below clinical utility thresholds.
Strategic Opportunities
- Singapore's Smart Nation sensor network convergence:The city-state's existing IoT infrastructure offers integration pathways for ambient environmental sensing combined with personal proximity detection.
- South Korean workplace safety mandates:Occupational health regulations require manufacturing facilities to maintain exposure documentation, creating regulatory tailwind for enterprise-grade outbreak analytics.
- Illinois biometric privacy law compliance services:Vendors can monetize jurisdiction-specific legal engineering as a recurring revenue stream separate from core software licensing.
Industry Challenges
- Interoperability standardization delays:Fragmented protocols between national health databases and private sector platforms extend sales cycles as buyers await clarity on data exchange specifications.
- Cybersecurity certification complexity:FedRAMP and HITRUST compliance timelines for cloud-based deployments stretch 14-18 months, delaying revenue recognition for government-facing contracts.
- Legacy electronic medical record integration friction:Hospital IT departments face skill gaps in HL7 FHIR implementation, requiring vendor professional services that compress software margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Tracing Application Market |
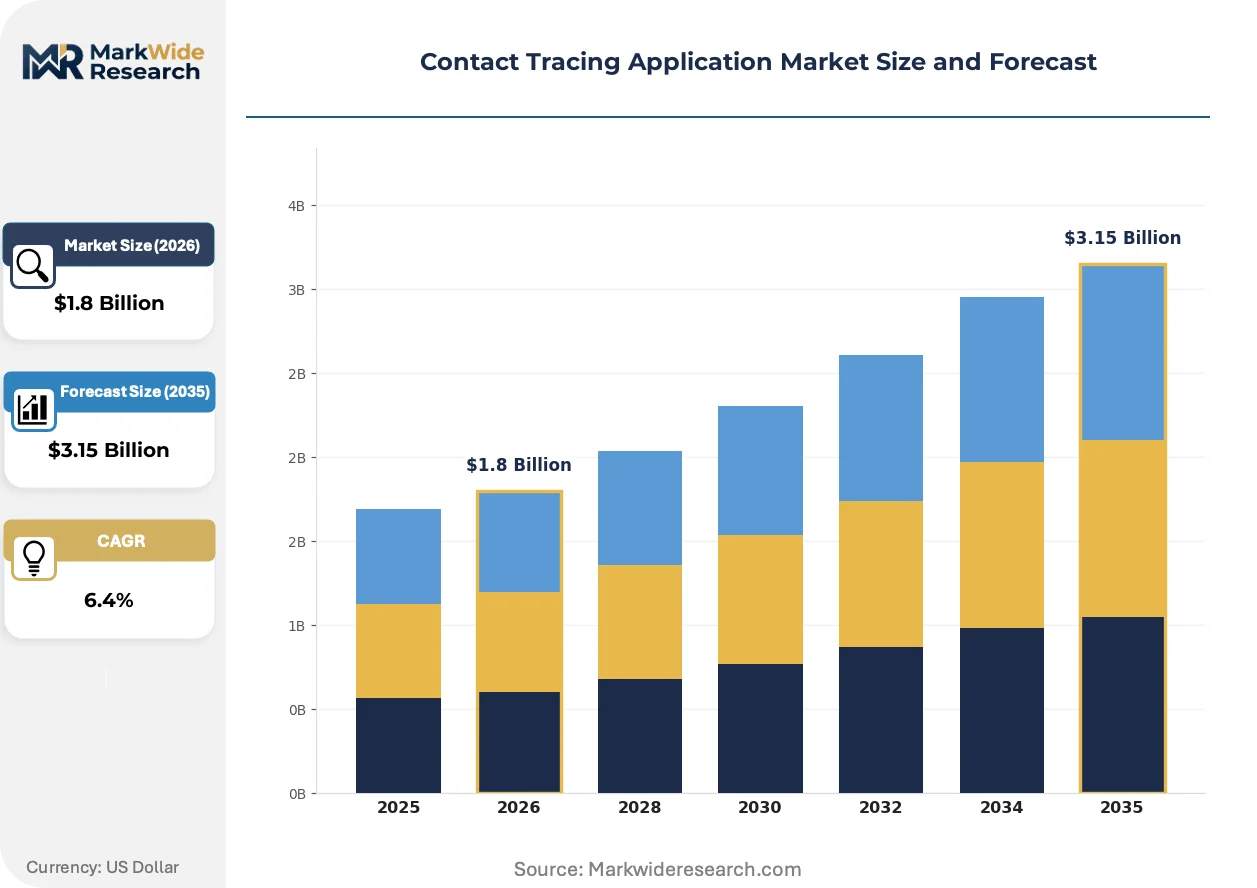
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Mobile Apps, Web-Based Solutions, API Integrations, Standalone Software End User Type: Healthcare Providers, Government Agencies, Corporate Sector, Educational Institutions Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS Technology Used: Bluetooth, GPS Tracking, QR Code Scanning, User Authentication |
| Companies Covered | Apple Inc., Google LLC, Microsoft Corporation, IBM Corporation, SAP SE, Oracle Corporation, Everbridge, Salesforce.com, Cisco Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Tracing Application Market Emerging Trajectories
Decentralized identity frameworks are displacing centralized server architectures across privacy-sensitive health technology deployments. This architectural rotation is reshaping competitive positioning around data sovereignty rather than feature breadth.
Edge-based federated learning is converging with on-device Bluetooth signal processing to enable exposure notification without raw location data leaving the handset. South Korean semiconductor firms are accelerating production of neural processing units optimized for this workload. The structural consequence is compression of cloud infrastructure spend per active user, forcing vendors to recapture margin through premium analytics tiers.
GDPR's Article 17 right-to-erasure provisions are forcing re-engineering of contact graph databases to support surgical deletion of individual encounter records without corrupting epidemiological models. German health authorities now require cryptographic proof of deletion as a procurement prerequisite. Enterprise buyers in France and the Netherlands are adopting these same technical specifications ahead of anticipated CNIL enforcement actions.
Hospital procurement committees are unbundling outbreak analytics from core contact tracing licenses, treating predictive risk scoring as a separate budget line item. This purchasing pattern shift concentrates negotiating leverage with integrated health systems possessing in-house data science capabilities. The phenomenon is most visible in California, where Kaiser Permanente and Sutter Health have established captive epidemiological modeling teams.
Contact Tracing Application Market Segmentation
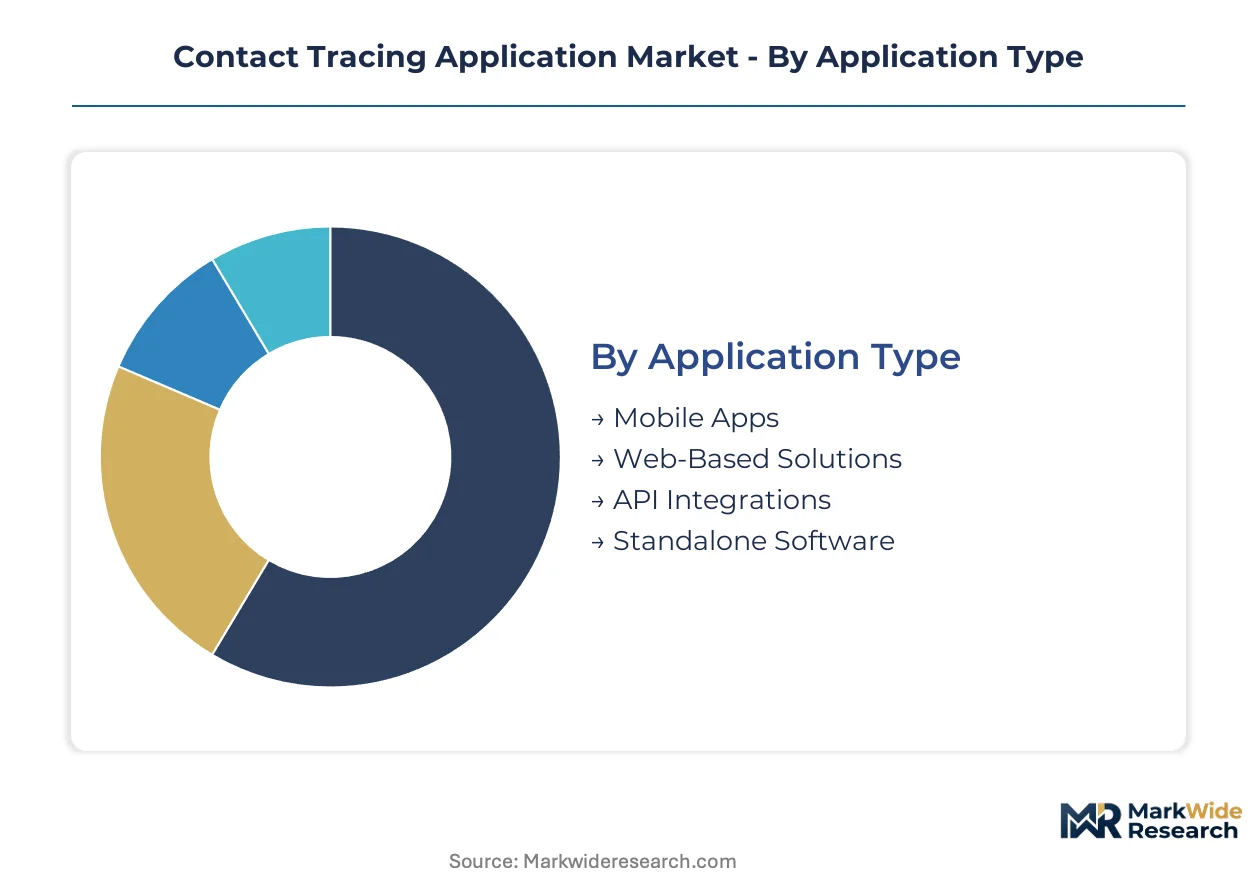
Segmentation in contact tracing applications reveals how procurement committees allocate budget across certification tiers. Deployment models and technology choices carry divergent compliance burdens that reshape vendor selection criteria.
Application Type:
FDA clearance applies to clinical decision-support features in healthcare-facing deployments, while FCC governs Bluetooth spectrum usage across all proximity-sensing formats.
- Mobile Apps:Smartphone-native platforms process Bluetooth Low Energy signals on-device to log interpersonal encounters without centralized data repositories. Demand concentrates among North American healthcare providers seeking post-pandemic preparedness infrastructure, driven by institutional mandates for digital epidemiological capabilities.
- API Integrations:Embedded tracing logic within existing electronic medical records and workforce management platforms via HL7 FHIR protocols. German health authorities require these modules for interoperability with federal epidemiological databases, compressing procurement timelines for compliant vendors.
- Web-Based Solutions:Browser-accessible dashboards for outbreak analytics requiring HITRUST certification for healthcare data handling.
- Standalone Software:On-premise installations for defense contractors with FedRAMP compliance and data sovereignty requirements.
Leading the category by volume: Mobile Apps. Growing fastest: API Integrations.
End User Type:
Cost tier stratification separates enterprise-grade analytics budgets from public sector grant-funded deployments.
- Healthcare Providers:Hospital networks and integrated delivery systems purchase predictive risk scoring as unbundled budget line items. Kaiser Permanente and Sutter Health in California have established captive epidemiological modeling teams, concentrating negotiating leverage with vendors.
- Corporate Sector:Manufacturing facilities under South Korean occupational health regulations maintain exposure documentation through enterprise-grade outbreak analytics. Workplace safety mandates create regulatory tailwind for premium analytics tiers.
- Government Agencies:Federal and state public health authorities procure through extended sales cycles awaiting interoperability standardization.
- Educational Institutions:Campus safety departments with constrained IT budgets favor SaaS subscriptions over capital-intensive on-premise installations.
Healthcare Providers command the steepest pricing premiums. Corporate Sector procurement is climbing the fastest.
Deployment Model:
Margin concentration follows recurring revenue predictability, with cloud architectures capturing dominant margin pools through subscription economics.
- Cloud-Based:SaaS delivery with recurring subscriptions dominates procurement across Germany, South Korea, and Singapore as governments institutionalize digital epidemiological infrastructure. GDPR Article 17 right-to-erasure provisions force re-engineering of contact graph databases to support surgical deletion without corrupting epidemiological models.
- SaaS:Multi-tenant architectures with jurisdiction-specific data governance modules for GDPR, Illinois BIPA, and California biometric privacy compliance.
- On-Premise:Air-gapped installations for intelligence agencies with data sovereignty requirements and 14-18 month FedRAMP certification timelines.
- Hybrid:Edge-based federated learning with on-device processing and cloud analytics tier for premium risk scoring.
Cloud-Based deployment leads by recurring revenue volume. SaaS is expanding most quickly as procurement shifts from capital to operational expenditure.
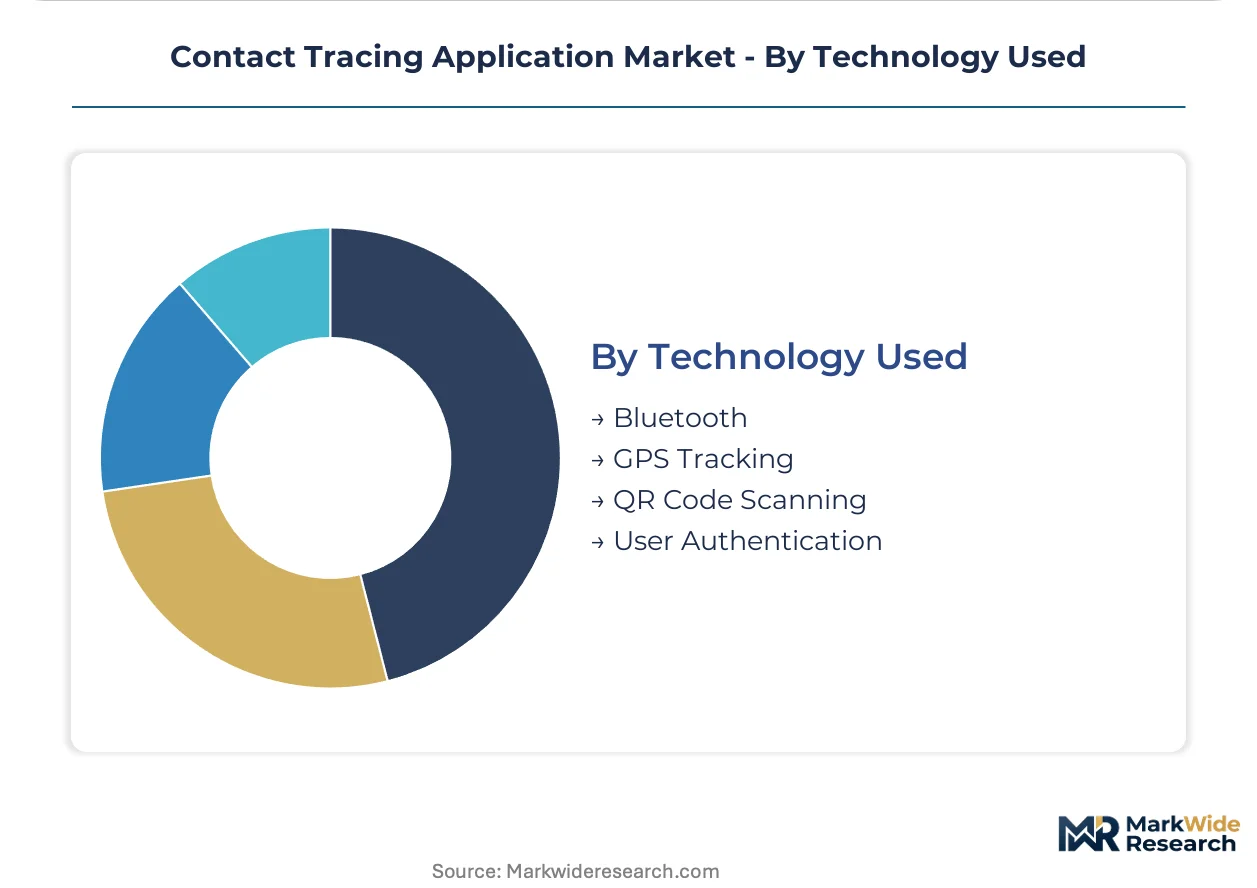
Technology Used:
Supply concentration in East Asian foundries for Bluetooth Low Energy chipsets creates margin pressure on hardware-dependent proximity sensing systems.
- Bluetooth:Low Energy proximity detection converges with federated learning architectures for privacy-preserving surveillance without centralized repositories. South Korean semiconductor firms accelerate neural processing unit production optimized for on-device signal processing.
- GPS Tracking:Signal degradation inside hospital complexes and corporate campuses reduces contact attribution precision below clinical utility thresholds, limiting addressable market.
- QR Code Scanning:Timestamp-based encounter logging with minimal hardware dependencies for cost-constrained deployments.
- User Authentication:Decentralized identity frameworks displacing centralized server architectures across privacy-sensitive health technology deployments.
Bluetooth leads the category by installed base. User Authentication is gaining share fastest as decentralized architectures reshape competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bluetooth Low Energy chipset fabrication concentrates in Taiwan and South Korea, anchoring hardware supply for proximity-sensing deployments across healthcare and enterprise sectors.
United States
Hospital networks in California and Texas drive procurement of cloud-based outbreak analytics, with Kaiser Permanente and Sutter Health operating captive epidemiological modeling teams. FDA oversees clinical decision-support algorithms embedded in healthcare-facing tools, while Illinois BIPA and California biometric privacy laws constrain location data retention policies. The Boston-Cambridge corridor hosts specialized vendors architecting jurisdiction-specific compliance modules for multi-state deployments.
Germany
Federal health ministry mandates for digital epidemiological infrastructure compress procurement timelines for interoperable tracing systems. GDPR Article 17 right-to-erasure provisions force re-engineering of contact graph databases to support surgical deletion without corrupting epidemiological models. Berlin and Munich clusters concentrate vendors developing cryptographic proof-of-deletion capabilities as procurement prerequisites.
Singapore
Smart Nation sensor network convergence creates integration pathways for ambient environmental sensing combined with personal proximity detection. Government institutionalization of digital epidemiological infrastructure drives concentrated demand for cloud-based deployment models. The city-state's IoT infrastructure spans commercial districts and public housing estates, enabling unified exposure notification architectures.
South Korea
Occupational health regulations require manufacturing facilities in Gyeonggi Province and Busan-Ulsan to maintain exposure documentation, creating regulatory tailwind for enterprise-grade outbreak analytics. MFDS oversight extends to clinical decision-support features in workplace safety applications. Seoul-based semiconductor firms accelerate neural processing unit production optimized for on-device federated learning workloads.
United Kingdom
NHS procurement committees unbundle outbreak analytics from core contact tracing licenses, treating predictive risk scoring as separate budget line items. MHRA governs software-as-medical-device classifications for clinical-facing deployments. London and Manchester health systems concentrate negotiating leverage through integrated data science capabilities, reshaping vendor selection criteria toward API interoperability.
Contact Tracing Application Market Vendor Landscape
Global majors compete with regional champions across regulatory compliance depth and healthcare system integration reach. The vendor base stratifies into three tiers: platform ecosystem controllers anchoring mobile operating systems, enterprise software incumbents with existing health system relationships, and specialized outbreak analytics vendors. Dominant competitive moves include API standardization alliances and jurisdiction-specific legal engineering services as recurring revenue streams.
Within the platform ecosystem tier, Apple Inc. and Google LLC occupy positions as operating system gatekeepers through exposure notification protocol standardization. IBM Corporation exemplifies the enterprise analytics archetype, competing for corporate campus and hospital network contracts. Microsoft Corporation and Oracle Corporation sit within the cloud infrastructure tier, leveraging existing SaaS relationships to embed tracing logic into workforce management platforms.
| Leading Market Players |
|---|
| Apple Inc. |
| Google LLC |
| Microsoft Corporation |
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Everbridge |
| Salesforce.com |
| Cisco Systems, Inc. |
| Others |
Supply Flow & Price Mechanics
Bluetooth Low Energy chipset fabrication costs cascade through three distinct pricing tiers, with Taiwan and South Korean foundry concentration compressing margins for hardware-dependent proximity sensing systems while cloud-native vendors capture recurring SaaS premiums.
Pricing Analysis
Service-bundling separates premium tiers from stripped-down offerings, with HITRUST-certified outbreak analytics commanding unbundled budget line items separate from core contact tracing licenses. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FedRAMP and GDPR Article 17 compliance driving differentiation. Cost compression in standard tiers intensifies because semiconductor input volatility from East Asian foundries squeezes hardware-dependent vendors. Educational institutions exhibit highest price sensitivity due to constrained capital budgets, while defense contractors with data sovereignty requirements show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan Semiconductor Manufacturing and Samsung Foundry for neural processing units optimized for on-device federated learning. Hardware supply draws from Taiwan, South Korea, and China, with Bluetooth Low Energy chipsets, GPS modules, and QR code scanning components forming critical input dependencies. Tariff exposure on semiconductor imports from China creates structural risk for margin-stretched vendors. Distribution runs through direct enterprise sales for healthcare and corporate contracts, supplemented by public sector procurement frameworks in Germany and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story, with GDPR Article 17 right-to-erasure provisions and cryptographic proof-of-deletion requirements erecting barrier-to-entry moats that favor vendors with jurisdiction-specific legal engineering capabilities.
For Market Incumbents: Hedge against margin erosion in hardware-dependent tiers by deepening API integration partnerships with electronic medical record platforms, while accelerating backward integration into neural processing unit design to offset foundry concentration risk. FedRAMP certification timelines stretching 14-18 months favor early movers with existing government relationships.
For New Entrants and Emerging Players: Digital-channel routes through HL7 FHIR protocol compliance offer the most penetrable entry path, targeting German health authorities with interoperable tracing modules as procurement timelines compress. Campus safety departments in educational institutions represent underserved demand for SaaS-native outbreak analytics with minimal hardware dependencies.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized outbreak analytics vendors with cryptographic deletion capabilities in Berlin and Munich clusters, where regulatory tailwinds from anticipated CNIL enforcement actions concentrate. Watch for interoperability standardization clarity between national health databases and private platforms as the inflection signal for government-facing contract acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| GDPR Article 17 Compliance Engineering | Cryptographic proof-of-deletion capabilities unlock German federal procurement mandates. |
| HL7 FHIR API Integration | Embedded tracing logic within Kaiser Permanente and Sutter Health systems expands addressable market. |
| Neural Processing Unit Co-Design | Seoul-based semiconductor partnerships compress cloud infrastructure spend per active user. |
| FedRAMP Certification Acceleration | Air-gapped deployment eligibility captures intelligence agency data sovereignty requirements. |
| Jurisdiction-Specific Legal Engineering | Illinois BIPA and California biometric privacy modules monetize compliance as recurring revenue. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across public health IT directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) submissions, GDPR enforcement actions from CNIL and Berlin data protection authorities, Bluetooth SIG certification databases, and hospital procurement databases formed the documentary backbone. Bottom-up active user estimates triangulated against top-down epidemiological infrastructure spending projections.
Data-stream reconciliation across deployment model, end-user type, technology architecture, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs derived from logistic adoption curves fitted to institutional mandate implementation timelines, with semiconductor foundry capacity constraints and interoperability standardization delays as industry-specific forecast inputs across the projection horizon.
The model holds under stable regulatory enforcement intensity; deviation in GDPR Article 17 interpretation or Bluetooth protocol standardization would shift vendor competitive positioning. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Bangladesh ICT Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Global Mobile Content Management Market
Digital Solutions
Contactless Ticketing Solutions Market
Digital Solutions
Key Management As a Service (Kmaas) Market
Digital Solutions
Big Data Technology Market
Digital Solutions
Demand Signal Repository Solutions Market
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Virtual Desktop Infrastructure (VDI) Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
United States ICT Market
Digital Solutions
Europe Multichannel Order Management Market
Digital Solutions
Smart Card Reader Market