
 Digital Signage Services Market | 2026-2036
Digital Signage Services Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Signage Services Market Outlook
Buyer concentration in the retail sector is recalibrating as mid-sized chains fragment procurement across specialized AV integrators while flagship operators consolidate under single-vendor managed service contracts. Samsung Electronics leverages its captive semiconductor and panel supply to bundle hardware with recurring content management subscriptions. Stratacache anchors its position through proprietary caching software that reduces bandwidth costs for high-density screen networks. NEC Display Solutions competes on commercial-grade reliability warranties that appeal to transportation hub operators with 24/7 uptime requirements.
Digital signage services encompass the design, deployment, integration, and ongoing management of networked visual communication systems, typically involving display hardware with minimum 4K resolution, media players with embedded Linux or Android operating systems, and cloud-connected content distribution platforms that schedule and render dynamic media across geographically dispersed endpoints. These systems serve commercial and institutional buyers seeking real-time audience engagement, operational messaging, or advertising monetization in physical spaces. Content management and cloud-based deployment segments command the deepest recurring revenue pools because customers trade capital intensity for predictable operational expenditures, while analytics solutions represent the fastest-expanding margin layer as computer vision and dwell-time measurement capabilities mature. LED technology segments sustain premium pricing for outdoor and high-ambient-light installations, whereas LCD deployments occupy the volume base across indoor corporate and retail environments.
The FCC governs electromagnetic emissions and equipment authorization for digital display hardware sold in the United States, while the EU Green Deal and Ecodesign directives push manufacturers toward lower standby power consumption and recyclable panel architectures. GDPR in Europe and state-level biometric privacy laws in Illinois and Texas constrain how analytics solutions capture and process audience demographic data. Stakeholders must weigh regulatory compliance costs against the revenue potential of personalized, sensor-triggered content delivery as privacy frameworks tighten across their operating geographies.
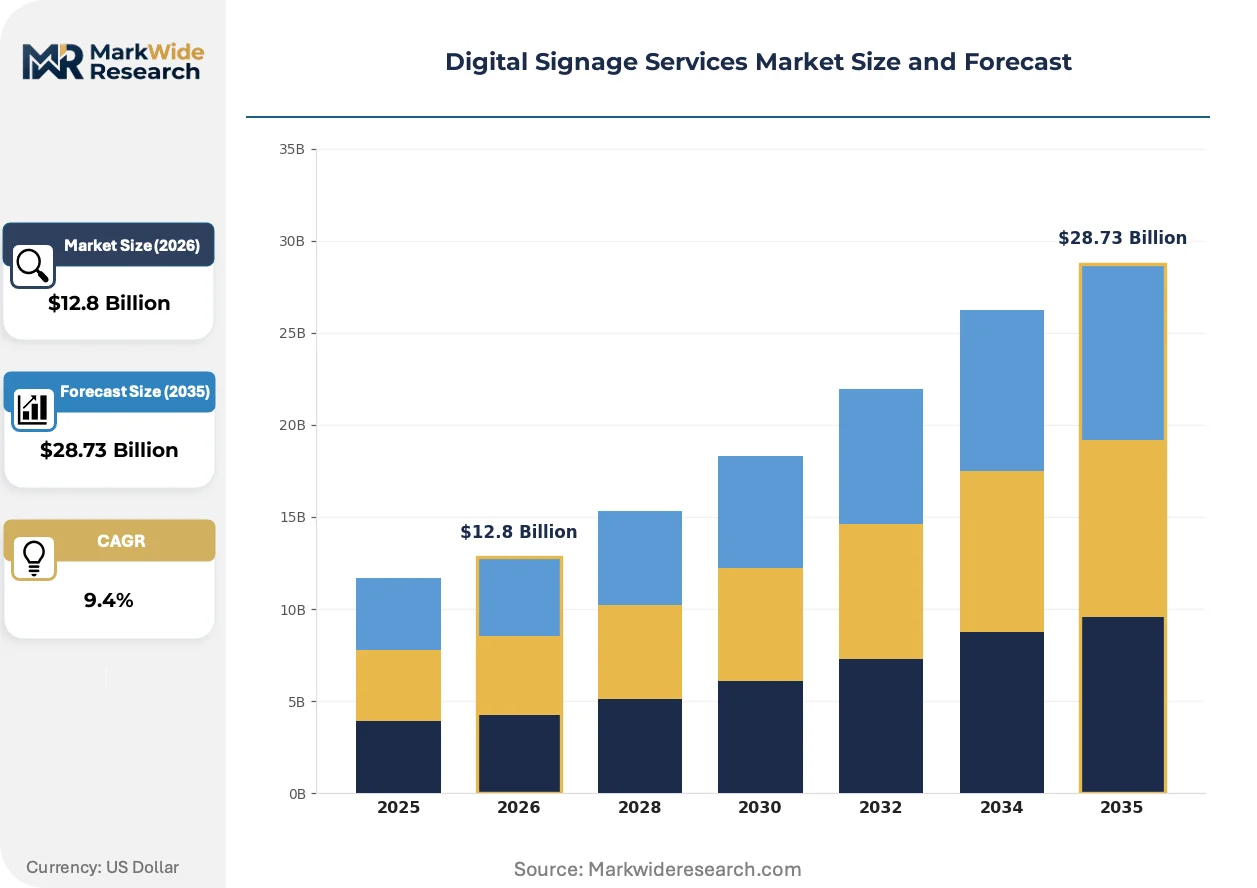
Market Dynamics
Cloud-based content management platforms are compressing deployment timelines and converting capital-heavy display rollouts into recurring operational expenditures, restructuring how retail chains and transportation authorities budget for visual communication infrastructure.
Growth Catalysts
- EU Green Deal Ecodesign mandates:Manufacturers accelerate LED backlight efficiency improvements and recyclable panel architectures to preempt compliance deadlines, creating upgrade cycles among installed base customers.
- Airport and transit hub modernization:Transportation authorities in Germany, Japan, and the United States deploy high-density screen networks for wayfinding and advertising monetization, driving demand for managed service contracts with guaranteed uptime.
- Computer vision analytics integration:Dwell-time measurement and demographic inference capabilities expand addressable use cases beyond passive content display into measurable audience engagement platforms.
Market Restraints
- Display panel supply concentration:South Korean and Chinese TFT-LCD and OLED substrate manufacturers control upstream capacity, exposing downstream integrators to allocation volatility during semiconductor cycle peaks.
- GDPR and Illinois BIPA biometric constraints:Analytics solutions face restricted deployment in European and select US state jurisdictions where facial recognition and demographic capture trigger consent and retention compliance burdens.
- LCD thermal degradation in outdoor installations:Liquid crystal response times and color accuracy degrade above 50°C ambient temperatures, limiting indoor-centric technology transfer to uncontrolled environments without costly thermal management.
Strategic Opportunities
- India smart city infrastructure programs:Municipal digital kiosk and public information display tenders under the Ministry of Housing and Urban Affairs create localized deployment opportunities for systems integrators with domestic manufacturing partnerships.
- Healthcare wayfinding and queue management:Hospital networks in France and Canada expand digital directory deployments to reduce staff interruption costs and improve patient flow metrics in acute care facilities.
- 5G network slicing for real-time content:Telecommunications operators in South Korea and Japan offer guaranteed bandwidth tiers that enable latency-sensitive interactive applications previously constrained by last-mile connectivity.
Industry Challenges
- Embedded Linux and Android security patching:Media player firmware maintenance across geographically dispersed endpoints strains integrator technical support capacity and exposes customers to CVE disclosure response gaps.
- FCC equipment authorization timeline variability:Hardware import delays from testing backlog at accredited laboratories compress project delivery schedules for US-bound deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Signage Services Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Content Management, Display Hardware, Software Development, Analytics Solutions End User: Retail Stores, Corporate Offices, Hospitality, Transportation Hubs Deployment: Cloud-Based, On-Premise, Hybrid Solutions, Managed Services Technology: LCD, LED, Projection, E-paper |
| Companies Covered | Samsung Electronics, LG Electronics, NEC Display Solutions, Panasonic Corporation, Stratacache, BrightSign, Cisco Systems, Sony Corporation, Daktronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Signage Services Market Strategic Shifts
Edge computing architectures and low-latency connectivity are redistributing processing loads from centralized cloud infrastructure toward local media players, enabling responsive interactive experiences without persistent wide-area network dependence.
Direct-view LED microdisplay technology is rewriting brightness and form-factor assumptions for indoor corporate and retail environments. Premium department stores in Milan and Tokyo adopt sub-2mm pixel pitch cabinets for seamless video wall installations previously dominated by tiled LCD arrays. The technology is compressing acceptable viewing distances and expanding placement options in space-constrained flagship locations.
The EU AI Act risk classification framework imposes documentation and human oversight requirements on computer vision analytics that process biometric data. Signage operators deploying audience measurement tools in France and Germany must maintain algorithmic impact assessments and audit trails. Transportation hubs and retail chains are responding by segregating data processing jurisdictions and investing in on-premise inference to limit cross-border data flows.
Mid-sized retail chains fragment vendor relationships across specialized AV integrators rather than consolidating under single-source managed service contracts. Flagship operators in contrast demand comprehensive uptime guarantees and remote monitoring dashboards. This bifurcation is most visible in the United Kingdom and Australia, where regional retail cooperatives negotiate project-based hardware procurement while airport authorities sign five-year operational service agreements with penalty clauses for availability shortfalls.
Digital Signage Services Market Segmentation
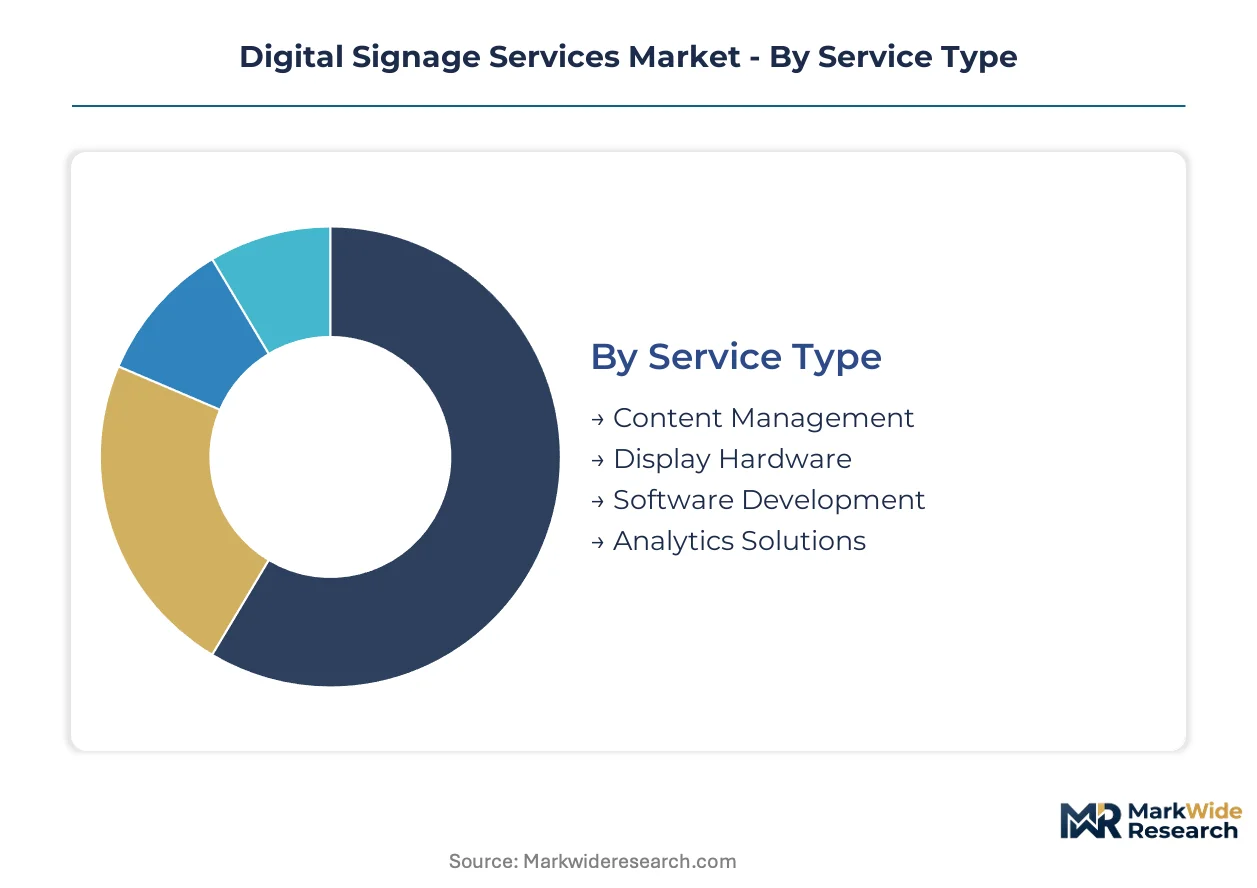
Digital signage services fragment across multiple axes that determine procurement patterns and vendor selection criteria. Service type dictates revenue model structure, while deployment mode shapes customer capital allocation and ongoing operational burden.
Service Type:
Upgrade cycles vary dramatically across service categories, with hardware refresh timelines compressing as display technology advances and software subscription models extending customer relationships beyond initial deployment.
- Content Management:Cloud-connected platforms schedule, distribute, and render dynamic media across geographically dispersed endpoints. Retail chains in Germany and Japan prioritize these recurring subscription services to convert capital-heavy rollouts into predictable operational expenditures. The segment captures the deepest recurring revenue pools as customers trade upfront hardware investment for ongoing service relationships.
- Display Hardware:Physical screens, media players, and mounting infrastructure with minimum 4K resolution specifications and embedded Linux or Android operating systems. Airport authorities in the United States and transportation operators in Japan demand commercial-grade reliability with 24/7 uptime warranties, driving premium pricing for hardened components.
- Software Development:Custom application creation for interactive kiosks, wayfinding systems, and proprietary content rendering engines. Bespoke projects concentrate among flagship retail operators seeking differentiated customer experiences.
- Analytics Solutions:Computer vision and dwell-time measurement capabilities that transform passive displays into audience engagement platforms. GDPR in Europe and Illinois BIPA constraints restrict deployment scope where biometric capture triggers compliance burdens.
Content Management sits at the top of the volume ranking, with Analytics Solutions climbing the fastest despite regulatory headwinds.
End User:
Customer type determines performance requirements, with 24/7 operational environments demanding fundamentally different service level agreements than intermittent-use settings.
- Retail Stores:Mid-sized chains fragment procurement across specialized AV integrators while flagship operators consolidate under single-vendor managed service contracts with comprehensive uptime guarantees.
- Corporate Offices:Indoor environments prioritize LCD deployments for space-constrained installations, with IT departments favoring cloud-based content management to minimize on-premise infrastructure.
- Hospitality:Hotels and resorts deploy digital directories and wayfinding systems to reduce staff interruption costs and improve guest flow metrics, particularly in French and Canadian acute care facilities.
- Transportation Hubs:Airports and transit authorities in Germany, Japan, and the United States deploy high-density screen networks for wayfinding and advertising monetization, driving demand for managed service contracts with penalty clauses for availability shortfalls.
Retail Stores anchor the largest addressable base, though Transportation Hubs generate the highest contract values per deployment.
Deployment:
Delivery model selection reflects customer IT maturity, bandwidth infrastructure, and risk tolerance for data sovereignty.
- Cloud-Based:Centralized content distribution platforms compress deployment timelines and enable remote management of geographically dispersed endpoints. South Korean and Japanese telecommunications operators offer 5G network slicing with guaranteed bandwidth tiers that enable latency-sensitive interactive applications.
- On-Premise:Local server infrastructure maintains content libraries and scheduling systems behind customer firewalls. Healthcare networks in France and financial institutions in Germany favor this model for sensitive data environments.
- Hybrid Solutions:Split architectures cache content locally while leveraging cloud connectivity for management and analytics, balancing responsiveness with centralized oversight.
- Managed Services:Comprehensive operational contracts covering hardware maintenance, content updates, and performance monitoring with guaranteed uptime SLAs. Airport authorities in the United Kingdom and Australia sign five-year agreements with penalty structures for availability shortfalls.
Cloud-Based deployments dominate new installations, while Managed Services expand most quickly among transportation and healthcare verticals.
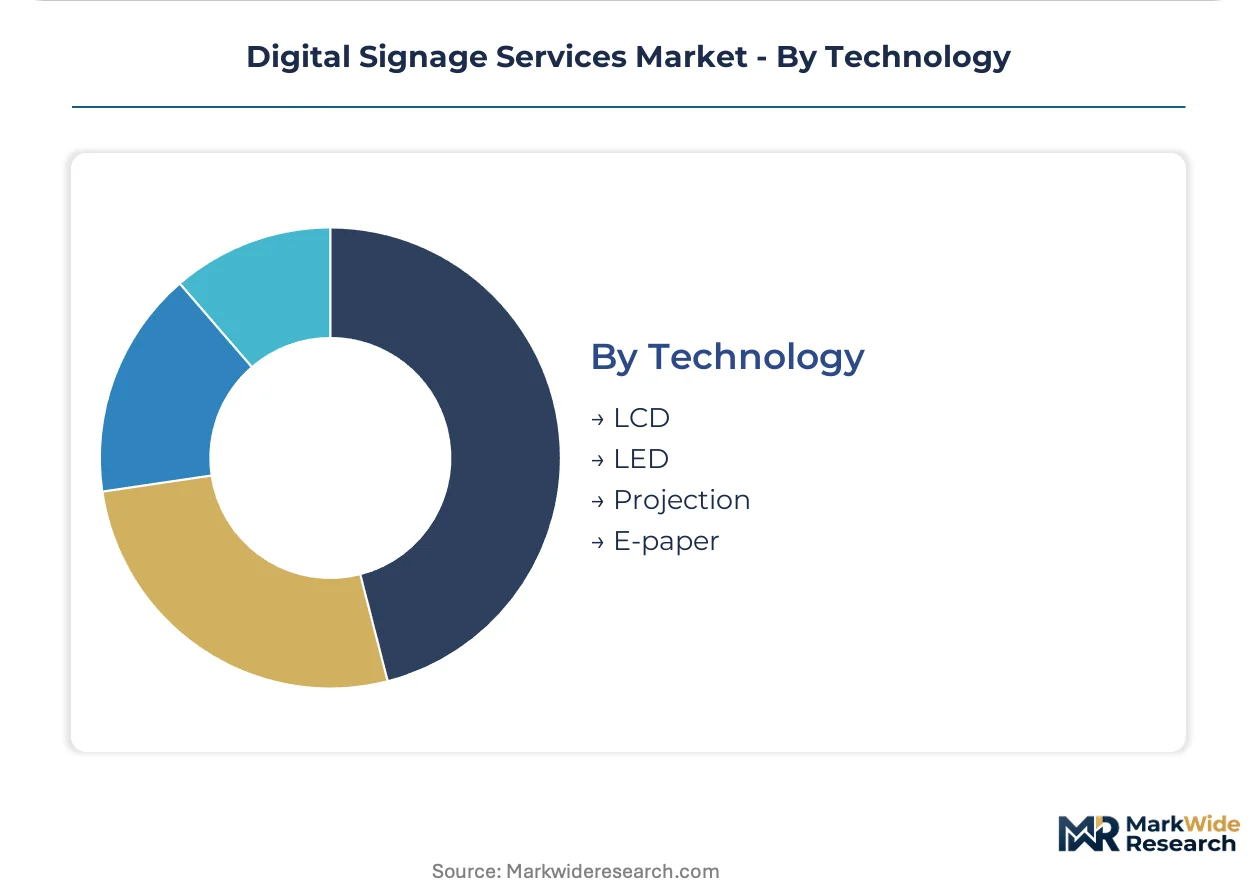
Technology:
Display technology selection hinges on ambient light conditions, viewing distance requirements, and thermal management constraints.
- LCD:Liquid crystal panels occupy the volume base across indoor corporate and retail environments. Thermal degradation above 50°C ambient temperatures limits technology transfer to uncontrolled outdoor installations without costly thermal management systems.
- LED:Direct-view LED microdisplay technology with sub-2mm pixel pitch cabinets enables seamless video wall installations in premium department stores in Milan and Tokyo. The technology sustains premium pricing for outdoor and high-ambient-light installations where brightness and durability justify higher costs.
- Projection:Large-format display solutions for temporary installations and immersive environments where physical screen deployment proves impractical.
- E-paper:Bistable display technology consuming power only during content updates, suited for static wayfinding and shelf-label applications with minimal animation requirements.
LCD retains the highest installation volume, with LED gaining share fastest as pixel pitch improvements compress acceptable viewing distances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean display manufacturers supply flagship retail networks in Tokyo while German transportation authorities source managed service contracts from domestic systems integrators, revealing how regional specialization shapes procurement geography.
United States
Airport authorities in Atlanta and Dallas deploy high-density screen networks for wayfinding and advertising monetization. The FCC's equipment authorization rules govern electromagnetic emissions for imported display hardware, creating testing backlog risks at accredited laboratories. Chicago and Los Angeles anchor demand for commercial-grade reliability warranties among transportation hub operators.
Germany
Transportation authorities in Frankfurt and Munich tender managed service contracts with penalty clauses for availability shortfalls. The EU Green Deal Ecodesign mandates accelerate LED backlight efficiency improvements and recyclable panel architectures among installed base customers. Berlin and Hamburg concentrate healthcare wayfinding deployments in acute care facilities.
Japan
Telecommunications operators offer 5G network slicing with guaranteed bandwidth tiers that enable latency-sensitive interactive applications. METI standards shape domestic procurement specifications for public information displays. Tokyo and Osaka premium department stores adopt sub-2mm pixel pitch LED cabinets for seamless video wall installations.
South Korea
Display panel manufacturers and systems integrators cluster around Seoul, creating concentrated upstream capacity for TFT-LCD and OLED substrates. Domestic telecommunications infrastructure supports real-time content distribution for dense urban deployments. Busan and Incheon transportation authorities source from this integrated supply base.
India
Municipal digital kiosk tenders under the Ministry of Housing and Urban Affairs create localized deployment opportunities for systems integrators with domestic manufacturing partnerships. BIS certification requirements shape hardware import compliance for commercial display installations. Mumbai and Delhi anchor smart city infrastructure programs for public information displays.
Digital Signage Services Market Competitive Environment
South Korean producers anchor one tier through captive semiconductor and panel supply; North American specialists hold positions in proprietary software and managed service delivery. The vendor base separates into hardware-integrated platform providers, content management specialists, and analytics software developers. Consolidation pressure runs highest where recurring subscription revenue pools attract vertical integration moves. Strategic partnerships between display manufacturers and telecommunications operators reshape competitive positioning in 5G-enabled deployments.
Within the hardware-integrated tier, Samsung Electronics and LG Electronics exemplify South Korean conglomerate structures that bundle captive panel production with recurring service relationships. Stratacache occupies a position among North American specialists leveraging proprietary caching software to reduce bandwidth costs for high-density screen networks. These three anchors represent divergent strategic archetypes: captive supply chain control, software-defined service differentiation, and operational expenditure conversion through subscription models.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| NEC Display Solutions |
| Panasonic Corporation |
| Stratacache |
| BrightSign |
| Cisco Systems |
| Sony Corporation |
| Daktronics |
| Others |
Value Chain & Pricing Dynamics
Systems integration engineers cluster in South Korea and Taiwan, creating labor-cost differentials that separate premium managed-service contracts from economy hardware-only transactions. Content management subscription tiers widen as cloud platform specialization deepens in Seoul while Shenzhen assembly lines compress media player unit costs.
Pricing Analysis
Capacity additions in Shenzhen and Guangdong are reshaping price floors for entry-level media players and display hardware. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and uptime guarantee differentiation. Pricing pressure stems from South Korean panel oversupply cycles that compress LCD margins for indoor deployments. Mid-sized retail chains exhibit highest price sensitivity, while airport authorities with 24/7 uptime requirements absorb premium service tiers.
Supply Chain Analysis
Workforce availability constraints in Vietnamese assembly plants and Mexican integration facilities are tightening logistics coordination for North American-bound deployments. Upstream capacity concentrates in South Korea, China, and Japan for TFT-LCD and OLED substrates. Panel production draws from indium tin oxide, liquid crystal compounds, and driver ICs. Single-source vulnerability in semiconductor backplane supply creates allocation risk during cycle peaks. Distribution runs through systems integrators with regional service footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Signage Services Market functions as a stable compounder, with cloud subscription conversion driving predictable recurring revenue streams across retail and transportation verticals.
For Market Incumbents: Lock in captive semiconductor supply through backward integration into driver IC sourcing, insulating against allocation volatility from South Korean foundries. Deepen certification investment for FCC equipment authorization pre-approval to compress project timelines for US-bound deployments. Consolidate under single-vendor managed service contracts with penalty clauses for availability shortfalls, neutralizing specialized AV integrator fragmentation. For New Entrants and Emerging Players: Capture municipal digital kiosk tenders under India's Ministry of Housing and Urban Affairs by forming domestic manufacturing partnerships for BIS certification compliance. Target healthcare wayfinding in French and Canadian acute care facilities, where hospital networks prioritize patient flow optimization over capital expenditure minimization. Lead with edge-computing content caching to differentiate bandwidth efficiency against cloud-heavy incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among hardware-integrated platform providers with undermonetized software attach rates. Five-to-ten year viability favors vendors converting transactional display sales into recurring content management subscriptions. Monitor 5G network slicing deployment timelines in South Korea and Japan as inflection signal for latency-sensitive interactive application demand.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Service Contract Consolidation | Airport authorities in Germany and Japan demand five-year operational agreements with guaranteed uptime SLAs. |
| Edge Computing Architecture Deployment | Local media player processing enables responsive interactive experiences without persistent wide-area network dependence. |
| Proprietary Caching Software Development | Bandwidth cost reduction for high-density screen networks differentiates service providers in transportation hubs. |
| Domestic Manufacturing Partnership Formation | BIS certification compliance unlocks municipal tender participation under India's smart city infrastructure programs. |
| Computer Vision Analytics Integration | Dwell-time measurement capabilities transform passive displays into measurable audience engagement platforms for retail chains. |
Study Parameters
Coverage spans North America, Europe, Asia-Pacific, and India, with primary inputs from each regional cluster. The research combines structured interviews with systems integration executives, AV procurement officers at retail chains, transportation authority technology directors, and cloud platform engineers with secondary validation. Secondary sources include FCC equipment authorization databases, EU Ecodesign directive compliance filings, METI public information display specifications, and BIS certification records. Bottom-up deployment tracking and top-down service revenue estimation undergo cross-triangulation.
Granularity-level modeling extends to service type, deployment mode, end-user vertical, and display technology across the analysis window. Cloud-based versus on-premise deployment splits, LCD versus LED technology trajectories, and retail versus transportation hub concentration receive discrete treatment. CAGRs derive from segment-level growth rate synthesis anchored to disclosed contract values and installation volumes. Forecast inputs incorporate 5G network slicing availability timelines and EU AI Act compliance cost assumptions.
Panel allocation volatility, biometric privacy regulatory expansion, and cloud subscription churn rates are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding telecommunications infrastructure buildout and display technology substitution curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Asia-Pacific API Management Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Media Asset Management (MAM) Solutions Market
Digital Solutions
G2P Systems Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
Digital Commerce Software Market
Digital Solutions
Utility Cases Market
Digital Solutions
Global Data Catalog Market
Digital Solutions
Global Web Hosting Service Market
Digital Solutions
Data Classification Tool Market
Digital Solutions
Mobile Marketing Market
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
Italy Digital Twin Market