
 Switzerland ICT Market | 2026-2036
Switzerland ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland ICT Market Insights
Enterprise software distribution is fragmenting across hybrid cloud and on-premise deployment models in Switzerland. Swisscom anchors its position through nationwide fiber and 5G infrastructure control. Microsoft leverages its Azure stack to compete for public sector and healthcare digitalization contracts. IBM sustains research intensity through its Zurich laboratory, which specializes in quantum computing and cryptography applications.
Information and communications technology encompasses electronic systems, software architectures, and network infrastructure that process, store, and transmit data at speeds exceeding 100 Gbps in backbone deployments. Its primary purpose is to enable real-time decision-making, secure transactions, and automated operations across commercial and governmental organizations. Software captures dominant margin pools as recurring subscription models displace perpetual licensing. Cybersecurity experiences the fastest structural expansion as FINMA operational resilience requirements and rising ransomware exposure force financial institutions to harden attack surfaces. Cloud computing underpins this shift, with hybrid architectures now standard across Swiss enterprises managing sensitive client data.
Swissmedic coordinates with FINMA and the Federal Data Protection and Information Commissioner to enforce cross-sector data governance standards that elevate compliance costs for foreign vendors. The revised Federal Act on Data Protection mandates explicit consent mechanisms and breach notification timelines that reshape product design priorities for ICT providers operating in the Confederation. Stakeholders must weigh the trade-off between Zurich's talent density and Ticino's emerging cost advantages when situating delivery centers.
Market Dynamics
FINMA's operational resilience requirements are compressing procurement cycles across Swiss banking infrastructure, forcing institutions to consolidate vendor relationships and accelerate cloud migration timelines for core transaction systems.
Growth Catalysts
- Federal Act on Data Protection revision:Explicit consent mandates and breach notification timelines are creating replacement demand for legacy data management architectures across healthcare and financial services.
- Zurich financial technology corridor concentration:Talent density and proximity to FINMA headquarters are attracting foreign ICT vendors to establish Swiss delivery centers.
- Quantum cryptography research:Federal investment in quantum-safe infrastructure is seeding demand for next-generation encryption solutions among cantonal banks and government agencies.
Market Restraints
- Specialized cybersecurity talent scarcity:Zurich and Geneva face acute shortages of certified security architects, inflating implementation timelines for FINMA-mandated resilience programs.
- Cross-border data transfer friction:Swissmedic coordination with EU GDPR equivalence mechanisms creates compliance overhead for foreign cloud providers serving pharmaceutical clients.
- Legacy core banking system entrenchment:Proprietary mainframe architectures at major cantonal banks resist modular replacement, slowing hybrid cloud adoption.
Strategic Opportunities
- Ticino cost arbitrage:Lower operational expenses and Italian-speaking talent pools are attracting ICT delivery centers serving northern Italian and Swiss markets.
- Healthcare AI diagnostic convergence:Swissmedic's digital health pathway is opening procurement channels for machine learning platforms integrated with electronic patient records.
- Cantonal procurement centralization:Shared service agreements across Bern, Zurich, and Geneva are consolidating demand for standardized SaaS government platforms.
Industry Challenges
- Interoperability certification delays:EHR systems face prolonged Swissmedic validation timelines, compressing vendor revenue recognition cycles.
- Multi-cloud orchestration complexity:Financial institutions struggle to maintain consistent security postures across Azure, AWS, and on-premise VMware environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland ICT Market |
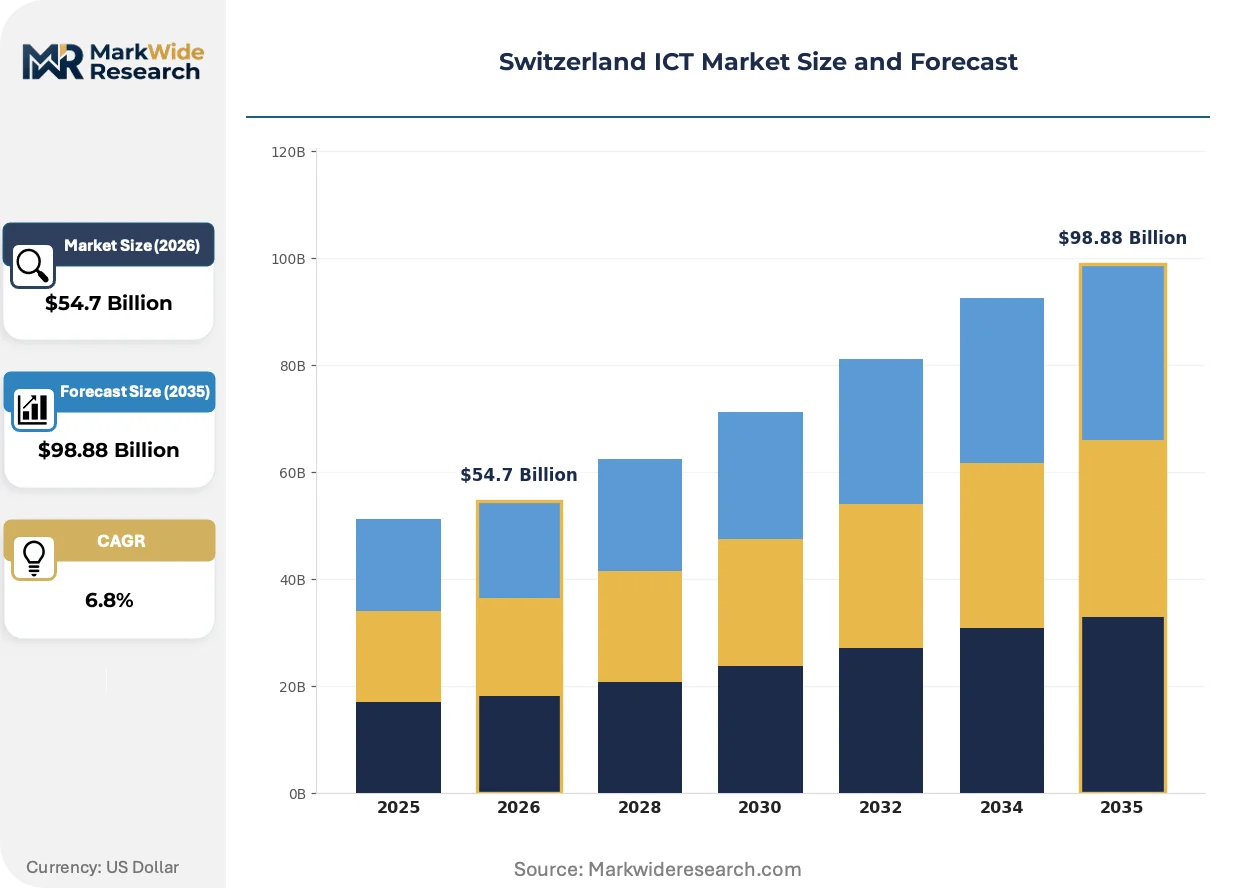
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $98.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Networking, Services Technology: Cloud Computing, Artificial Intelligence, Blockchain, Cybersecurity End User: Finance, Healthcare, Education, Manufacturing Application: Data Analytics, Communication, Project Management, E-Commerce |
| Companies Covered | Google, IBM, Microsoft, Swisscom, Logitech International, Temenos AG, Cisco Systems, Accenture, Deloitte AG (Switzerland), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland ICT Market Trends and Innovations
Swiss ICT procurement is pivoting from perpetual licensing toward consumption-based models, with cantonal governments and healthcare networks leading contract restructuring.
Confidential computing architectures are hybridizing data processing and encryption functions within hardware-isolated enclaves. Swiss banks are piloting these technologies for cross-institutional fraud detection without exposing raw transaction records. This convergence is compressing the traditional separation between security infrastructure and application layers.
The revised Federal Act on Data Protection mandates algorithmic transparency for automated decision systems. Financial institutions must now document AI model logic for credit scoring and insurance underwriting. Wealth management divisions are responding by establishing dedicated model governance committees and procuring explainability tooling.
Subscription fatigue among mid-market enterprises is fragmenting software procurement authority. Department heads now negotiate directly with vertical SaaS vendors, bypassing centralized IT procurement. This pattern is most visible in Geneva's private banking sector, where relationship managers independently adopt client-facing productivity tools.
Switzerland ICT Market Segmentation
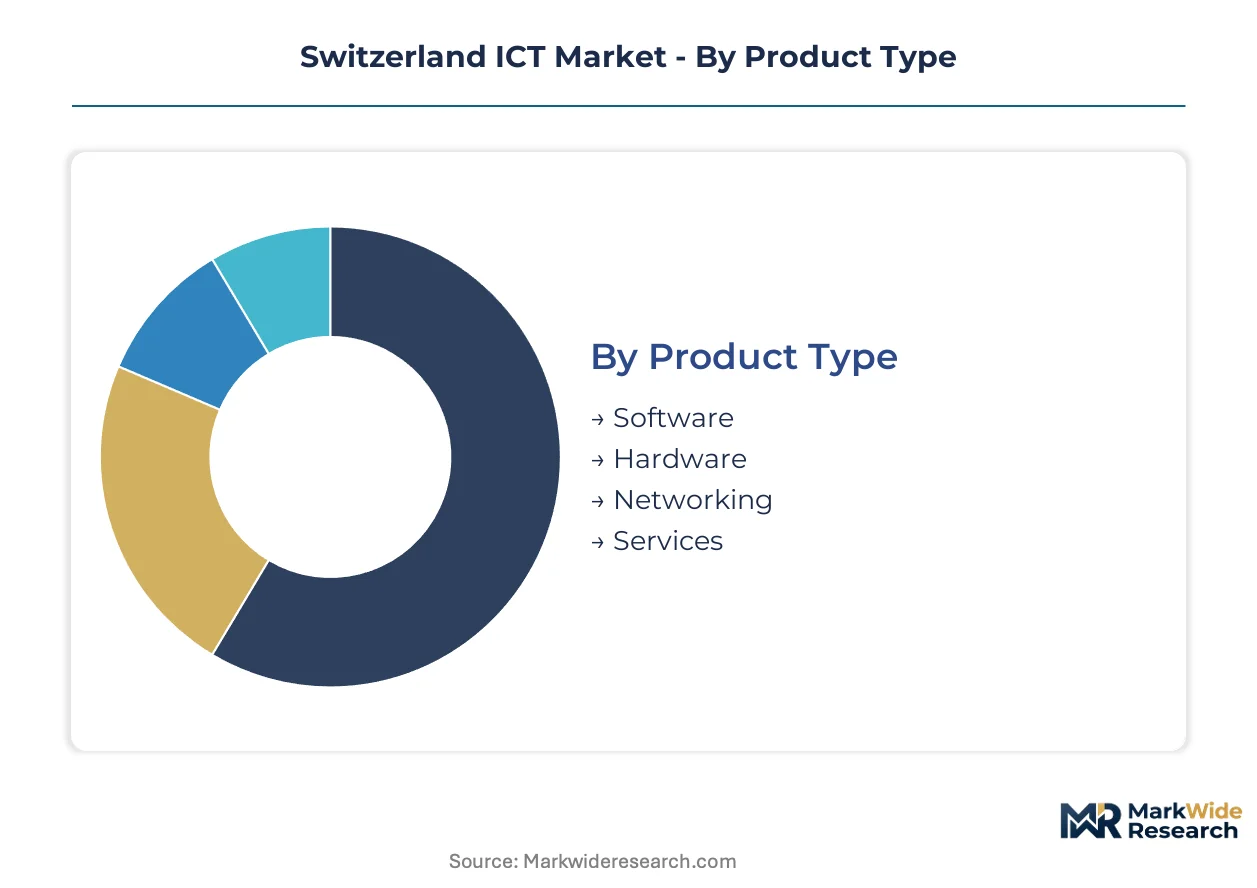
Swiss ICT procurement cycles vary dramatically across product categories, with infrastructure hardware turning over every 3-5 years while software subscriptions refresh annually. Understanding these velocity differences helps vendors align inventory and sales capacity with actual purchasing rhythms.
Product Type:
Hardware assets depreciate on the slowest cycle in Swiss enterprise accounts, while services contracts turn over fastest as FINMA compliance requirements shift quarterly.
- Software:Cloud-native architectures and SaaS delivery now dominate Swiss enterprise procurement, with subscription models displacing perpetual licenses across banking and healthcare. Zurich's financial technology corridor generates concentrated demand for regulatory compliance suites and risk analytics platforms driven by FINMA operational resilience mandates.
- Hardware:Servers, storage arrays, and endpoint devices constitute the physical infrastructure layer. Swisscom's nationwide fiber and 5G buildouts sustain demand for telecommunications hardware, though cantonal governments face budget constraints extending replacement cycles.
- Networking:Backbone routers and switching equipment processing 100+ Gbps traffic.
- Services:Systems integration, managed security, and consulting engagements. FINMA-mandated resilience programs compress procurement cycles for cybersecurity assessments and cloud migration advisory.
Hardware anchors the volume base while services gains share at the steepest rate.
Technology:
Cost tiers separate established infrastructure plays from emerging premium segments, with cloud computing commanding the lowest marginal cost per transaction and quantum-ready cryptography sitting at the premium extreme.
- Cloud Computing:Hybrid and multi-cloud architectures are now standard across Swiss enterprises managing sensitive client data under Federal Act on Data Protection constraints. Healthcare networks and cantonal governments lead contract restructuring toward consumption-based models.
- Cybersecurity:FINMA operational resilience requirements and rising ransomware exposure force financial institutions to harden attack surfaces. Zurich and Geneva face acute shortages of certified security architects, inflating implementation timelines.
- Artificial Intelligence:Machine learning platforms integrated with electronic patient records.
- Blockchain:Distributed ledger applications for trade finance and digital identity verification.
Cloud computing captures the dominant revenue pool while cybersecurity climbs the fastest.
End User:
Application maturity varies sharply across verticals, with finance running production-grade systems and education still piloting core infrastructure modernization.
- Finance:Swiss banks are expanding digital infrastructure investments while consolidating vendor relationships under FINMA pressure. Core transaction systems are accelerating cloud migration timelines, though proprietary mainframe architectures at major cantonal banks resist modular replacement.
- Healthcare:Swissmedic coordinates with FINMA and the Federal Data Protection and Information Commissioner to enforce cross-sector data governance standards. Electronic health records face prolonged validation timelines, compressing vendor revenue recognition cycles.
- Education:Universities and vocational institutions deploying learning management systems.
- Manufacturing:Industrial IoT and predictive maintenance platforms for precision engineering clusters.
Finance anchors the volume base while healthcare expands most quickly.
Application:
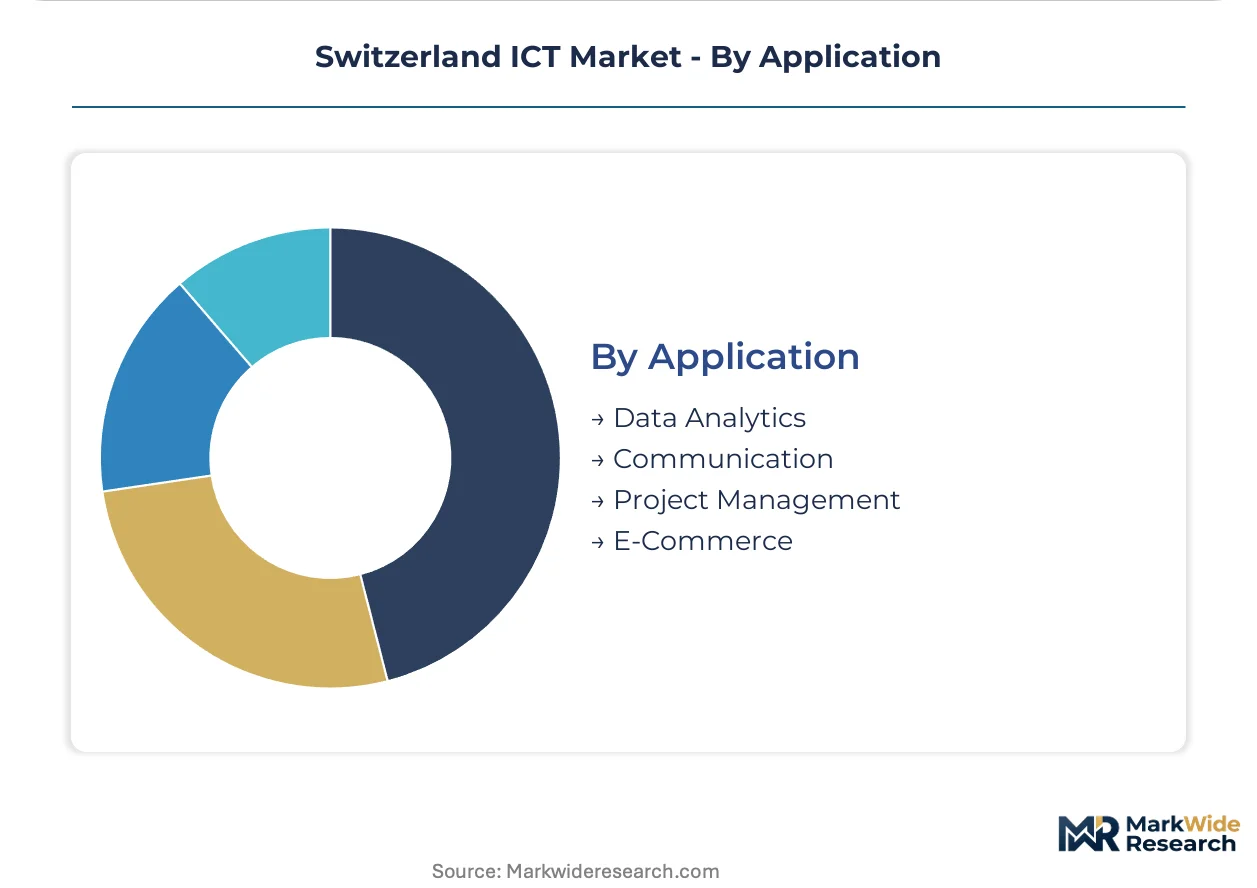
Customer type segmentation reveals divergent procurement authority patterns, with centralized IT controlling infrastructure while department heads independently adopt productivity tools.
- Data Analytics:Real-time decision-making platforms processing structured and unstructured datasets. The revised Federal Act on Data Protection mandates algorithmic transparency for automated decision systems, forcing financial institutions to document AI model logic.
- Communication:Unified messaging and collaboration infrastructure. Geneva's private banking sector shows fragmentation as relationship managers bypass centralized IT procurement.
- Project Management:Workflow orchestration tools for professional services and consulting.
- E-Commerce:Digital transaction platforms and customer experience infrastructure.
Communication anchors the volume base while data analytics gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gotthard Base Tunnel anchors Switzerland's digital infrastructure connectivity, linking northern European data centers with Mediterranean submarine cable landing points through low-latency fiber corridors.
Zurich
FINMA headquarters drives concentrated demand for regulatory compliance software and risk analytics platforms. The revised Federal Act on Data Protection mandates explicit consent mechanisms for financial data processing. The financial technology corridor attracts foreign ICT vendors establishing Swiss delivery centers to serve private banking clients.
Geneva
Wealth management divisions generate specialized demand for client-facing productivity tools and secure collaboration infrastructure. Swissmedic coordination with cross-sector data governance standards elevates compliance costs for foreign vendors serving pharmaceutical clients. The Lake Geneva region hosts concentrated procurement activity for healthcare AI diagnostic platforms.
Ticino
Lower operational expenses and Italian-speaking talent pools attract ICT delivery centers serving northern Italian markets. Cantonal incentives for technology sector investment accelerate facility buildouts. The Lugano-Locarno axis emerges as a cost-competitive alternative to Zurich for software development operations.
Basel
Pharmaceutical headquarters generate demand for machine learning platforms integrated with electronic patient records. Swissmedic validation timelines for EHR systems compress vendor revenue recognition cycles. The Rhine corridor concentration of life science R&D drives procurement of quantum-safe encryption for intellectual property protection.
Bern
Federal government digitalization programs sustain demand for standardized SaaS platforms across cantonal administrations. Shared service agreements consolidate procurement authority for cloud migration advisory services. The capital region anchors public sector ICT spending through centralized IT infrastructure modernization.
Switzerland ICT Market Competitive Landscape
On the supply side, the industry is consolidating around infrastructure control and cloud platform dominance, with national telecommunications operators and global hyperscalers occupying distinct competitive tiers. Swisscom anchors nationwide fiber and 5G infrastructure control. Microsoft and IBM compete for enterprise and public sector contracts through differentiated cloud and research capabilities. Strategic moves concentrate on vendor relationship consolidation under FINMA pressure and accelerated cloud migration timelines for core banking systems.
Among global technology platforms, Microsoft and Google exemplify the hyperscaler archetype competing for Swiss enterprise and healthcare digitalization contracts through Azure and cloud productivity stacks. IBM occupies a research-intensive position through its Zurich laboratory specialization in quantum computing and cryptography applications. Swisscom represents the national infrastructure anchor, controlling fiber and 5G buildouts that underpin enterprise connectivity pricing. Temenos AG sits within the financial software specialist tier serving core banking modernization requirements.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Swisscom |
| Logitech International |
| Temenos AG |
| Cisco Systems |
| Accenture |
| Deloitte AG (Switzerland) |
| Others |
Pricing and Supply Chain Analysis
Zurich's financial technology corridor concentrates cloud infrastructure capacity and specialized cybersecurity labor, translating supply scarcity into premium pricing tiers for FINMA-compliant solutions. The Federal Act on Data Protection revision amplifies this dynamic by mandating architectural replacements that vendors price at certification-grade premiums.
Pricing Analysis
Volume-discount tiering separates enterprise banking contracts above CHF 5 million annual spend from mid-market SaaS subscriptions and per-seat productivity licenses. Certification under FINMA operational resilience standards commands 15-25% price premiums over uncertified alternatives. Pricing pressure stems from subscription fatigue among Geneva's private banking relationship managers who independently procure shadow IT tools. Mid-market enterprises exhibit highest price sensitivity as procurement authority fragments to department heads bypassing centralized IT negotiations.
Supply Chain Analysis
Semiconductor feedstock for Swiss ICT hardware flows from Taiwan, South Korea, and the United States through Rotterdam and Hamburg logistics hubs. Specialized encryption chipsets and quantum-ready cryptographic processors draw from IBM's Zurich laboratory and limited European foundry capacity. Single-source vulnerability concentrates in advanced networking silicon where Swisscom's nationwide 5G buildout competes for constrained supply. Distribution runs through systems integrators like Accenture and Deloitte AG who bundle hardware procurement with FINMA-mandated compliance advisory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Switzerland ICT market represents a high-growth disruption as quantum cryptography research seeds replacement demand for encryption infrastructure across cantonal banking networks.
For Market Incumbents: Build switching-cost moats through deep integration with Swissmedic validation pathways for healthcare AI platforms. Consolidate vendor relationships under FINMA operational resilience mandates to capture multi-year managed security contracts. Defend against hyperscaler encroachment by embedding compliance automation into core banking modernization programs. For New Entrants and Emerging Players: Build out Ticino delivery centers to exploit 30-40% cost arbitrage against Zurich operations while serving northern Italian cross-border demand. Target healthcare AI diagnostic convergence where Swissmedic's digital health pathway opens procurement channels absent entrenched incumbents. Lead with explainability tooling for Federal Act on Data Protection algorithmic transparency mandates. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FINMA and Swissmedic coordination elevates compliance costs that favor scaled platforms with dedicated governance infrastructure. Acquisition targets include vertical SaaS specialists with Swissmedic pre-validation and quantum-safe cryptography laboratories with federal research partnerships. Watch for cantonal procurement centralization signals across Bern, Zurich, and Geneva shared service agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Safe Cryptography Partnership | Federal investment in quantum infrastructure seeds demand among cantonal banks for next-generation encryption. |
| Swissmedic Pre-Validation Acquisition | Machine learning platforms with cleared EHR integration compress revenue recognition cycles for healthcare AI vendors. |
| Ticino Delivery Center Buildout | Italian-speaking talent pools and cantonal incentives attract ICT operations serving cross-border northern Italian markets. |
| FINMA Compliance Automation Platform | Operational resilience mandates force financial institutions to consolidate vendor relationships around integrated tooling. |
| Cantonal Shared Service Agreement | Bern, Zurich, and Geneva procurement centralization consolidates demand for standardized SaaS government platforms. |
Research Methodology
A spread of perspectives from CTOs at cantonal banks, Swissmedic regulatory affairs leads, IT procurement officers at pharmaceutical headquarters, and integration specialists at systems integrators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC filings from listed ICT vendors, Swisscom infrastructure capex disclosures, and FINMA circulars on operational resilience. Customs data on networking hardware imports and cantonal government procurement databases anchored bottom-up sizing, cross-referenced against top-down ICT spend estimates from federal digitalization program budgets.
Demand-supply-balance framing modeled adoption curves across deployment model, organization size, vertical sector, and integration complexity dimensions throughout the forecast period. CAGRs derived from segment-level growth rate convergence analysis incorporating FINMA compliance cycle timing, Federal Act on Data Protection implementation phases, and Swissmedic validation pipeline throughput. Quantum cryptography research commercialization timelines and cantonal procurement centralization momentum served as scenario-weighting inputs.
Stress conditions across semiconductor supply availability, cybersecurity talent wage inflation, and cross-border data transfer equivalence negotiations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pace and vendor consolidation behavior. Cross-checking against hyperscaler capex allocation disclosures and Swisscom infrastructure investment reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Self Service Technology Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Global Connected Enterprise Market
Digital Solutions
Europe Digital Pen Market
Digital Solutions
Asia-Pacific Data Monetization Market
Digital Solutions
North America API Management Market
Digital Solutions
Demand Signal Repository Solutions Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
Global Commerce Cloud Solution Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Cultivation Management Software Market
Digital Solutions
Global Referral Management Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Smart Card Reader Market