
 Zygomycosis Treatments Market | 2026-2036
Zygomycosis Treatments Market Size, Share, and Industry Trends Forecast 2026-2036
Zygomycosis Treatments Market Analytics
India's active pharmaceutical ingredient manufacturing corridor for antifungal agents is narrowing the supply bottleneck for liposomal amphotericin B formulations. Pfizer Inc. leverages its hospital infusion infrastructure to sustain distribution reach across tertiary care centers. Merck & Co., Inc. anchors its position through deep R&D investment in novel azole compounds. Astellas Pharma Inc. differentiates via specialized infectious disease portfolios in European and Asian markets.
Zygomycosis treatments comprise therapeutic interventions targeting invasive fungal infections caused by Mucorales fungi, primarily utilizing polyene macrolides and triazole compounds that disrupt fungal cell membrane ergosterol synthesis. Liposomal amphotericin B remains the first-line intervention due to its improved renal safety profile versus conventional deoxycholate formulations, with posaconazole and isavuconazole serving as salvage or step-down oral therapy. The product type dimension shows amphotericin B formulations occupying the dominant revenue share while isavuconazole represents the fastest-expanding category driven by its FDA-approved status for mucormycosis. Delivery mode segmentation reveals intravenous administration leading hospital-based acute phase treatment, though oral posaconazole is gaining ground in maintenance therapy protocols that shift care toward specialty pharmacy channels.
The FDA's orphan drug program and EMA's priority medicines designation shape developer incentives by granting market exclusivity and accelerated review pathways for rare fungal indications. India's CDSCO and the WHO prequalification program influence manufacturing standards and export eligibility for generic liposomal formulations produced in Hyderabad and Ahmedabad clusters. Stakeholders must monitor how evolving antifungal stewardship guidelines from IDSA and ESCMID reshape prescribing patterns across hospital formularies.
Market Dynamics
Hospital antifungal stewardship programs are compressing empiric prescribing windows for Mucorales infections, forcing developers to demonstrate mortality benefit in smaller trial cohorts or risk formulary exclusion.
Growth Catalysts
- FDA orphan drug exclusivity:Seven-year market protection for mucormycosis indications accelerates venture funding for novel polyene derivatives. Developers file breakthrough therapy requests alongside orphan designations.
- Allogeneic stem cell transplant volume:Expanded cord blood banking in tertiary oncology centers creates sustained prophylactic demand for posaconazole suspension. Transplant units now represent the fastest-growing prescriber segment.
- Liposomal encapsulation advances:Nanoparticle engineering from Indian API clusters reduces nephrotoxicity thresholds, enabling extended infusion protocols in renal-compromised patients.
Market Restraints
- Phospholipid excipient concentration:Single-source supply of hydrogenated soy phosphatidylcholine from German chemical manufacturers creates formulation bottlenecks for liposomal amphotericin B.
- Diagnostic latency:Tissue biopsy turnaround times exceeding 72 hours delay targeted therapy initiation, sustaining empiric azole overuse and masking true treatment efficacy signals.
- Reimbursement compression:CMS inpatient prospective payment bundles limit per-dose cost recovery for novel isavuconazole loading regimens in US hospital systems.
Strategic Opportunities
- Brazilian transplant network expansion:ANVISA's accelerated review pathway for tropical fungal indications opens access to Latin America's largest immunocompromised patient pool.
- Point-of-care beta-D-glucan testing:Rapid biomarker detection at bedside enables pre-emptive therapy initiation before radiographic progression.
- Specialty pharmacy maintenance channels:Oral step-down protocols shift reimbursement risk from hospital DRGs to outpatient pharmacy benefit managers.
Industry Challenges
- Clinical trial enrollment velocity:Mucorales infection rarity requires transnational site activation across 15+ countries to achieve statistical powering.
- Pharmacovigilance signal management:QT prolongation reporting for triazole compounds triggers EMA referral procedures that delay label expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zygomycosis Treatments Market |
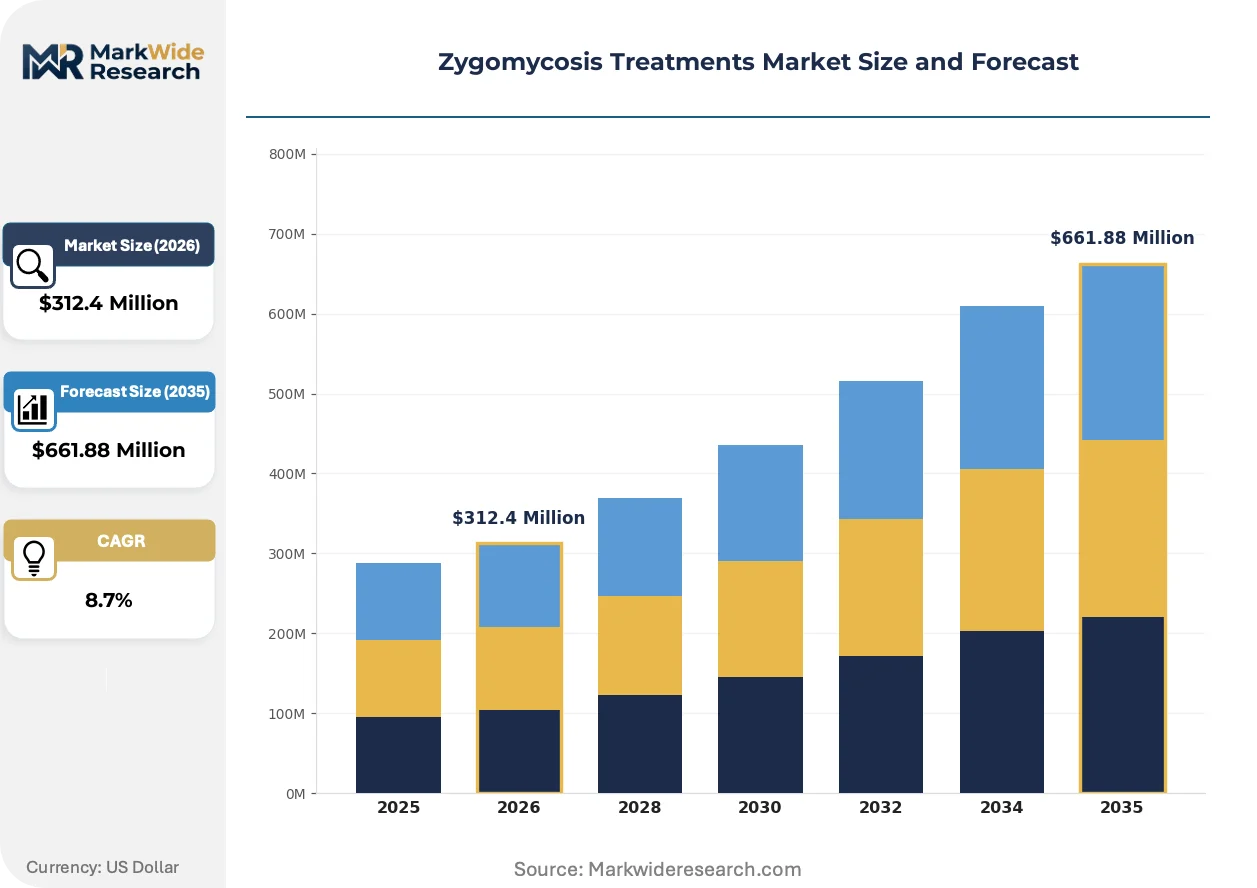
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amphotericin B, Posaconazole, Isavuconazole, Other Antifungals Delivery Mode: Intravenous, Oral, Topical, Inhalation End User: Hospitals, Clinics, Home Care, Specialty Pharmacy Treatment Stage: Acute Phase, Chronic Phase, Maintenance Therapy, Preventive Care |
| Companies Covered | Abbott Laboratories, Merck & Co., Inc., Pfizer Inc., Novartis AG, Astellas Pharma Inc., Gilead Sciences, GlaxoSmithKline plc, Bayer AG, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zygomycosis Treatments Market Evolving Landscape
Antifungal development pipelines are pivoting toward host-directed immunomodulation alongside direct-acting agents, reflecting recognition that Mucorales clearance requires functional neutrophil recovery.
Continuous manufacturing of liposomal formulations is rendering obsolete batch-processed amphotericin B production. Contract development organizations in Hyderabad and Ahmedabad are adopting single-use bioreactor trains that cut cycle times from 21 days to 72 hours. This shift compresses working capital requirements for generic manufacturers and enables just-in-time supply to hospital consignment stock.
EMA's priority medicines scheme now mandates pediatric investigation plans for all novel antifungal submissions, forcing developers to establish juvenile pharmacokinetic bridging studies early in Phase II. This regulatory pressure extends development timelines by 18-24 months but opens access to extended market exclusivity rewards. European infectious disease centers are responding by consolidating pediatric mucormycosis case registries to support extrapolation arguments.
Specialty pharmacy networks are disintermediating traditional hospital discharge channels for oral maintenance therapy. Patients completing IV induction now receive home-infusion nursing for posaconazole delayed-release tablets, with pharmacy benefit managers capturing margin previously retained by hospital outpatient departments. This channel shift is most visible in US Medicare Advantage plans, where 72-hour readmission penalties create institutional preference for off-site monitoring.
Zygomycosis Treatments Market Segmentation
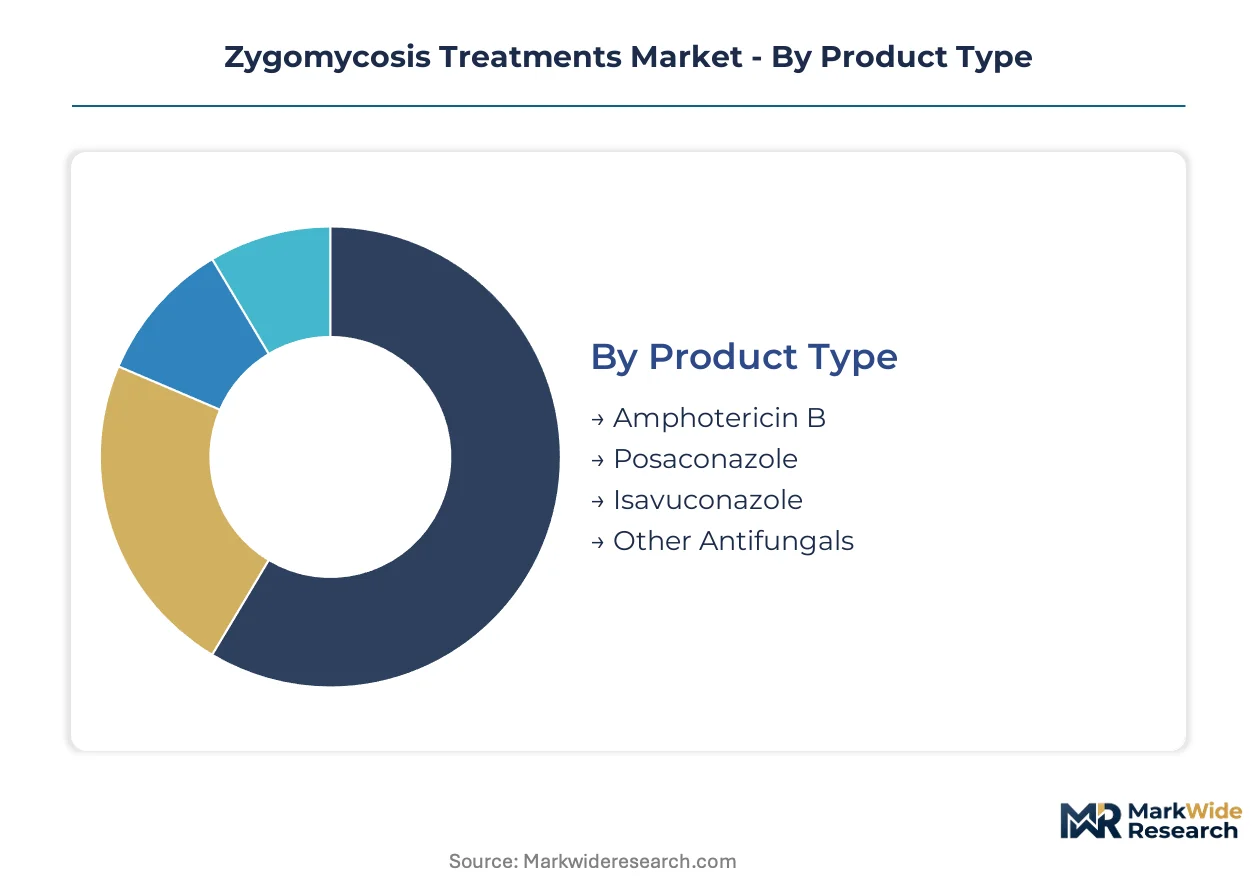
Zygomycosis treatment segmentation reveals how clinical protocols, reimbursement pathways, and manufacturing constraints intersect to shape commercial outcomes. Each dimension carries distinct margin profiles and service intensity requirements that determine go-to-market economics.
Product Type:
After-sales service intensity varies sharply across antifungal classes, with liposomal formulations demanding cold-chain logistics support and clinical pharmacist consultation that azole compounds rarely require.
- Amphotericin B:Liposomal and lipid complex formulations dominate hospital formularies through superior renal safety profiles versus deoxycholate versions. Demand concentrates in tertiary oncology centers across the United States, Germany, and Japan where stem cell transplant volumes sustain prophylactic protocols. Nephrotoxicity monitoring requirements create recurring service touchpoints.
- Isavuconazole:FDA-approved specifically for mucormycosis with streamlined loading regimens that reduce ICU length of stay. Specialty pharmacy networks in US Medicare Advantage plans are capturing step-down prescriptions previously retained by hospital outpatient departments. Formulary positioning depends on mortality data from smaller orphan-designated trials.
- Posaconazole:Delayed-release tablets and oral suspension serve maintenance therapy with established pharmacokinetic profiles in immunocompromised populations.
- Other Antifungals:Investigational polyene derivatives and combination therapies occupy pipeline stages with unproven commercial trajectories.
By volume, Amphotericin B formulations lead hospital procurement. By growth pace, Isavuconazole is expanding most quickly through label-specific indications and oral bioavailability advantages.
Delivery Mode:
Cost tier stratification separates acute-phase intravenous administration from outpatient oral maintenance, with reimbursement bundles favoring channel shifts that reduce institutional liability.
- Intravenous:Liposomal amphotericin B infusions require centralized pharmacy compounding and continuous cardiac monitoring in ICU settings. Tertiary care centers in Hyderabad, Ahmedabad, and Mumbai clusters supply generics to domestic and export markets under WHO prequalification standards. Per-dose costs face compression from CMS inpatient prospective payment bundles.
- Oral:Posaconazole and isavuconazole tablets enable discharge protocols that shift financial risk from hospital DRGs to pharmacy benefit managers. Specialty pharmacy networks in US Medicare Advantage plans now coordinate home-infusion nursing for delayed-release formulations, capturing margin previously retained by hospital outpatient departments.
- Topical:Limited applicability for cutaneous zygomycosis presentations in diabetic foot clinics.
- Inhalation:Experimental delivery for pulmonary mucormycosis with unvalidated pharmacokinetic profiles.
By volume, Intravenous administration dominates acute-phase hospital admissions. By growth pace, Oral delivery is gaining share fastest through step-down protocols and 72-hour readmission penalty avoidance.
End User:
Customer type determines procurement authority, with hospital pharmacy and therapeutics committees controlling formulary access while specialty pharmacies capture maintenance therapy margin.
- Hospitals:Antifungal stewardship programs compress empiric prescribing windows, forcing manufacturers to demonstrate mortality benefit or risk exclusion from restricted formularies. IDSA and ESCMID guideline adherence shapes purchasing decisions across tertiary infectious disease centers.
- Specialty Pharmacy:Oral azole dispensing integrates with home-infusion nursing and therapeutic drug monitoring services that reduce institutional readmission exposure.
- Clinics:Outpatient infectious disease practices manage stable patients with delayed-release posaconazole prescriptions.
- Home Care:Limited penetration for stable maintenance patients with established tolerance profiles.
By volume, Hospitals retain dominant procurement authority for acute-phase induction. By growth pace, Specialty Pharmacy channels are climbing the fastest through reimbursement-driven channel migration.
Treatment Stage:
Maturity differentiation separates established acute-phase protocols from emerging preventive care indications with unproven pharmacoeconomic returns.
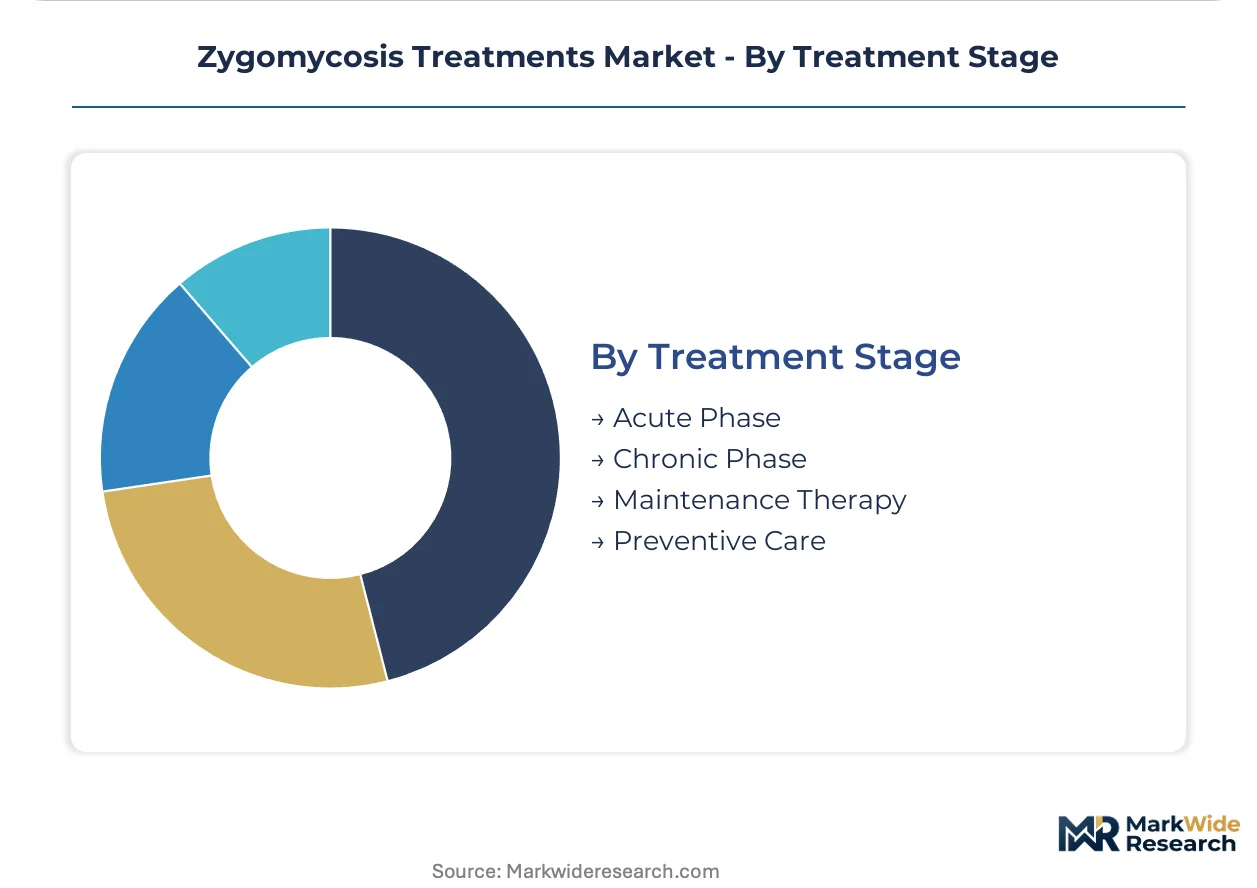
- Acute Phase:Liposomal amphotericin B induction requires ICU-level monitoring with mortality outcomes driving formulary positioning. Diagnostic latency exceeding 72 hours for tissue biopsy confirmation sustains empiric initiation protocols.
- Maintenance Therapy:Oral step-down regimens transition patients to outpatient settings with therapeutic drug monitoring requirements.
- Chronic Phase:Extended suppression for refractory infections with limited evidence-based duration guidelines.
- Preventive Care:Prophylactic posaconazole in allogeneic stem cell transplant units represents the fastest-expanding prescriber segment through expanded cord blood banking.
By volume, Acute Phase treatment leads hospital-based consumption. By growth pace, Preventive Care applications are gaining share fastest through transplant volume expansion and prophylactic protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing for liposomal antifungals clusters in Indian pharmaceutical corridors, while tertiary care demand concentrates in transplant-heavy markets across the United States, Germany, and Japan. Regulatory pathways in these jurisdictions determine developer incentives and patient access trajectories.
United States
Stem cell transplant volume at tertiary oncology centers sustains prophylactic posaconazole demand. FDA orphan drug exclusivity grants seven-year market protection for mucormycosis indications, accelerating venture funding for novel polyene derivatives. Hospital consignment stock in Boston, Houston, and Seattle anchors distribution networks for acute-phase liposomal formulations.
Germany
Specialized infectious disease centers in Berlin and Munich anchor European clinical trial networks for Mucorales therapeutics. EMA priority medicines designation mandates pediatric investigation plans, extending development timelines but opening extended exclusivity rewards. Hydrogenated soy phosphatidylcholine supply from domestic chemical manufacturers creates formulation dependencies for liposomal production.
India
Hyderabad and Ahmedabad clusters supply generic liposomal amphotericin B under WHO prequalification standards. CDSCO manufacturing standards influence export eligibility to African and Southeast Asian markets. Continuous manufacturing adoption in these cities cuts production cycle times from 21 days to 72 hours, compressing working capital for generic manufacturers.
Japan
PMDA review pathways for rare fungal indications align with transplant center expansion in Tokyo and Osaka. METI industrial policy supports domestic fermentation capacity for polyene macrolide production. Specialty pharmacy networks remain underdeveloped, sustaining hospital-based maintenance therapy retention.
Brazil
ANVISA accelerated review pathways for tropical fungal indications open access to Latin America's largest immunocompromised patient pool. Expanded cord blood banking in São Paulo and Rio de Janeiro transplant units creates prophylactic demand growth. Import dependency for finished liposomal formulations creates procurement vulnerability during supply disruptions.
Zygomycosis Treatments Market Competitive Landscape
Integrated pharmaceutical conglomerates and specialized infectious disease developers split the market between broad hospital formulary access and targeted rare-disease positioning. The competitive structure consolidates around manufacturing scale advantages in liposomal encapsulation and regulatory expertise in orphan drug navigation. Two dominant archetypes emerge: diversified giants leveraging hospital infusion infrastructure, and mid-cap specialists concentrating on azole compound innovation. Capacity expansion in Indian API clusters and strategic partnerships for diagnostic co-development represent the primary competitive moves reshaping positioning.
Within the diversified pharmaceutical tier, Pfizer Inc. and Merck & Co., Inc. exemplify scale-driven hospital channel dominance, while Astellas Pharma Inc. occupies a specialized infectious disease position in European and Asian markets. These three anchors represent contrasting strategic postures—broad infrastructure deployment versus targeted portfolio concentration—without asserting specific product claims or financial performance metrics.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Novartis AG |
| Astellas Pharma Inc. |
| Gilead Sciences |
| GlaxoSmithKline plc |
| Bayer AG |
| Sanofi |
| Others |
Value Network & Pricing Analysis
Undercapacity in German hydrogenated soy phosphatidylcholine production is tightening formulation economics for liposomal amphotericin B, forcing manufacturers to absorb input cost volatility while CMS inpatient bundles compress per-dose recovery. This utilization squeeze rewards backward-integrated API producers in Indian pharmaceutical corridors with captive phospholipid supply, while non-integrated formulators face margin compression from dual sourcing premiums.
Pricing Analysis
FDA orphan drug exclusivity dictates the pricing tier structure for mucormycosis indications, with seven-year market protection enabling premium positioning for novel polyene derivatives against generic liposomal formulations. Three-tier pricing separates originator liposomal products from WHO-prequalified Indian generics and conventional deoxycholate alternatives, with differentiation anchored in nephrotoxicity profiles and cold-chain reliability. Cost compression in the generic tier is intensifying because continuous manufacturing adoption in Hyderabad and Ahmedabad clusters collapses production cycle times. Hospital pharmacy and therapeutics committees exhibit highest price sensitivity in acute-phase procurement, while specialty pharmacy channels capturing step-down oral azole prescriptions show greater tolerance for therapeutic value premiums.
Supply Chain Analysis
Upstream hydrogenated soy phosphatidylcholine feedstock draws from German chemical manufacturers, Indian oleochemical processors, and Chinese soy processing clusters, creating geographic dispersion masking single-source concentration at the refined excipient tier. Liposomal amphotericin B production rests on phospholipid excipient supply, fermentation-derived amphotericin B API from Indian and Chinese sites, and single-use bioreactor equipment from US and European vendors. Single-source vulnerability in German phosphatidylcholine supply creates formulation bottlenecks during plant turnaround periods. Distribution runs through hospital consignment stock in tertiary oncology centers, with cold-chain logistics providers managing temperature-controlled last-mile delivery to ICU pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zygomycosis treatments constitute a defensive-moat market where FDA orphan drug exclusivity and EMA priority medicines designation create regulatory entrenchment that protects incumbent positions from rapid commoditization. Switching costs for hospital formularies—anchored in antifungal stewardship program validation and mortality outcome data—extend competitive persistence beyond patent expiry.
For Market Incumbents: Pre-empt generic erosion in liposomal formulations by securing captive hydrogenated soy phosphatidylcholine supply through backward integration into Indian oleochemical processing or long-term offtake agreements with German manufacturers. Accelerate pediatric investigation plan completion to capture EMA-mandated extended exclusivity rewards before competitor filings trigger referral procedures.
For New Entrants and Emerging Players: Pursue point-of-care diagnostic co-development partnerships that compress tissue biopsy turnaround times below 72 hours, enabling pre-emptive therapy initiation protocols that differentiate from empiric azole prescribing. Brazilian transplant network expansion offers the most penetrable geography, with ANVISA accelerated review pathways and underserved prophylactic demand in São Paulo cord blood banking units.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous manufacturing adoption in Indian API clusters, compressing working capital requirements and improving return thresholds for generic liposomal producers. Target acquisition candidates with WHO prequalification status and established hospital consignment stock relationships in US tertiary oncology centers. The signal to monitor is CMS inpatient prospective payment bundle adjustments for novel isavuconazole loading regimens, which would recalibrate acute-phase pricing power across the forecast horizon.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA seven-year exclusivity accelerates venture funding for novel polyene derivatives in mucormycosis. |
| Continuous Manufacturing Adoption | Single-use bioreactor deployment in Hyderabad cuts liposomal formulation cycle times from 21 days to 72 hours. |
| Diagnostic Co-Development Partnership | Bedside beta-D-glucan testing integration enables pre-emptive therapy before radiographic progression. |
| Pediatric Investigation Plan Completion | EMA-mandated juvenile pharmacokinetic studies unlock extended market exclusivity rewards. |
| Specialty Pharmacy Network Expansion | Home-infusion nursing for oral step-down protocols captures margin from hospital outpatient departments. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with infectious disease clinicians, hospital formulary directors, antifungal stewardship pharmacists, and specialty pharmacy operations managers; and secondary validation against FDA orphan drug filings, EMA priority medicines submissions, ClinicalTrials.gov mucormycosis trial registries, and WHO prequalification lists for liposomal amphotericin B. Bottom-up patient volume modeling across stem cell transplant units and top-down API production capacity analysis from Indian CDSCO manufacturing data were triangulated to constrain forecast variance.
Forecast inputs span treatment stage segmentation across acute-phase induction, maintenance therapy, and preventive care protocols; delivery mode differentiation between intravenous hospital administration and oral specialty pharmacy channels; and end-user procurement authority split between hospital pharmacy committees and outpatient benefit managers. CAGRs were derived from elasticity-adjusted price-volume relationships across the projection horizon, with transplant volume expansion and diagnostic latency reduction serving as primary demand-side drivers.
Sensitivities concentrate around CMS inpatient bundle adjustments, phospholipid excipient supply disruptions, and EMA referral procedure timelines for QT prolongation signals. Cross-checking against IDSA and ESCMID antifungal stewardship guideline revisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Monoclonal Antibody Therapy Market
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Hemorrhagic Stroke Treatment Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
Glaucoma Market
Specialty Medicine
CARD9 Deficiency Treatment Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market