
 Pseudomonas Aeruginosa Treatment Market | 2026-2036
Pseudomonas Aeruginosa Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pseudomonas Aeruginosa Treatment Market Analysis
Polymyxin B is rebalancing clinical prescribing economics as carbapenem resistance erodes last-line alternatives. Pfizer Inc. leverages its broad-spectrum antibiotic portfolio to sustain hospital formulary presence. Merck & Co., Inc. anchors its position through anti-infective R&D intensity across North American and European markets.
Pseudomonas aeruginosa treatment encompasses therapeutic interventions targeting a Gram-negative opportunistic pathogen characterized by intrinsic resistance to multiple antibiotic classes and biofilm-mediated persistence, requiring minimum inhibitory concentration-guided dosing and combination regimens to achieve clinical eradication. The primary purpose centers on reducing mortality in immunocompromised, mechanically ventilated, and cystic fibrosis patient populations where colonization progresses to life-threatening infection. Antibiotics occupy the dominant value share as resistance surveillance dictates cycling protocols across hospital networks. Inhalation delivery is accelerating fastest, propelled by nebulized formulations that achieve high epithelial lining fluid concentrations with reduced systemic toxicity. Cystic fibrosis application segments command premium pricing due to chronic suppressive therapy requirements and orphan drug economics.
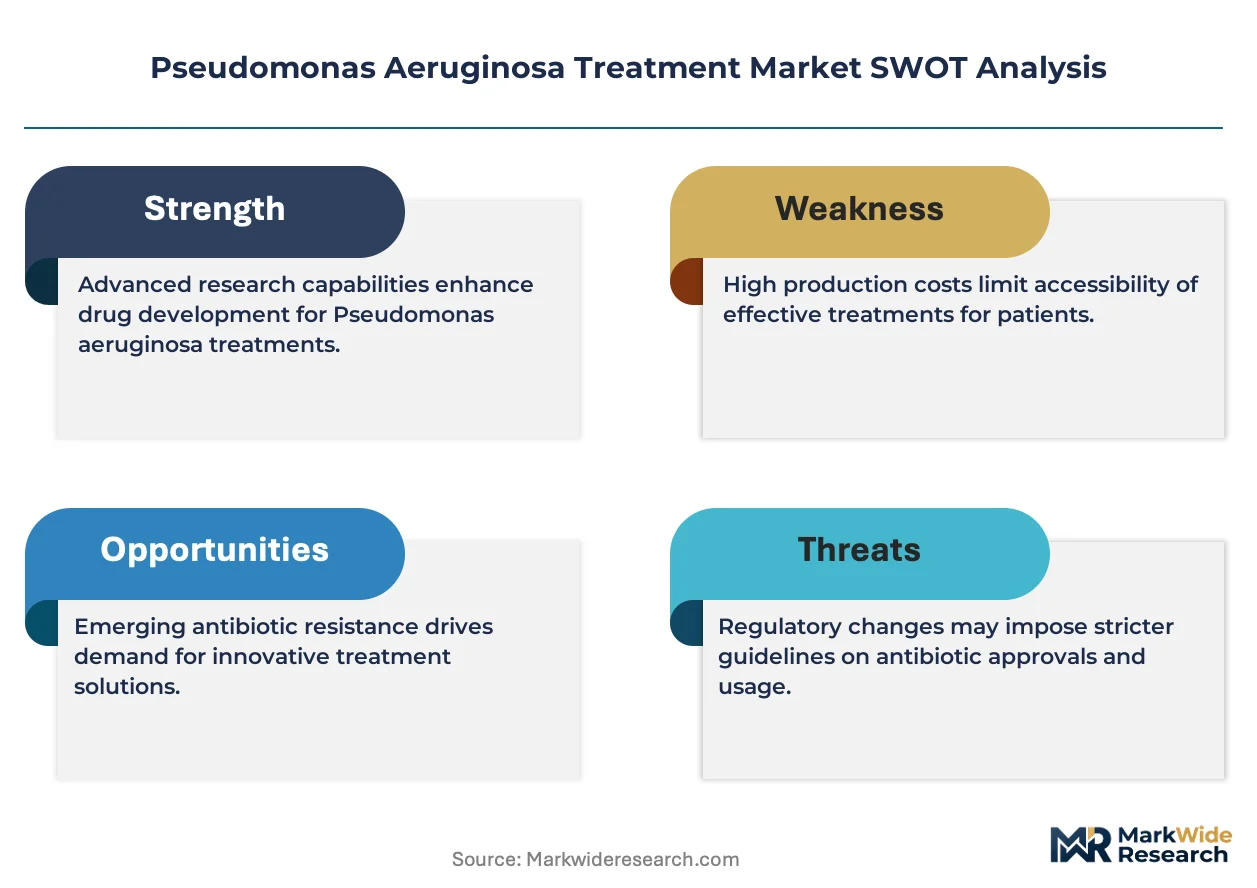
The FDA's QIDP and Fast Track pathways compress development timelines for novel anti-pseudomonal agents, while the EMA's Priority Medicines (PRIME) scheme shapes European access negotiations. EMA and FDA pharmacovigilance mandates on nephrotoxicity and neurotoxicity restrict polymyxin utilization, redirecting investment toward biofilm disruptors and immunomodulators with cleaner safety profiles. Stakeholders must monitor resistance surveillance data from the CDC and ECDC to anticipate formulary shifts before pipeline assets reach pivotal trials.
Market Dynamics
Multidrug-resistant Pseudomonas aeruginosa strains are compressing therapeutic half-lives for existing antibiotics, forcing hospital formulary committees into accelerated cycling protocols and combination therapy mandates.
Growth Catalysts
- QIDP Acceleration:The FDA's Qualified Infectious Disease Product designation compresses review timelines for novel anti-pseudomonal agents, incentivizing developers to prioritize Gram-negative programs.
- Cystic Fibrosis Center Expansion:Specialized treatment networks in the United States concentrate high-value chronic suppressive therapy demand, creating predictable revenue pools for inhaled formulations.
- Resistance Surveillance Integration:CDC and ECDC pathogen tracking systems enable real-time formulary adaptation, aligning hospital procurement with local resistance patterns.
Market Restraints
- Polymyxin Toxicity Constraints:FDA and EMA pharmacovigilance mandates on nephrotoxicity and neurotoxicity restrict last-line utilization, narrowing therapeutic options for carbapenem-resistant infections.
- API Supply Concentration:Active pharmaceutical ingredient production for polymyxins and aminoglycosides clusters in South Asian manufacturing hubs, exposing formulators to single-source disruption risk.
- Biofilm Penetration Limits:Current antibiotics fail to achieve minimum inhibitory concentrations within established Pseudomonas biofilms, necessitating prolonged combination regimens that elevate resistance selection pressure.
Strategic Opportunities
- Phage Therapy Convergence:Engineered bacteriophage cocktails combined with biofilm-disrupting enzymes offer mechanistic alternatives to conventional antibiotics in recalcitrant infections.
- Inhalation Delivery Expansion:Nebulized liposomal formulations achieve epithelial lining fluid concentrations unattainable through systemic administration, opening chronic suppressive therapy segments.
- EMA PRIME Pathway:European Priority Medicines designation accelerates access negotiations for anti-pseudomonal agents, creating parallel commercialization tracks alongside FDA pathways.
Industry Challenges
- Clinical Trial Recruitment Bottlenecks:Cystic fibrosis patient populations for pivotal efficacy studies are geographically dispersed across specialized centers, extending enrollment timelines.
- Resistance Surveillance Standardization:Discordant breakpoint definitions between EUCAST and CLSI create regulatory submission complexity for multinational developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pseudomonas Aeruginosa Treatment Market |
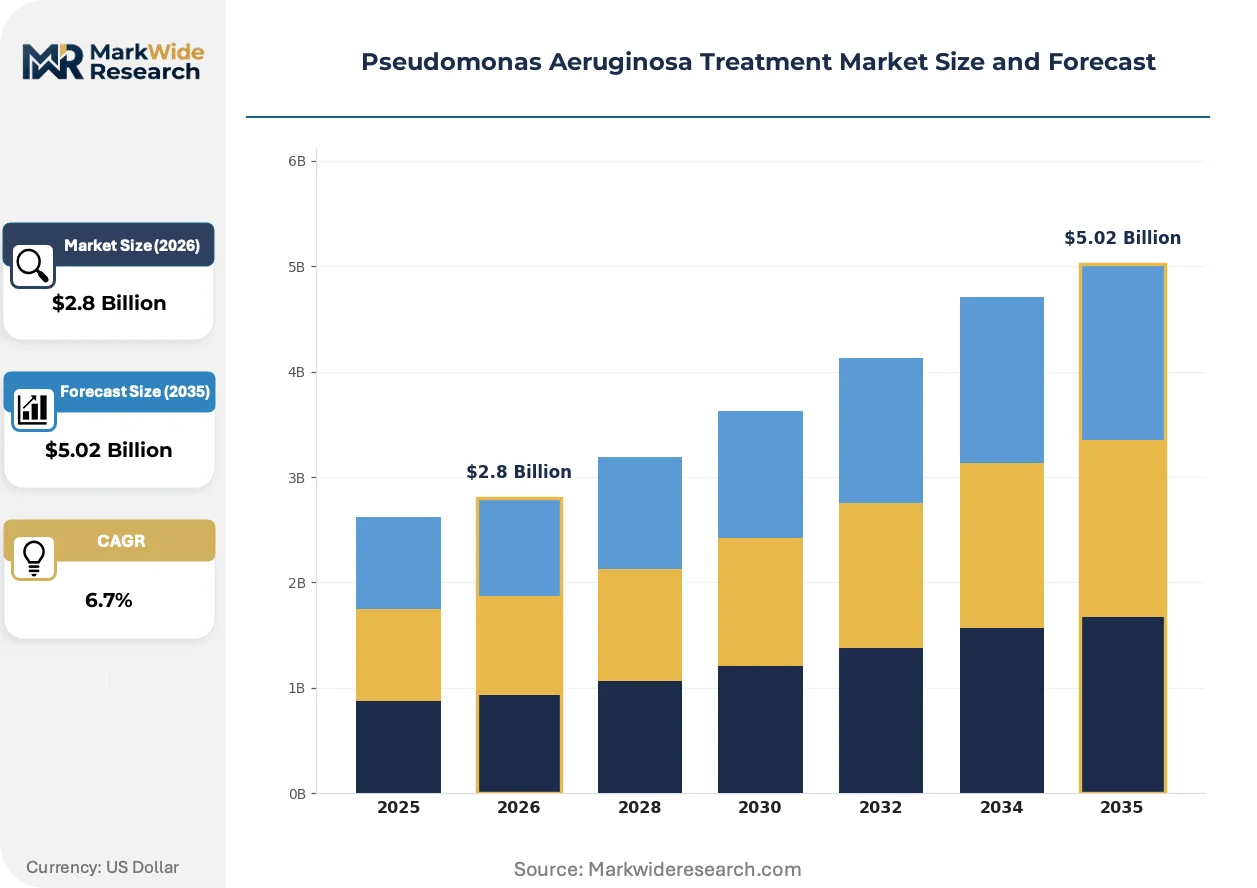
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiseptics, Biofilm Disruptors, Immunomodulators Delivery Mode: Inhalation, Injection, Topical, Oral End User: Hospitals, Homecare, Clinics, Research Laboratories Application: Cystic Fibrosis, Burn Wounds, Pneumonia, Urinary Tract Infection |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., AbbVie Inc., Johnson & Johnson, Novartis AG, Teva Pharmaceutical Industries Ltd, Roche, GlaxoSmithKline plc, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pseudomonas Aeruginosa Treatment Market Emerging Trajectories
Anti-pseudomonal development is pivoting from broad-spectrum chemical antibiotics toward precision biological modalities and localized delivery systems that circumvent systemic toxicity constraints.
Artificial intelligence-driven molecular design platforms are automating scaffold optimization for outer membrane-permeating compounds, compressing lead identification from months to weeks. Large pharmaceutical developers deploy these tools across early-stage Gram-negative programs. The structural consequence is a pipeline shift toward mechanistically novel chemical classes rather than incremental beta-lactam modifications.
EMA's Priority Medicines scheme now shapes European reimbursement negotiations for anti-infective assets, conditioning market access on resistance stewardship commitments. Hospital procurement consortia in Germany and France integrate PRIME-designated products into pre-negotiated framework contracts. Anti-pseudomonal developers respond by embedding real-world evidence generation into post-authorization study designs.
Consolidated cystic fibrosis center networks in the United States are centralizing formulary decision-making, compressing vendor selection cycles from annual to quarterly reviews. Regional treatment hubs in Boston, Denver, and Minneapolis now coordinate purchasing through shared therapeutic committees. This concentration elevates the importance of health economics and outcomes research in competitive positioning.
Pseudomonas Aeruginosa Treatment Market Segmentation
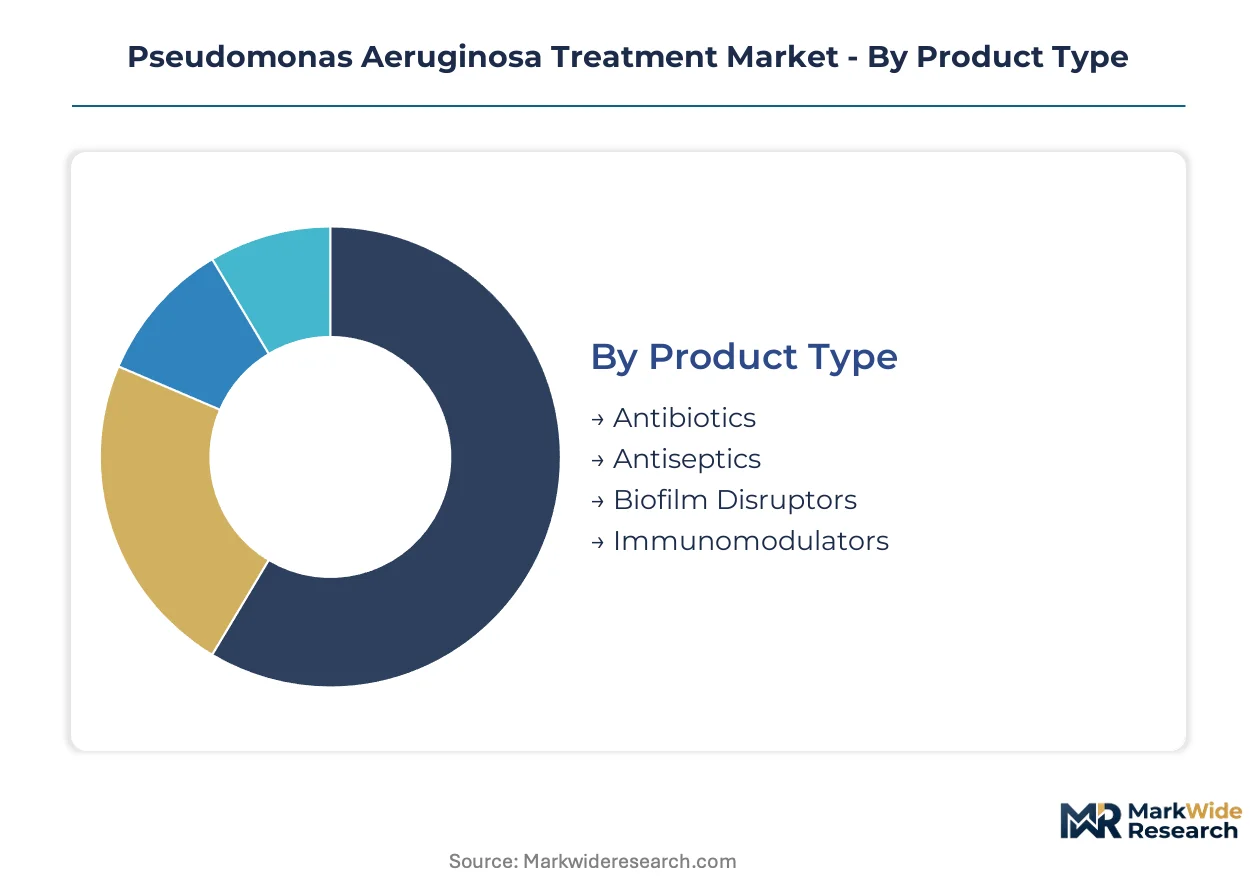
Segmentation in the Pseudomonas aeruginosa treatment market reveals how regulatory pathways and clinical requirements fragment commercial opportunity across product modalities and care settings. Each dimension carries distinct approval burdens, reimbursement codes, and prescriber access patterns that shape go-to-market economics.
Product Type:
FDA QIDP designation and EMA PRIME eligibility vary sharply across these categories, with novel chemical entities facing distinct toxicology requirements versus biological modalities.
- Antibiotics:Beta-lactams, aminoglycosides, polymyxins, and fluoroquinolones constitute the clinical backbone. Hospital formularies in the United States cycle these agents based on CDC resistance surveillance data from local isolates. Antibiotics sit at the top of the volume ranking, with biofilm disruptors climbing the fastest.
- Antiseptics:Topical chlorhexidine and silver-based preparations serve prophylactic roles in burn units and catheter insertion protocols. Demand concentrates in surgical suites where pre-operative decolonization protocols are mandated.
- Biofilm Disruptors:Enzymatic and small-molecule agents that degrade extracellular polymeric substances. EMA's PRIME scheme accelerates development timelines for these first-in-class modalities targeting recalcitrant colonization.
- Immunomodulators:Monoclonal antibodies and vaccine candidates targeting type III secretion systems or lipopolysaccharide. Development programs require extended immunogenicity assessment under FDA and EMA biological licensing pathways.
Antibiotics dominate current procurement volumes, though biofilm disruptors are gaining share fastest as resistance erodes conventional options.
Delivery Mode:
Cost tiering separates these modalities, with chronic inhaled therapy commanding premium pricing versus acute parenteral generics.
- Inhalation:Nebulized liposomal formulations and dry powder inhalers achieve high epithelial lining fluid concentrations. Cystic fibrosis centers in Denver and Minneapolis drive uptake of chronic suppressive regimens with quarterly formulary reviews.
- Injection:Intravenous and intramuscular routes dominate hospitalized pneumonia and sepsis cases. EUCAST breakpoint definitions for MIC interpretation create submission complexity for developers seeking transatlantic approval.
- Topical:Creams, gels, and wound irrigation solutions target localized burn wound infections. Burn units in Boston anchor demand for silver sulfadiazine and alternative antiseptic formulations.
- Oral:Fluoroquinolones and selected beta-lactams enable outpatient step-down therapy. Generic substitution pressure compresses margins for oral agents post-patent expiry.
Injection retains the highest patient-volume position, while inhalation delivery expands most quickly through orphan drug economics.
End User:
Customer type determines procurement sophistication, with consolidated hospital networks exercising price leverage versus fragmented homecare channels.
- Hospitals:Academic medical centers and community hospitals administer acute intravenous therapy through antimicrobial stewardship programs. German and French hospital procurement consortia negotiate framework contracts for anti-pseudomonal agents.
- Homecare:Infusion services and self-administered inhaled therapy for cystic fibrosis patients. Homecare settings face reimbursement coding complexity for nebulizer maintenance and nursing visits.
- Clinics:Outpatient infusion centers and specialized infectious disease practices. Clinics in the United States concentrate prescriber influence for novel agent adoption.
- Research Laboratories:Reference labs and contract research organizations support resistance surveillance and clinical trial endpoints. CDC's Antibiotic Resistance Laboratory Network supplies phenotypic and genotypic characterization data.
Hospitals represent the largest revenue pool, with homecare demonstrating the steepest expansion trajectory as chronic suppressive therapy shifts site of care.
Application:
Maturity varies across indications, with decades-old cystic fibrosis treatment paradigms contrasting emerging burn wound protocols.
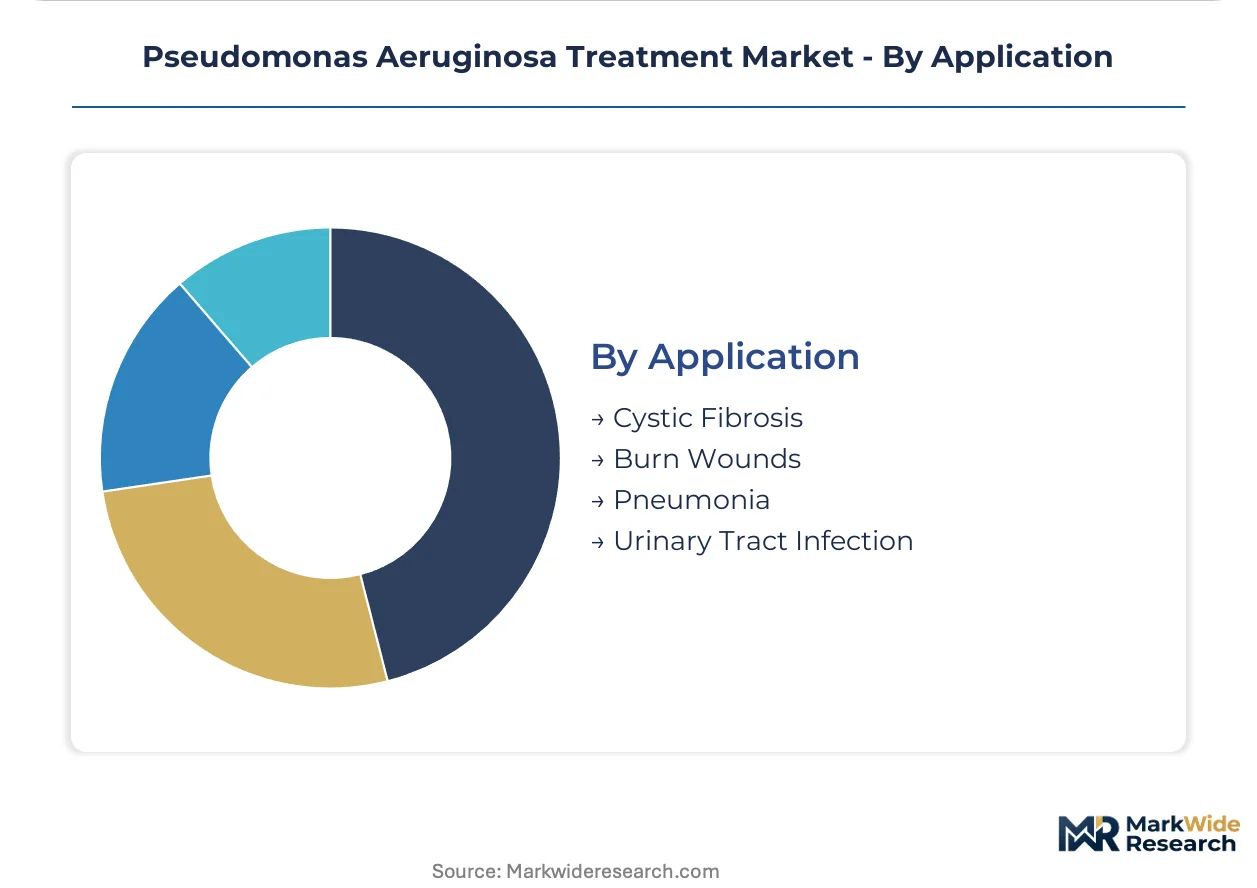
- Cystic Fibrosis:Chronic suppressive therapy against persistent Pseudomonas colonization. Specialized treatment networks in the United States concentrate high-value demand and enable predictable revenue forecasting for developers.
- Burn Wounds:Topical and systemic therapy for pseudomonal sepsis in thermal injury patients. Burn centers in Boston and Denver anchor procurement for advanced wound care products with biofilm-targeting claims.
- Pneumonia:Ventilator-associated and hospital-acquired pneumonias require rapid empiric coverage. ECDC surveillance data on ICU resistance patterns shapes European formulary decisions for carbapenem-sparing regimens.
- Urinary Tract Infection:Complicated UTIs in catheterized or immunocompromised patients. Resistance surveillance from outpatient urology practices lags behind ICU data, complicating empiric selection.
Cystic fibrosis leads by revenue concentration, with burn wound applications advancing most rapidly through advanced dressing integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cystic fibrosis treatment centers in the United States concentrate the highest-value demand for chronic suppressive therapy against Pseudomonas aeruginosa colonization. Hospital procurement networks in Germany and France negotiate framework contracts for anti-pseudomonal agents through consolidated antimicrobial stewardship programs. Resistance surveillance infrastructure varies sharply across geographies, shaping local formulary adaptation and developer market access strategies.
United States
Cystic fibrosis center networks in Denver, Minneapolis, and Boston drive premium uptake of inhaled formulations through quarterly formulary reviews. The FDA's QIDP designation compresses development timelines for novel Gram-negative programs targeting multidrug-resistant strains. Regional treatment hubs coordinate purchasing through shared therapeutic committees, elevating health economics evidence requirements for competitive positioning.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia integrate EMA PRIME-designated products into pre-negotiated framework contracts for anti-infective assets. The country's national pharmaceutical regulator mandates resistance stewardship commitments as conditions for reimbursement eligibility. Academic medical centers in Berlin and Heidelberg anchor clinical trial recruitment for pivotal efficacy studies in ventilator-associated pneumonia.
France
Burn centers in Paris and Lyon anchor demand for topical antiseptic formulations with biofilm-targeting claims in thermal injury protocols. ANSM pharmacovigilance mandates on nephrotoxicity restrict polymyxin utilization in carbapenem-resistant infections, redirecting investment toward alternative modalities. Regional hospital networks in Provence-Alpes-Côte d'Azur pilot real-time resistance surveillance integration into empiric prescribing decisions.
United Kingdom
Specialized infectious disease clinics in London and Manchester concentrate prescriber influence for novel agent adoption in complicated urinary tract infections. NICE technology appraisals condition market access on resistance stewardship commitments and real-world evidence generation. Research laboratories in the Southeast supply phenotypic characterization data to the CDC's Antibiotic Resistance Laboratory Network surveillance infrastructure.
Japan
PMDA accelerated review pathways for anti-pseudomonal agents align with domestic pharmaceutical industry R&D priorities in Gram-negative programs. Academic medical centers in Tokyo and Osaka lead enrollment for combination therapy trials targeting biofilm-mediated persistence. The country's national health insurance system reimburses inhaled chronic suppressive therapy for cystic fibrosis patients through designated rare disease protocols.
Pseudomonas Aeruginosa Treatment Market Vendor Landscape
Global majors compete with regional champions across regulatory pathway navigation and specialized therapeutic segment focus. The vendor base structures around three tiers: diversified pharmaceutical conglomerates with broad-spectrum antibiotic portfolios, mid-cap specialists concentrating on orphan disease indications, and emerging biotechnology developers pursuing mechanistically novel modalities. Strategic archetypes include hospital formulary incumbents defending position through resistance surveillance integration, and pipeline-stage developers leveraging FDA QIDP and EMA PRIME designations to compress commercialization timelines. Dominant competitive moves encompass portfolio diversification into inhalation delivery systems and geographic expansion through centralized cystic fibrosis center networks.
Within the diversified pharmaceutical tier, Pfizer Inc. and Merck & Co., Inc. exemplify hospital formulary incumbents with sustained antimicrobial stewardship program presence. Novartis AG occupies a position representing mid-cap specialization in rare disease therapeutic development. These three companies anchor the competitive structure through contrasting strategic postures: broad-spectrum portfolio breadth versus targeted indication focus versus biological modality investment.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| AbbVie Inc. |
| Johnson & Johnson |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| Roche |
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Others |
Supply Flow & Price Mechanics
Captive API manufacturing for polymyxins and aminoglycosides anchors both supply security and pricing leverage for integrated formulators serving hospital networks. South Asian production clusters for active pharmaceutical ingredients concentrate cost structures, while FDA and EMA pharmacovigilance mandates on nephrotoxicity narrow the therapeutic window and elevate quality-tier differentiation.
Pricing Analysis
Input-cost pass-through from concentrated API manufacturing in India and China intensifies margin pressure on generic injectable antibiotics. Three-tier pricing structure across premium liposomal formulations, standard parenteral generics, and economy oral step-down therapy segments the market by delivery sophistication. Price differentiation hinges on FDA QIDP designation status and biofilm penetration claims. Cost compression in standard injectables runs through formulary cycling mandates, while cystic fibrosis centers demonstrate lowest price sensitivity due to orphan drug reimbursement protocols.
Supply Chain Analysis
Certification gating through FDA Current Good Manufacturing Practice and EMA Good Manufacturing Practice standards restricts qualified API suppliers to a narrow tier of South Asian and European facilities. Active pharmaceutical ingredient production draws from manufacturing hubs in India, China, and Italy, with fermentation-derived polymyxins resting on agricultural commodity feedstock inputs. Single-source vulnerability concentrates in endotoxin-controlled finishing operations for parenteral formulations. Distribution runs through hospital procurement consortia in Germany and France and specialized cystic fibrosis center networks in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where chronic suppressive therapy demand in cystic fibrosis shifts procurement toward premium inhaled formulations with demonstrated biofilm penetration. Hospital formulary committees now weight resistance stewardship commitments above unit cost in vendor selection.
For Market Incumbents: Cement formulary position through integration into CDC and ECDC resistance surveillance data feeds, enabling real-time cycling protocol alignment. Prioritize captive API supply for polymyxin-class agents to mitigate South Asian single-source disruption exposure. Defensive consolidation around nebulized liposomal delivery capabilities counters emerging phage therapy developers targeting recalcitrant colonization segments. For New Entrants and Emerging Players: The premium-to-economy price-point gap in chronic suppressive therapy opens white-space targeting for biofilm disruptor adjuncts positioned between generic inhaled antibiotics and orphan-priced biological modalities. Burn wound applications in Boston and Denver treatment hubs represent the most penetrable segment for topical antiseptic formulations with biofilm-targeting claims. A reimbursement-first go-to-market angle leveraging EMA PRIME designation accelerates European hospital procurement consortia access negotiations. For Investors and Strategic Acquirers: Consolidation pressure builds where pipeline-stage developers hold FDA QIDP-designated Gram-negative programs but lack commercial infrastructure for cystic fibrosis center network penetration. Acquisition targets with complementary modality portfolios—pairing conventional antibiotics with biofilm-disrupting enzymes—offer the strongest five-to-ten year viability framing against resistance erosion. The signal to watch is EUCAST-CLSI breakpoint harmonization progress, which would streamline multinational regulatory submissions and unlock geographic expansion capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Enrollment in cystic fibrosis centers in Denver and Minneapolis accelerates pivotal efficacy readouts for inhaled formulations. |
| Regulatory Approval Pathway | FDA QIDP designation compresses review timelines and extends market exclusivity for novel anti-pseudomonal agents. |
| Manufacturing Scale-Up | Liposomal encapsulation capacity expansion addresses supply constraints for nebulized chronic suppressive therapy. |
| Pipeline Diversification | Phage therapy and immunomodulator programs hedge against carbapenem resistance erosion of chemical antibiotic utility. |
| Hospital System Partnership | Framework contracts with German and French procurement consortia secure multi-year revenue visibility for approved agents. |
Methodological Framework
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases; and customs trade data on API import flows — were reconciled through bottom-up patient-volume modeling and top-down pharmaceutical market sizing. Triangulation across these sources addressed data gaps in resistance surveillance reporting and proprietary hospital contracting terms.
Cross-referencing historical approval timelines against expert panel input on development-stage asset probability-of-success shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed treatment line, delivery mode, patient population, and regional regulatory cluster. CAGRs were derived from epidemiological trend extrapolation, pricing trajectory assumptions, and penetration curve analysis for novel modalities. Forecast inputs included CDC Antibiotic Resistance Laboratory Network surveillance trends and cystic fibrosis center expansion pipeline data.
Caveats apply where EUCAST-CLSI breakpoint harmonization delays or polymyxin API supply disruptions could materially shift the outlook. Forecasts reflect assumptions on resistance stewardship program persistence and orphan drug reimbursement stability. A model refresh is warranted upon material change in carbapenem resistance prevalence rates or FDA pharmacovigilance mandate scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Animal Hormone Therapy Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Bulimia Nervosa Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Anal Cancer Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Generalized Myasthenia Gravis (GMG) Management Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Epistaxis Market