
 Used Semi Truck Market | 2026-2036
Used Semi Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Used Semi Truck Market Analytics
Multi-source procurement from auction houses and certified pre-owned programs is repositioning how fleet managers acquire sleeper cab and day cab inventory. PACCAR Inc leverages its dealer network to sustain certified resale values across Kenworth and Peterbilt nameplates. Volvo Trucks competes through powertrain inspection protocols that extend warranty coverage on diesel and natural gas units. Ryder System Inc controls lease return volume, anchoring supply flows into secondary channels for logistics providers and construction companies.
A used semi truck denotes a previously operated Class 8 commercial vehicle with gross vehicle weight ratings exceeding 33,000 pounds, typically retaining engine displacement above 12 liters and sleeper berth configurations for long-haul duty cycles. These assets serve freight carriers and independent operators seeking lower capital outlay than new equipment while maintaining highway freight capacity. Sleeper cab inventory commands structural premiums due to over-the-road utilization rates, while electric and hybrid fuel types represent the fastest-appreciating segment as fleet sustainability targets harden. Day cab units occupy stable demand pools from regional construction companies and urban logistics providers with return-to-base routing.
EPA Phase 3 standards and NHTSA fuel efficiency rules shape engine rebuild eligibility and resale certification requirements for diesel-powered units entering secondary markets. The Department of Transportation's electronic logging device mandate and FMCSA hours-of-service enforcement alter utilization economics, pushing freight carriers toward newer used models with integrated telematics. Stakeholders must monitor how CARB zero-emission vehicle mandates in California and cascading state adoptions reshape residual value curves for internal combustion assets across interstate sales channels.
Market Dynamics
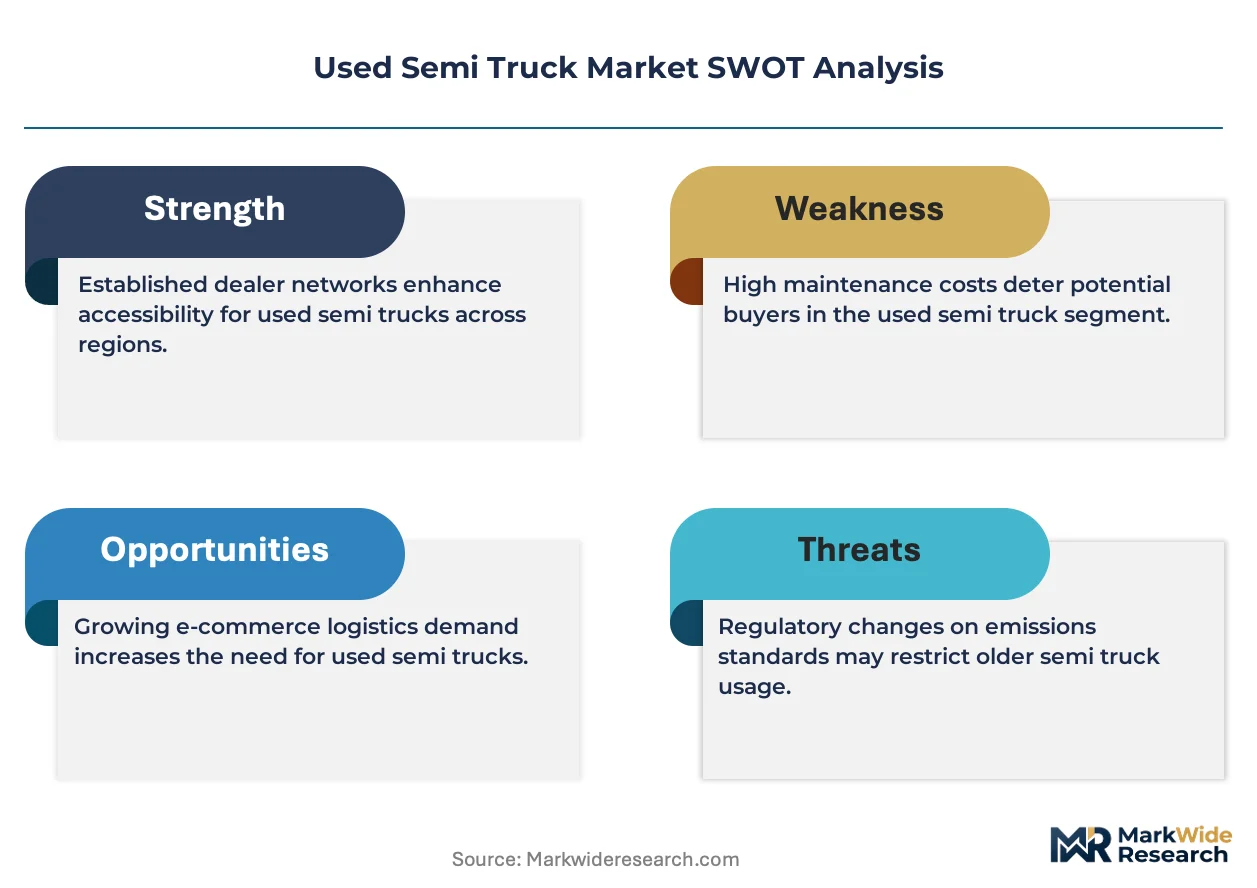
EPA Phase 3 greenhouse gas standards are compressing resale windows for pre-2021 diesel tractors, forcing freight carriers to accelerate fleet turnover and redirect procurement toward certified pre-owned channels with verified emissions compliance documentation.
Growth Catalysts
- Owner-operator expansion:Independent drivers across the Texas-Oklahoma corridor seek sleeper cab inventory with integrated telematics to meet FMCSA hours-of-service enforcement without new equipment premiums.
- CARB zero-emission mandates:California's Advanced Clean Trucks regulation cascades into neighboring state adoptions, creating transferable compliance value for low-mileage diesel units sold across state lines.
- Lease return velocity:Fleet management companies are shortening replacement cycles, flooding secondary channels with three- to four-year-old Class 8 tractors carrying residual manufacturer warranties.
Market Restraints
- Engine rebuild cost inflation:EPA-certified remanufacturing for 12-liter and 15-liter diesel blocks now consumes 35-45% of residual asset value, eroding total cost of ownership calculations for buyers.
- Parts supply concentration:Aftermarket component distribution for emission control systems clusters around Detroit and Memphis distribution hubs, extending downtime risk for operators outside these radii.
- Telematics interoperability gaps:Proprietary data protocols from original equipment manufacturers prevent seamless integration with third-party fleet management platforms, limiting resale appeal.
Strategic Opportunities
- Natural gas powertrain arbitrage:Compressed natural gas tractors with verified tank integrity command structural premiums in California and Texas corridors where fuel infrastructure density supports operational economics.
- Certified pre-owned program expansion:Dealer networks can capture margin expansion by extending powertrain inspection protocols and warranty coverage to day cab inventory serving construction verticals.
- Electric tractor pre-positioning:Early secondary market development for battery-electric Class 8 units offers first-mover positioning ahead of mainstream fleet electrification mandates.
Industry Challenges
- Technician certification bottlenecks:EPA emission system diagnostics and high-voltage electric powertrain servicing require specialized training that community college programs and manufacturer academies have not scaled to meet demand.
- Title washing and odometer fraud:Interstate sales documentation inconsistencies enable asset misrepresentation, eroding buyer confidence and extending due diligence timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Semi Truck Market |
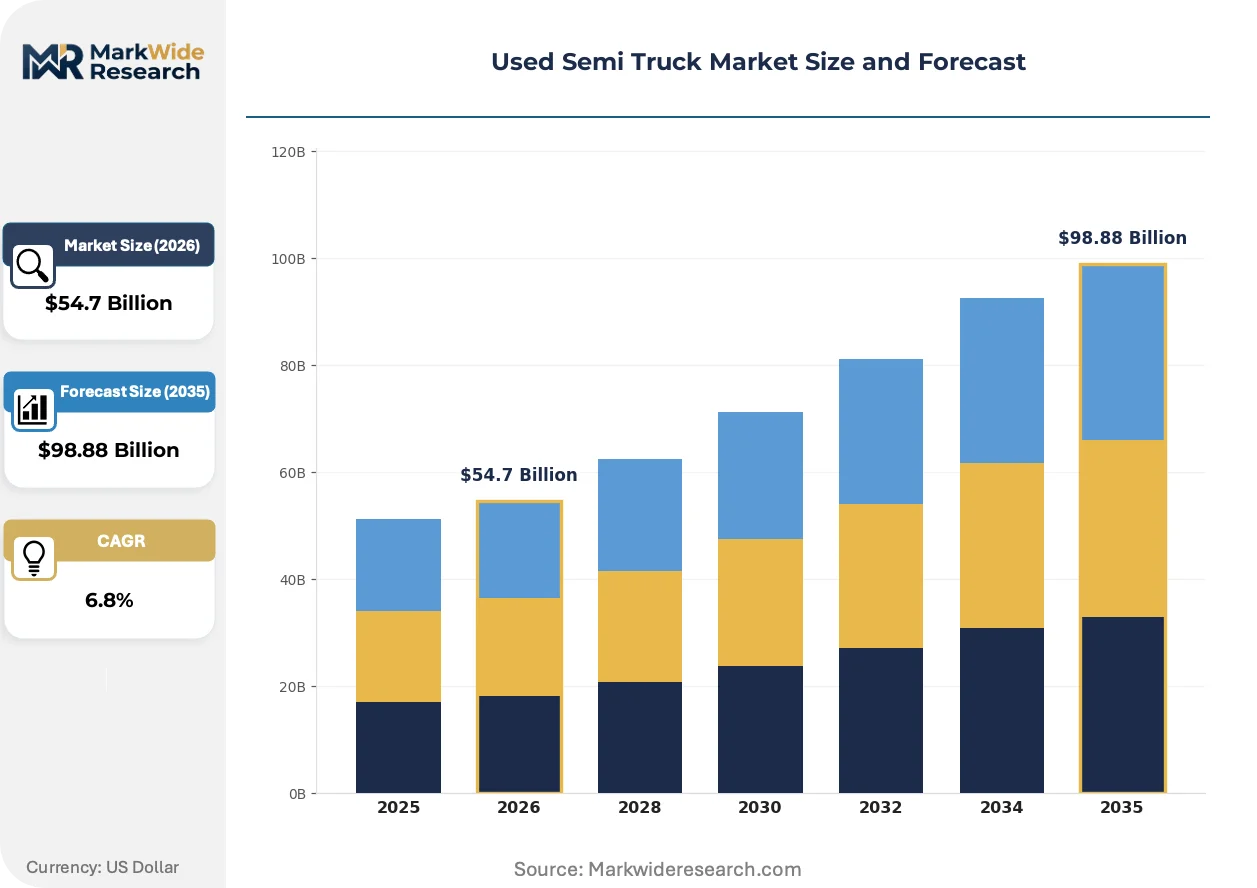
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $98.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Day Cab, Sleeper Cab, Dump Truck, Refrigerated Truck Fuel Type: Diesel, Natural Gas, Electric, Hybrid End User: Logistics Providers, Freight Carriers, Construction Companies, Independent Owner-Operators Sales Channel: Online Auctions, Dealerships, Private Sales, Lease Returns |
| Companies Covered | PACCAR Inc, Volvo Trucks, Daimler Trucks, Ryder System Inc, Penske Used Trucks, Navistar International, Peterbilt, Kenworth, Gordon Truck Centers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Semi Truck Market Evolving Landscape
Digital auction platforms and predictive analytics are compressing price discovery cycles and rewiring how fleet managers source sleeper cab and day cab inventory across fragmented secondary channels.
Telematics data monetization is consolidating residual value assessment methodologies. Fleet management platforms now bundle engine performance histories with auction listings, enabling buyers to price assets based on actual duty cycle severity rather than mileage alone. Large logistics providers with captive maintenance data are licensing these records to certified pre-owned programs, compressing information asymmetry between sellers and buyers.
EPA Phase 3 standards and NHTSA fuel efficiency rules are tightening engine rebuild eligibility criteria. Diesel blocks manufactured before 2021 face restricted certification pathways in states adopting California Air Resources Board thresholds, pushing secondary market flows toward jurisdictions with less stringent enforcement. Interstate carriers operating across regulatory boundaries must maintain dual compliance documentation, increasing administrative overhead and insurance verification complexity.
Procurement through subscription-based fleet access models is displacing traditional ownership structures. Mid-size logistics providers in the Southeast and Midwest are piloting monthly per-mile contracts that bundle maintenance, compliance monitoring, and replacement guarantees. These arrangements shift residual risk to fleet management companies while giving operators flexibility to scale capacity without capital deployment.
Used Semi Truck Market Segmentation
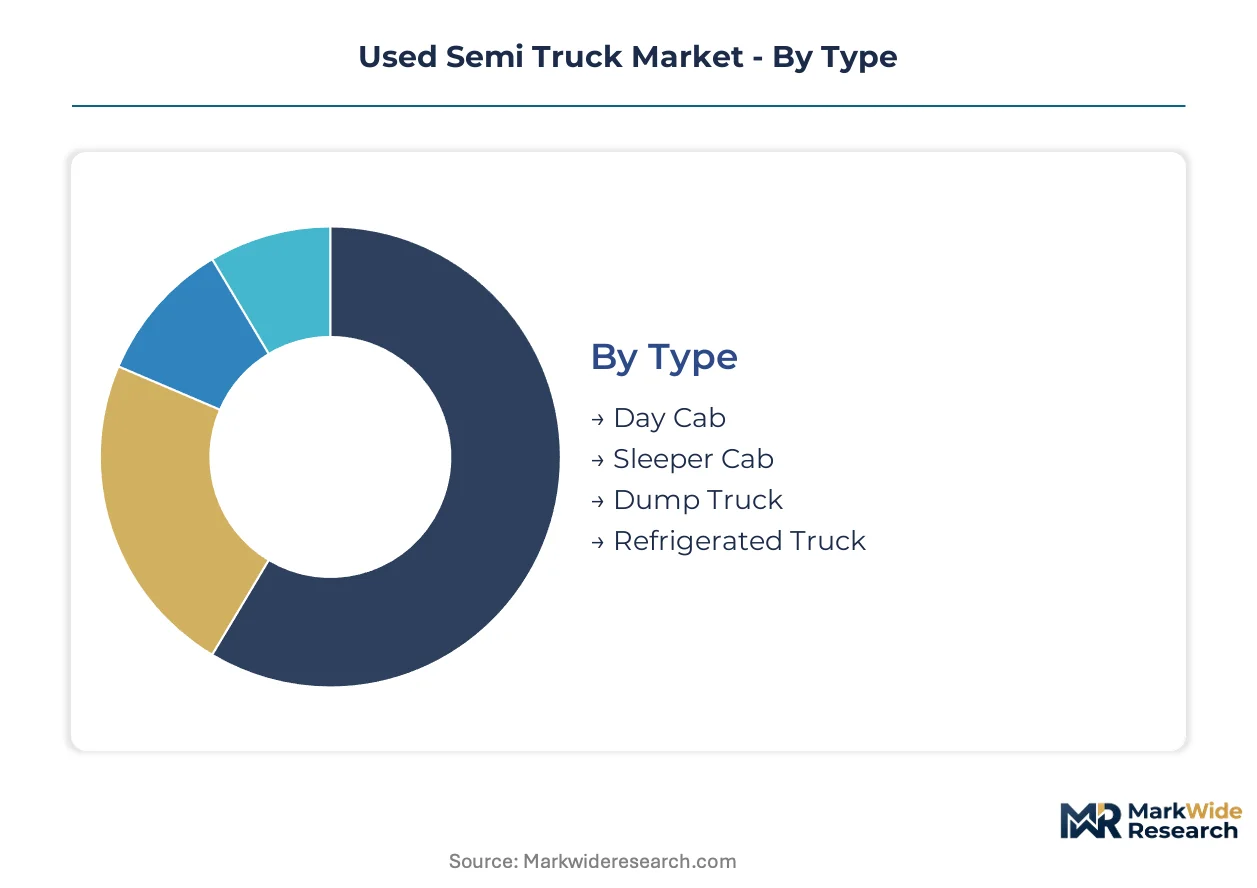
Used semi truck segmentation reveals divergent value capture across duty cycles and regulatory exposure. Fleet managers prioritize sleeper cab configurations for over-the-road routes while construction verticals stabilize day cab demand. Fuel type stratification increasingly reflects emissions compliance geography rather than operational preference alone.
Type:
Sleeper cab units command volume leadership in interstate freight corridors, while day cabs anchor regional construction and urban logistics pools.
- Sleeper Cab:These tractors integrate berth compartments behind the cab for extended haul operations, typically retaining 72-inch or longer sleeper boxes. Demand concentrates along the Texas-Oklahoma corridor where independent owner-operators require FMCSA hours-of-service compliance without motel costs.
- Day Cab:Cab-only configurations eliminate sleeper weight for return-to-base routing under 500-mile radii. Regional construction companies in the Southeast and Midwest source these units through dealership networks for equipment hauling and material delivery.
- Dump Truck:Hydraulic bed configurations serve aggregate and demolition verticals with reinforced chassis specifications. Municipal contractors and quarry operators favor three-axle variants for payload capacity compliance.
- Refrigerated Truck:Insulated van bodies with transport refrigeration units protect temperature-sensitive cargo. Food distributors and pharmaceutical logistics providers prioritize low-hour units with verified reefer compressor maintenance histories.
Today's leader: Sleeper Cab. Tomorrow's challenger: Refrigerated Truck.
Fuel Type:
Diesel retains transaction volume dominance while electric and natural gas segments capture regulatory arbitrage premiums.
- Diesel:Compression-ignition engines above 12 liters displacement power the vast majority of Class 8 secondary market flows. EPA Phase 3 standards compress resale windows for pre-2021 blocks, pushing procurement toward certified pre-owned channels with verified emissions documentation.
- Electric:Battery-electric tractors with 200-plus mile ranges are entering secondary channels as early fleet adopters rotate equipment. California CARB zero-emission mandates create transferable compliance value for low-mileage units sold across state lines.
- Natural Gas:Compressed natural gas powertrains with verified tank integrity command structural premiums in corridors with fuel infrastructure density. Texas and California buyers price these assets above comparable diesel units for operational cost predictability.
- Hybrid:Diesel-electric auxiliary systems reduce idle fuel consumption for urban delivery cycles. Last-mile logistics providers in emissions-restricted municipalities source these units for regulatory compliance without range anxiety.
The steepest expansion trajectory belongs to Electric. Diesel maintains the deepest liquidity pool.
End User:
Independent owner-operators drive sleeper cab premiums while logistics providers standardize procurement through fleet management platforms.
- Freight Carriers:Asset-based trucking companies with 100-plus unit fleets source three- to four-year-old lease returns with residual manufacturer warranties. These buyers prioritize telematics integration and verified maintenance histories over acquisition price.
- Independent Owner-Operators:Single-truck operators in the Texas-Oklahoma corridor seek sleeper cab inventory with integrated ELD compliance. Financing availability through captive lender programs determines purchase timing more than equipment age.
- Logistics Providers:Third-party freight brokers and dedicated contract carriers acquire day cab units for regional shuttle networks. Subscription-based fleet access models are displacing traditional ownership for this segment.
- Construction Companies:Heavy civil and specialty contractors source dump truck configurations with reinforced suspensions. Equipment utilization rates below 50 percent annually extend acceptable acquisition age versus freight applications.
Volume concentration rests with Freight Carriers. Margin capture favors Independent Owner-Operators.
Sales Channel:
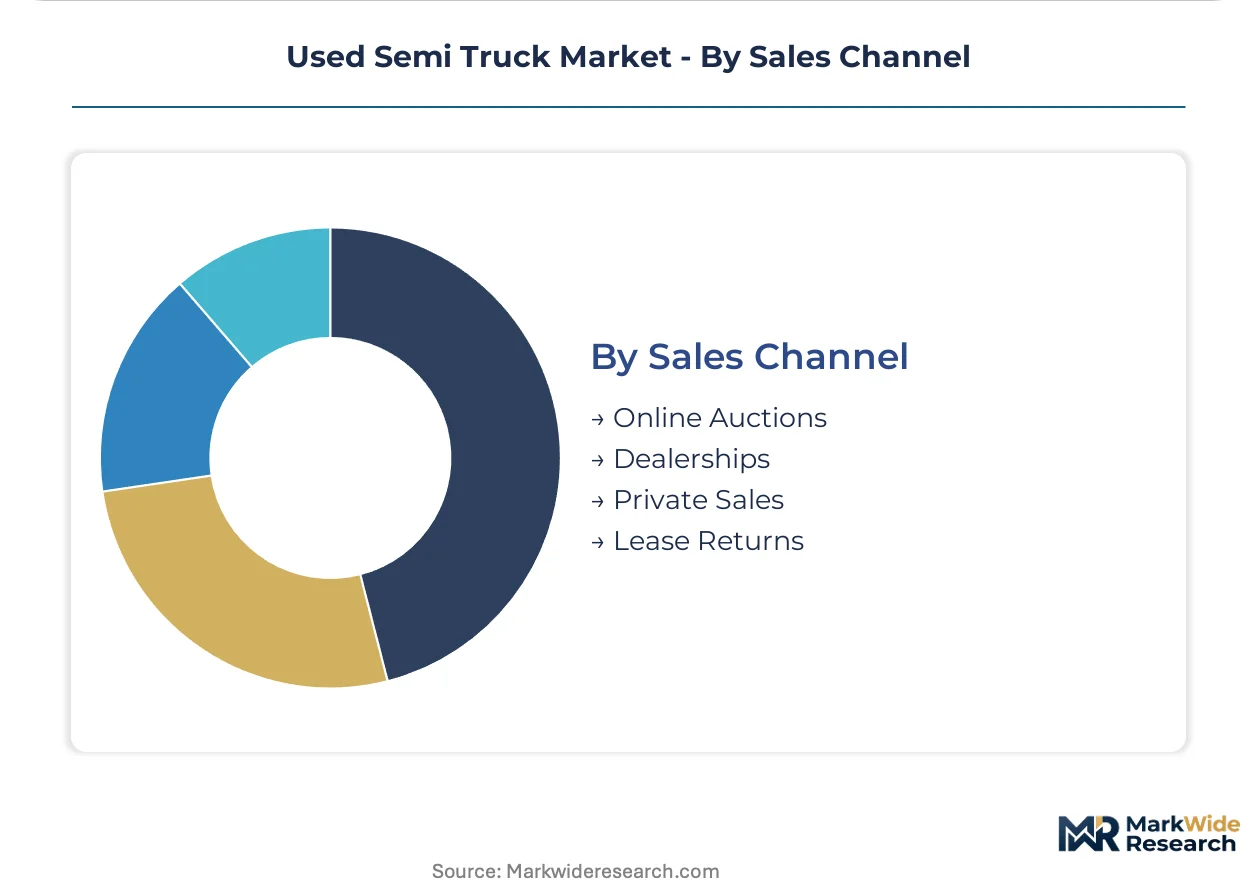
Dealership networks anchor price discovery while digital auction platforms compress transaction cycles.
- Dealerships:Authorized dealer networks for PACCAR, Volvo, and Daimler Truck certify pre-owned inventory with extended powertrain warranties. These channels capture margin premiums through inspection protocols and financing arrangements.
- Lease Returns:Fleet management companies including Ryder System Inc anchor secondary supply flows with volume dispositions. Three- to four-year-old Class 8 tractors enter these channels with predictable maintenance histories and residual documentation.
- Online Auctions:Digital platforms aggregate listings from fleet operators and financial institutions with predictive analytics pricing. Telematics data bundling is compressing information asymmetry between sellers and buyers.
- Private Sales:Direct transactions between operators bypass intermediary fees but extend due diligence timelines. Title documentation inconsistencies and odometer verification risks temper buyer confidence in this channel.
Dealerships define price ceilings. Online Auctions are gaining transaction velocity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-Oklahoma corridor anchors North American used semi truck liquidity, with sleeper cab transactions clustering around Dallas-Fort Worth auction houses and Oklahoma City dealership networks serving independent owner-operators.
United States
Freight carriers in the Southeast and Midwest accelerate fleet renewal through lease return channels as EPA Phase 3 standards tighten emissions thresholds. The Department of Transportation enforces electronic logging device mandates through FMCSA, altering utilization economics for older tractors. The I-35 corridor from Dallas through Kansas City concentrates certified pre-owned inventory flows, with three- to four-year-old Class 8 units commanding structural premiums.
Canada
Cross-border carriers source low-mileage diesel tractors from US auction channels to circumvent domestic supply constraints in the Prairie Provinces. Transport Canada aligns commercial vehicle standards with EPA thresholds, creating regulatory continuity for interstate operators. Calgary and Edmonton distribution hubs anchor secondary market activity, with Alberta construction companies stabilizing day cab demand for oilfield equipment hauling.
Mexico
Manufacturing logistics providers in Nuevo León and the Bajío Region absorb US-exported sleeper cabs for cross-border freight corridors. The Secretariat of Economy enforces emissions documentation requirements for imported commercial vehicles, extending due diligence timelines. Monterrey trucking clusters concentrate procurement through dealership networks serving automotive parts distributors and electronics manufacturers.
Germany
European freight operators source certified pre-owned tractors through KBA-registered channels as EU Green Deal standards compress resale windows for pre-2021 diesel blocks. The Federal Motor Transport Authority mandates digital tachograph compliance, pushing procurement toward newer used models with integrated telematics. The Rhine-Ruhr industrial corridor anchors secondary market liquidity, with Duisburg logistics clusters standardizing procurement through manufacturer-backed programs.
China
Domestic logistics providers rotate battery-electric Class 8 units into secondary channels as MIIT subsidy programs accelerate fleet electrification. The Ministry of Ecology and Environment enforces dual carbon goals that reshape residual value curves for internal combustion assets. The Yangtze River Delta manufacturing belt concentrates electric tractor pre-positioning, with Shanghai-based fleet operators piloting subscription-based access models.
Used Semi Truck Market Competitive Landscape
Global majors compete with regional champions across certification and financing dimensions. The market structure tiers around manufacturer-backed dealer networks, fleet management dispositions, and independent auction platforms. Three archetypes dominate: OEM-captive certification programs, lease return aggregators, and digital marketplace operators. Competitive intensity concentrates on warranty extension protocols and telematics data bundling rather than price alone.
Among OEM-captive players, PACCAR Inc and Volvo Trucks exemplify the certification-driven archetype, anchoring premium pricing through extended powertrain inspection protocols. Ryder System Inc occupies the lease return aggregation position, controlling supply flows from shortened replacement cycles. These three entities represent distinct strategic postures: manufacturer-backed quality assurance, fleet management scale economics, and residual risk retention.
| Leading Market Players |
|---|
| PACCAR Inc |
| Volvo Trucks |
| Daimler Trucks |
| Ryder System Inc |
| Penske Used Trucks |
| Navistar International |
| Peterbilt |
| Kenworth |
| Gordon Truck Centers |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between EPA Phase 3-compliant units and pre-2021 diesel blocks shapes both pricing power and supply routing. Premium-capture concentrates in dealer networks with verified emissions documentation, while commodity flows redirect toward jurisdictions with softer enforcement thresholds.
Pricing Analysis
Input-cost pass-through from EPA-certified remanufacturing and high-voltage technician training feeds into sleeper cab premiums. Three-tier pricing structure across certified pre-owned, lease-return standard, and auction-economy levels separates warranty-backed inventory from as-is sales. Cost compression in pre-2021 diesel segments is intensifying because rebuild eligibility narrows under state-level CARB adoption. Independent owner-operators in the Texas-Oklahoma corridor exhibit highest price sensitivity, while freight carriers with captive maintenance data prioritize telematics integration over acquisition cost.
Supply Chain Analysis
Workforce availability constraints in Michigan, Tennessee, and Texas manufacturing geographies bottleneck emission-system diagnostics capacity. Used semi truck supply draws from Detroit diesel remanufacturing hubs, Memphis aftermarket distribution centers, and Dallas-Fort Worth auction aggregation points. Single-source vulnerability clusters around proprietary telematics protocols from PACCAR and Volvo that prevent cross-platform integration. Distribution runs through manufacturer-authorized dealer networks, fleet management lease return channels, and digital auction platforms with predictive analytics bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The used semi truck market functions as a geographic-arbitrage play where CARB-state compliance premiums in California diverge from Texas-Oklahoma pricing floors, creating margin capture opportunities for cross-border traders.
For Market Incumbents: Lock in certified pre-owned program expansion by extending powertrain inspection protocols to day cab inventory serving construction verticals. Capture margin expansion through telematics data licensing agreements that compress information asymmetry between sellers and buyers. Vertical integration into captive financing arrangements anchors customer retention against digital auction platform encroachment.
For New Entrants and Emerging Players: The price-point gap between premium certified pre-owned sleeper cabs and economy auction day cabs offers white-space positioning for subscription-based fleet access models. Target mid-size logistics providers in the Southeast and Midwest with monthly per-mile contracts bundling maintenance and compliance monitoring. Lead with natural gas powertrain arbitrage in Texas and California corridors where fuel infrastructure density supports operational economics.
For Investors and Strategic Acquirers: Consolidation pressure builds where technician certification bottlenecks and proprietary telematics fragmentation create capability scarcity. Long-term viability hinges on positioning ahead of electric tractor secondary market development as fleet electrification mandates harden. Watch for inflection where battery-electric Class 8 units achieve critical mass in lease return channels, signaling residual value methodology shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Pre-Owned Program Expansion | Dealer networks capture margin premiums through EPA Phase 3 compliance verification and extended warranty coverage. |
| Telematics Data Licensing | Fleet operators monetize engine performance histories to compress price discovery cycles in digital auction channels. |
| Natural Gas Infrastructure Partnership | Fuel station operators anchor powertrain premiums by verifying tank integrity for California and Texas corridor buyers. |
| Subscription-Based Fleet Access | Logistics providers shift residual risk to fleet management companies while scaling capacity without capital deployment. |
| Electric Tractor Pre-Positioning | Early secondary market development for battery-electric units offers first-mover positioning ahead of mainstream electrification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet managers, dealership operators, auction platform executives, and independent owner-operators with secondary validation. Regulatory filings from EPA and CARB, FMCSA enforcement data, SEC disclosures from PACCAR and Ryder System, and auction transaction databases anchored supply-side quantification. Bottom-up unit flow analysis and top-down market sizing triangulated volume estimates across sleeper cab, day cab, and alternative fuel segments.
Comparable-period anchoring tied projection models to historical fleet turnover cycles and lease return velocity patterns across the analysis window. Segmentation dimensions modeled include cab configuration, fuel type, end-user archetype, and sales channel structure, with regulatory compliance geography layered as an industry-specific overlay. CAGRs derived from unit transaction velocity, residual value depreciation curves, and replacement cycle compression under EPA Phase 3 standards. Forecast inputs incorporated telematics penetration rates and technician certification pipeline data.
Caveats apply where CARB zero-emission mandate adoption timelines or battery-electric residual value methodologies could materially shift the outlook. Forecasts reflect assumptions around regulatory enforcement continuity and fleet electrification capital allocation priorities. Material deviation in EPA Phase 3 state-level adoption patterns or electric tractor secondary market liquidity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Canada Used Car Market
Used Vehicles
Spain Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
Qatar Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
GCC Used Car Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
UAE Certified Pre-Owned Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
Europe Used Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
Malaysia Used Car Market