
 Qatar Used Car Market | 2026-2036
Qatar Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Used Car Market Insights
Buyer fragmentation across young Qatari professionals and expatriate families is realigning how inventory moves through Doha's secondary vehicle channels. Oasis Cars leverages its showroom network to sustain visibility among mid-income sedan shoppers. CarSemsar anchors its platform with verified listings, while Autobahn Qatar differentiates through performance-oriented European imports.
A used car denotes a previously registered motor vehicle transferred through resale, subject to odometer verification, mechanical inspection protocols, and title-history documentation prior to re-registration. Its commercial purpose centers on affordable mobility access for buyers priced out of new-vehicle markets. The SUV segment dominates transaction volumes given family-size requirements and desert-driving conditions across Qatar's road network. Online Platforms capture the fastest inventory turnover by compressing search-to-sale timelines through digital verification tools. Certified Pre-Owned vehicles command the strongest margin pools due to warranty-backed assurances and manufacturer-backed inspection standards.
Qatar's Ministry of Transport and Communications enforces digital marketplace licensing that filters unverified sellers from online platforms. The General Directorate of Traffic mandates roadworthiness inspections before ownership transfer, shaping vehicle quality thresholds. Stakeholders must monitor how emissions-testing proposals from Qatar's environmental regulator alter import eligibility for older diesel inventory.
Market Dynamics
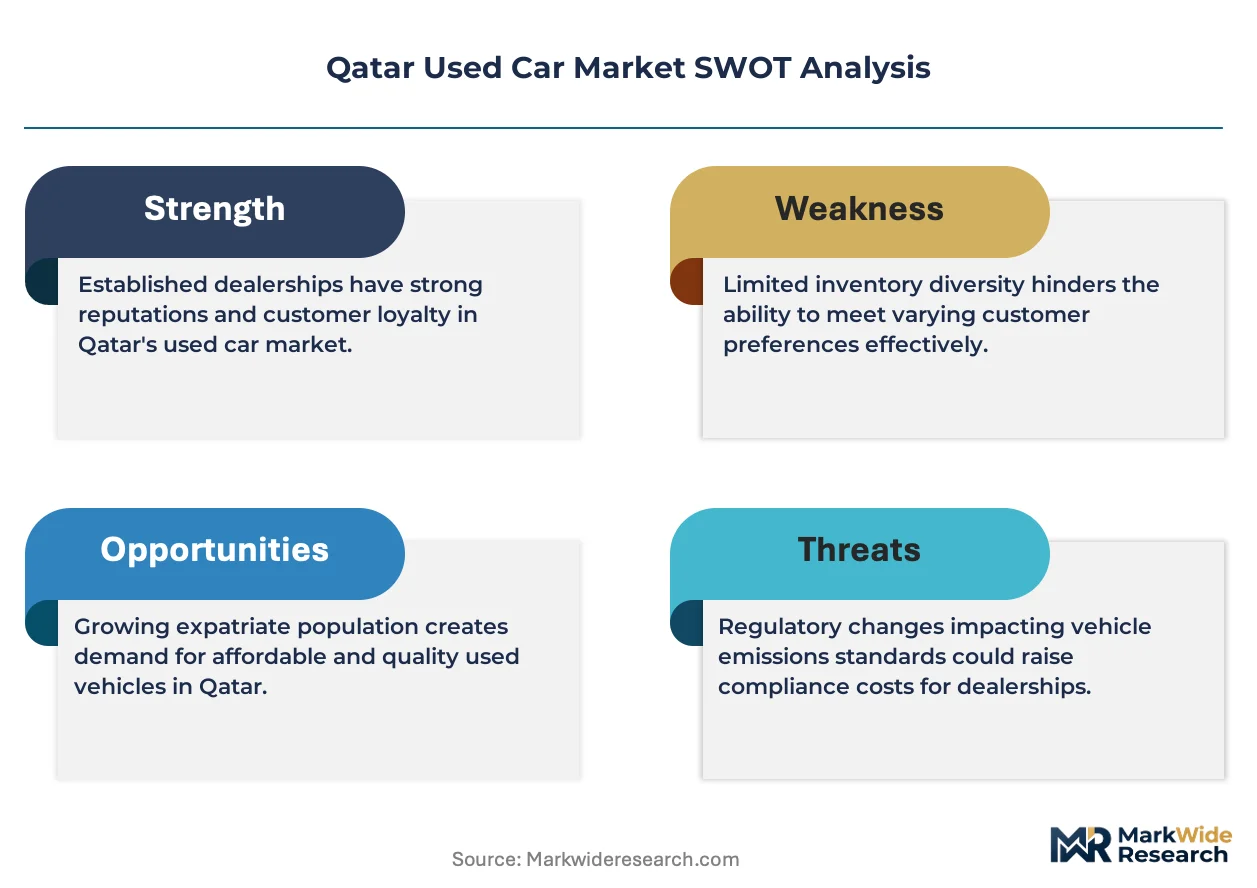
Qatar's Ministry of Transport and Communications tightened digital marketplace licensing requirements, forcing unverified sellers off online platforms and accelerating consolidation among certified dealers with showroom networks in Doha and Al Wakrah.
Growth Catalysts
- Digital Verification Infrastructure:Online platforms now integrate odometer authentication and title-history databases, compressing search-to-sale timelines for SUV-seeking families in Lusail.
- Desert-Driving Utility Demand:Qatar's road network and recreational dune access push young professional households toward four-wheel-drive inventory with proven service records.
- Certified Pre-Owned Standards:Manufacturer-backed inspection protocols and warranty assurances from European and Japanese marques expand buyer confidence in premium segments.
Market Restraints
- Import Age Restrictions:Qatar's environmental regulator proposes emissions-testing mandates that threaten eligibility for older diesel SUVs popular among budget buyers.
- Financing Concentration:Vehicle loans cluster among three dominant banks, limiting credit access for expatriate workers without salary-transfer arrangements.
- Spare Parts Supply Bottlenecks:Specialized components for European performance vehicles face extended lead times through Doha's Jebel Ali corridor.
Strategic Opportunities
- Al Wakrah Satellite Showrooms:Underpenetrated secondary locations south of Doha offer lower rental costs and proximity to family-sized housing developments.
- Subscription-to-Ownership Pathways:Short-term leasing platforms convert trial users into used-car buyers through equity-building structures.
- EV Secondary Market Preparation:Battery health certification standards position early movers for electric vehicle remarketing as Qatar Energy expands charging infrastructure.
Industry Challenges
- Technical Inspection Workforce Shortages:Qatar's General Directorate of Traffic mandates roadworthiness checks, but trained assessors remain concentrated in Doha.
- Cross-Platform Listing Coordination:Inventory synchronization between dealer management systems and aggregator sites creates data-integrity friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Used Car Market |
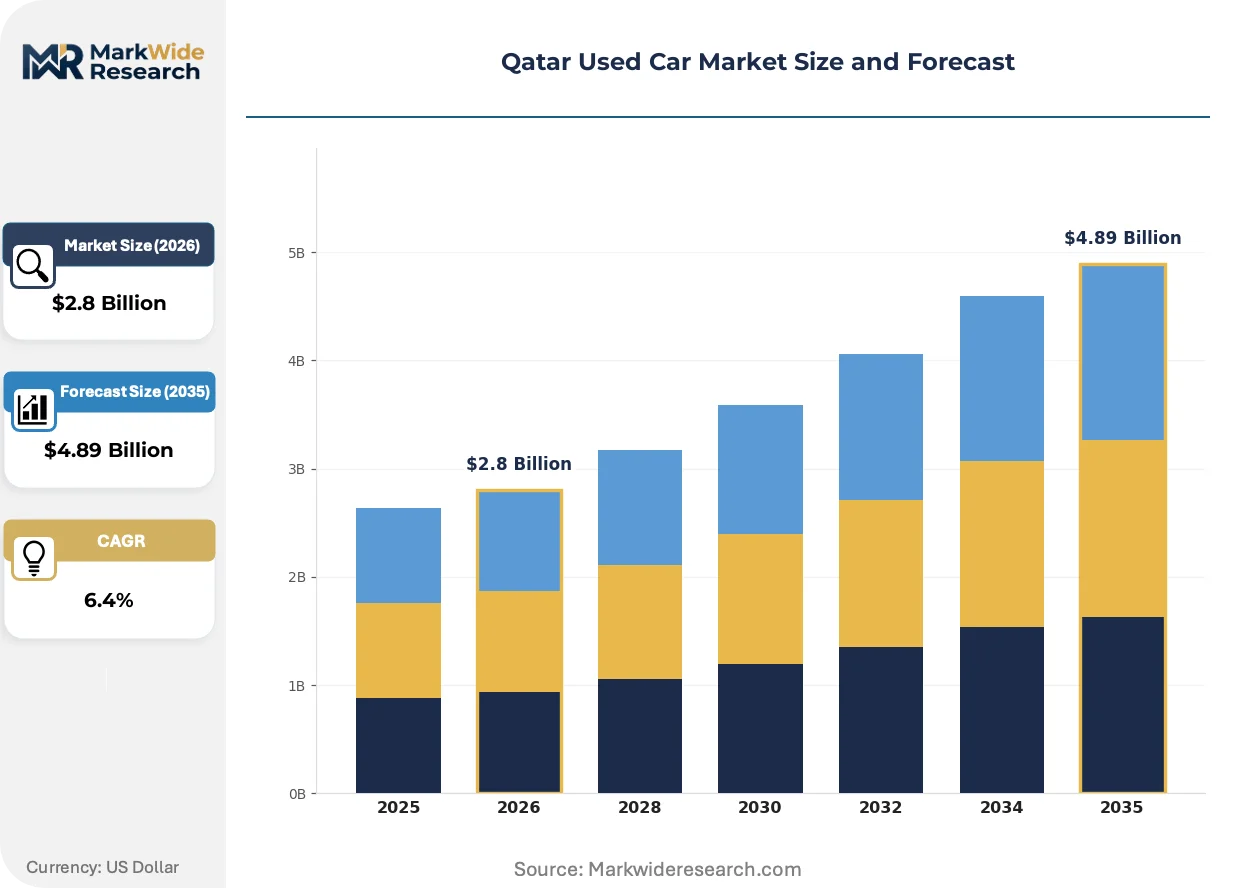
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Hybrid, Electric Condition: Certified Pre-Owned, Used, Salvage, Damaged Sales Channel: Dealerships, Online Platforms, Auctions, Private Sellers |
| Companies Covered | Oasis Cars, CarSemsar, Dubizzle, Edition Motors, Autobahn Qatar, Qmotor, Qatarsale, Elite Motors, Automall Qatar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Used Car Market Trends and Innovations
Digital verification tools and platform consolidation are compressing transaction timelines while reshaping how inventory reaches buyers across Qatar's urban corridor.
Blockchain-based title verification is overtaking paper-based ownership documentation in high-value transactions. Premium sedan and SUV dealers in West Bay adopt distributed-ledger systems to authenticate service histories and previous registrations. This compression of trust-building steps shortens negotiation cycles and reduces post-sale disputes.
Qatar's Ministry of Transport and Communications now mandates real-time seller verification for all digital listings. The regulation forces marketplace operators to integrate national ID authentication and commercial license validation before inventory goes live. Smaller unlicensed operators are exiting the market, concentrating volume among platforms with compliance infrastructure.
Young professional households now initiate purchases through mobile-native discovery platforms rather than physical showroom visits. WhatsApp-integrated negotiation and video inspection replace traditional test-drive sequences for buyers in Al Rayyan and Lusail. This behavioral pivot rewards dealers with digital-first operations and penalizes those dependent on foot traffic in Doha's industrial zone clusters.
Qatar Used Car Market Segmentation
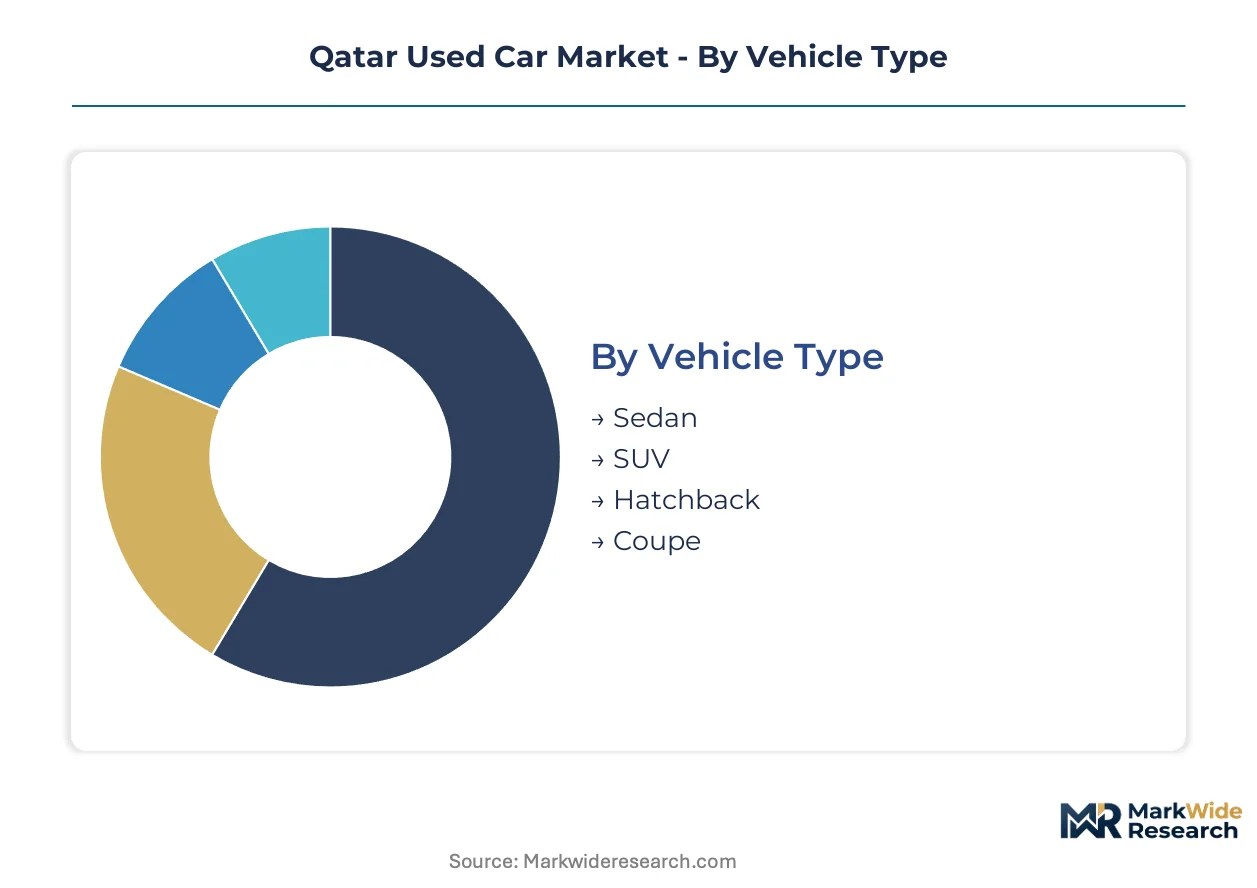
Buyer priorities in Qatar's used car market diverge sharply between family utility requirements and professional mobility needs. Segmentation reveals how vehicle configuration, transaction format, and certification status shape purchase decisions across Doha's urban corridor and emerging residential zones.
Vehicle Type:
Family size and terrain access dominate Qatar's vehicle selection calculus, with desert-driving capability and passenger capacity outweighing fuel efficiency for most buyers.
- SUV:Four-wheel-drive platforms with elevated ground clearance and expanded cabin volume serve Qatar's dual requirements of family transport and recreational dune access. Demand concentrates among young professional households in Al Wakrah and Lusail, where housing developments feature larger parking provisions and proximity to desert access corridors.
- Sedan:Three-box passenger configurations prioritize cabin quietness and trunk capacity for commuting-focused buyers. Mid-income professionals in Doha's central business district favor these vehicles for daily office commutes, though resale values face pressure from SUV preference shifts.
- Hatchback:Compact two-box designs with rear cargo access suit single professionals and secondary household vehicles. Young Qatari professionals in Al Rayyan select these for maneuverability in dense urban parking environments.
- Coupe:Two-door sport configurations with fixed rooflines attract performance-oriented buyers seeking European marques. Limited practicality restricts volume to enthusiast segments in West Bay and The Pearl-Qatar.
SUV leads on scale; Hatchback leads on momentum among younger buyer cohorts.
Fuel Type:
Energy cost structures and infrastructure maturity shape propulsion choices, with Qatar's subsidized petrol pricing and expanding charging networks creating divergent economic calculations.
- Petrol:Spark-ignition internal combustion engines dominate Qatar's inventory given subsidized fuel pricing and established service infrastructure. Families across Doha and Al Wakrah default to these powertrains for reliability predictability.
- Diesel:Compression-ignition engines deliver torque advantages for heavy SUV applications and long-distance desert travel. Budget buyers favor older diesel SUVs, though Qatar's environmental regulator threatens eligibility through proposed emissions-testing mandates.
- Hybrid:Dual-powertrain systems combining petrol engines with electric motors gain traction among cost-conscious professionals. Toyota and Honda hybrid variants show climbing turnover rates in Lusail's showroom networks.
- Electric:Battery-electric vehicles with zero tailpipe emissions remain nascent but positioned for expansion. Qatar Energy's charging infrastructure rollout and battery health certification standards prepare secondary market channels for eventual volume.
Petrol commands current transaction volume; Electric climbs the fastest as infrastructure matures.
Condition:
Trust mechanisms and risk tolerance separate buyer segments, with warranty backing and inspection documentation commanding premium positioning.
- Certified Pre-Owned:Manufacturer-backed inspection protocols with extended warranty coverage attract risk-averse premium buyers. European and Japanese marques deploy these programs through authorized Doha dealerships to defend margin pools.
- Used:Standard previously registered vehicles without manufacturer certification dominate transaction volume through price accessibility. General Directorate of Traffic roadworthiness mandates set baseline quality thresholds for all transfers.
- Salvage:Insurance-totaled vehicles with repairable structural damage serve specialist rebuilders and parts harvesters. Limited legal pathways for roadworthiness restoration constrain commercial scale.
- Damaged:Cosmetically compromised vehicles with intact mechanical systems attract budget buyers prioritizing function over appearance. Qatar's tight digital marketplace licensing filters unverified sellers of these units from online platforms.
Used vehicles lead on scale; Certified Pre-Owned gains share fastest through confidence premiums.
Sales Channel:
Transaction format selection reflects buyer urgency, technical confidence, and price sensitivity, with digital verification tools compressing traditional search-to-sale timelines.
- Dealerships:Physical showroom networks with inspection bays and financing partnerships anchor mid-market SUV transactions. Oasis Cars and similar operators sustain visibility through Doha and Al Wakrah locations.
- Online Platforms:Digital marketplaces integrating odometer authentication and title-history databases capture the fastest inventory turnover. CarSemsar and competitors leverage real-time seller verification mandated by Qatar's Ministry of Transport and Communications.
- Auctions:Competitive bidding formats for fleet disposals and dealer excess inventory serve trade buyers with technical assessment capabilities. Volume concentrates among licensed dealers with inspection infrastructure.
- Private Sellers:Direct owner-to-buyer transactions offer price advantages but carry documentation risks. WhatsApp-integrated negotiation and video inspection increasingly substitute for physical meetings among mobile-native buyers in Al Rayyan.
Dealerships retain volume leadership; Online Platforms show steepest expansion trajectory as verification infrastructure matures.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's used car market operates at roughly triple Qatar's transaction volume, yet both Gulf Cooperation Council states share similar SUV preference patterns and regulatory frameworks governing digital marketplace licensing.
Doha Metropolitan Area
Young professional households in West Bay and The Pearl-Qatar drive demand for certified pre-owned European sedans and performance coupes. Qatar's Ministry of Transport and Communications enforces real-time seller verification for all digital listings, filtering unverified operators from online platforms. Showroom networks concentrate along Salwa Road and Al Sadd Street, where Oasis Cars and Autobahn Qatar anchor mid-market and premium segments respectively.
Al Wakrah
Family-sized housing developments and proximity to desert access corridors position Al Wakrah as Qatar's fastest-growing SUV demand center. The General Directorate of Traffic mandates roadworthiness inspections before ownership transfer, shaping vehicle quality thresholds for transactions. Lower commercial rental costs compared to central Doha attract satellite showroom investments from dealership chains seeking underpenetrated secondary locations.
Lusail
Planned city infrastructure and larger parking provisions in new residential towers accommodate four-wheel-drive platforms with expanded cabin volume. Qatar Energy's charging infrastructure rollout prepares secondary market channels for eventual electric vehicle remarketing. Mobile-native buyers in Al Rayyan and Lusail increasingly initiate purchases through WhatsApp-integrated negotiation platforms rather than physical showroom visits.
Al Rayyan
Single professionals and secondary household vehicle purchasers favor compact hatchbacks for maneuverability in dense urban parking environments. Qatar's environmental regulator proposes emissions-testing mandates that threaten eligibility for older diesel SUVs popular among budget buyers. Digital verification tools compress search-to-sale timelines as trained assessors remain concentrated in Doha proper.
Qatar Used Car Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Qatar's used car channels, yielding a tiered structure where platform operators, dealership networks, and classified aggregators each defend distinct transaction formats. Consolidation pressures intensify as Qatar's Ministry of Transport and Communications tightens digital marketplace licensing, forcing unverified sellers toward exit. Three archetypes dominate: certified dealership networks with inspection infrastructure, mobile-native platforms with real-time verification, and horizontal classified sites with broad inventory reach. Dominant competitive moves include geographic expansion into Al Wakrah satellite locations and backward integration into captive financing arrangements.
Within the certified dealership tier, Oasis Cars and Autobahn Qatar occupy positions reflecting divergent segment focus—Oasis Cars exemplifies the mid-market sedan specialist with showroom density along Doha's commercial corridors, while Autobahn Qatar represents the performance-oriented European import archetype targeting West Bay and The Pearl-Qatar buyers. CarSemsar anchors the platform-native segment, its verified listing infrastructure aligning with regulatory mandates from Qatar's Ministry of Transport and Communications.
| Leading Market Players |
|---|
| Oasis Cars |
| CarSemsar |
| Dubizzle |
| Edition Motors |
| Autobahn Qatar |
| Qmotor |
| Qatarsale |
| Elite Motors |
| Automall Qatar |
| Others |
Pricing and Supply Chain Analysis
Certified Pre-Owned tier divergence against standard used inventory creates parallel pricing architectures in Qatar's secondary vehicle market, with manufacturer-backed warranty coverage commanding substantial premiums while unverified listings face compression from the Ministry of Transport and Communications' digital licensing mandates. This bifurcation reshapes procurement patterns as dealers source inventory through auction channels versus direct consumer trade-ins.
Pricing Analysis
Capacity additions in Al Wakrah satellite showrooms are reshaping price floors for family-oriented SUVs as lower rental costs enable competitive positioning against Doha's established corridors. Three-tier pricing structure across Certified Pre-Owned, standard used, and damaged-repairable levels separates warranty-backed European imports from General Directorate of Traffic-inspected domestic units and salvage-channel budget inventory. Cost compression in the standard used tier intensifies because Qatar's environmental regulator threatens older diesel eligibility through proposed emissions-testing mandates. Expatriate workers without salary-transfer banking arrangements exhibit highest price sensitivity, while West Bay professionals purchasing Certified Pre-Owned European sedans demonstrate lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows for part-exchange vehicles and lease-return inventory feed Qatar's remarketing pipeline through Jebel Ali corridor refurbishment centers before Doha redistribution. Geographic supply concentration draws from Japan, Germany, and the United Arab Emirates as primary sourcing markets for four-wheel-drive platforms and European performance marques. Component dependencies rest on specialized suspension systems, desert-rated cooling assemblies, and infotainment modules calibrated for regional specifications. Single-source vulnerability concentrates in trained technical assessor availability for roadworthiness certification. Distribution runs through authorized dealership networks, mobile-native platforms with real-time verification, and horizontal classified aggregators with broad inventory reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's used car market offers margin-expansion pathways through Certified Pre-Owned certification investments and digital verification infrastructure that compresses transaction timelines while reducing post-sale dispute costs.
For Market Incumbents: Cement dominance in SUV-heavy segments by acquiring inspection-capable satellite locations in Al Wakrah before rental cost advantages erode. Integrate backward into captive financing arrangements to circumvent the three-bank loan concentration that restricts expatriate buyer access. Defend against mobile-native platform displacement by embedding WhatsApp-negotiation workflows and video inspection capabilities into existing showroom operations. For New Entrants and Emerging Players: Single professionals in Al Rayyan seeking compact hatchbacks represent an underserved buyer archetype with distinct maneuverability priorities and parking-constrained use cases. Battery health certification capabilities position early movers for electric vehicle remarketing as Qatar Energy expands charging infrastructure across Lusail. Launch through subscription-to-ownership equity-building structures that convert trial users into permanent buyers with embedded financing. For Investors and Strategic Acquirers: Consolidation pressure builds where unlicensed operators exit under tightened Ministry of Transport and Communications digital marketplace mandates, concentrating volume among compliance-capable platforms. Long-term viability favors acquisition targets with integrated inspection infrastructure and verified listing technology rather than pure classified aggregation. Monitor emissions-testing mandate progression from Qatar's environmental regulator as inflection indicator for diesel SUV inventory obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Pre-Owned Program Expansion | Manufacturer-backed warranty coverage from European and Japanese marques defends margin pools against unverified competition. |
| Digital Verification Infrastructure Investment | Real-time seller authentication mandated by Qatar's Ministry of Transport and Communications filters non-compliant operators from online platforms. |
| Al Wakrah Satellite Showroom Network | Lower commercial rental costs and proximity to family-sized housing developments capture fastest-growing SUV demand geography. |
| Battery Health Certification Capability | Early positioning for electric vehicle remarketing aligns with Qatar Energy charging infrastructure rollout across Lusail. |
| Subscription-to-Ownership Pathway Launch | Short-term leasing platforms convert trial users into used-car buyers through equity-building structures that bypass traditional financing concentration. |
Research Methodology
Bottom-up vehicle transaction modeling reconciled against top-down inventory flow tracking forms the analytical core of this study. Primary interviews with dealership operations directors, online platform product managers, General Directorate of Traffic certification officers, and financing product specialists at dominant banks were validated against secondary sources including vehicle registration databases, customs import records, and regulatory filings from Qatar's Ministry of Transport and Communications. Triangulation across these inputs ensures dimensional consistency between reported transaction volumes and observed supply-side movements.
Input-output matrices map propulsion architecture, vehicle class, certification status, and sales channel against buyer archetype segmentation throughout the forecast period. CAGRs were derived from trend extrapolation of verified transaction flows and inspection volume data. Industry-specific forecast inputs include desert-driving utility demand shifts, emissions-testing mandate progression, and charging infrastructure deployment timelines from Qatar Energy.
Underlying measurement precision varies by segment; Certified Pre-Owned and online platform transactions carry tighter precision than private seller exchanges where documentation gaps persist. Forecasts reflect assumptions regarding regulatory enforcement continuity and infrastructure investment commitments. Practitioners should monitor emissions-testing mandate finalization and battery health standard development for early signals of inventory eligibility and electric vehicle remarketing timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
South Korea Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
Switzerland Used Car Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
North America Used Car Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
Italy Used Car Market
Used Vehicles
Portugal Used Car Market
Used Vehicles
Australia Used Car Market
Used Vehicles
Norway Used Car Market
Used Vehicles
Middle East and Africa Used Car Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
South Africa Used Car Market