
 Vietnam Used Car Market | 2026-2036
Vietnam Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Used Car Market Outlook
The digital auction-to-retail pipeline is reconfiguring how inventory reaches Vietnamese consumers. Toyota Sure leverages its factory-backed certification network to anchor buyer trust in major metros. Cho Tot Xe competes through peer-to-peer listing density and mobile-first discovery tools. Bonbanh.com dominates price transparency with real-time valuation algorithms that compress information asymmetry between sellers and buyers.
A used car is a previously registered motor vehicle transferred through resale channels, evaluated against odometer readings, structural integrity assessments, and service history documentation before re-entering circulation. Its commercial purpose centers on delivering mobility at depreciated cost points below new-vehicle thresholds while absorbing residual manufacturing value. Sedan and SUV segments lead transaction volumes due to family utility and ride-hailing fleet replenishment cycles, while certified pre-owned condition classifications command margin premiums through warranty-backed quality assurance. Electric and hybrid fuel types are gaining segment traction as charging infrastructure spreads beyond Hanoi and Ho Chi Minh City.
Vietnam's Ministry of Transport sets periodic technical inspection mandates that determine roadworthiness eligibility for resale vehicles, while the Vietnam Register enforces emissions testing protocols that filter non-compliant units from circulation. These frameworks elevate compliance costs for informal dealers and shift volume toward organized channel operators with inspection capabilities. Stakeholders must monitor how inspection stringency evolves and whether battery health certification standards emerge for used electric vehicles.
Market Dynamics
Vietnam's tightened vehicle emissions inspection protocols are compressing informal dealer margins and accelerating channel consolidation toward organized operators with certified inspection capabilities. The Ministry of Transport's roadworthiness mandates now filter non-compliant inventory before resale circulation.
Growth Catalysts
- Urban first-time buyer expansion:Ho Chi Minh City's industrial corridor absorbs workforce migration, concentrating transaction demand in metropolitan nodes with established financing infrastructure.
- Emissions testing protocols:The Vietnam Register's enforcement filters substandard vehicles, elevating certified pre-owned standards and shifting volume toward warranty-backed quality assurance.
- Ride-hailing fleet replenishment:Platform operators cycle vehicles through secondary markets at accelerated depreciation schedules, sustaining transaction velocity in sedan and SUV segments.
Market Restraints
- Compliance cost escalation:Technical inspection mandates impose capital requirements on small dealers, compressing participation to operators with captive testing facilities.
- Charging infrastructure gaps:Used electric vehicle circulation remains constrained outside Hanoi and Ho Chi Minh City, limiting battery-powered segment liquidity.
- Information asymmetry persistence:Odometer tampering and service history opacity sustain buyer skepticism, elongating transaction cycles and compressing price realization.
Strategic Opportunities
- Central Highlands penetration:Da Nang and surrounding provinces exhibit underdeveloped organized retail density, creating first-mover positioning for inspection-capable dealers.
- Battery health certification standards:Anticipated Vietnam Register protocols for used electric vehicles would unlock warranty-backed pricing premiums in emerging electrification corridors.
- Mobile-first discovery convergence:Peer-to-peer listing platforms integrating real-time valuation algorithms compress search friction and expand addressable buyer pools beyond traditional metro boundaries.
Industry Challenges
- Technician certification gaps:Diagnostic capability for electric powertrain assessment remains concentrated in major metros, limiting rural dealer participation in electrifying segments.
- Legacy system integration:Established dealers face reconfiguration costs connecting inventory management to digital auction pipelines, compressing margin recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Used Car Market |
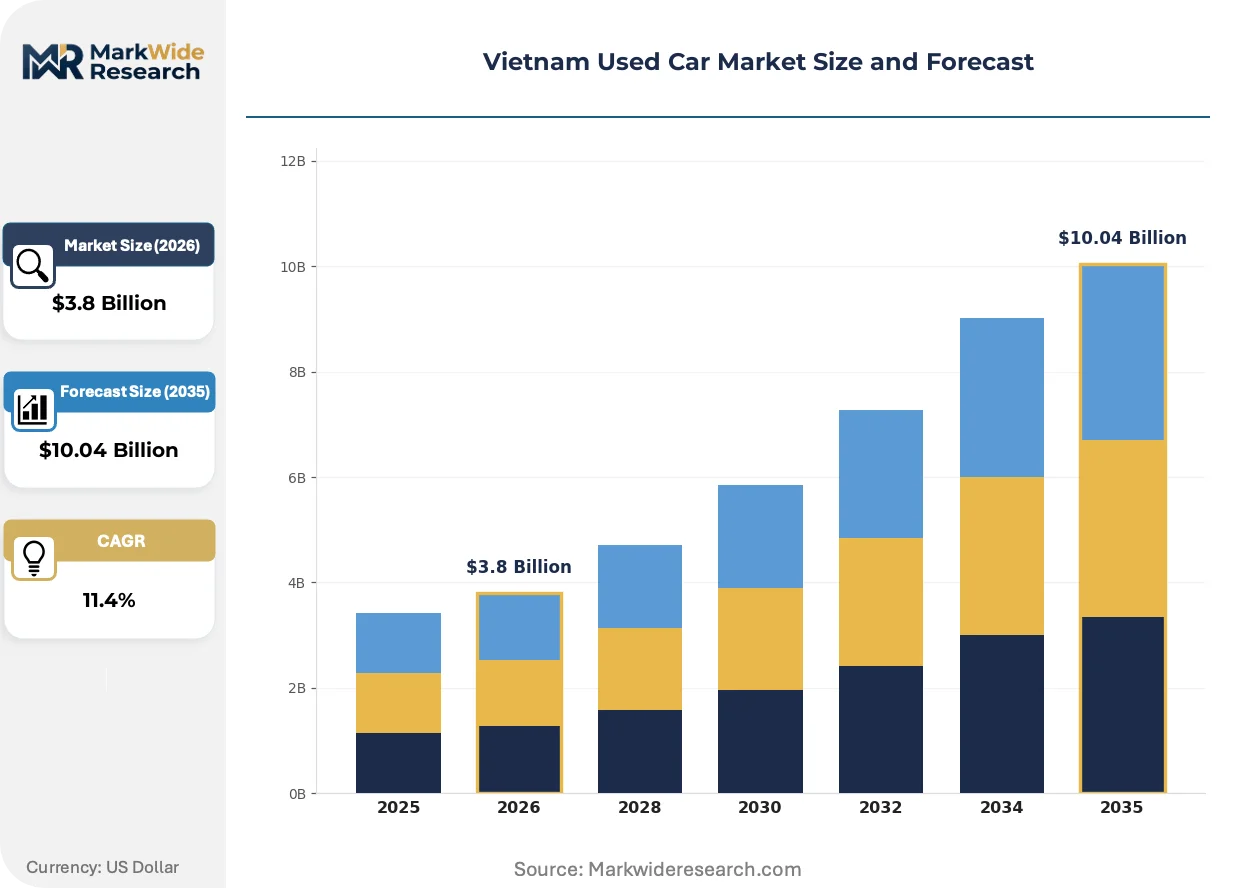
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Truck Fuel Type: Petrol, Diesel, Electric, Hybrid Age of Vehicle: 0-3 Years, 4-6 Years, 7-10 Years, 10+ Years Condition: Certified Pre-Owned, As-Is, Salvage, Refurbished |
| Companies Covered | Toyota Sure, Hyundai Thanh Cong, Ford Vietnam, VinFast, Bonbanh.com, Cho Tot Xe, Oto.com.vn, Viet Han Used Cars, LSH Auto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Used Car Market Strategic Shifts
Digital infrastructure is compressing transaction friction across Vietnam's historically fragmented used vehicle ecosystem. Three developments are restructuring how inventory reaches buyers and how trust is manufactured in secondary markets.
Blockchain-based title verification is virtualizing ownership history authentication. Major metro dealers are piloting distributed ledger systems to immutably record service intervals and accident declarations. This compression of documentation opacity is enabling warranty-backed pricing premiums previously unavailable in peer-to-peer channels.
The Ministry of Transport's tightened periodic technical inspection mandates are restructuring compliance economics. Non-compliant vehicles now face circulation bans, forcing inventory aggregation toward organized operators with Vietnam Register-certified testing facilities. Northern provinces with newer inspection station networks are absorbing volume shifts from informal southern channels.
Buyer discovery patterns are fragmenting across platform types. Mobile-first consumers now initiate searches through valuation-integrated applications before visiting physical inspection sites, compressing the traditional dealer-led sales process. This behavioral pivot concentrates transaction initiation in Ho Chi Minh City and Hanoi's digital-native demographics, forcing physical dealers to maintain hybrid presence across discovery and fulfillment touchpoints.
Vietnam Used Car Market Segmentation
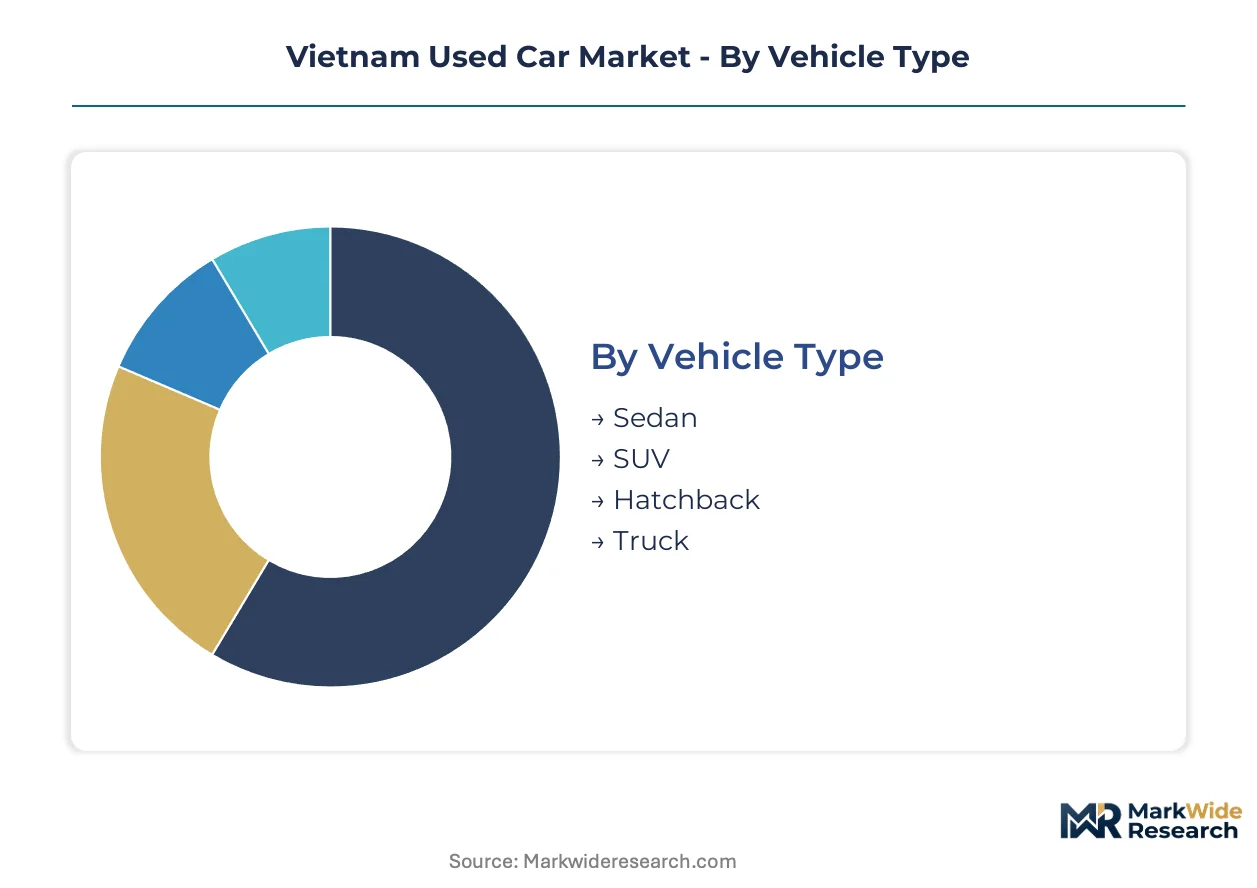
Vietnam's used car segmentation reflects divergent depreciation curves and inspection compliance economics. Cycle times vary dramatically across vehicle age brackets and condition grades, compressing margin recovery windows for dealers managing mixed inventory.
Vehicle Type:
Sedans and SUVs command the shortest inventory cycles in Ho Chi Minh City's industrial corridor, while trucks and hatchbacks linger longer in secondary markets.
- Sedan:Four-door passenger configurations with enclosed cargo compartments dominate ride-hailing fleet replenishment cycles. Grab and Be drivers in Ho Chi Minh City and Hanoi cycle sedans through secondary markets at accelerated depreciation schedules, sustaining transaction velocity.
- SUV:Sport utility vehicles with elevated ground clearance and expanded cabin volume attract family buyers in suburban Hanoi districts. The Vietnam Register's emissions testing protocols filter older SUV inventory more aggressively than sedans due to heavier powertrain configurations.
- Hatchback:Compact two-box designs with rear cargo access suit first-time urban buyers in Da Nang and Can Tho. Higher depreciation rates compress dealer margins relative to sedan equivalents.
- Truck:Commercial utility vehicles with open-bed configurations serve Central Highlands agricultural and construction sectors. Slower turnover reflects rural financing infrastructure gaps and specialized buyer pools.
Sedan inventory anchors the volume base while SUV transaction value climbs the fastest in organized retail channels.
Fuel Type:
Petrol powertrains dominate liquidity metrics, though electrification corridors in Hanoi and Ho Chi Minh City are reordering segment economics.
- Petrol:Internal combustion engines with spark-ignition configurations constitute the liquid core of Vietnamese secondary markets. Ubiquitous refueling infrastructure and technician familiarity sustain rapid turnover across all age brackets.
- Diesel:Compression-ignition powertrains concentrate in commercial truck and SUV applications. The Vietnam Register's tightened emissions testing protocols are accelerating diesel inventory obsolescence in northern provinces with newer inspection station networks.
- Electric:Battery-electric vehicles with zero tailpipe emissions face circulation constraints outside Hanoi and Ho Chi Minh City charging corridors. Battery health opacity elongates transaction cycles pending anticipated certification standards.
- Hybrid:Dual-powertrain configurations combining petrol engines with electric assist are gaining segment traction. Toyota Sure's factory-backed certification network has established warranty-backed pricing premiums for hybrid inventory in metropolitan nodes.
Petrol vehicles retain the deepest buyer pool while hybrid powertrains expand most quickly in certified pre-owned channels.
Age of Vehicle:
Depreciation curves steepen nonlinearly across age brackets, with inspection compliance costs inflecting sharply after the six-year threshold.
- 0-3 Years:Near-new inventory with minimal wear patterns commands certified pre-owned premiums. Factory warranty transferability and low odometer readings concentrate demand in Hanoi and Ho Chi Minh City organized retail channels.
- 4-6 Years:Mid-cycle vehicles exiting initial depreciation curves balance affordability with remaining service life. Ride-hailing fleet operators in the industrial corridor cycle vehicles through this bracket at predictable intervals.
- 7-10 Years:Mature inventory faces escalating Vietnam Register inspection stringency. Technical compliance costs compress margins and shift volume toward informal southern channels with testing facility gaps.
- 10+ Years:Legacy vehicles with accelerated mechanical degradation circulate primarily in rural provinces. Emissions testing failures filter substantial inventory from legal resale circulation.
The 4-6 year bracket sustains transaction velocity while 0-3 year inventory captures expanding share in warranty-backed channels.
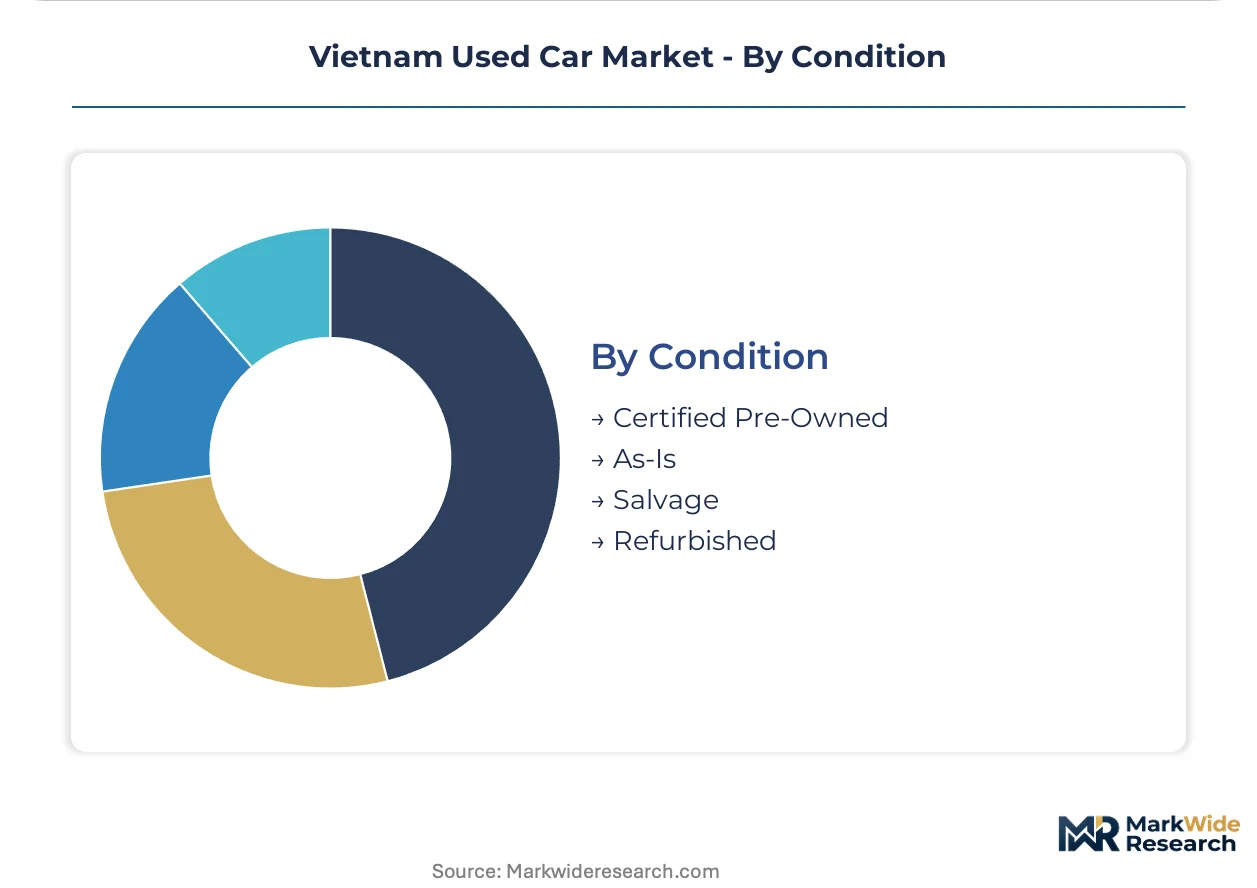
Condition:
Certification grade determines pricing power and buyer trust architecture, with sharp segmentation between organized and informal channel economics.
- Certified Pre-Owned:Factory or dealer-backed vehicles passing structured multi-point inspections with warranty coverage. Toyota Sure and comparable programs in Ho Chi Minh City command margin premiums through documented service history and return policies.
- As-Is:Unwarranted inventory sold without quality guarantees dominates peer-to-peer transactions. Cho Tot Xe listing density concentrates this segment in mobile-first discovery channels.
- Salvage:Insurance-totaled vehicles with structural or flood damage requiring reconstruction. Limited legal circulation and specialized buyer pools constrain liquidity to repair-oriented operators.
- Refurbished:Dealer-reconditioned units with cosmetic and mechanical restoration falling short of full certification. Pricing positions between as-is and certified tiers attract budget-conscious urban first-time buyers.
Certified Pre-Owned anchors margin recovery in organized retail while refurbished inventory gains transaction share in price-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Vietnam Register's emissions testing protocols and the Ministry of Transport's roadworthiness mandates are redistributing used vehicle circulation across provincial boundaries, concentrating transaction liquidity in inspection-capable urban corridors while filtering non-compliant inventory from secondary markets.
Ho Chi Minh City Metropolitan Area
Ride-hailing fleet operators cycle sedans through secondary markets at accelerated depreciation schedules, sustaining transaction velocity in the industrial corridor. The Vietnam Register enforces stringent emissions testing protocols that filter older diesel SUVs more aggressively than petrol alternatives. Districts surrounding Tan Son Nhat International Airport absorb workforce migration, concentrating first-time buyer demand in nodes with established financing infrastructure.
Hanoi Capital Region
Hybrid powertrains gain segment traction as Toyota Sure's factory-backed certification network establishes warranty-backed pricing premiums. The Ministry of Transport mandates periodic technical inspections that elevate compliance costs for informal dealers. Charging infrastructure corridors extending from the urban core are unlocking battery-electric vehicle circulation, though battery health opacity elongates transaction cycles pending certification standards.
Da Nang and Central Coast Provinces
Underdeveloped organized retail density creates first-mover positioning for inspection-capable dealers penetrating beyond traditional metro boundaries. The Vietnam Register's newer inspection station networks in northern provinces absorb volume shifts from informal southern channels. Compact hatchbacks suit first-time urban buyers in Can Tho and surrounding secondary cities, though higher depreciation rates compress dealer margins.
Central Highlands Agricultural Belt
Commercial utility vehicles with open-bed configurations serve agricultural and construction sectors where slower turnover reflects rural financing infrastructure gaps. The Ministry of Transport's roadworthiness mandates filter substantial legacy inventory from legal resale circulation. Specialized buyer pools in Gia Lai and Dak Lak provinces constrain liquidity to repair-oriented operators with localized mechanical expertise.
Vietnam Used Car Market Competitive Environment
On the supply side, the industry is bifurcating between factory-backed certification networks and mobile-first peer-to-peer discovery platforms, with informal dealer channels compressing under compliance cost escalation. Three strategic archetypes dominate: organized multi-point inspection operators, algorithmic price transparency engines, and ride-hailing fleet aggregators cycling inventory at accelerated depreciation schedules. Competitive moves concentrate on geographic expansion into underpenetrated provincial markets and backward integration into captive testing facilities.
Within the factory-certification tier, Toyota Sure anchors buyer trust through warranty-backed quality assurance and documented service history transferability. Among digital-native platforms, Bonbanh.com and Cho Tot Xe exemplify divergent discovery architectures—real-time valuation algorithms versus peer-to-peer listing density—each compressing information asymmetry through distinct mobile-first interfaces. These operators occupy positions that force traditional physical dealers toward hybrid presence across discovery and fulfillment touchpoints.
| Leading Market Players |
|---|
| Toyota Sure |
| Hyundai Thanh Cong |
| Ford Vietnam |
| VinFast |
| Bonbanh.com |
| Cho Tot Xe |
| Oto.com.vn |
| Viet Han Used Cars |
| LSH Auto |
| Others |
Value Chain & Pricing Dynamics
Regulatory chokepoint exposure through the Vietnam Register's emissions testing protocols determines both pricing tier spreads and supply chain shape, as compliance cost escalation filters non-compliant inventory toward organized operators with captive inspection capabilities while compressing informal dealer participation.
Pricing Analysis
Certification level creates the primary spread across Vietnam's used car market, with Vietnam Register-backed inspection grades separating certified pre-owned premiums from as-is discount tiers. Toyota Sure's factory-backed warranty programs command margin premiums in Ho Chi Minh City and Hanoi, while peer-to-peer channels absorb price-sensitive first-time buyers in secondary cities. Pricing pressure stems from inspection compliance cost escalation, which compresses margins for refurbished inventory and accelerates volume concentration toward organized retail.
Supply Chain Analysis
Single-source vulnerability in inspection station networks dominates supply chain risk, as the Vietnam Register's certified testing facilities concentrate in Ho Chi Minh City, Hanoi, and emerging Da Nang corridors. Inventory aggregation draws from Japan's export auction pipelines, Thailand's regional redistribution hubs, and domestic ride-hailing fleet retirements. Distribution runs through hybrid digital-physical channels, with mobile-first discovery platforms feeding physical inspection sites in metropolitan nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
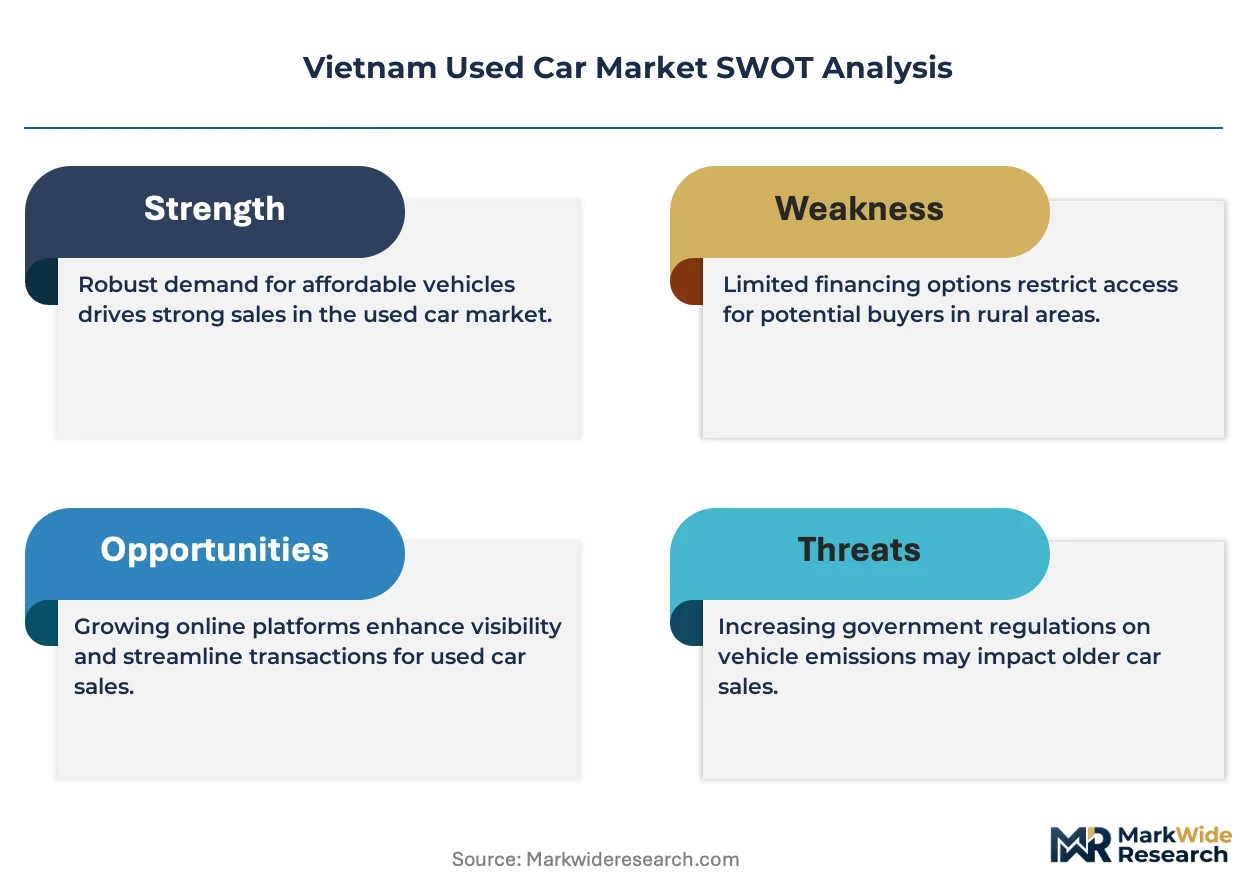
Buyer power is concentrating among organized retail networks with Vietnam Register certification capabilities, as compliance cost escalation fragments informal dealer participation and shifts volume toward inspection-backed quality assurance.
For Market Incumbents: Insulate margin position by deepening captive inspection infrastructure in the Central Highlands corridor before regulatory stringency spreads beyond major metros. Toyota Sure and comparable factory-backed networks should accelerate technician certification programs for electric powertrain assessment, as battery health opacity currently elongates transaction cycles and threatens warranty-backed pricing premiums in emerging electrification segments. For New Entrants and Emerging Players: Da Nang and surrounding Central Coast provinces represent the most penetrable entry point, given underdeveloped organized retail density and newer Vietnam Register inspection station networks absorbing volume shifts from informal southern channels. Battery health certification services for used electric vehicles offer a specialized go-to-market angle, as anticipated Vietnam Register protocols would unlock warranty-backed pricing premiums before established operators capture this whitespace. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors inspection-capable dealer networks with hybrid digital-physical presence. Long-term viability across the projection horizon rests on backward integration into captive testing facilities and mobile-first discovery platform ownership. The signal to monitor is Vietnam Register protocol expansion for battery-electric vehicle certification standards, which would inflect competitive positioning toward electrification-ready operators.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Inspection Facility Buildout | Vietnam Register certification enables warranty-backed pricing premiums in organized retail channels. |
| Mobile-First Discovery Platform Integration | Real-time valuation algorithms compress information asymmetry and expand addressable buyer pools beyond metro boundaries. |
| Battery Health Certification Investment | Anticipated Vietnam Register standards for used electric vehicles would unlock pricing premiums in electrification corridors. |
| Central Highlands Geographic Expansion | Da Nang and surrounding provinces exhibit underdeveloped organized retail density with absorptive inspection infrastructure. |
| Technician Certification Program Development | Electric powertrain diagnostic capability remains concentrated in major metros, constraining rural dealer participation. |
Study Parameters
Desk research of Vietnam Register regulatory filings, Ministry of Transport technical inspection mandates, and vehicle registration databases preceded structured interviews with organized dealer operations managers, peer-to-peer platform product leads, ride-hailing fleet procurement directors, and automotive technician training program administrators. Secondary validation drew from customs import records, auction house transaction data, and charging infrastructure deployment maps. Bottom-up transaction volume estimates triangulated against top-down market sizing from macroeconomic mobility indicators.
Assumptions held fixed include Vietnam Register inspection stringency trajectories and charging infrastructure rollout pace across the projection horizon, while fuel price volatility and ride-hailing platform growth curves were stress-tested across scenarios. Segmentation dimensions modeled encompass vehicle type, fuel architecture, age bracket, condition grade, and geographic regulatory cluster. CAGRs were derived from historical transaction velocity patterns and inspection capacity expansion timelines, with electric vehicle adoption curves and hybrid penetration rates serving as key sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer credit availability, urban migration patterns, or fuel subsidy policies would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and infrastructure deployment schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Used Semi Truck Market
Used Vehicles
Spain Used Car Market
Used Vehicles
United States Used Car Market
Used Vehicles
Canada Used Car Market
Used Vehicles
Italy Used Car Market
Used Vehicles
GCC Used Car Market
Used Vehicles
Used Cars Market
Used Vehicles
Hong Kong Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Australia Used Car Market
Used Vehicles
Vintage Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
North America Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
North America Used Truck Market