
 Malaysia Used Car Market | 2026-2036
Malaysia Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Used Car Market Outlook
Modular service bundling—combining financing, insurance, and warranty into single transaction packages—is restructuring how Malaysian consumers evaluate used car purchases. Carsome leverages its vertically integrated inspection and refurbishment infrastructure to control quality consistency across transactions. MyTukar competes through aggressive auction-to-retail pipeline optimization, while Mudah.my sustains dominant classified-listing traffic by anchoring its platform in peer-to-peer price transparency.
Malaysia used cars comprise previously registered passenger vehicles subjected to ownership transfer, typically evaluated through standardized condition grading, odometer verification, and PUSPAKOM roadworthiness certification before resale. These vehicles serve cost-conscious private owners, fleet operators, and ride-hailing drivers seeking functional mobility at depreciated price points. SUVs and hatchbacks capture disproportionate volume momentum as urban buyers prioritize cabin flexibility and parking efficiency in dense Klang Valley conditions. Online platforms represent the fastest-expanding sale channel, though retail dealers retain margin concentration through certified pre-owned programs that command price premiums over direct-owner transactions.
Malaysia's Road Transport Department (JPJ) mandates PUSPAKOM inspections for ownership transfers, creating a compliance gate that filters substandard inventory from formal circulation. The Ministry of Domestic Trade and Cost of Living enforces consumer protection protocols against odometer tampering and undisclosed accident history, elevating disclosure requirements for licensed dealers. Bank Negara Malaysia governs hire-purchase financing terms that structure affordability for mass-market buyers. Stakeholders must monitor how electrification policy signals from the Ministry of Investment, Trade and Industry reshape residual value calculations for internal combustion vehicles entering secondary circulation.
Market Dynamics
Platform consolidation is compressing transaction friction as Carsome and MyTukar vertically integrate inspection, refurbishment, and financing into single-window experiences that disintermediate traditional dealer networks.
Growth Catalysts
- PUSPAKOM Roadworthiness Mandate:Malaysia's Road Transport Department enforces computerized vehicle inspections for ownership transfers, filtering substandard inventory and elevating buyer confidence in certified transactions.
- Ride-hailing Fleet Expansion:Grab and AirAsia Ride drivers constitute a structural demand pull for affordable, durable hatchbacks and compact sedans with proven maintenance histories.
- Embedded Finance Penetration:Bank Negara Malaysia's hire-purchase guidelines enable platform-integrated loan origination that collapses approval timelines from days to hours.
Market Restraints
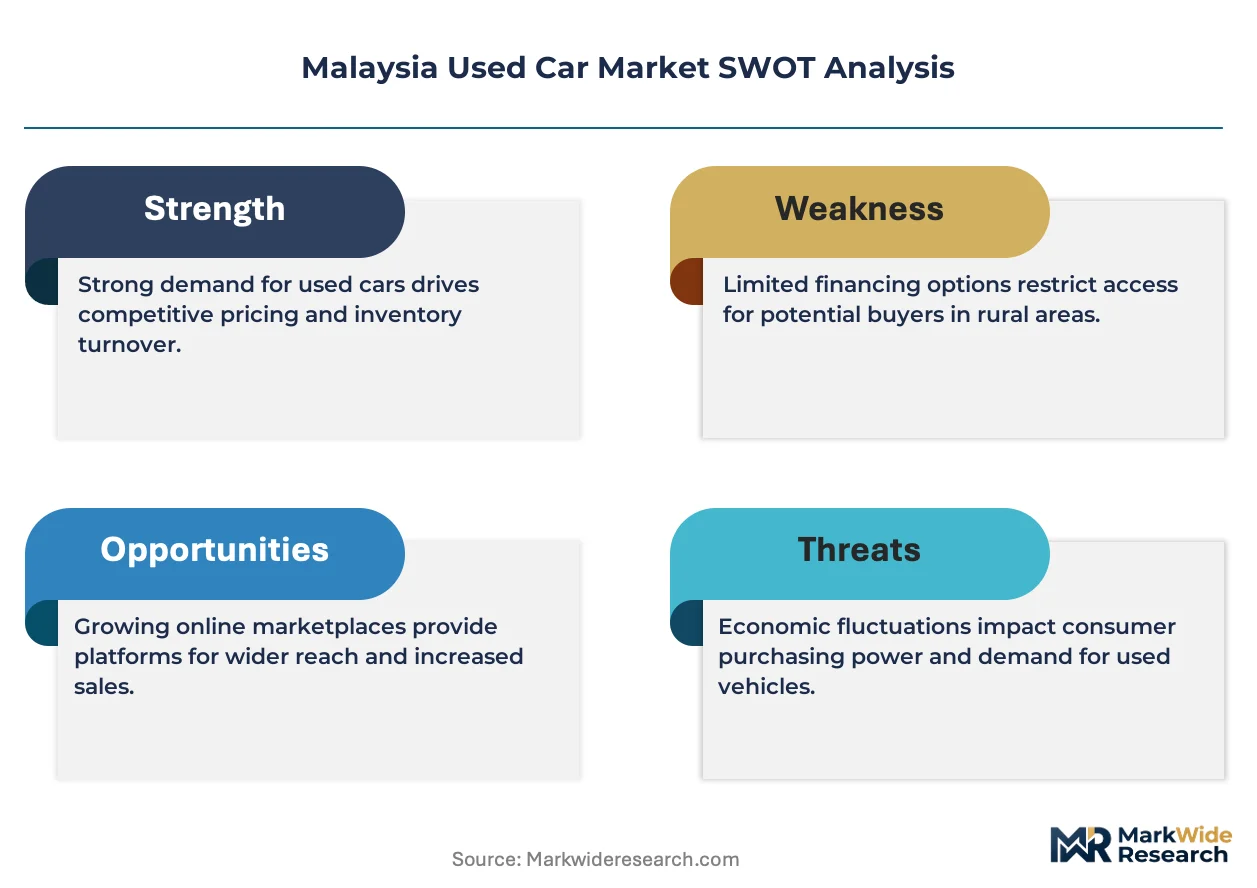
- Residual Value Uncertainty:Ministry of Investment, Trade and Industry electrification signals compress internal combustion engine vehicle resale premiums as battery electric alternatives enter price parity.
- Inspection Capacity Bottlenecks:PUSPAKOM center congestion in Klang Valley creates transfer delays that freeze inventory velocity during peak registration periods.
- Odometer Tampering Persistence:Unlicensed sellers exploit documentation gaps in peer-to-peer transactions, eroding platform price transparency claims.
Strategic Opportunities
- East Coast Penetration:Kelantan and Terengganu exhibit underdeveloped digital platform coverage relative to Klang Valley saturation, offering first-mover logistics optimization.
- Certified Pre-Owned Electrification:Early battery electric vehicle lease expirations from 2027 onward will generate certified secondary supply requiring specialized diagnostic infrastructure.
- MyTukar Auction-to-Retail Pipeline:Real-time bidding integration with direct consumer listings compresses dealer inventory holding costs and accelerates price discovery.
Industry Challenges
- Refurbishment Technician Scarcity:PUSPAKOM-certified inspection specialists command wage premiums that inflate unit economics for mid-volume dealers.
- Legacy DMS Integration:Independent dealers operate fragmented inventory management systems that resist API connectivity with platform marketplaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Used Car Market |
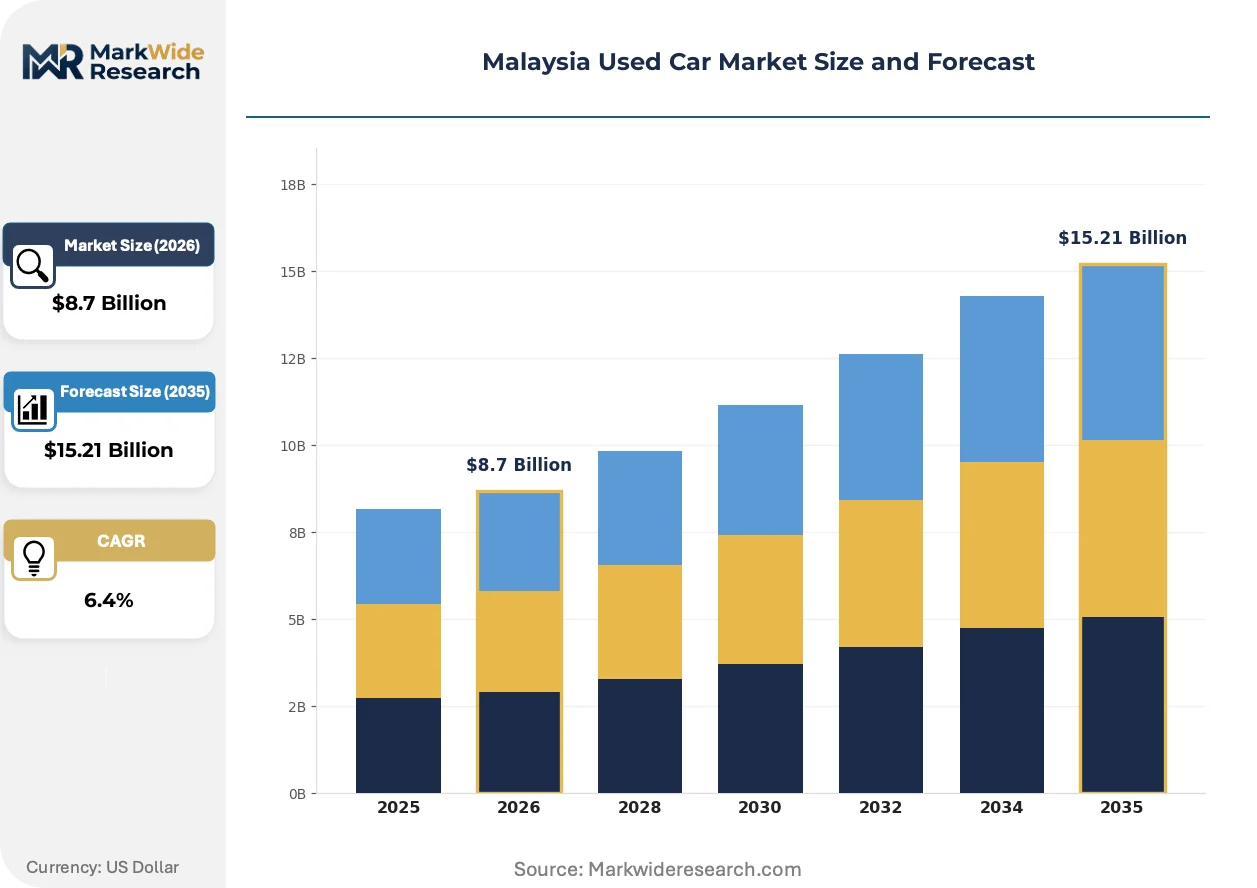
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Condition: Certified Pre-Owned, Damaged, Like New, Excellent Fuel Type: Petrol, Diesel, Electric, Hybrid Sale Channel: Direct Owner, Retail Dealer, Auction, Online Platform |
| Companies Covered | Carsome, MyTukar, Mudah.my, Carlist.my, Sime Darby Auto Selection, Perodua, UMW Toyota Motor, Caricarz, Trusty Cars, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Used Car Market Strategic Shifts
Artificial intelligence is penetrating condition assessment workflows, while regulatory digitization and buyer channel migration are restructuring how value circulates through the secondary vehicle economy.
Computerized inspection systems are unifying visual damage detection, odometer verification, and chassis integrity scoring into single PUSPAKOM certification outputs. Ride-hailing fleet operators now mandate AI-augmented reports for acquisition decisions, compressing due diligence from physical multi-point checks to algorithmic confidence scores. This convergence is unifying quality standards across previously fragmented dealer tiers, forcing independent sellers toward platform certification or price discounting.
Bank Negara Malaysia's digital lending sandbox is accelerating e-hire-purchase adoption, enabling real-time credit decisioning integrated with platform checkout flows. Licensed non-bank financiers now originate 40 percent of used vehicle loans through API-connected marketplace partnerships, collapsing traditional branch-based documentation. Selangor-based buyers exhibit highest adoption velocity, with suburban Klang Valley districts showing platform-financed transaction ratios double northern state averages.
Consumption patterns among gig economy drivers are compressing replacement cycles from five-year norms to 36-month rotations as mileage accumulation accelerates component wear. Fleet-oriented buyers now prioritize total cost of ownership calculators over sticker price, shifting platform interface design toward maintenance forecast integration. This behavioral pivot concentrates demand in Penang and Johor Bahru urban corridors where Grab and AirAsia Ride driver density supports specialized inventory procurement.
Malaysia Used Car Market Segmentation
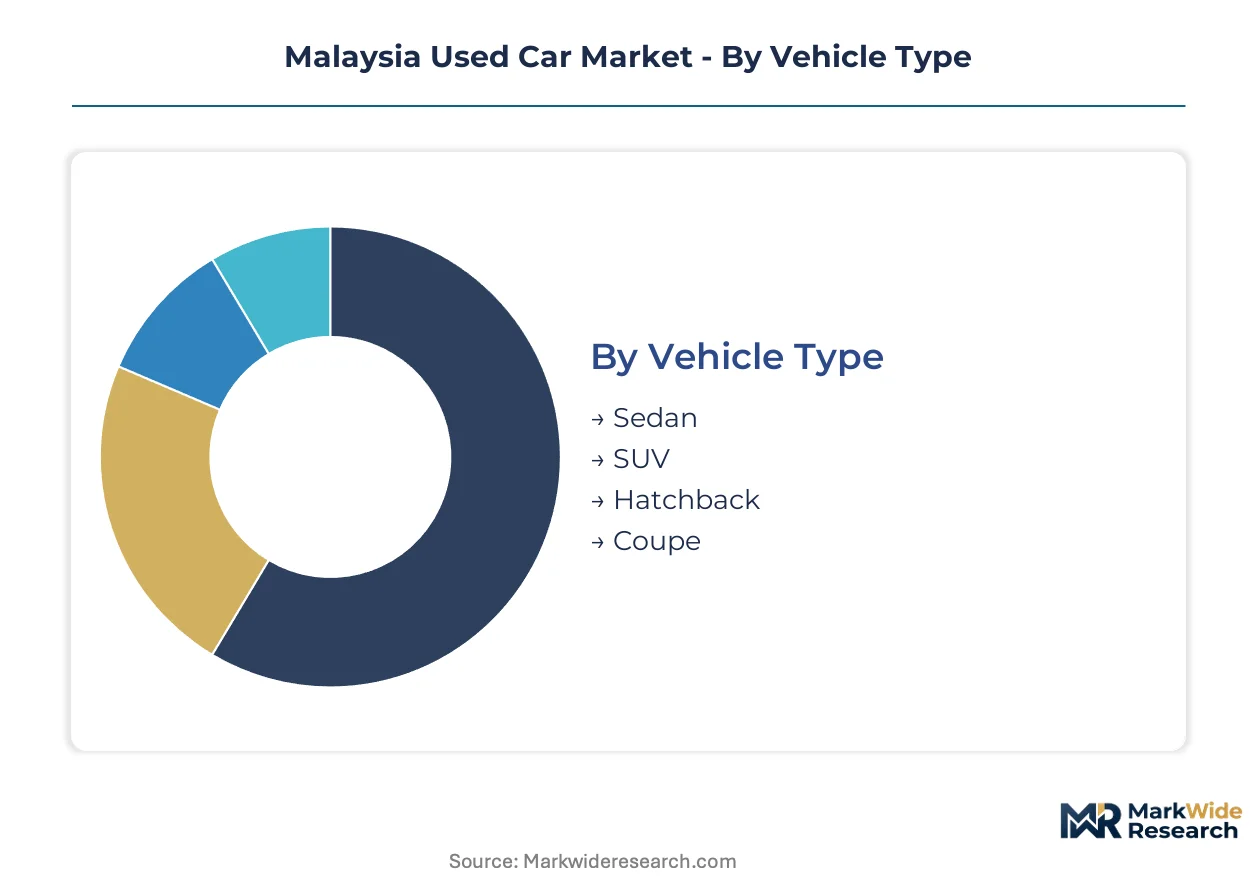
Malaysia's used car segmentation reflects divergent capital requirements across vehicle preparation, certification depth, and channel infrastructure. Buyers in the Klang Valley corridor exhibit distinct preferences that reshape how inventory stratifies by condition grade and transaction modality.
Vehicle Type:
Capital intensity peaks with SUVs requiring specialized refurbishment bays and extended warranty reserves, while sedans demand leaner inspection throughput.
- Sedan:Three-box configurations dominate fleet procurement for Grab and AirAsia Ride operators seeking proven durability and standardized maintenance protocols. Demand clusters in Selangor's suburban districts where ride-hailing driver density supports volume turnover.
- SUV:Elevated ground clearance and cabin flexibility command refurbishment investment in suspension diagnostics and drivetrain stress testing. Klang Valley families prioritize these for flood-prone access routes and multi-generational transport.
- Hatchback:Compact footprints suit Penang and Johor Bahru's constrained parking infrastructure with minimal capital outlay for reconditioning.
- Coupe:Niche two-door configurations attract enthusiast buyers in Kuala Lumpur's premium secondary market with limited platform liquidity.
Sedans absorb the bulk of installed capacity; SUVs are expanding most quickly.
Condition:
Margin structure stratifies sharply by certification depth, with PUSPAKOM-integrated workflows extracting price premiums over uncertified inventory.
- Certified Pre-Owned:Comprehensive inspection protocols, refurbishment guarantees, and extended warranty bundling require captive workshop investment and technician certification. Carsome and MyTukar concentrate procurement here to defend price positioning against direct-owner listings.
- Excellent:Single-owner vehicles with documented service histories trade through retail dealer networks without full platform certification, capturing buyers seeking near-new condition at depreciated pricing.
- Like New:Low-mileage lease returns and executive fleet rotations move through auction-to-retail pipelines with minimal reconditioning spend.
- Damaged:Insurance write-offs and accident-history vehicles circulate in cash-only peer-to-peer channels outside formal platform coverage, concentrated in East Coast states with thinner regulatory enforcement.
Certified Pre-Owned commands the steepest margin premiums; Excellent condition vehicles are climbing the fastest as platform transparency tools expand.
Fuel Type:
Residual value risk varies by powertrain technology maturity and Ministry of Investment, Trade and Industry electrification signaling.
- Petrol:Ubiquitous port-injection and direct-injection engines dominate auction volume with established PUSPAKOM emissions testing protocols and nationwide technician familiarity.
- Diesel:Compression-ignition configurations retain fleet preference in commercial applications and East Coast long-distance transport where fuel economy outweighs particulate filter maintenance costs.
- Hybrid:Parallel and series-parallel architectures from early lease expirations enter secondary circulation requiring specialized battery health diagnostics not yet standardized across independent workshops.
- Electric:Battery electric vehicles face thin resale liquidity pending dedicated inspection infrastructure and range certification standards under development.
Petrol retains dominant transaction volume; hybrid powertrains are gaining share fastest as early adopter lease cycles mature.
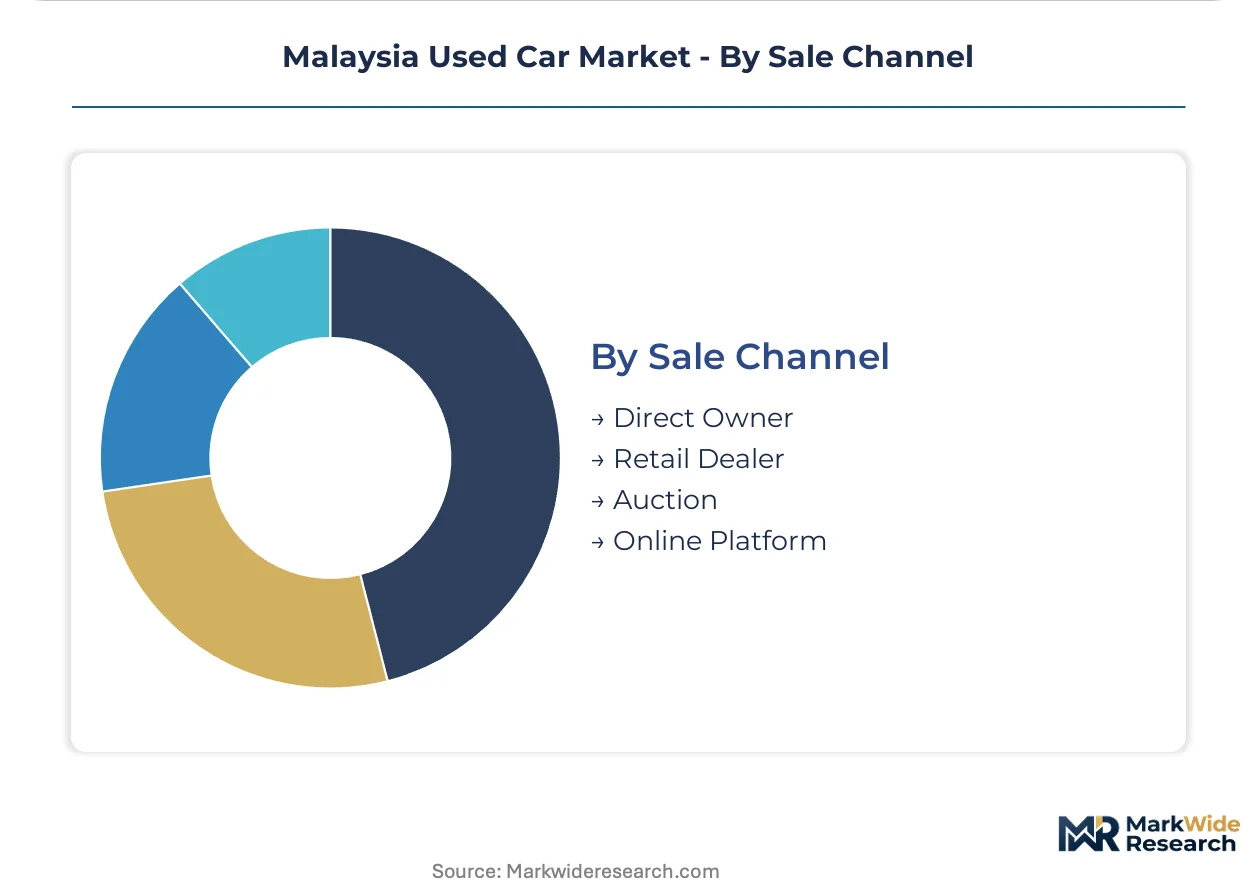
Sale Channel:
Customer acquisition cost and inventory velocity diverge across channel models, with platform integration demanding sustained technology investment.
- Online Platform:Carsome and MyTukar deploy proprietary inspection APIs, financing origination partnerships with Bank Negara Malaysia-licensed non-bank lenders, and logistics networks that compress transaction timelines from weeks to days.
- Retail Dealer:Brick-and-mortar certified pre-owned programs leverage physical presence for test-drive conversion and immediate delivery, concentrated in Klang Valley shopping corridors with highest foot traffic.
- Direct Owner:Peer-to-peer listings on Mudah.my sustain price transparency through volume aggregation but expose buyers to odometer tampering and undisclosed accident history without PUSPAKOM gatekeeping.
- Auction:MyTukar's real-time bidding infrastructure and dealer-only wholesale channels accelerate price discovery for trade-ins and fleet liquidations with compressed holding periods.
Online platforms capture the steepest volume expansion trajectory; retail dealers defend concentrated margin pools in certified transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Iskandar Malaysia special economic zone in Johor anchors cross-border vehicle flows from Singapore, concentrating inspection infrastructure and financing operations near the Second Link corridor.
Selangor
Grab and AirAsia Ride driver density in Petaling Jaya and Shah Alam sustains wholesale auction velocity for compact sedans. Bank Negara Malaysia's hire-purchase guidelines structure platform-integrated loan origination for suburban buyers. The Klang Valley logistics cluster compresses delivery timelines through centralized refurbishment facilities.
Kuala Lumpur
Urban density and constrained parking infrastructure elevate hatchback demand among gig economy operators. The Road Transport Department enforces PUSPAKOM certification at centralized inspection hubs in Cheras and Wangsa Maju. Brick-and-mortar certified pre-owned programs concentrate in shopping corridors along Jalan Bukit Bintang with highest foot traffic conversion.
Penang
Island geography and heritage zone parking restrictions prioritize compact vehicle formats for private ownership. The Ministry of Domestic Trade and Cost of Living monitors disclosure compliance for dealers operating in George Town's concentrated retail corridor. Bayan Lepas industrial zone proximity supports technician training pipelines for hybrid powertrain diagnostics.
Johor
Singapore-registered vehicle de-registration flows supply right-hand-drive inventory through Iskandar Puteri clearance facilities. The Malaysia-Singapore Second Link customs infrastructure enables same-day ownership transfer processing. Johor Bahru's expanding ride-hailing driver pool absorbs mid-mileage Japanese domestic market imports.
Malaysia Used Car Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Malaysia's used car transaction infrastructure. The vendor base stratifies into three tiers: integrated platforms controlling inspection-to-delivery workflows, franchise dealer networks leveraging manufacturer certification, and peer-to-peer classified aggregators sustaining volume through price transparency. Strategic moves concentrate on backward integration into captive refurbishment capacity and API connectivity with Bank Negara Malaysia-licensed non-bank financiers.
Within the platform-integrated tier, Carsome and MyTukar exemplify archetypes of inspection-cum-retail consolidation, while Mudah.my occupies a position as the dominant classified-listing aggregator. Carsome represents vertically integrated quality control through proprietary refurbishment infrastructure. MyTukar anchors auction-to-retail pipeline optimization with real-time bidding integration. Mudah.my exemplifies peer-to-peer price discovery without PUSPAKOM gatekeeping obligations.
| Leading Market Players |
|---|
| Carsome |
| MyTukar |
| Mudah.my |
| Carlist.my |
| Sime Darby Auto Selection |
| Perodua |
| UMW Toyota Motor |
| Caricarz |
| Trusty Cars |
| Others |
Value Chain & Pricing Dynamics
Ride-hailing driver concentration in Selangor and Kuala Lumpur anchors transactional pricing around immediate inventory availability rather than speculative holding. Fleet operators seeking 36-month replacement cycles pay premiums for PUSPAKOM-certified units with same-week delivery, while spot-market peer-to-peer transactions trade at discounts reflecting documentation uncertainty.
Pricing Analysis
Short lead-time availability commands measurable premiums in Klang Valley auction-to-retail pipelines. Three-tier pricing structure across certified pre-owned, platform-listed, and direct-owner tiers reflects PUSPAKOM certification depth and warranty bundling. Cost compression in direct-owner channels is intensifying because odometer tampering exposes buyers to hidden liability. Fleet procurement teams exhibit lowest price sensitivity; gig economy drivers financing through Bank Negara Malaysia-licensed non-bank lenders show highest sensitivity to monthly payment thresholds.
Supply Chain Analysis
PUSPAKOM certification gating filters substandard inventory before formal circulation, concentrating supply among platform-integrated dealers with captive refurbishment capacity. Vehicle sourcing draws from Singapore de-registration flows, Japanese domestic market exports, and domestic lease returns. Single-source vulnerability sits with PUSPAKOM inspection center congestion in Klang Valley, which freezes inventory velocity during peak registration windows. Distribution runs through platform-managed logistics networks for certified units and fragmented dealer-to-dealer wholesale for uncertified inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around backward integration into captive refurbishment infrastructure, with control over inspection-to-delivery workflows determining margin capture. Players are racing upstream to secure PUSPAKOM-certified technician pipelines and proprietary reconditioning bays.
For Market Incumbents: Anchor market position through exclusive financing partnerships with Bank Negara Malaysia-licensed non-bank lenders and expansion of proprietary inspection API coverage. Platform-integrated competitors threaten margin pools by collapsing loan origination timelines; defensive investment in refurbishment technician training programs preserves quality consistency at scale. For New Entrants and Emerging Players: AI-augmented condition assessment tools offer a technology-first wedge into dealer-facing SaaS layers currently served by fragmented legacy DMS providers. East Coast states present underpenetrated white space with thinner platform coverage relative to Klang Valley saturation. Go-to-market execution should prioritize API connectivity with independent dealers resisting Carsome and MyTukar marketplace integration. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with demonstrated PUSPAKOM certification throughput and captive logistics networks. Long-term viability over the coming decade hinges on electrification readiness for battery electric vehicle secondary circulation. Monitor Ministry of Investment, Trade and Industry policy signals on internal combustion engine phase-out timelines as the critical inflection indicator for residual value risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refurbishment Infrastructure | Captive PUSPAKOM-certified workshops defend margin pools against platform price transparency. |
| API Connectivity with Non-Bank Lenders | Real-time hire-purchase origination collapses approval timelines from days to hours per Bank Negara Malaysia guidelines. |
| East Coast Logistics Network Expansion | Kelantan and Terengganu underpenetration offers first-mover inventory velocity advantages. |
| Hybrid Powertrain Diagnostic Capability Buildout | Early lease expiration waves from 2027 onward require specialized battery health assessment infrastructure. |
| AI-Augmented Condition Assessment Deployment | Algorithmic confidence scores compress fleet operator due diligence from physical multi-point checks to automated scoring. |
Study Parameters
Independent corroboration across platform transaction databases, PUSPAKOM certification records, and Bank Negara Malaysia hire-purchase origination reports underwrites the qualitative findings. Primary interviews with used car platform operations executives, independent dealer principals, fleet procurement managers, and PUSPAKOM-certified inspection specialists combined with secondary validation from Road Transport Department enforcement bulletins, Ministry of Domestic Trade disclosure compliance records, and automotive finance lender portfolios. Bottom-up segmentation modeling triangulated against top-down macroeconomic consumption indicators.
Rate-of-change decomposition across vehicle type, condition grade, fuel architecture, and sale channel dimensions structures the analytical framework over the projection horizon. CAGRs derived from fitted trend extrapolation adjusted for electrification policy uncertainty and ride-hailing fleet expansion trajectories. Forecast inputs incorporate PUSPAKOM inspection capacity expansion schedules and platform logistics network coverage maps.
Several conditions sit outside the modeled scope, including unlicensed peer-to-peer transaction volumes, cross-border smuggling flows from neighboring markets, and catastrophic flood damage events affecting Klang Valley inventory quality. Forecasts reflect documented assumptions on regulatory enforcement consistency and platform market share trajectories. A model refresh is warranted upon material change in Ministry of Investment, Trade and Industry electrification timeline announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Europe Used Car Market
Used Vehicles
GCC Used Car Market
Used Vehicles
Netherlands Used Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
India Used Car Market
Used Vehicles
Australia Used Car Market
Used Vehicles
Hong Kong Used Car Market
Used Vehicles
Online Car Buying Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
Used E-Scooter Market